
 Engine Rocker Arm Market | 2026-2036
Engine Rocker Arm Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Rocker Arm Market Insights
Software-defined valve train calibration is expanding the serviceable revenue attached to each rocker arm shipment. Schaeffler Technologies leverages its integrated mechatronics portfolio to bundle digital tuning protocols with hardware deliveries. BorgWarner sustains R&D intensity in electromechanical actuator designs that reduce parasitic losses. Eaton Corporation anchors its position through captive forging capacity and direct OEM supply agreements across North American heavy-duty platforms.
An engine rocker arm is a reciprocating lever, typically investment-cast from steel or aluminum alloy, that transfers camshaft lobe motion to open and close poppet valves with precise lift and duration control. Its primary industrial purpose is to convert rotational cam profile energy into linear valve actuation while maintaining lash tolerance under cyclic thermal and mechanical loading. Steel rocker arms dominate heavy-duty and high-load applications where fatigue resistance commands premium positioning, while aluminum alloy variants gain ground in light-duty automotive programs chasing mass reduction targets. Hydraulic lash adjuster technology leads installed base volumes, though electromechanical and variable valve timing architectures represent the fastest-growing configuration pools as OEMs pursue cylinder deactivation and Miller-cycle combustion strategies.
EPA tailpipe standards and Euro 7 emissions frameworks are tightening permissible NOx and particulate thresholds, forcing rocker arm suppliers to certify surface finishes, material traceability, and dimensional tolerances that support precise valve event control. China's GB standards and MIIT fuel consumption regulations add parallel compliance layers for components entering domestic engine assembly plants. Stakeholders must monitor how electromechanical valve actuation patents and regional emissions enforcement timelines reshape sourcing decisions across OEM and aftermarket channels.
Market Dynamics
Valve train electrification is compressing traditional hydraulic rocker arm demand as OEMs pursue cylinder deactivation and variable lift strategies for compliance with tightening emissions frameworks. This technological pivot is restructuring supplier relationships and forging requirements across engine manufacturing clusters.
Growth Catalysts
- Euro 7 NOx thresholds:Precision-machined rocker arms with enhanced surface finishes enable precise valve event timing required for aftertreatment integration in European heavy-duty platforms.
- Commercial fleet replacement cycles:North American and European logistics operators are retiring pre-2020 powertrains, generating fresh OEM demand for hardened steel rocker arm assemblies.
- Aluminum alloy forging advances:Mass reduction targets in light-duty automotive programs are accelerating specification shifts from steel to aluminum variants with equivalent fatigue performance.
Market Restraints
- Electromechanical valve actuation substitution:Camless engine architectures eliminate rocker arms entirely, threatening long-term installed base volumes in premium passenger vehicle segments.
- Specialized alloy supply concentration:High-grade steel and aluminum billet sourcing clusters in China and India create vulnerability to export duty fluctuations and logistics bottlenecks.
- REACH substance restrictions:European surface treatment chemistries face phase-out timelines that force reformulation of anti-wear coatings with unproven field durability.
Strategic Opportunities
- Aftermarket digital service bundling:Software-defined valve train calibration protocols create recurring revenue streams attached to hardware shipments for independent repair networks.
- Mexico engine manufacturing expansion:Relocated powertrain assembly plants from US and European OEMs generate localized forging and machining demand with reduced tariff exposure.
- India BS-VI Phase II compliance:Tighter particulate mandates for commercial vehicles drive specification upgrades for precision lash control in domestic engine programs.
Industry Challenges
- Mechatronics skill scarcity:Integration of hydraulic lash adjusters with electronic control units demands calibration engineers with cross-disciplinary competencies that outpace vocational training pipelines.
- Dual certification timelines:Simultaneous EPA and Euro 7 homologation requirements extend validation cycles and strain testing facility capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Rocker Arm Market |
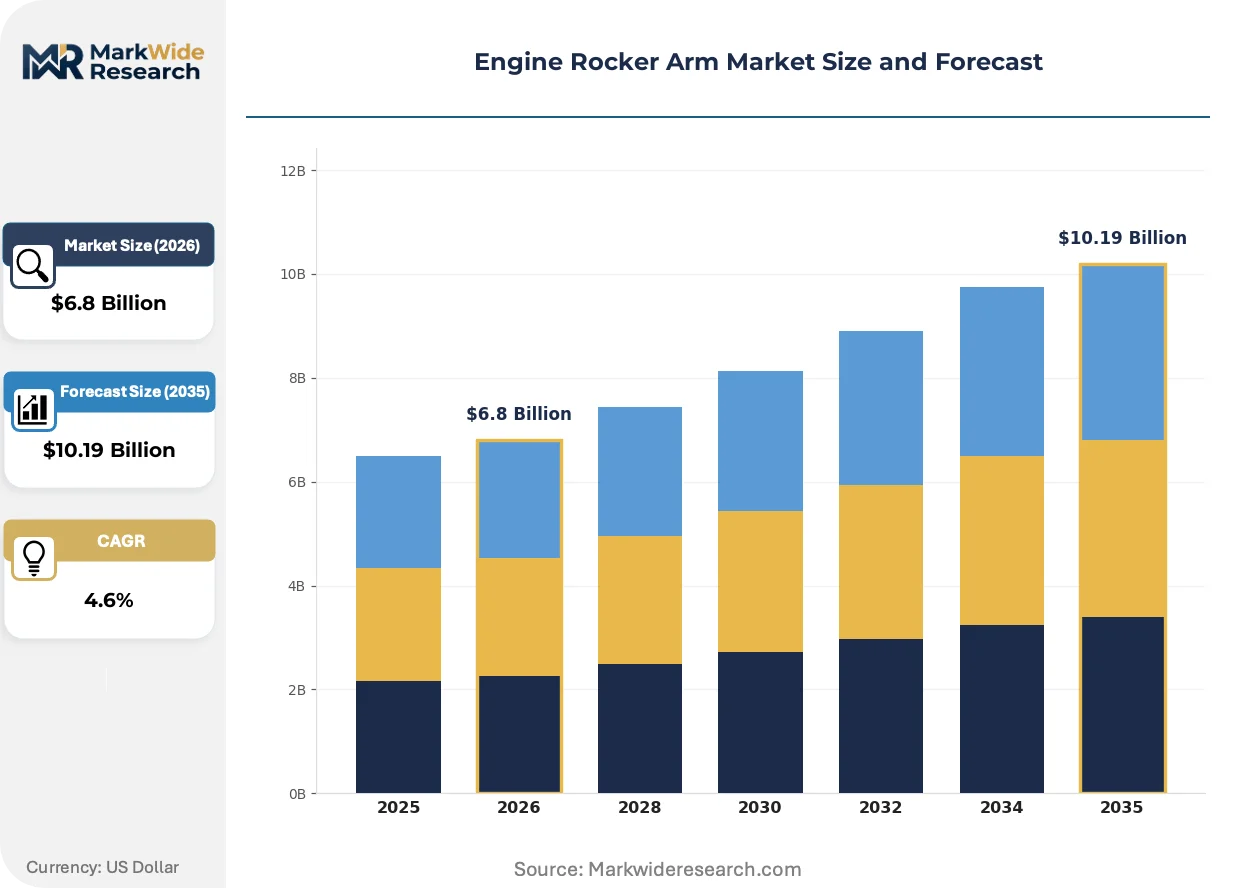
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive, Heavy-Duty, Performance, Manual Material: Aluminum Alloy, Steel, Cast Iron, Composite End User: OEMs, Aftermarket Providers, Component Suppliers, Vehicle Assemblers Technology: Hydraulic, Mechanical, Variable Valve Timing, Electromechanical |
| Companies Covered | Schaeffler Technologies, BorgWarner, Federal-Mogul, Eaton Corporation, COMP Cams, Crower Cams & Equipment, Dubuque Stamping, Incast Inc, Rane Engine Valve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Rocker Arm Market Trends and Innovations
Valve train architectures are converging with electronic control systems, transforming rocker arms from passive mechanical levers into precision actuation nodes. This convergence is redefining supplier capability requirements and competitive differentiation across forging, machining, and calibration competencies.
Electromechanical variable valve lift systems are integrating cam profile switching with electronic lash compensation to enable cylinder deactivation without drivability penalties. Heavy-duty OEMs in North America are piloting these configurations for line-haul efficiency gains. The technology is integrating hydraulic damping elements with solid-state actuators, compressing the addressable market for conventional stamped steel rockers in premium segments.
EPA tailpipe standards and Euro 7 frameworks are mandating sub-micron surface finish tolerances and complete material traceability from melt to final machining. These requirements are disqualifying smaller forging operations lacking spectrographic verification capacity. Suppliers with captive heat treatment and in-process gauging are capturing specification authority for emissions-critical engine platforms.
Fleet procurement teams are consolidating valve train component sourcing under long-term service agreements that bundle hardware, calibration data, and predictive maintenance analytics. This model displaces spot purchasing through traditional distribution channels. The shift is most visible in North American heavy-duty segments where telematics integration enables outcome-based component life guarantees.
Engine Rocker Arm Market Segmentation
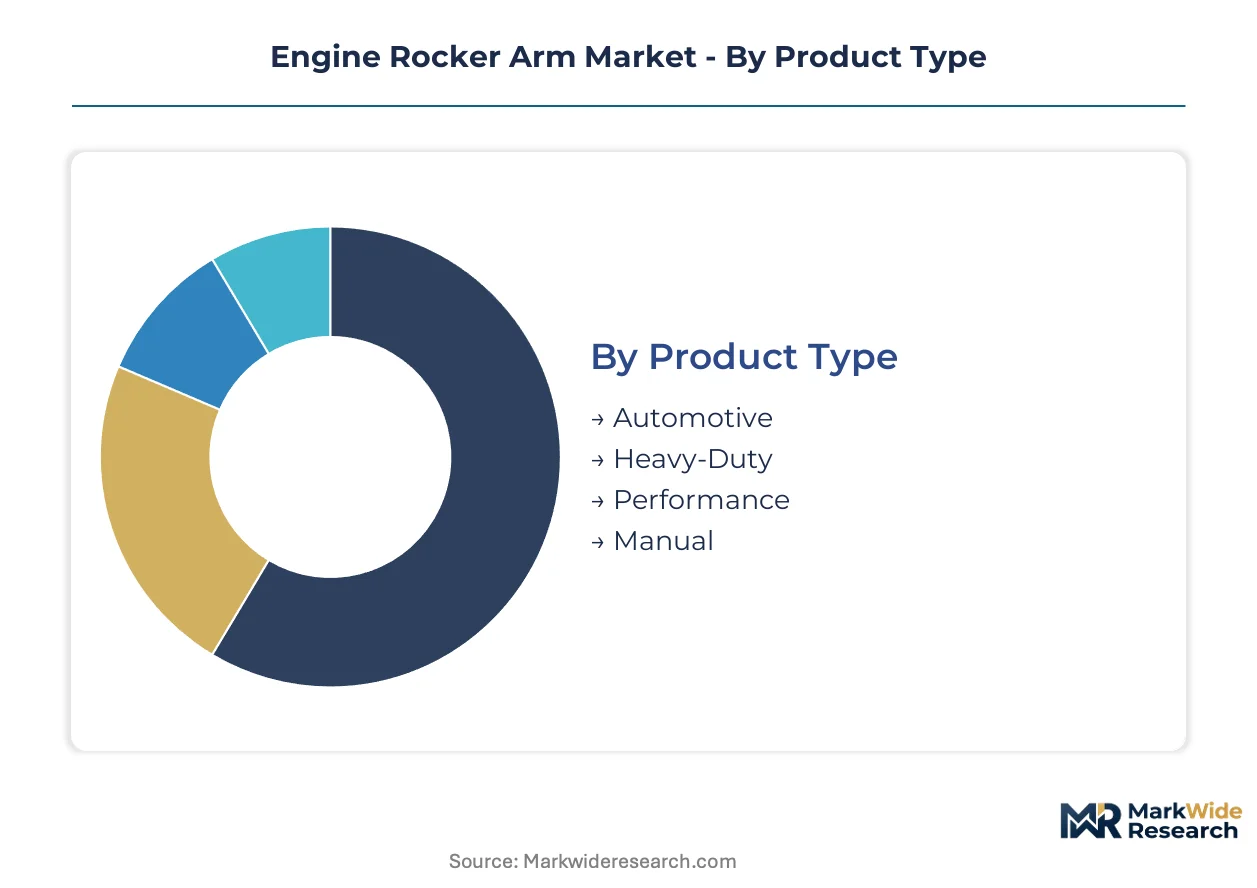
Rocker arm procurement patterns diverge sharply across duty cycles, material specifications, and valve train architectures. Suppliers must align forging capacity and calibration protocols with distinct performance envelopes rather than treating components as interchangeable commodities.
Product Type:
Standardization dominates high-volume automotive programs while heavy-duty and performance segments demand bespoke metallurgy and surface engineering.
- Automotive:Light-duty passenger and commercial vehicle applications specify aluminum alloy stampings with hydraulic lash compensation for mass efficiency. China's MIIT fuel consumption regulations and India's BS-VI Phase II mandates concentrate demand for low-friction variants in domestic engine plants.
- Heavy-Duty:Forged steel assemblies with investment-cast bodies withstand cyclic thermal loading in line-haul and vocational powertrains. North American fleet replacement cycles and Euro 7 NOx thresholds drive specification for hardened contact surfaces and full material traceability.
- Performance:Billet-machined roller tip configurations serve racing and specialty engine builds requiring precise lift control at elevated RPM.
- Manual:Solid mechanical rockers without hydraulic compensation persist in cost-optimized emerging market powertrains and vintage restoration supply chains.
Most installed capacity flows through Automotive. Expansion is steepest in Heavy-Duty.
Material:
Cost tiers separate commodity forgings from premium alloys certified for emissions-critical valve event precision.
- Steel:SAE 4140 and 8620 alloy grades deliver fatigue resistance for heavy-duty contact stresses. EPA and Euro 7 surface finish mandates push demand toward vacuum-melted billets with spectrographic verification from melt to final machining.
- Aluminum Alloy:A356-T6 and comparable specifications reduce reciprocating mass in light-duty programs. China's GB standards and Mexico's expanding engine manufacturing clusters concentrate forging orders for mass-optimized variants.
- Cast Iron:Pearlitic grades persist in legacy commercial engine platforms and aftermarket replacement channels where cost minimization overrides mass targets.
- Composite:Polymer-metal hybrid prototypes target extreme mass reduction in electrified powertrain auxiliary drives, though field durability remains unproven at scale.
Steel commands the largest share of forging tonnage. Aluminum Alloy is climbing the fastest on mass reduction imperatives.
End User:
Procurement concentration varies by channel control—captive OEM supply agreements versus fragmented aftermarket distribution.
- OEMs:Direct supply relationships with engine manufacturers specify lot-controlled production with embedded calibration data for telematics integration. Long-term service agreements now bundle hardware with predictive maintenance analytics.
- Aftermarket Providers:Independent repair networks and distributors source replacement rockers for aging powertrain parc, with software-defined valve train calibration emerging as a service attachment.
- Component Suppliers:Tier-2 forging and machining operations supply semi-finished rocker arm blanks to valve train integrators lacking captive metallurgical capacity.
- Vehicle Assemblers:Full-vehicle manufacturers with in-house engine operations source complete rocker arm assemblies for captive powertrain programs.
OEMs absorb the dominant share of precision-machined output. Aftermarket Providers are expanding most quickly on fleet telematics penetration.
Technology:
Maturity gradients separate established hydraulic architectures from emerging electromechanical configurations threatening long-term displacement.
- Hydraulic:Self-adjusting lash compensators dominate installed base volumes across light and medium-duty applications. EPA and Euro 7 emissions frameworks sustain demand for precision-machined bodies with sub-micron surface finishes.
- Variable Valve Timing:Cam phasing and profile-switching mechanisms enable cylinder deactivation and Miller-cycle combustion strategies. Heavy-duty OEMs in North America pilot these configurations for line-haul efficiency gains.
- Mechanical:Solid adjusters with manual lash setting persist in racing, vintage, and cost-optimized commercial applications where electronic control complexity is unwarranted.
- Electromechanical:Camless valve actuation eliminates rocker arms entirely in premium passenger vehicle prototypes, compressing future addressable market for conventional lever architectures.
Hydraulic technology retains the deepest installed base. Variable Valve Timing is gaining share fastest on emissions compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing engine rocker arm production toward jurisdictions where emissions compliance costs and labor inputs create favorable manufacturing economics. Suppliers are relocating forging and precision-machining capacity to capture these cost-of-compliance gaps while maintaining certification pathways for EPA and Euro 7 markets.
China
MIIT fuel consumption regulations and GB emissions standards are concentrating domestic demand for aluminum alloy rocker arms in light-duty automotive programs. The Yangtze River Delta engine manufacturing corridor hosts expanded forging operations serving both local OEM assembly plants and export markets. Suzhou and Shanghai machining clusters are adding spectrographic verification capacity to meet Euro 7 material traceability requirements for European-bound shipments.
United States
Commercial fleet replacement cycles and EPA tailpipe standards are sustaining demand for hardened steel rocker arm assemblies in heavy-duty platforms. The Midwest manufacturing belt retains captive forging capacity for line-haul powertrains. Detroit-area engine plants are integrating telematics-enabled valve train calibration protocols under long-term service agreements with direct OEM suppliers.
Germany
Euro 7 NOx thresholds are mandating sub-micron surface finishes and complete material traceability for emissions-critical valve event control. Baden-Württemberg precision-machining operations are capturing specification authority through captive heat treatment and in-process gauging. Stuttgart-area suppliers are bundling predictive maintenance analytics with hardware deliveries for European heavy-duty OEMs.
India
BS-VI Phase II particulate mandates are driving specification upgrades for precision lash control in domestic commercial vehicle engine programs. Tamil Nadu and Maharashtra powertrain assembly corridors are absorbing relocated forging capacity from higher-cost jurisdictions. Pune and Chennai machining clusters are expanding hydraulic lash adjuster production for both local OEM integration and aftermarket export channels.
Mexico
Relocated US and European OEM engine plants are generating localized forging demand with reduced tariff exposure to North American markets. Nuevo León and Bajío Region manufacturing clusters are adding investment-casting capacity for aluminum alloy variants. Querétaro and Monterrey machining operations are certifying surface finish protocols to serve EPA-compliant powertrain programs.
Engine Rocker Arm Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated supply relationships dominating OEM channels while fragmented sourcing persists in aftermarket distribution. The vendor base organizes around three strategic archetypes: integrated mechatronics suppliers with calibration software portfolios, captive forging operations with direct OEM agreements, and specialized machining houses serving tier-2 valve train integrators. M&A activity concentrates on acquiring spectrographic verification capacity and predictive maintenance analytics platforms. Geographic expansion into Mexico and India represents the dominant competitive move as suppliers follow relocated engine manufacturing clusters.
Among Germany-based integrated suppliers, Schaeffler Technologies and BorgWarner exemplify the mechatronics archetype, bundling digital tuning protocols with hardware deliveries. Eaton Corporation, identifiable by its corporate suffix, anchors the captive-forging tier through direct supply agreements across North American heavy-duty platforms. These three entities represent distinct competitive positioning vectors—software-enabled service bundling, metallurgical scale, and OEM relationship depth—without implying specific market shares or financial performance.
| Leading Market Players |
|---|
| Schaeffler Technologies |
| BorgWarner |
| Federal-Mogul |
| Eaton Corporation |
| COMP Cams |
| Crower Cams & Equipment |
| Dubuque Stamping |
| Incast Inc |
| Rane Engine Valve |
| Others |
Pricing and Supply Chain Analysis
Precision-machining specialist concentrations in the Yangtze River Delta and Baden-Württemberg create labor-cost differentials that widen pricing-tier spreads between spectrographically verified premium forgings and commodity stampings.
Pricing Analysis
Capacity additions in Mexico's Bajío Region are reshaping price floors for aluminum alloy variants serving EPA-compliant powertrain programs. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-melted steel with full material traceability from induction-melted grades and unverified aftermarket replacements. Cost compression in standard-tier hydraulic lash adjusters reflects forging automation investments in India and China. Fleet procurement teams demonstrate lowest price sensitivity due to bundled predictive maintenance contracts, while independent repair networks remain highly sensitive to unit economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by North American heavy-duty OEMs force valve train integrators to qualify secondary forging operations in India alongside primary suppliers. Raw material flows draw from vacuum-melted billet producers in Germany, induction-melted steel mills in China, and A356-T6 aluminum smelters in Mexico. Single-source vulnerability concentrates in spectrographic verification equipment, where German and Japanese manufacturers control installed base. Distribution runs through captive OEM supply agreements for precision-machined output, with aftermarket channels served by tier-2 distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through software-defined calibration bundling that captures service revenue beyond hardware shipment economics.
For Market Incumbents: To counter electromechanical valve actuation substitution in premium passenger segments, Schaeffler Technologies and BorgWarner should deepen backward integration into forging capacity while accelerating predictive maintenance analytics platform development. Captive heat treatment investments in Mexico and India defend specification authority for emissions-critical platforms. For New Entrants and Emerging Players: Capture aftermarket digital service attachment opportunities in North American heavy-duty fleets where telematics penetration outpaces supplier calibration capability. India's BS-VI Phase II compliance window offers the most penetrable geography for hydraulic lash adjuster specialists lacking Euro 7 certification. Partner with independent repair networks for software-defined valve train protocol distribution. For Investors and Strategic Acquirers: Integrated automotive suppliers with mechatronics portfolios are the most active acquirer in this space, targeting spectrographic verification capacity and predictive maintenance analytics platforms. Long-term viability hinges on electromechanical substitution timelines in premium segments. Monitor patent filings for camless valve actuation prototypes as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging | Captive steel and aluminum billet production secures material traceability for Euro 7 certification pathways. |
| Predictive Maintenance Platform Launch | Telematics-enabled valve train analytics create recurring revenue attached to hardware shipments for fleet customers. |
| Mexico Manufacturing Footprint Expansion | Localized forging capacity reduces tariff exposure to North American markets and EPA-compliant OEM supply chains. |
| Spectrographic Verification Acquisition | In-process gauging and melt-to-final traceability capture specification authority for emissions-critical engine platforms. |
| Software-Defined Calibration Partnership | Digital tuning protocol bundling with independent repair networks expands aftermarket serviceable revenue pools. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with valve train procurement managers at heavy-duty OEMs, forging operations directors, aftermarket distribution heads, and calibration engineering leads with secondary validation against EPA certification databases, Euro 7 homologation filings, and IHS Markit powertrain production data. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates across the analysis window.
Historical reference periods anchored the projection horizon to commercial fleet replacement cycle timing and regulatory enforcement phase-in schedules. Segmentation dimensions modeled include product type, material specification, end-user channel, and valve train architecture technology. CAGRs derived from regression analysis against OEM platform launch timelines and forging capacity expansion announcements. Electromechanical substitution rates and emissions compliance cost pass-through assumptions shaped trajectory sensitivity.
Underlying measurement precision varies by segment; hydraulic lash adjuster volumes carry tighter precision than emerging electromechanical configurations where prototype-to-production timelines remain uncertain. Forecasts reflect assumptions regarding Euro 7 enforcement consistency and MIIT fuel consumption regulation stringency. Deviation in electromechanical valve actuation commercialization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Power Modules Market
Powertrain
Power Assisted Steering Market
Powertrain
Asia-Pacific Torque Vectoring Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Automotive Fluid Reservoir Market
Powertrain
Mechanical Reciprocating Engine Market
Powertrain
Engine Cylinder Liners Market
Powertrain
Automotive Counter Shaft Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Fuel Injection Systems Market
Powertrain
Fuel Pumps Market
Powertrain
Drive Shaft Market
Powertrain
Canada Automotive Engine Oils Market
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
Automotive Performance Tuning Market
Powertrain
South America Automotive Market