
 Automotive Driveline Market | 2026-2036
Automotive Driveline Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Driveline Market Analysis
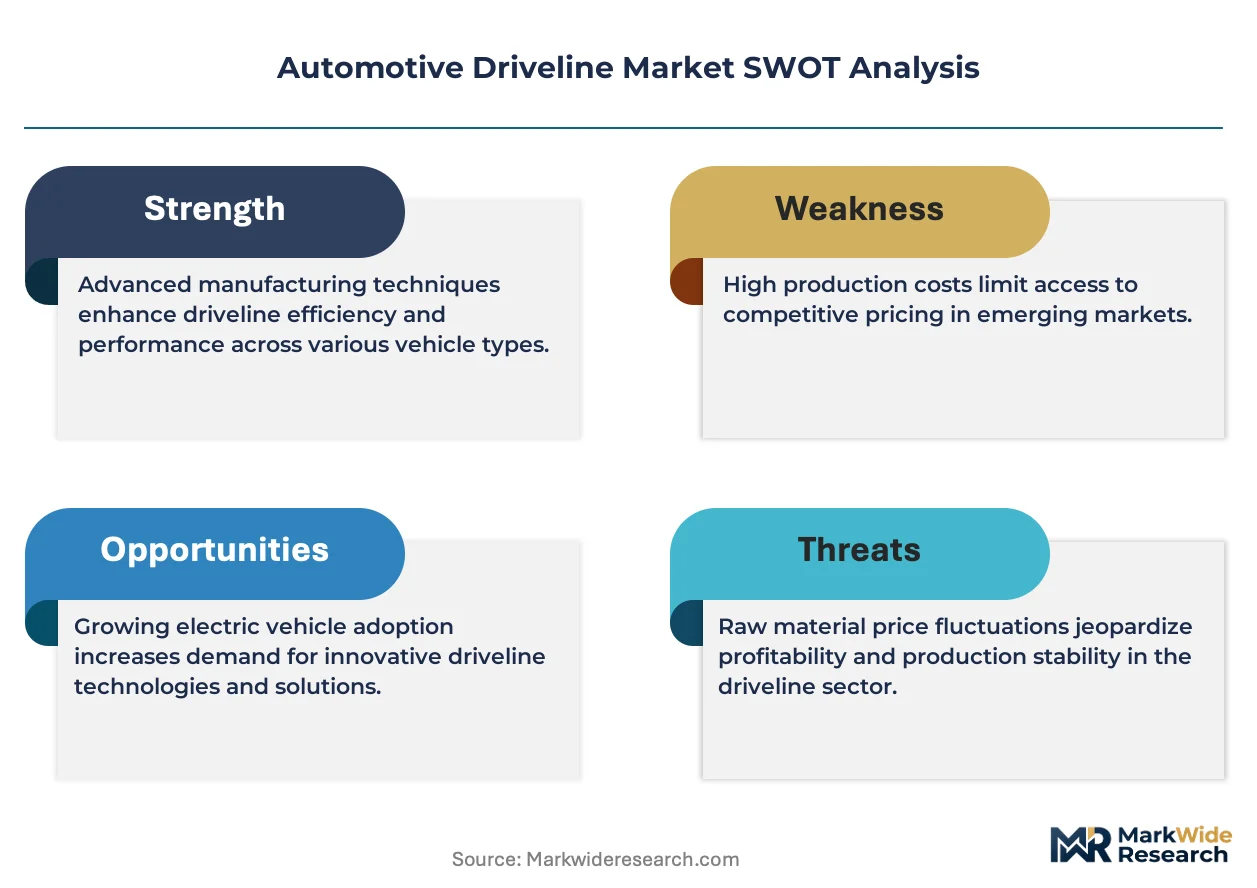
Lightweight aluminum-alloy specification upgrades across axle housings and differential carriers is bifurcating the competitive landscape between mass-market steel architectures and premium consolidated modules. BorgWarner Inc. leverages its integrated drive module portfolio to anchor North American EV truck programs. ZF Friedrichshafen AG sustains technology leadership through its 800-volt electric axle systems. GKN Automotive Limited dominates the all-wheel-drive coupling segment with torque-vectoring differentials that command premium positioning.
An automotive driveline comprises the complete mechanical assembly transmitting engine torque to the driving wheels, encompassing transmissions operating at input speeds exceeding 10,000 rpm in electric variants, drive shafts with constant-velocity joints maintaining angular velocity across suspension travel, and differentials distributing torque through hypoid or helical gear sets. Its primary purpose is converting rotational power into controlled tractive force while managing speed reduction and wheel-speed differentiation across operating conditions. All-wheel-drive product types now capture the fastest expansion as electrified platforms integrate dual-motor torque distribution. By component, differential assemblies concentrate margin pools where limited-slip and torque-vectoring variants replace open differentials in performance segments. Installation categories reveal modular architectures gaining share as vehicle assemblers outsource complete axle modules rather than individual components.
NHTSA fuel economy standards and EPA greenhouse gas regulations in the United States mandate driveline efficiency improvements that increase engineering costs but create barriers for non-compliant imports. Euro 7 emission rules from the European Commission and China's MIIT dual carbon goals collectively push suppliers toward electrified axle designs and lightweight material substitution. Stakeholders must monitor how battery-electric platform standardization alters the aftermarket service lifecycle for traditional transmission and differential components.
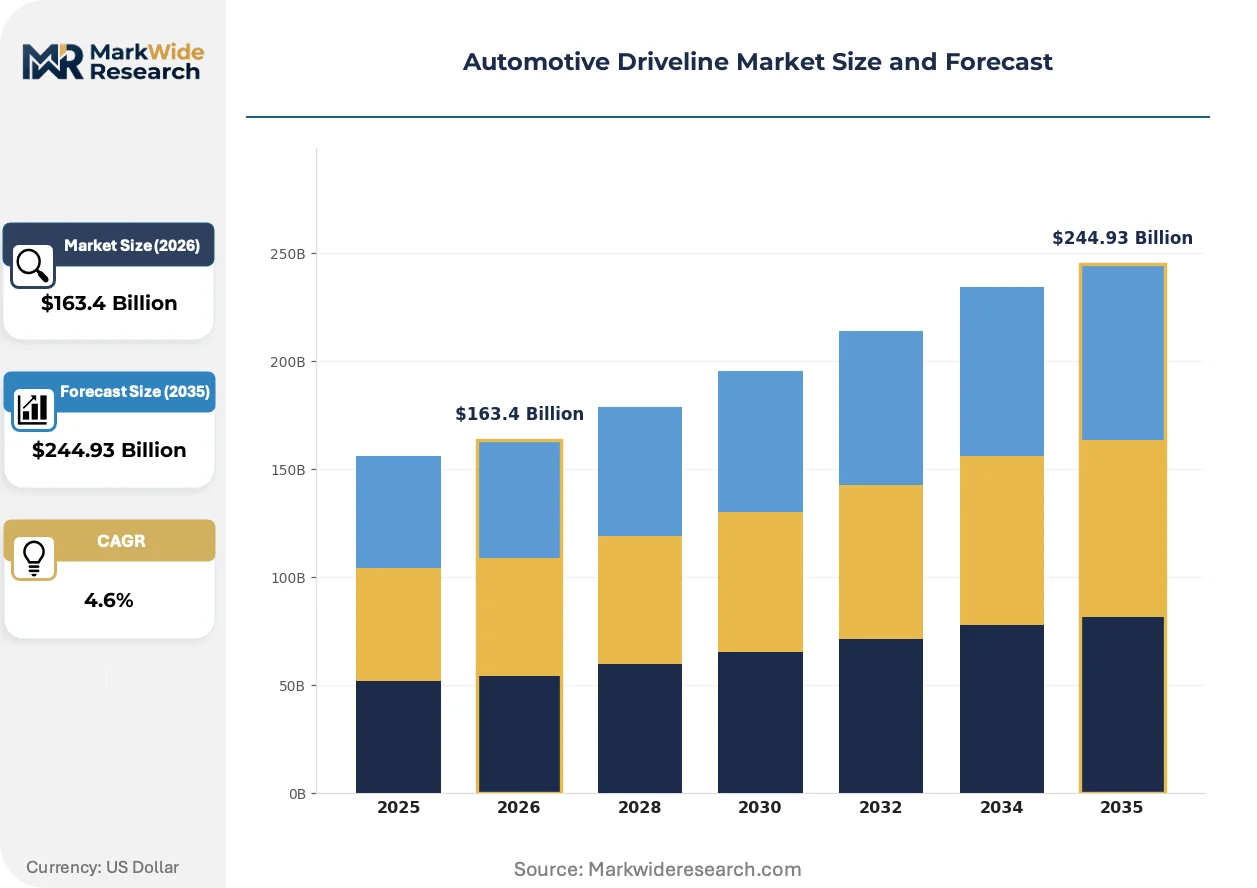
Market Dynamics
The automotive driveline market is experiencing a fundamental restructuring as electric vehicle platforms eliminate traditional transmission architectures and consolidate powertrain functions into integrated axle modules. This platform shift compresses supplier tiers and rewards systems integrators capable of delivering complete electrified driveline solutions.
Growth Catalysts
- EPA tailpipe standards:NHTSA fuel economy mandates force OEMs to adopt lightweight axle housings and efficiency-optimized differentials, accelerating material substitution from steel to aluminum alloys.
- Dual-motor torque distribution:Electrified platforms integrate all-wheel-drive functionality through independent motor control, expanding addressable market for torque-vectoring systems.
- China MIIT dual carbon goals:Domestic EV brands localize all-wheel-drive supply chains, creating concentrated demand hubs for integrated driveline modules.
Market Restraints
- Aluminum price volatility:Raw material cost swings for lightweight alloys squeeze margin pools on premium axle architectures, compressing returns for suppliers locked into long-term OEM contracts.
- Single-source forging capacity:Hypoid gear manufacturing concentrates in German and Japanese precision machining clusters, creating geographic supply vulnerability.
- Battery-electric range anxiety:Consumer hesitation toward full electrification sustains demand for hybrid transmissions, fragmenting R&D investment across parallel development tracks.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for automotive component manufacturing attract driveline suppliers to establish localized axle assembly capacity serving domestic SUV demand.
- 800-volt platform convergence:High-voltage electric axle architectures enable faster charging compatibility, opening premium positioning for suppliers with silicon carbide inverter integration.
- Aftermarket service lifecycle gaps:Battery-electric platform standardization eliminates traditional transmission overhaul demand, creating white space for predictive maintenance software and remanufactured e-axle programs.
Industry Challenges
- Electromechanical systems integration:Combining high-speed electric motors with multi-speed reduction gearsets requires rare cross-functional expertise spanning power electronics and tribology.
- Euro 7 homologation timelines:Compressed certification windows for emission-compliant driveline variants strain validation resources and compress product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Driveline Market |
| Market Size in 2026 | $163.4 Billion |
| Market Size in 2035 | $244.93 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FWD, RWD, AWD, 4WD Component: Transmission, Drive Shaft, Differential, Driveshaft Coupling Installation: Built-in, Modular, Integrated, Aftermarket End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | BorgWarner Inc., ZF Friedrichshafen AG, Continental AG, Robert Bosch GmbH, GKN Automotive Limited, Schaeffler AG, DENSO Corporation, Toyota Motor Corporation, Volkswagen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Driveline Market Emerging Trajectories
Electrification is dismantling the traditional boundaries between transmission, axle, and motor functions. Suppliers now compete on system integration depth rather than component precision alone.
Silicon carbide power electronics is bifurcating the electric axle market into 400-volt mass-market architectures and 800-volt premium platforms capable of sustained high-speed operation. Luxury passenger car OEMs adopt the higher-voltage standard to enable 350-kilowatt charging compatibility. This voltage stratification is bifurcating supplier capabilities and capital requirements.
REACH substance restrictions and the EU Green Deal carbon border adjustments are forcing driveline manufacturers to document full lifecycle emissions for steel and aluminum inputs. Suppliers must requalify casting and forging processes to meet embedded carbon thresholds. The German automotive supply base is responding fastest, with KBA type-approval processes now incorporating supply chain carbon audits.
Fleet operators now specify total cost of ownership over upfront component pricing, unbundling traditional powertrain warranties from vehicle purchase contracts. Leasing companies and commercial truck aggregators negotiate service-inclusive driveline supply agreements. This preference shift is most visible in North American Class 8 truck procurement, where megafleet buyers consolidate supplier relationships around uptime guarantees.
Automotive Driveline Market Segmentation
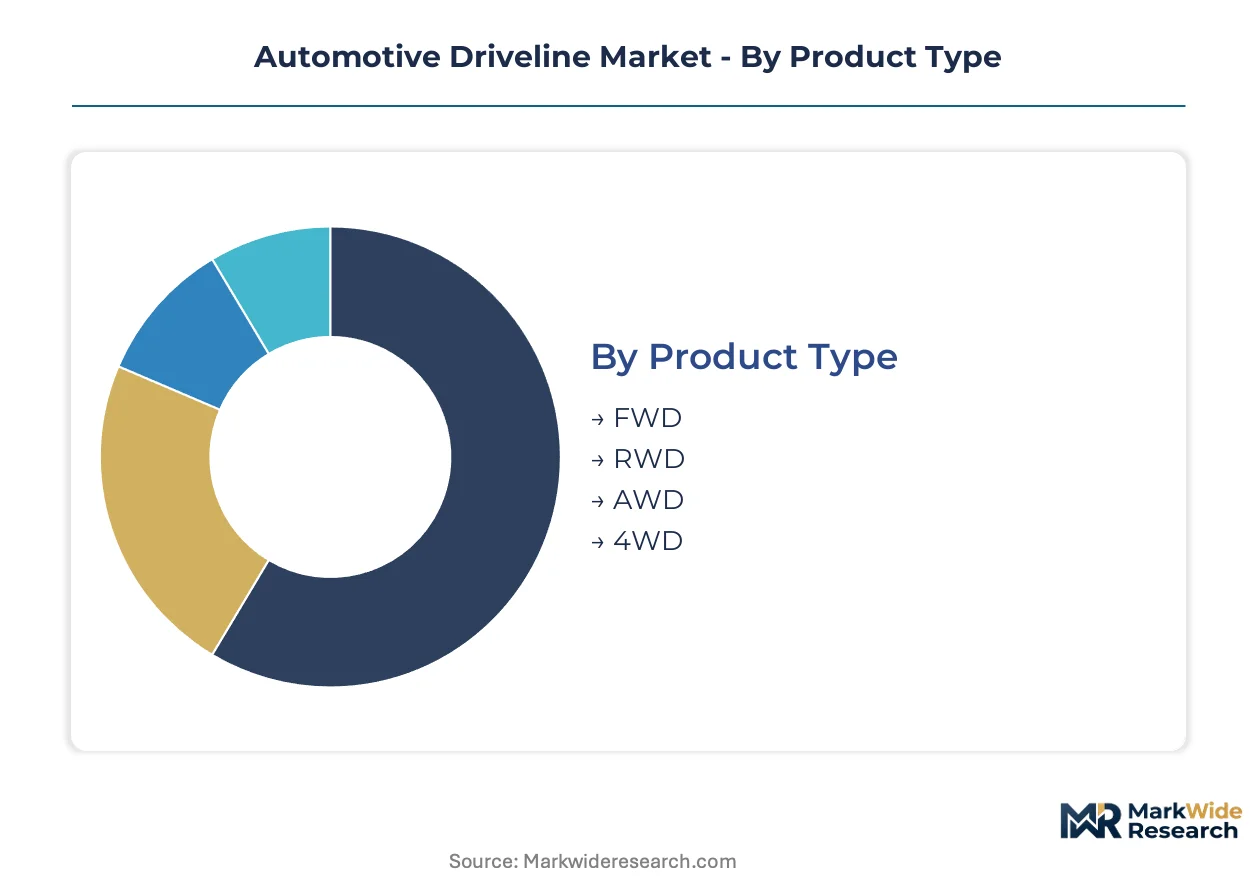
Driveline segmentation reveals how electrification is redrawing category boundaries. Product architectures that once traveled through discrete component channels now consolidate into integrated modules, compressing traditional supplier tiers and rewiring procurement relationships across the value chain.
Product Type:
Channel mix varies sharply by driveline configuration, with front-wheel-drive flowing through high-volume OEM direct contracts while all-wheel-drive systems increasingly route through Tier-1 systems integrators.
- FWD:Compact transverse layouts dominate mass-market passenger cars, with torque delivered through short half-shafts to the front wheels. Demand concentrates in China and India where urban vehicle density favors space-efficient packaging and cost-minimized architectures.
- RWD:Longitudinal engine mounting enables higher torque capacity through robust propeller shafts, serving luxury sedans and performance vehicles. Rear-wheel-drive platforms from BMW and Mercedes-Benz sustain German supplier relationships around precision-machined differential housings.
- AWD:Electrified torque-vectoring systems command premium positioning through dual-motor control.
- 4WD:Part-time transfer case architectures persist in commercial and off-road segments.
Front-wheel-drive dominates installed base. All-wheel-drive is where expansion concentrates.
Component:
Margin pools concentrate in assemblies requiring precision machining expertise, with differential carriers and transmission housings capturing value that commodity shafts cannot access.
- Transmission:Multi-speed reduction gearsets for electric axles integrate planetary stages with helical gearing, replacing traditional stepped automatics. Engineering resources are concentrating on two-speed architectures for 800-volt platforms that extend high-speed cruising efficiency.
- Drive Shaft:Tubular steel and carbon-fiber-reinforced polymer shafts with constant-velocity joints accommodate suspension travel while maintaining angular velocity. Hollow shaft designs from Japanese suppliers serve Toyota and Honda hybrid programs demanding rotational inertia reduction.
- Differential:Torque-biasing mechanisms replace open differentials in performance applications.
- Driveshaft Coupling:Flexible couplings isolate driveline vibration from vehicle cabin.
Transmission assemblies anchor revenue concentration. Differential variants are climbing the fastest.
Installation:
Procurement patterns split between vehicle assemblers seeking complete axle modules and those retaining in-house integration of discrete components.
- Built-in:Traditional component-by-component assembly remains prevalent in legacy truck platforms where frame-rail mounting tolerances vary by manufacturer. Ford and Stellantis retain this approach for North American full-size pickup architectures.
- Modular:Pre-assembled axle modules with integrated housings, bearings, and seals reduce plant-floor complexity. ZF and Magna supply these architectures to European premium OEMs outsourcing complete rear axle integration.
- Integrated:Motor-gearbox-housing combinations eliminate separate transmission packaging.
- Aftermarket:Remanufactured differentials and driveshaft components serve vehicle aging pools.
Modular architectures dominate new program awards. Integrated systems are gaining share fastest.
End User:
Customer type determines contract structure, with OEMs negotiating systems-level supply agreements while aftermarket providers compete on inventory velocity and service coverage.
- OEMs:Volkswagen Group and Hyundai-Kia specify complete driveline performance envelopes, delegating detailed engineering to approved suppliers. These relationships lock in multi-year capacity commitments with penalty clauses for technical non-compliance.
- Tier-1 Suppliers:Bosch, Denso, and Continental aggregate subcomponents into vehicle-ready modules, managing qualification testing and warranty exposure. Their procurement power concentrates forging and casting capacity among approved Tier-2 metalworkers.
- Aftermarket Providers:Independent distributors stock replacement differentials and CV joints for vehicle parc maintenance.
- Vehicle Assemblers:Contract manufacturers and emerging EV brands purchase complete axle systems.
Tier-1 suppliers dominate value capture. Aftermarket providers are where margin pressure concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for driveline components tilt toward surplus positions in precision-manufacturing economies while deficit markets absorb integrated modules. Germany and China anchor outbound shipment volumes through specialized forging and electric axle assembly capacity.
United States
Domestic EV truck programs from Ford and General Motors consume integrated drive modules at accelerating rates. NHTSA fuel economy standards tighten compliance windows for axle efficiency, pushing suppliers toward aluminum-alloy architectures. Michigan and Ohio industrial corridors concentrate Tier-1 assembly plants serving Detroit Three electrification timelines.
Germany
Premium passenger car OEMs specify 800-volt electric axle systems for Mercedes-Benz and BMW platforms. KBA type-approval processes now embed supply chain carbon audits under EU Green Deal implementation. Baden-Württemberg precision machining clusters dominate hypoid gear manufacturing for torque-vectoring differentials.
China
Domestic EV brands localize all-wheel-drive supply chains at scale under MIIT dual carbon goals. GB standards for electric vehicle drivelines harmonize with export market requirements. Yangtze River Delta manufacturing hubs consolidate integrated e-axle capacity serving BYD and NIO production ramps.
Japan
Hybrid transmission architectures sustain demand for multi-speed reduction gearsets alongside full-electric platforms. METI technology roadmaps prioritize silicon carbide inverter integration for next-generation axle efficiency. Toyota City and Nagoya industrial zones anchor hollow driveshaft production for rotational inertia reduction programs.
India
SUV demand growth attracts driveline suppliers through PLI scheme production-linked incentives for component manufacturing. BIS certification requirements for automotive axles tighten quality thresholds for domestic assembly. Tamil Nadu and Gujarat automotive corridors localize axle module capacity for Maruti Suzuki and Hyundai-Kia export programs.
Automotive Driveline Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and integration depth, creating a tiered structure where scale advantages clash with niche engineering agility. The supplier base compresses vertically as vehicle assemblers outsource complete axle modules rather than discrete components. Three archetypes dominate: systems integrators delivering electrified driveline solutions, precision metalworkers capturing differential margin pools, and diversified conglomerates leveraging cross-divisional power electronics expertise. Consolidation pressures intensify through strategic partnerships for 800-volt platform development and geographic expansion into China-localized supply chains.
Within the systems integrator tier, BorgWarner Inc. and ZF Friedrichshafen AG exemplify competing approaches to electric axle consolidation. GKN Automotive Limited occupies a specialized position in torque-vectoring differential architectures. These three entities anchor distinct competitive vectors—integrated module delivery, high-voltage platform leadership, and all-wheel-drive coupling specialization—around which mid-cap suppliers organize partnership strategies.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| ZF Friedrichshafen AG |
| Continental AG |
| Robert Bosch GmbH |
| GKN Automotive Limited |
| Schaeffler AG |
| DENSO Corporation |
| Toyota Motor Corporation |
| Volkswagen AG |
| Others |
Supply Flow & Price Mechanics
Euro 7 emission rules gate both supplier qualification and price differentiation simultaneously, forcing Tier-1 systems integrators to absorb carbon-audit compliance costs while OEMs bifurcate procurement between certified premium axle modules and uncertified commodity architectures. This regulatory threshold concentrates pricing power among German and Chinese suppliers with pre-qualified casting and forging processes, compressing margins for second-tier metalworkers locked out of Mercedes-Benz and BMW program awards.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the automotive driveline market. Three-tier pricing structure across premium, standard, and economy levels reflects 800-volt silicon carbide integration, aluminum-alloy specification grade, and bundled predictive maintenance software. Cost compression in mass-market steel axle architectures is intensifying because Chinese domestic EV brands negotiate volume-scale discounts for localized all-wheel-drive supply chains. Fleet operators and commercial truck aggregators exhibit lowest price sensitivity, prioritizing uptime guarantees and service-inclusive contracts over per-unit component pricing.
Supply Chain Analysis
German precision machining clusters for hypoid gear manufacturing underwrite torque-vectoring differential supply security for European premium OEMs. Raw material flows draw from Chinese aluminum smelters, Japanese specialty steel producers, and South Korean silicon carbide wafer foundries. Single-source forging capacity in Baden-Württemberg and Nagoya industrial zones creates geographic supply vulnerability for limited-slip differential carriers. Distribution runs through Tier-1 systems integrators consolidating subcomponents into vehicle-ready axle modules for OEM direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive returns as 800-volt electric axle standardization across Volkswagen Group and Hyundai-Kia architectures forces interoperability investments. Suppliers must embed themselves into electrified powertrain ecosystems or face displacement by integrated motor-gearbox-housing combinations.
For Market Incumbents: Compound defensive positioning through backward integration into aluminum-alloy casting capacity and captive supply of silicon carbide inverter components. BorgWarner and ZF Friedrichshafen anchor North American EV truck programs by locking in multi-year capacity commitments with penalty clauses for technical non-compliance. Threat substitution from Chinese domestic EV brands localizing all-wheel-drive supply chains demands immediate certification investment under Euro 7 carbon-audit protocols. For New Entrants and Emerging Players: CE marking fast-track for 800-volt electric axle systems opens white-space penetration into European premium passenger car retrofit programs and Indian PLI scheme axle assembly capacity. The most penetrable segment lies in aftermarket remanufactured e-axle programs serving battery-electric platform standardization gaps. Go-to-market execution should target fleet operators negotiating service-inclusive driveline supply agreements with uptime guarantee positioning. For Investors and Strategic Acquirers: Euro 7 homologation timeline compression reshapes the acquisition landscape toward mid-cap specialists with validated carbon-audit processes and KBA type-approval track records. Long-term viability across the analysis window favors systems integrators with demonstrated 800-volt platform convergence and silicon carbide inverter integration capabilities. Watch for MIIT dual carbon goal acceleration in China as the signal indicating consolidated e-axle capacity buildout exceeding indigenous demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | 800-volt electric axle convergence across Volkswagen Group architectures reduces supplier qualification overhead. |
| Battery Supply Agreement | Dual-motor torque distribution systems require secured lithium-ion cell offtake for integrated e-axle production ramps. |
| Software-Defined Vehicle Investment | Predictive maintenance algorithms for torque-vectoring differentials capture fleet operator service contract value. |
| Geographic Manufacturing Footprint | Tamil Nadu and Gujarat corridors localize axle module capacity for Maruti Suzuki and Hyundai-Kia export programs. |
| Charging Infrastructure Partnership | 350-kilowatt charging compatibility for 800-volt platforms extends high-speed cruising efficiency and premium positioning. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and dealership operations anchored the qualitative base. Primary interview data combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA fuel economy filings, and KBA type-approval records. Bottom-up segmentation modeling across propulsion architecture, vehicle class, content per vehicle, and regional production cluster triangulated against top-down macroeconomic indicators.
Sensitivity analysis framed volume and value outputs across the projection horizon. Segmentation dimensions modeled included propulsion architecture, vehicle class, OEM tier positioning, content per vehicle thresholds, and regional production cluster concentration. CAGRs derived from historical shipment trajectories, technology substitution curves for electrified platforms, and regulatory compliance timeline impacts. Forecast inputs incorporated aluminum price volatility scenarios and MIIT dual carbon policy implementation pace.
Decision-makers should treat outputs as directional under sustained EV platform standardization and Euro 7 enforcement assumptions; material deviation in battery-electric adoption rates or trade policy shifts would warrant model refresh. Practitioners should keep alternative scenarios live as China MIIT dual carbon goal acceleration and NHTSA fuel economy standard tightening evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Fuel Cell Powertrain Market
Powertrain
Reciprocating Engine Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Crankshaft Position Sensor Market
Powertrain
LNG Engine Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
South America Automotive Market
Powertrain
Clutch Hub Puller Market
Powertrain
Automotive Thrust Washer Market
Powertrain
United States Electro Hydraulic Power Steering Market
Powertrain
Automotive Driveshaft Couplings Market
Powertrain
Automotive Cylinder Block Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Crate Engines Market
Powertrain
Diesel Engine Market