
 Truck Auxiliary Power Units Market | 2026-2036
Truck Auxiliary Power Units Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Auxiliary Power Units Market Insights
Asset-light leasing and power-by-the-hour service contracts is tilting competitive dynamics toward suppliers with strong financing partnerships rather than pure manufacturing scale. Thermo King leverages its integrated cold-chain and APU service networks to bundle auxiliary power with refrigeration contracts. Bergstrom Inc. anchors its position through deep specialization in cab climate systems and thermal management hardware for sleeper cabs.
Truck auxiliary power units are self-contained energy systems that generate electricity and regulate cabin climate independently of the main engine, typically delivering 5–15 kW output through diesel combustion, battery discharge, or fuel-cell chemistry to eliminate overnight idling. Diesel generators still occupy the largest installed base among product types, though battery packs are capturing the fastest growth as lithium-ion energy density improves and fleet electrification targets harden. Thermal management technology leads current revenue pools, while smart controls represent the emerging margin layer as telematics-linked predictive maintenance reshapes service economics.
EPA Phase 3 standards and state-level anti-idling ordinances enforced by California Air Resources Board and analogous agencies in New York and Texas are mandating idle-reduction equipment or penalizing non-compliance, directly expanding the addressable APU population. NHTSA fuel-economy benchmarking and CARB zero-emission vehicle mandates are accelerating hybrid and fuel-cell APU pilots in regulated corridors. Stakeholders must monitor how pending EPA rulemakings on heavy-duty NOx limits recalibrate the cost advantage of battery-electric versus combustion auxiliary systems.
Market Dynamics
Idle-reduction mandates from the EPA and state air-quality boards are compressing replacement cycles for combustion-based auxiliary systems while accelerating fleet trials of battery-electric alternatives. This regulatory pressure is restructuring supplier economics toward service bundling and financing partnerships.
Growth Catalysts
- EPA Phase 3 Standards:Federal greenhouse-gas limits for heavy-duty vehicles tighten idle-time restrictions, forcing long-haul carriers to install auxiliary power units or face operational penalties.
- Lithium-Ion Density Gains:Improved battery chemistry enables overnight cab climate control without diesel combustion, aligning with fleet electrification targets and zero-emission corridor planning.
- California CARB Enforcement:The state's anti-idling ordinances and zero-emission vehicle mandates create a compliance-driven replacement market that ripples through interstate trucking networks.
Market Restraints
- Lithium Price Volatility:Battery-electric APU cost structures remain exposed to raw-material fluctuations in cathode minerals, compressing margins for suppliers without long-term supply agreements.
- Midwest Manufacturing Concentration:Thermal management component fabrication clusters in the Ohio-Illinois corridor create geographic supply risk from regional labor disruptions or weather events.
- Combustion Infrastructure Lock-In:Existing diesel APU service networks and technician training slow fleet transitions to electrochemical alternatives despite regulatory pressure.
Strategic Opportunities
- Texas Interstate Corridors:Weak state-level anti-idling enforcement combined with high trucking density creates an underpenetrated market for compliance-focused APU deployment.
- Fuel-Cell Convergence:Integration of hydrogen fuel-cell chemistry with battery buffers offers extended-range auxiliary power for cross-border Canadian routes beyond charging infrastructure.
- Power-by-the-Hour Contracts:Asset-light leasing models shift revenue from hardware sales to recurring service fees, opening fleet procurement to smaller carriers with constrained capital.
Industry Challenges
- Electronics Technician Scarcity:Battery management system diagnostics and high-voltage safety protocols require skills absent from traditional diesel mechanic training pipelines.
- Dual Certification Burden:Suppliers must simultaneously meet EPA emissions verification and NHTSA electrical safety standards, extending product development timelines.
- Telematics Integration Complexity:Legacy fleet management platforms resist seamless data exchange with smart APU control systems, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Auxiliary Power Units Market |
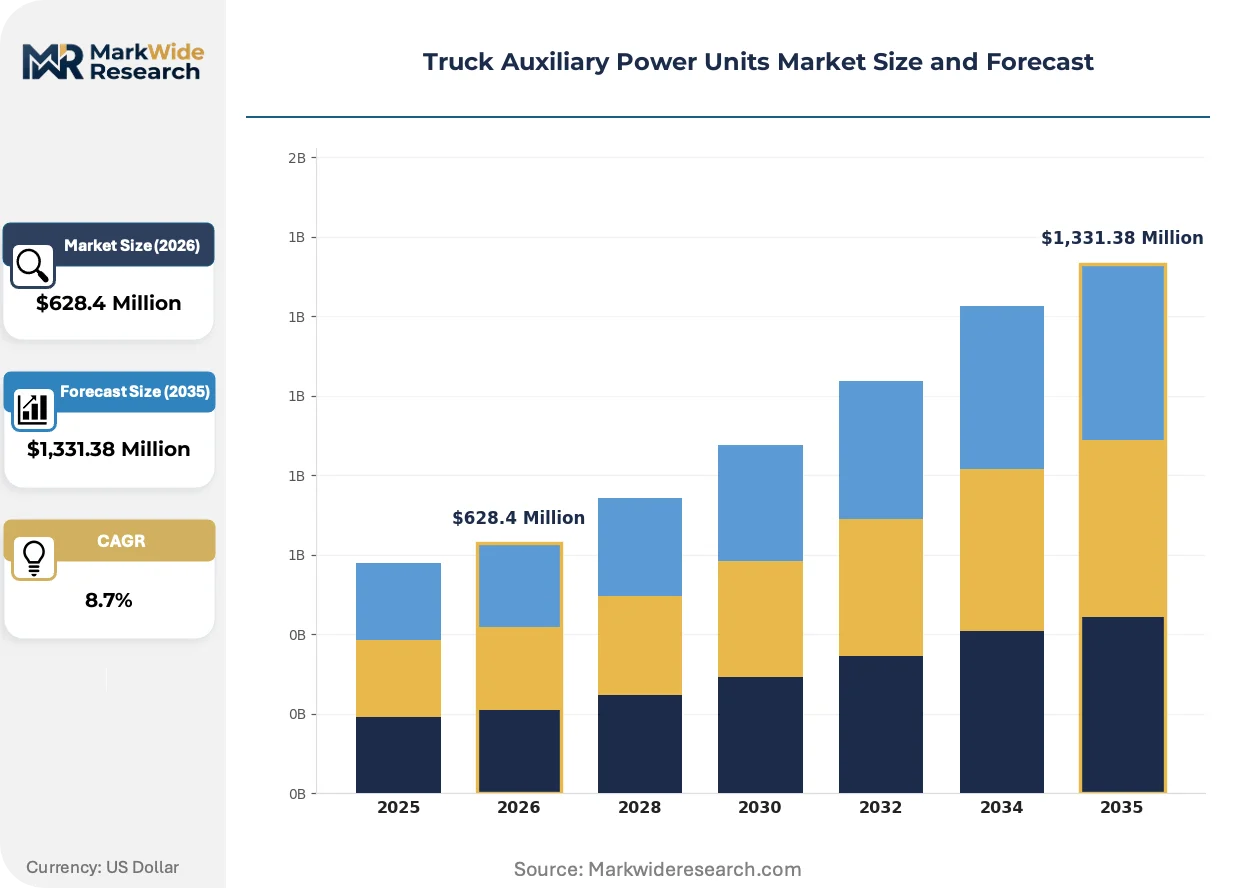
| Market Size in 2026 | $628.4 Million |
| Market Size in 2035 | $1,331.38 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Battery Packs, Hybrid Systems, Fuel Cells Technology: Thermal Management, Energy Storage, Smart Controls, Hybrid Technology End User: Fleet Operators, Owner-Operators, Trucking Companies, Transportation Services Installation: OEM Installation, Aftermarket Installation, Mobile Installations, Professional Services |
| Companies Covered | Thermo King, Carrier Transicold, RigMaster Power, Green APU, Bergstrom Inc., Cummins Inc., Kohler Co., Webasto, Idle Free Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Auxiliary Power Units Market Trends and Innovations
Telematics-enabled predictive maintenance is digitizing service economics while regulatory pressure accelerates electrochemical alternatives to combustion. These forces are compressing traditional hardware margins and elevating software-linked recurring revenue streams.
Solid-state battery chemistries are digitizing how auxiliary power units manage thermal loads and state-of-charge optimization. Sleeper-cab fleet operators in the Pacific Northwest are piloting these systems for multi-day routes with limited charging access. The technology is digitizing warranty and service contract structures by enabling real-time performance monitoring that shifts liability from carrier to supplier.
California CARB zero-emission vehicle mandates and pending EPA heavy-duty NOx rulemakings are tightening the compliance window for diesel auxiliary systems. These regulations force suppliers to maintain dual product lines while accelerating fuel-cell hybrid development. Long-haul carriers operating the I-5 corridor face the most acute compliance pressure and are consolidating procurement around vendors with electrification roadmaps.
Leasing arrangements are displacing outright purchase for battery-electric auxiliary units among mid-size fleets with capital constraints. Traditional equipment distributors lose volume to captive finance arms of major suppliers. This shift concentrates most visibly in the Upper Midwest where seasonal temperature extremes maximize APU utilization rates and justify operational expenditure models.
Truck Auxiliary Power Units Market Segmentation
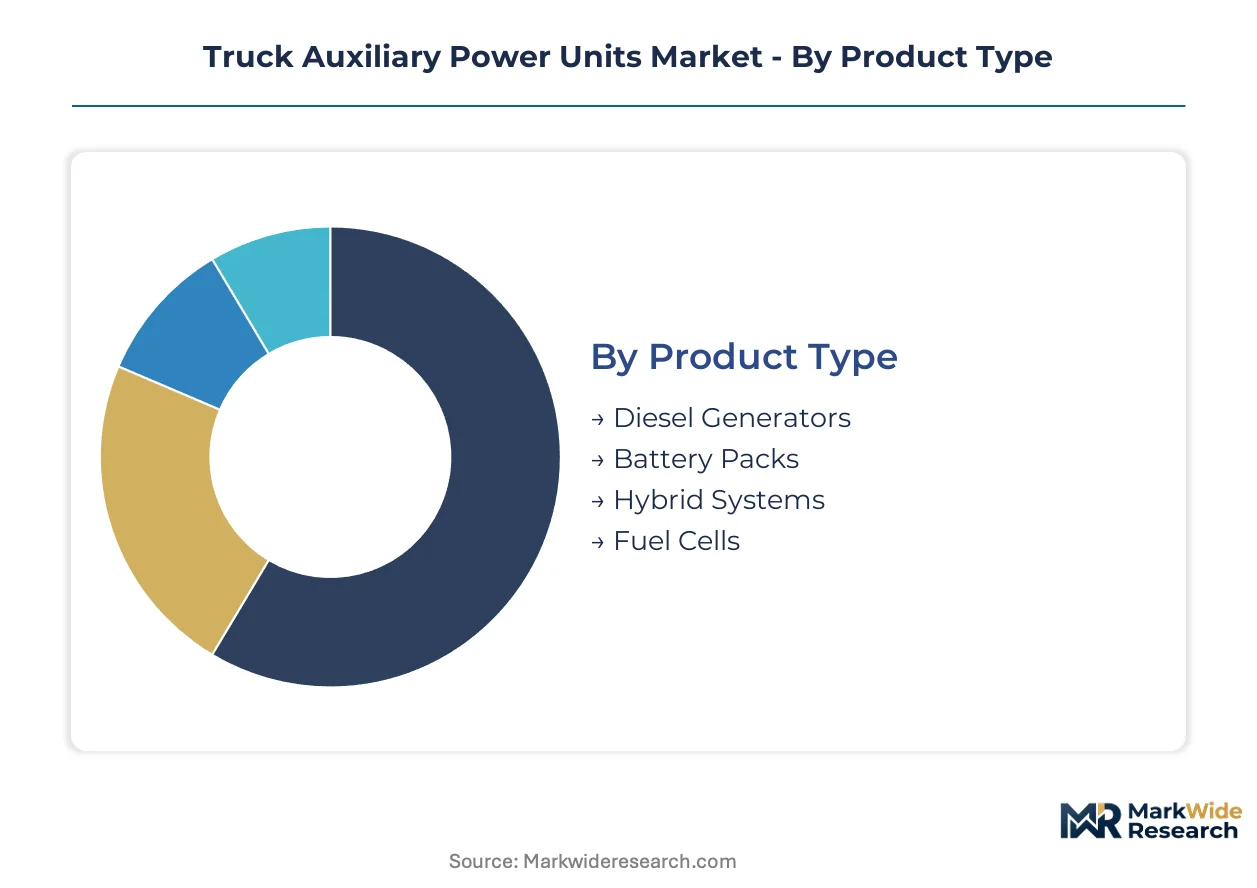
Truck APUs serve divergent duty cycles across sleeper-cab configurations and regional route patterns. Segmentation reveals where service bundling commands premium pricing versus hardware-only transactions.
Product Type:
After-sales service intensity varies sharply by powertrain chemistry, with combustion systems requiring scheduled maintenance and electrochemical alternatives demanding specialized diagnostics.
- Diesel Generators:Compression-ignition engines delivering 5–15 kW output through onboard fuel combustion. Fleet operators along the I-10 corridor from California to Florida maintain the largest installed base due to established service networks and technician familiarity.
- Battery Packs:Lithium-ion electrochemical storage systems discharging stored energy for overnight climate control. Sleeper-cab fleets in the Pacific Northwest are adopting these most aggressively to comply with Oregon and Washington state anti-idling ordinances while eliminating diesel particulate exposure.
- Hybrid Systems:Dual-mode architectures combining combustion generation with battery buffering.
- Fuel Cells:Hydrogen-fed proton-exchange-membrane systems for extended-range auxiliary power.
By volume, Diesel Generators leads. By growth pace, Battery Packs is climbing the fastest.
Technology:
Cost tier stratification separates mature thermal hardware from emerging digital control layers that reshape supplier margins.
- Thermal Management:Climate-control hardware including compressors, heat exchangers, and ducting systems that regulate sleeper-cab temperature. Long-haul carriers operating cross-border Canadian routes prioritize these systems due to extreme temperature differentials across seasons.
- Smart Controls:Telematics-linked control units enabling predictive maintenance and remote diagnostics. Fleet management platforms in the Upper Midwest are integrating these systems first, where high APU utilization rates justify connectivity expenditures.
- Energy Storage:Battery management systems and thermal runaway protection electronics.
- Hybrid Technology:Power electronics coordinating multiple energy sources.
By revenue contribution, Thermal Management dominates. By margin expansion, Smart Controls is gaining share fastest.
End User:
Customer type determines procurement sophistication, with large fleets negotiating power-by-the-hour contracts while smaller operators favor outright purchase.
- Fleet Operators:Asset-intensive carriers with centralized procurement functions managing hundreds of sleeper-cab tractors. These buyers in Texas and the Southeast are consolidating vendor relationships to secure volume pricing on battery-electric conversions.
- Trucking Companies:Mid-size carriers with mixed fleet compositions balancing compliance costs against capital constraints. Operators in the Ohio-Illinois manufacturing corridor are leasing battery-electric units to avoid upfront acquisition risk.
- Owner-Operators:Independent drivers with single-vehicle operations.
- Transportation Services:Third-party logistics providers specifying APU equipment for contracted capacity.
By unit volume, Fleet Operators leads. By contract value growth, Trucking Companies is expanding most quickly.
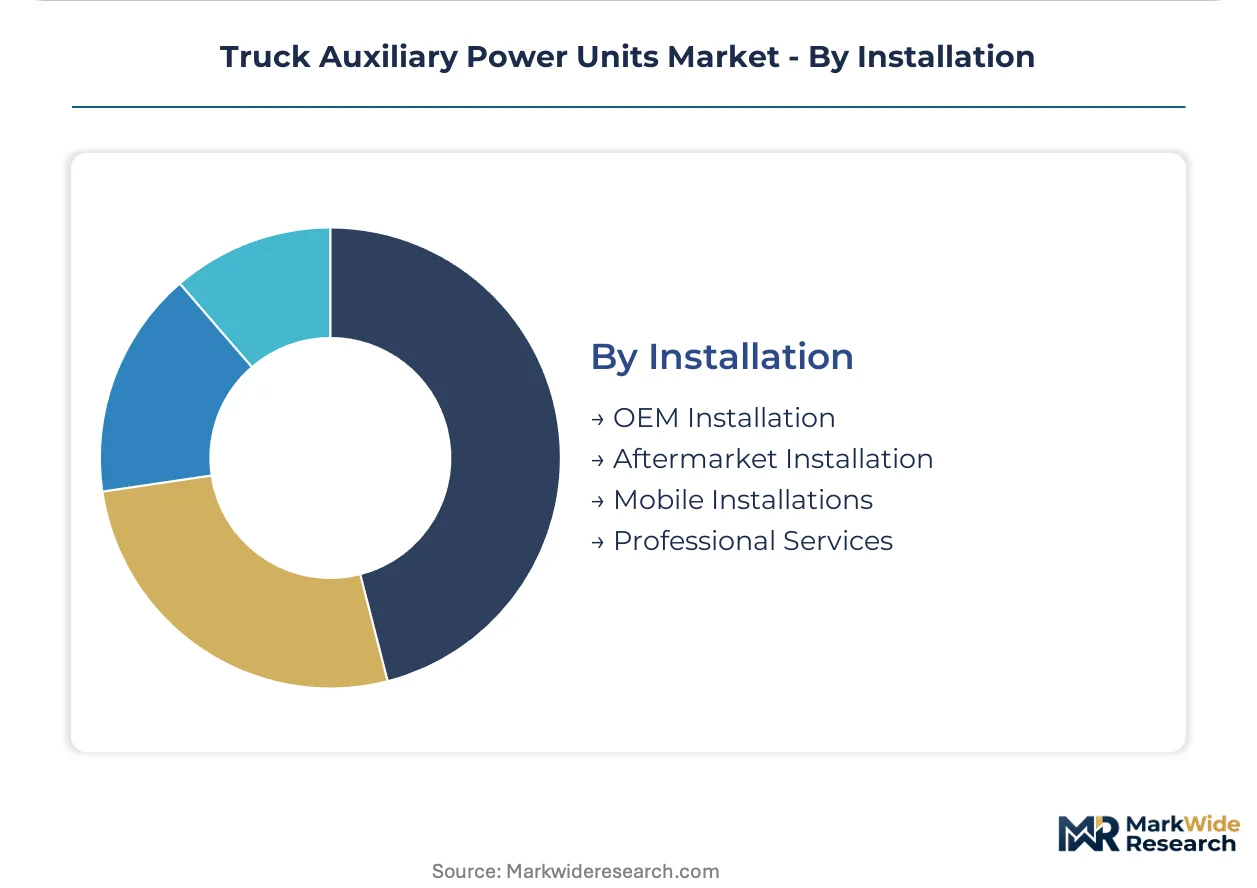
Installation:
Channel structure divides between factory-integrated systems and post-delivery retrofit opportunities with divergent margin profiles.
- OEM Installation:Factory-integrated auxiliary power systems specified at vehicle order. Major sleeper-cab manufacturers in Michigan and Tennessee are expanding electrified APU offerings to meet fleet sustainability procurement criteria.
- Aftermarket Installation:Retrofit services performed at independent truck service centers. Installers in California are experiencing strongest demand as CARB enforcement deadlines accelerate replacement cycles for non-compliant diesel units.
- Mobile Installations:On-site service at fleet terminals or truck stops.
- Professional Services:Engineering consultation and custom integration for specialized applications.
By installation count, Aftermarket Installation leads. By growth trajectory, OEM Installation is climbing the fastest as electrification hardens factory specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States imports battery-electric auxiliary power systems from South Korean and Japanese suppliers while exporting diesel-generator components to Canadian and Mexican cross-border fleets. This trade flow concentrates regulatory compliance costs in domestic manufacturing clusters and accelerates technology transfer through joint ventures.
United States
Long-haul trucking density along Interstate corridors drives replacement demand as EPA Phase 3 standards tighten idle-time restrictions. The California Air Resources Board enforces the nation's strictest anti-idling ordinances, creating a compliance-driven market that ripples through interstate networks. Manufacturing clusters in Michigan and Tennessee specialize in factory-integrated electrified APU systems for major sleeper-cab producers.
Canada
Cross-border carriers operating Vancouver-Toronto routes require extended-range auxiliary power for extreme temperature differentials across seasons. Transport Canada's proposed heavy-duty vehicle emissions regulations mirror EPA frameworks, pushing fleet conversion timelines. Industrial concentration in Southern Ontario around Windsor and Hamilton supports thermal management component fabrication for North American supply chains.
Germany
European Union Green Deal targets and impending Euro VII emissions standards compress the viable window for combustion-based auxiliary systems. The KBA enforces type-approval requirements that extend product development timelines for electrochemical alternatives. Manufacturing gravity centers on Baden-Württemberg and Bavaria, where automotive supplier networks integrate APU development with commercial vehicle electrification programs.
China
Domestic heavy-duty truck production volume exceeds any single market, creating scale economies for battery-electric APU component suppliers. MIIT dual carbon goals and GB standards for commercial vehicle emissions accelerate fleet electrification procurement mandates. Yangtze River Delta industrial clusters around Shanghai and Suzhou concentrate lithium-ion cell production and battery management system manufacturing.
Japan
MetI technology roadmaps prioritize solid-state battery commercialization for auxiliary power applications in long-haul logistics. Domestic regulations on diesel particulate emissions in port corridors and urban freight zones restrict combustion-based system deployment. Kanto region manufacturing around Tokyo and Yokohama specializes in precision thermal management components and telematics-integrated control systems.
Truck Auxiliary Power Units Market Competitive Landscape
On the supply side, the industry is consolidating around suppliers with integrated service networks and financing capabilities rather than pure manufacturing scale. Three strategic archetypes dominate: thermal management specialists with deep cab-climate expertise, diversified powertrain conglomerates leveraging engine manufacturing scale, and battery-system integrators capturing electrification transitions. Competitive moves concentrate on service bundling partnerships and captive finance arm development to support power-by-the-hour contract expansion.
Among diversified industrial conglomerates, Cummins Inc. and Kohler Co. occupy positions anchored by legacy power generation expertise and established technician training networks. Within the climate-system specialization tier, Bergstrom Inc. exemplifies focused positioning through sleeper-cab thermal hardware, while Thermo King represents integrated cold-chain and auxiliary power service bundling. These three companies illustrate how supplier economics tilt toward recurring revenue models and fleet financing partnerships rather than transactional hardware sales.
| Leading Market Players |
|---|
| Thermo King |
| Carrier Transicold |
| RigMaster Power |
| Green APU |
| Bergstrom Inc. |
| Cummins Inc. |
| Kohler Co. |
| Webasto |
| Idle Free Systems |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in South Korean lithium-ion cell production is compressing supplier margins and forcing tiered pricing concessions to fleet procurement teams across North American long-haul corridors. This utilization imbalance rewards buyers with volume leverage while squeezing mid-tier battery pack assemblers without captive cathode supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture fleet operators demanding CARB-certified zero-emission compliance with bundled predictive maintenance, while economy tiers serve price-sensitive owner-operators through stripped hardware-only transactions. Cost compression in the standard tier is intensifying because Korean cell suppliers are offloading excess inventory into North American aftermarket channels. Fleet operators with centralized procurement functions exhibit lowest price sensitivity, whereas independent trucking companies in the Ohio-Illinois corridor demonstrate highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for battery management system electronics and thermal runaway protection components. Manufacturing gravity centers on South Korea, Japan, and China for lithium-ion cells, with Michigan and Tennessee housing final assembly for OEM-integrated units. The supply chain rests on cathode active materials from Indonesian nickel and Chilean lithium brine operations. Single-source vulnerability concentrates in semiconductor content for smart control modules. Distribution runs through captive finance arms of major suppliers and independent truck service centers with divergent margin profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across state-level anti-idling ordinances is fragmenting demand into compliance-driven replacement cycles and voluntary upgrade niches. This dispersion creates entry points for specialized service bundlers and regional installers.
For Market Incumbents: Entrench position by deepening backward integration into thermal management component fabrication and securing long-term cathode supply agreements with Korean cell producers. Battery-electric APU challengers with power-by-the-hour financing capabilities represent the primary substitution threat. Priority investment should target telematics-integrated smart controls where recurring revenue margins exceed hardware-only transactions. For New Entrants and Emerging Players: Build out service infrastructure in Texas interstate corridors where weak state-level enforcement and high trucking density create underpenetrated compliance deployment opportunities. The most penetrable segment is mid-size trucking companies in the Upper Midwest seeking leased battery-electric units to avoid capital expenditure risk. Go-to-market execution should emphasize mobile installation capabilities at fleet terminals to bypass established distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with captive finance arms and integrated cold-chain service networks. Long-term viability over the coming decade favors acquisition targets with demonstrated electrification roadmaps and NHTSA electrical safety certification capabilities. The critical inflection signal to monitor is EPA finalization of heavy-duty NOx rulemakings that would recalibrate battery-electric versus combustion auxiliary system economics.| Strategic Initiative | Industry Significance |
|---|---|
| Power-by-the-Hour Contract Expansion | Shifts revenue from hardware sales to recurring service fees among capital-constrained mid-size fleets. |
| Backward Integration into Cathode Supply | Reduces lithium price volatility exposure for battery pack assemblers without long-term Korean agreements. |
| Telematics Platform Integration | Enables predictive maintenance revenue streams linked to fleet management software in the Upper Midwest. |
| CARB Zero-Emission Certification Investment | Unlocks California aftermarket replacement demand driven by enforcement deadline acceleration. |
| Fuel-Cell Hybrid Development Partnership | Addresses extended-range requirements for cross-border Canadian routes beyond charging infrastructure reach. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors, aftermarket service center managers, OEM platform engineers, and thermal management component fabricators. Secondary validation drew from EPA regulatory filings, NHTSA safety standard documentation, CARB enforcement bulletins, and SEC disclosures from diversified powertrain conglomerates. Bottom-up unit demand modeling triangulated against top-down market sizing across product type, technology tier, and end-user segmentation.
Calibration against historical replacement cycle data and regulatory implementation timelines anchored projections across the analysis window. Segmentation dimensions modeled include powertrain chemistry, thermal management versus smart control technology layers, fleet operator versus owner-operator end-user archetypes, and OEM versus aftermarket installation channels. CAGRs were derived from regression analysis of adoption curves correlated with state-level anti-idling ordinance enforcement intensity and lithium-ion cell cost trajectories.
Stress conditions across lithium carbonate price bands, EPA rulemaking acceleration scenarios, and Midwest manufacturing labor disruption events were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet electrification target compliance and charging infrastructure deployment pacing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Transmission Control System Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
Europe Electro Hydraulic Power Steering Market
Powertrain
Fuel Pumps Market
Powertrain
Turbocharger Actuators Market
Powertrain
Sway Bar Bushing Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Diesel Engine Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
Automotive Cylinder Block Market