
 Automotive Engine Piston Rings Market | 2026-2036
Automotive Engine Piston Rings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Piston Rings Market Outlook
Foundry metallurgist availability is collapsing across the Midwestern United States and Western Europe, constraining cast iron ring output just as OEMs demand tighter tolerances. Tenneco Inc. leverages its captive steel processing to buffer against raw material volatility, while MAHLE GmbH anchors European supply through its Stuttgart-centered R&D and forging footprint. Nippon Piston Ring Co., Ltd. dominates East Asian OEM channels with precision machining capabilities that sustain just-in-time contracts with Toyota and Honda.
Automotive engine piston rings are circular metallic or composite seals installed in grooves on piston crowns, engineered to maintain combustion pressure, control oil consumption, and transfer heat to the cylinder wall; modern rings achieve radial wall thickness tolerances within 0.01 mm and face coatings such as chromium-ceramic or PVD diamond-like carbon to survive specific power outputs exceeding 100 kW per liter. Cast iron rings retain the largest volume share in aftermarket channels due to cost parity and established rebuild protocols, yet coated steel rings generate the fastest OEM adoption as downsized turbocharged engines elevate thermal and mechanical loads. The aftermarket segment concentrates margin pools in Latin America and Southeast Asia where vehicle parc age exceeds twelve years and repair shops favor two-piece oil control ring sets over full replacement.
The EPA enforces Tier 3 evaporative and tailpipe standards that mandate reduced blow-by rates, directly tightening ring seal specifications for gasoline engines sold in the United States, while the EU Green Deal and Euro 7 proposals from EMA frameworks compel European suppliers to validate chromium-free coating chemistries. Japan's METI coordinates domestic OEMs through JIS standards that specify nitriding depth and surface roughness parameters, creating a technical barrier for non-Japanese entrants. Stakeholders must monitor how California Air Resources Board waivers and EU-27 delegated acts synchronize on particulate number limits, as divergence would fragment ring design portfolios and force dual certification investments.
Market Dynamics
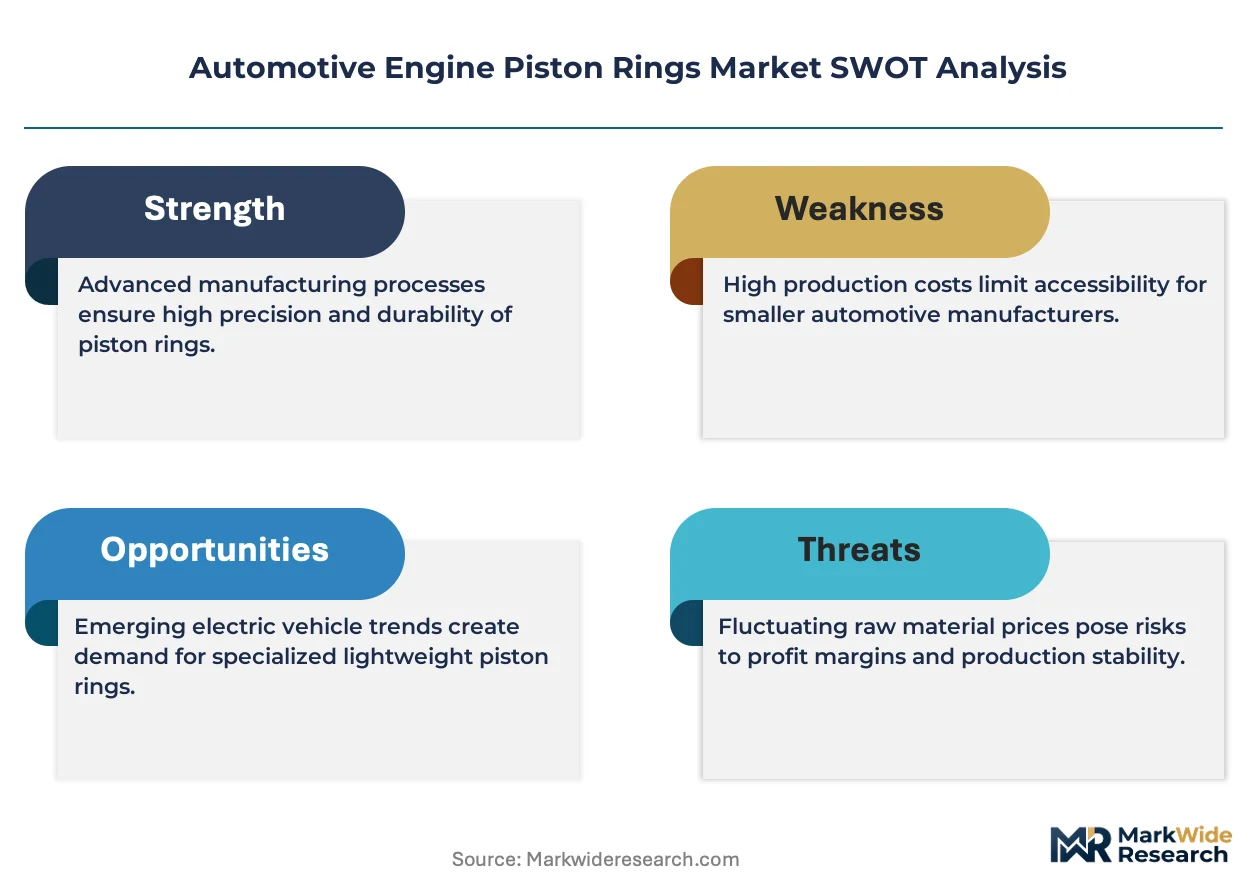
EPA Tier 3 and Euro 7 emission standards are compressing blow-by tolerance thresholds, forcing foundries to retool for nitrided steel ring production while cast iron capacity erodes across the Midwestern United States and Western Europe.
Growth Catalysts
- Downsized turbocharged gasoline engines:OEM powertrain strategies prioritize thermal efficiency gains that elevate mechanical loads on piston rings, accelerating coated steel ring specifications.
- China's dual carbon goals:Domestic OEM procurement of nitrided steel rings is expanding fastest globally as MIIT efficiency mandates tighten combustion chamber sealing requirements.
- Euro 7 proposals:EMA frameworks compel chromium-free coating validation, creating technical differentiation opportunities for suppliers with qualified alternative chemistries.
Market Restraints
- Foundry metallurgist scarcity:Cast iron ring output constraints in the Midwestern United States and Western Europe limit supply elasticity as OEMs demand tighter radial wall tolerances.
- Steel price volatility:Alloy steel input costs fluctuate with energy markets, compressing margin buffers for non-vertically integrated ring manufacturers.
- Chromium coating restrictions:REACH substance evaluations and EU Green Deal chemistry roadmaps threaten established PVD-chromium production lines with phase-out timelines.
Strategic Opportunities
- Latin American aftermarket concentration:Vehicle parc age exceeding twelve years in Brazil and Mexico sustains margin pools for two-piece oil control ring sets preferred by independent repair channels.
- Hybrid powertrain expansion:Gasoline-electric architectures with frequent stop-start cycles demand enhanced oil control ring durability, opening specification windows for advanced face coatings.
- India's PLI scheme:Automotive component manufacturing incentives under DGFT frameworks attract ring suppliers seeking to localize supply for Maruti Suzuki and Tata Motors.
Industry Challenges
- Nitriding depth certification:JIS standards enforced by METI create technical barriers for non-Japanese entrants seeking Toyota and Honda just-in-time contracts.
- Dual certification investments:Divergence between California Air Resources Board waivers and EU-27 delegated acts on particulate number limits fragments ring design portfolios.
- Precision machining talent:East Asian OEMs sustain competitive moats through captive technician training programs that Western suppliers struggle to replicate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Piston Rings Market |
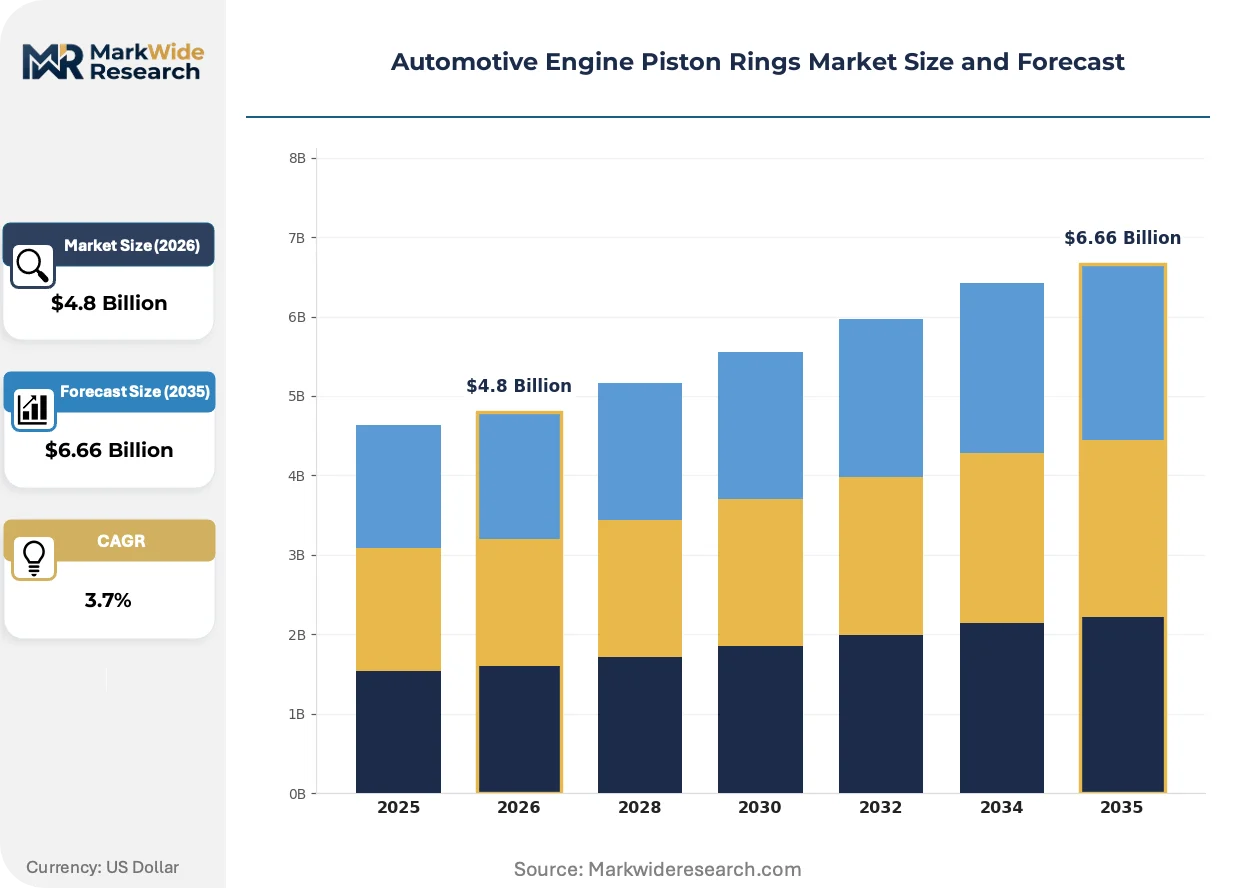
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Cast Iron, Polymer, Coated Engine Type: Internal Combustion, Diesel, Gasoline, Hybrid Manufacturing Process: Forging, Casting, Machining, Extrusion End User: OEMs, Aftermarket, Fleet Operators, Repair Shops |
| Companies Covered | TPR Co., Ltd., Hastings Manufacturing Company, LLC, Nippon Piston Ring Co., Ltd., Performance Sealing, Inc., Precision Rings, Inc. of Indianapolis, Tenneco Inc., Shriram Pistons & Rings Ltd., Grover Corporation, MAHLE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Piston Rings Market Strategic Shifts
Coating chemistry evolution and procurement model restructuring are redrawing competitive boundaries between captive OEM supply and independent aftermarket channels.
PVD diamond-like carbon face coatings are displacing traditional chromium-ceramic layers in high-specific-output engines. European premium OEMs specify these for downsized turbocharged powertrains exceeding 100 kW per liter. The shift is compressing demand for legacy electroplated ring architectures in original equipment procurement.
EU Green Deal chemistry roadmaps and ECHA substance evaluations are accelerating chromium-free coating development. Suppliers must validate alternative PVD chemistries under compressed timelines to maintain European OEM qualification status. German and French automakers are demanding supply chain documentation proving compliance with delegated acts on hazardous substance restrictions.
Aftermarket procurement is consolidating through distributor private-label programs in Southeast Asia. Independent repair shops in Indonesia and Thailand now source ring sets through consolidated parts platforms rather than traditional jobber networks. This channel compression favors suppliers with certified quality management systems and regional logistics footprints.
Automotive Engine Piston Rings Market Segmentation
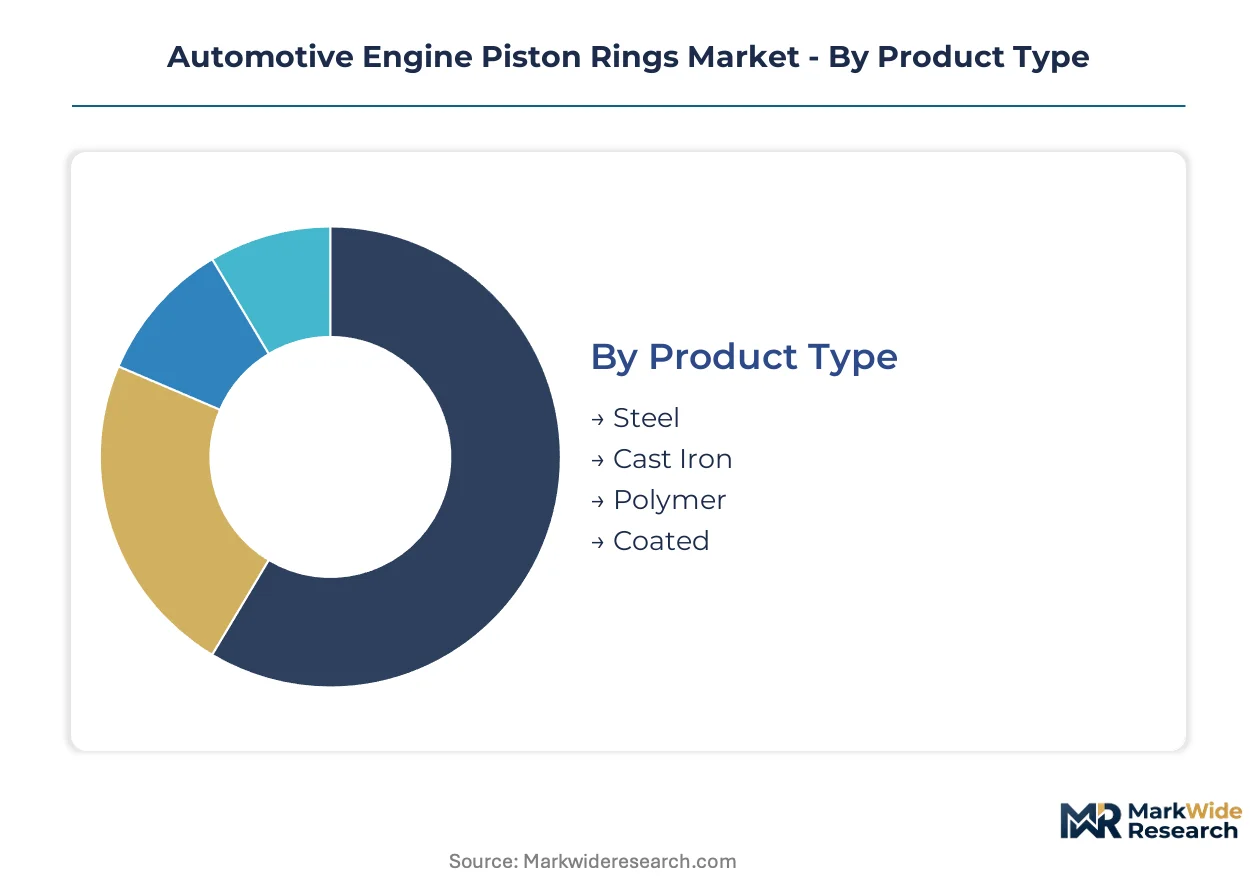
Piston ring specifications diverge sharply between OEM and aftermarket channels, with material composition and manufacturing precision determining margin capture. Segmentation reveals how emission regulations and powertrain electrification are reallocating value across traditional metallurgical categories.
Product Type:
Margin pools concentrate in coated steel rings where OEMs pay premiums for thermal durability in downsized turbocharged engines.
- Steel:Nitrided alloy steel rings withstand cylinder pressures exceeding 200 bar in high-specific-output gasoline engines. Chinese OEMs through MIIT efficiency mandates are expanding procurement fastest, though JIS nitriding depth certifications from METI limit supplier qualification.
- Coated:PVD diamond-like carbon and chromium-ceramic face coatings reduce friction losses below 1.5 percent in engines exceeding 100 kW per liter. European premium OEMs specify these for Euro 7 pre-compliance, creating technical differentiation moats for qualified suppliers.
- Cast Iron:Gray cast iron rings retain aftermarket dominance in Latin American and Southeast Asian rebuild markets where cost parity overrides performance specifications.
- Polymer:PTFE-composite rings serve niche low-friction applications in range-extender hybrid architectures with intermittent combustion cycles.
Cast iron holds installed capacity across Midwestern US and Western European foundries. Coated rings are rotating up the share rankings as EPA Tier 3 blow-by thresholds tighten.
Engine Type:
Volume concentration follows gasoline powertrain production, though hybrid architectures are rewriting durability specifications.
- Gasoline:Downsized direct-injection engines with turbocharging elevate thermal loads on top compression rings, forcing specification shifts toward nitrided steel and advanced face coatings. OEM procurement concentrates in Germany, Japan, and the United States.
- Hybrid:Gasoline-electric powertrains with stop-start cycling demand enhanced oil control ring durability against thermal shock. Toyota and Honda just-in-time contracts favor Japanese suppliers with precision machining capabilities.
- Diesel:Compression ignition rings face declining OEM specification in passenger vehicles as Euro 7 particulate number limits complicate combustion chamber sealing.
- Internal Combustion:This residual category captures legacy naturally aspirated engines in emerging market vehicle parc with replacement intervals exceeding 150,000 kilometers.
Gasoline maintains the dominant production footprint. Hybrid specifications are climbing fastest as powertrain electrification accelerates.
Manufacturing Process:
Cost tier separation runs between precision machining for OEM qualification and casting for aftermarket volume.
- Machining:CNC grinding and lapping achieve radial wall thickness tolerances within 0.01 mm required for EPA Tier 3 blow-by compliance. Nippon Piston Ring and MAHLE anchor this capability in East Asia and Europe respectively.
- Forging:Closed-die forging of alloy steel blanks produces grain structures optimized for nitriding depth uniformity. Tenneco's captive steel processing buffers against raw material volatility.
- Casting:Centrifugal and sand casting of gray iron persists in aftermarket channels where dimensional tolerances relax to 0.03 mm.
- Extrusion:Powder metallurgy extrusion serves polymer-composite ring production for low-load hybrid applications.
Machining commands the premium pricing tier. Forging is rotating up the share rankings as nitrided steel specifications expand.
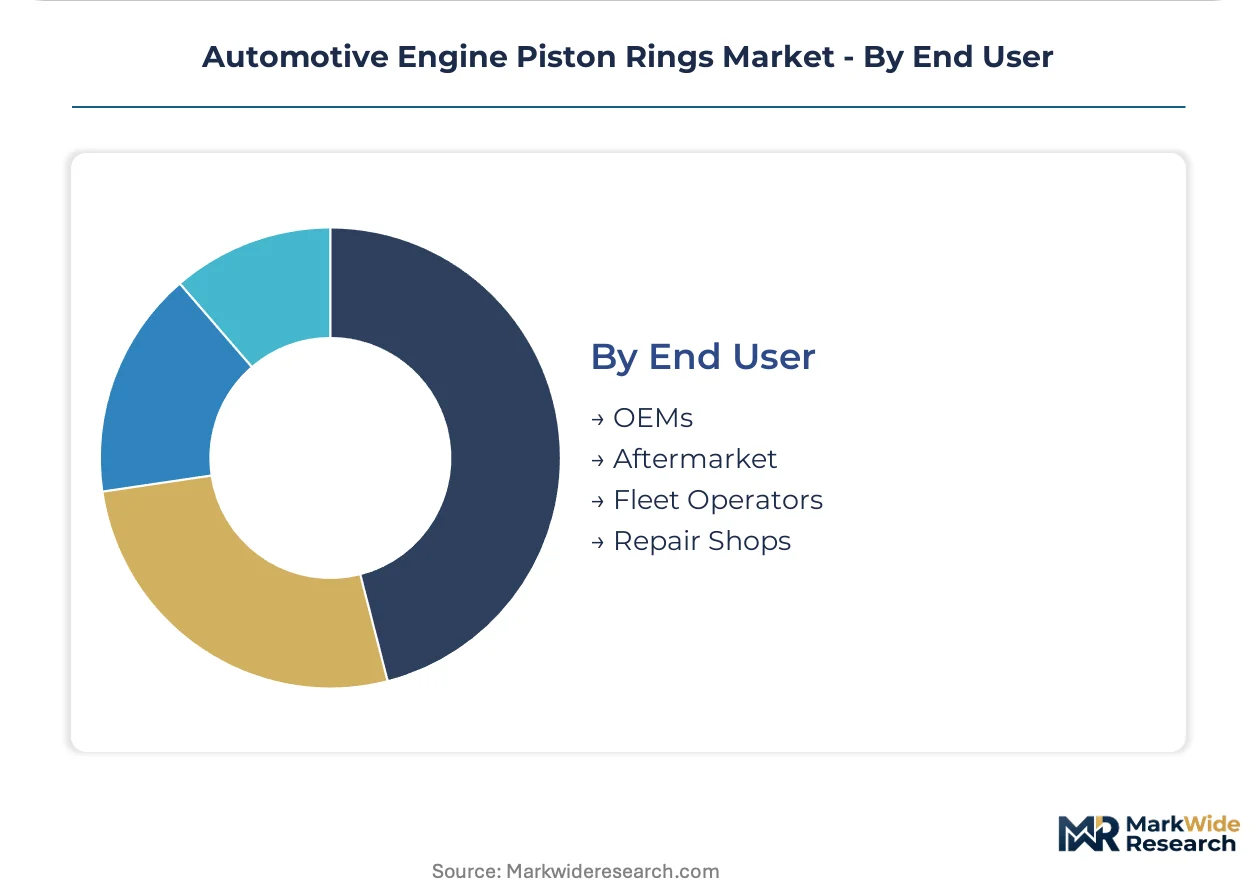
End User:
Customer type determines certification burden and pricing power, with OEMs demanding full traceability and aftermarket tolerating broader specifications.
- OEMs:Original equipment procurement requires IATF 16949 certification, JIS nitriding validation for Japanese automakers, and REACH-compliant coating documentation for EU supply. Contract durations typically span five to seven years with indexed steel price adjustments.
- Aftermarket:Independent repair channels in Brazil, Mexico, Indonesia, and Thailand favor two-piece oil control ring sets over full replacement. Distributor private-label consolidation in Southeast Asia favors suppliers with regional logistics footprints.
- Repair Shops:Jobber networks in Latin America source cast iron ring sets through traditional wholesale channels, though platform consolidation is compressing margins.
- Fleet Operators:Commercial vehicle fleets with centralized maintenance contracts specify premium coated rings for extended drain intervals and reduced total cost of ownership.
OEMs anchor the value chain through specification authority. Aftermarket channels are rotating up the share rankings as vehicle parc age exceeds twelve years in major emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's OEMs specify nitrided steel rings at the highest penetration rates globally, while Latin American aftermarket channels retain cast iron dominance due to vehicle parc age exceeding twelve years. This consumption-mix differential shapes procurement patterns across major automotive production clusters.
China
Domestic OEM procurement of nitrided steel rings accelerates fastest globally as MIIT efficiency mandates tighten combustion chamber sealing specifications. The dual carbon goals framework compels automakers to prioritize thermal efficiency gains in downsized turbocharged gasoline engines. Shanghai and Beijing anchor the premium specification tier, with Yangtze River Delta foundries scaling coated steel capacity to serve BYD and Geely just-in-time contracts.
Germany
Premium OEMs specify PVD diamond-like carbon face coatings for powertrains exceeding 100 kW per liter, driving specification premiums in the European market. ECHA substance evaluations and EU Green Deal chemistry roadmaps accelerate chromium-free coating validation timelines. Stuttgart-centered R&D clusters in Baden-Württemberg concentrate forging and precision machining capabilities for Euro 7 pre-compliance programs.
United States
EPA Tier 3 blow-by tolerance thresholds compress ring seal specifications for gasoline engines, forcing foundry retooling investments across Midwestern manufacturing belts. Foundry metallurgist scarcity in Michigan and Ohio constrains cast iron ring output elasticity. Tennessee and Michigan anchor captive steel processing investments that buffer against alloy input cost volatility.
Japan
METI-coordinated JIS standards specify nitriding depth and surface roughness parameters, creating technical qualification barriers for non-domestic entrants seeking Toyota and Honda contracts. Precision machining capabilities concentrate in Aichi Prefecture's Nagoya industrial corridor. Kanto region suppliers sustain just-in-time delivery networks through captive technician training programs.
Brazil
Vehicle parc age exceeding twelve years sustains aftermarket margin pools for two-piece oil control ring sets preferred by independent repair channels in São Paulo and Minas Gerais. ANVISA chemical substance frameworks influence coating import regulations. Distributor private-label consolidation in the Southeast region favors suppliers with certified quality management systems and regional logistics footprints.
Automotive Engine Piston Rings Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive steel processing and precision machining capabilities determining contract access. The structure stratifies between vertically integrated manufacturers with in-house alloy production and independent specialists competing on coating chemistry differentiation. Three archetypes dominate: integrated metallurgical processors, precision machining specialists, and aftermarket-focused volume fabricators. Competitive moves center on nitriding depth certification investments and chromium-free coating validation partnerships.
Within the integrated processor tier, Tenneco Inc. and MAHLE GmbH occupy positions defined by captive raw material control and European-centered R&D footprints. Among East Asian precision specialists, Nippon Piston Ring Co., Ltd. exemplifies the machining-intensive archetype required for Japanese OEM just-in-time contracts. These three entities represent the capability spectrum spanning upstream metallurgy through downstream coating qualification.
| Leading Market Players |
|---|
| TPR Co., Ltd. |
| Hastings Manufacturing Company, LLC |
| Nippon Piston Ring Co., Ltd. |
| Performance Sealing, Inc. |
| Precision Rings, Inc. of Indianapolis |
| Tenneco Inc. |
| Shriram Pistons & Rings Ltd. |
| Grover Corporation |
| MAHLE GmbH |
| Others |
Value Chain & Pricing Dynamics
EPA Tier 3 and Euro 7 certification regimes gate both supplier qualification and price differentiation simultaneously, compressing margin structures for non-compliant foundries while elevating premiums for nitrided steel ring producers with validated coating chemistries. OEM procurement contracts index alloy steel input costs against energy market volatility, forcing tiered pricing separation between IATF-certified precision machinists and aftermarket cast iron fabricators.
Pricing Analysis
Long-term offtake agreements spanning five to seven years dominate OEM procurement, with indexed steel price adjustments buffering Tenneco and MAHLE against raw material volatility. Price differentiation rests on JIS nitriding depth certification and REACH-compliant coating documentation, separating premium European and Japanese suppliers from standard-tier competitors. Cost compression in cast iron aftermarket channels intensifies because distributor private-label consolidation in Southeast Asia compresses jobber margins. Fleet operators demonstrate lowest price sensitivity, accepting coated ring premiums for extended drain intervals, while independent Latin American repair shops prioritize two-piece oil control sets on unit cost alone.
Supply Chain Analysis
China, Germany, and Japan anchor nitrided steel ring production, with Yangtze River Delta foundries scaling fastest to serve BYD and Geely contracts. Raw material dependencies draw from alloy steel mills, chromium-ceramic coating substrates, and PVD deposition gases. Single-source vulnerability concentrates in Japanese precision machining capabilities, where METI-coordinated technician training programs sustain Toyota and Honda just-in-time networks. Distribution runs through captive OEM supply chains for original equipment, while aftermarket channels consolidate through regional distributor platforms in Brazil and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Downsized turbocharged powertrain proliferation and chromium-free coating mandates constitute a dual regulatory-technological inflection, compressing legacy electroplated ring architectures while opening specification windows for qualified alternative chemistries.
For Market Incumbents: Secure JIS nitriding depth certifications ahead of METI enforcement timelines to defend Japanese OEM contract access against emerging Chinese competitors. Anchor European qualification through ECHA-compliant coating validation partnerships, as REACH substance evaluations threaten established PVD-chromium production lines with phase-out risk. Deepen upstream control over alloy steel processing to buffer margin compression from energy-market-linked input volatility. For New Entrants and Emerging Players: Differentiate on chromium-free PVD chemistries for Euro 7 pre-compliance programs, where German and French automakers demand supply chain documentation under compressed validation timelines. Target Latin American aftermarket consolidation, where vehicle parc age exceeding twelve years in Brazil and Mexico sustains margin pools for two-piece oil control ring sets. Penetrate through distributor private-label partnerships requiring certified quality management systems and regional logistics footprints rather than direct jobber networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision machining segments, as EPA Tier 3 blow-by tolerances force CNC grinding and lapping investments achieving radial wall thickness within 0.01 mm. Five-to-ten-year viability favors vertically integrated processors with captive steel production and coating qualification capabilities over standalone foundries facing metallurgist scarcity. Monitor divergence between California Air Resources Board waivers and EU-27 delegated acts on particulate number limits as the signal indicating whether dual certification investments fragment supplier portfolios or harmonize toward single-standard dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Chromium-Free Coating Validation | ECHA substance evaluations under EU Green Deal roadmaps accelerate alternative chemistry qualification timelines for European OEM supply. |
| Nitriding Depth Certification Investment | METI-coordinated JIS standards create technical barriers that qualified suppliers leverage for Toyota and Honda just-in-time contracts. |
| Captive Steel Processing Expansion | Tenneco's backward integration into alloy production buffers margin compression from energy-market-linked raw material volatility. |
| Aftermarket Distributor Consolidation | Platform compression in Indonesia and Thailand favors suppliers with certified quality systems over traditional jobber networks. |
| Hybrid Powertrain Specification Development | Stop-start cycling durability demands from gasoline-electric architectures open coating specification windows for enhanced oil control rings. |
Study Parameters
Desk research of EPA regulatory filings, EMA framework proposals, MIIT efficiency mandates, and JIS standard documentation preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and foundry metallurgists across Midwestern US and Western European manufacturing belts. Secondary validation drew from vehicle production databases, customs trade records for alloy steel inputs, and SEC filings of publicly traded component manufacturers. Bottom-up segment sizing triangulated against top-down OEM procurement volume estimates.
Variance decomposition across product type, engine architecture, manufacturing process, and end-user channel informed the analytical framework throughout the projection horizon. CAGRs derived from segment-level production forecasts, content-per-vehicle assumptions for downsized turbocharged engines, and penetration rate modeling for nitrided steel specifications across Chinese, German, and US OEM procurement. Forecast inputs incorporated MIIT dual carbon goal implementation timelines and Euro 7 delegated act progression through EU legislative bodies.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Tier 3 enforcement, Euro 7 chemistry roadmap adherence, and continued Chinese OEM expansion of nitrided steel ring procurement; material deviation in regulatory synchronization or powertrain electrification pace would warrant model refresh. Recalibration cycles align with material shifts in emission standard implementation schedules and hybrid powertrain production volume inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
EGR and Emissions Control Actuator Systems Market
Powertrain
Global Automotive Drive Shaft Market
Powertrain
Engines Market
Powertrain
Automotive Drivetrain Market
Powertrain
Transmission Fluids Market
Powertrain
Torque Limiter Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Crankshaft Position Sensor Market
Powertrain
Automatic Transmission Market
Powertrain
Crankshaft Oil Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Dual Clutch Transmission (DCT) Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Tuning Box Market
Powertrain
Automotive Camless Engine Market