
 Automatic Transmission Torque Converter Market | 2026-2036
Automatic Transmission Torque Converter Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Transmission Torque Converter Market Insights
Aftermarket refurbishment revenue is tilting toward OEM-captive remanufacturing programs as original equipment producers extend control over component lifecycle value. ZF Friedrichshafen AG leverages its integrated transmission-torque converter architecture to dominate European OEM supply channels. Aisin Corporation anchors Asian production networks through captive foundry and precision stamping operations. BorgWarner Inc. competes on electronic integration, embedding lock-up clutch controls into broader mechatronic systems.
An automatic transmission torque converter is a fluid coupling device comprising an impeller, turbine, and stator assembly housed within a sealed converter shell, typically measuring 240-350 mm in diameter for passenger vehicle applications; it transmits engine torque to the transmission input shaft while multiplying torque through fluid dynamics during vehicle launch. The device serves to isolate engine torsional vibrations from the driveline and enable smooth power transfer across varying load conditions. Lock-up technology leads product type value pools as automakers prioritize highway fuel economy, while integrated electronic-hydraulic systems command premium positioning by combining clutch actuation with real-time adaptive control algorithms. Conventional hydraulic designs retain volume dominance in emerging-market commercial vehicle segments where cost sensitivity limits electronic adoption.
EPA fuel economy regulations and NHTSA safety standards shape US product specifications by mandating efficiency benchmarks that lock-up clutch engagement strategies must optimize. China MIIT enforces dual carbon targets through GB standards that tighten permissible fuel consumption across vehicle classes, directly influencing torque converter stall speed and K-factor calibration requirements. EMA and EU Green Deal frameworks in Europe accelerate electrified transmission adoption, creating compliance pathways for suppliers integrating torque converters with hybrid motor-generator units. Stakeholders must monitor regulatory divergence across these jurisdictions to determine where platform standardization yields cost advantages versus where localized engineering investments protect market access.
Market Dynamics
Lock-up clutch calibration strategies are compressing development cycles as EPA and China MIIT fuel economy mandates force simultaneous optimization of highway efficiency and launch performance across hybrid architectures.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Stringent efficiency benchmarks compel OEMs to specify multi-plate lock-up clutches with expanded engagement maps, directly expanding converter complexity and value content per unit.
- Hybrid powertrain integration:Motor-generator packaging adjacent to torque converter housings creates demand for compact, high-stall designs that manage thermal loads from combined ICE-electric operation.
- China MIIT dual carbon goals:GB standards tightening permissible fuel consumption across NEDC test cycles force recalibration of K-factor curves, driving replacement demand for next-generation stator geometries.
Market Restraints
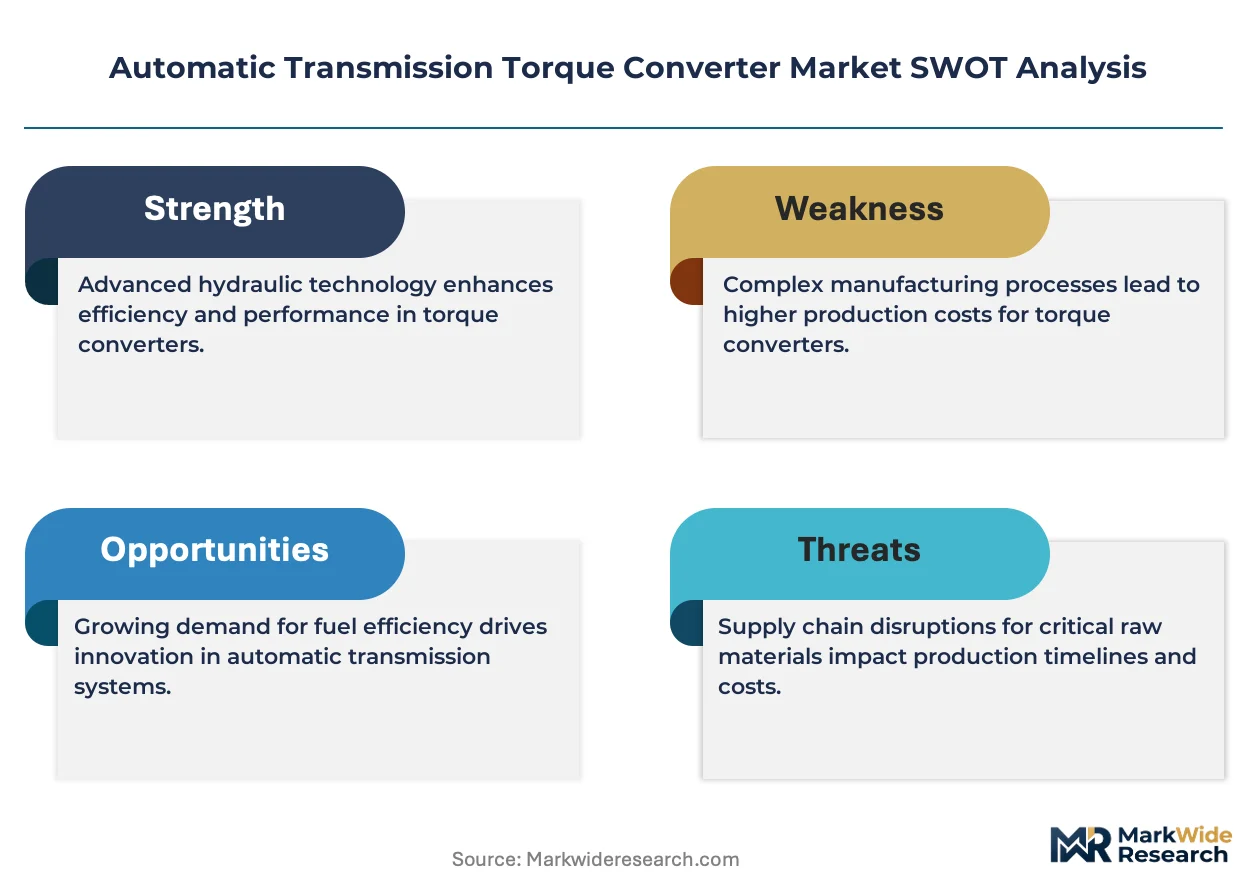
- Precision steel stamping capacity concentration:Captive foundry operations at Aisin Corporation and ZF Friedrichshafen AG limit independent supplier access to thin-gauge high-strength steel laminations critical for impeller turbine efficiency.
- Electronically controlled lock-up clutch cost premium:Solenoid valve bodies, position sensors, and adaptive control modules add material cost that excludes penetration in emerging-market commercial vehicle segments where mechanical hydraulic controls dominate.
- Electrified transmission substitution:Dedicated hybrid transmissions with disconnect clutches and multi-speed e-axles reduce torque converter relevance in full-hybrid architectures, compressing addressable volume in electrified vehicle classes.
Strategic Opportunities
- India BIS fuel efficiency labeling:Mandatory disclosure of fuel consumption ratings across vehicle classes creates competitive pressure for lock-up adoption in domestic passenger vehicles previously specified with open converters.
- Remanufacturing program expansion:OEM-captive refurbishment networks capture lifecycle value through core return incentives, creating aftermarket revenue streams insulated from price competition with independent rebuilders.
- Mechatronic-hydraulic convergence:Integration of clutch actuation with real-time adaptive algorithms enables tiered performance calibration that commands premium positioning in luxury and performance vehicle segments.
Industry Challenges
- Multi-physics simulation expertise scarcity:Coupled fluid-structure-thermal modeling for converter stall behavior requires specialized CAE competencies that transmission suppliers struggle to staff at scale.
- Hybrid thermal management integration:Motor-generator heat rejection into converter housing coolant circuits demands revised sealing and bearing specifications that extend validation timelines by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Transmission Torque Converter Market |
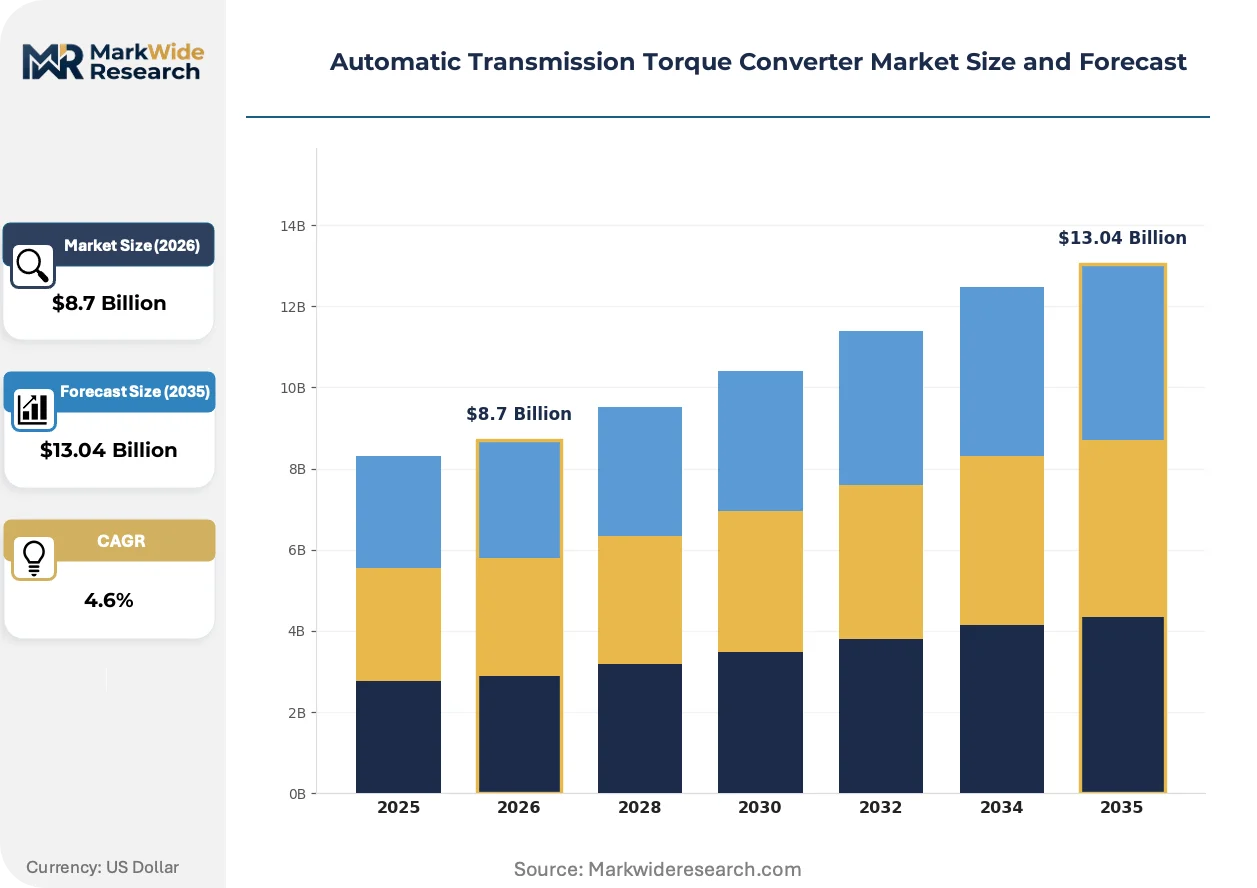
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Lock-up, CVT, Dual Clutch Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Off-Road Vehicles End User: OEMs, Aftermarket Providers, Fleet Operators, Rental Services Technology: Hydraulic, Electronic, Mechanical, Integrated Systems |
| Companies Covered | ZF Friedrichshafen AG, Aisin Corporation, BorgWarner Inc., Schaeffler AG, Valeo SA, Allison Transmission Holdings, EXEDY Corporation, Continental AG, JATCO Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Transmission Torque Converter Market Trends and Innovations
Fluid coupling architectures are undergoing forced convergence with electrified drivetrains, compressing the traditional boundary between mechanical torque multiplication and electronic power modulation.
Multi-plate lock-up clutch technology is hybridizing torque converter function with discrete mechanical connection. The design embeds friction plates within the turbine hub to enable rigid engine-transmission coupling above calibrated speed thresholds. Full-hybrid and PHEV powertrains are adopting this configuration at accelerated rates to eliminate slip losses during electric-only cruising. The technology is hybridizing the historical trade-off between launch comfort and highway efficiency into a single controllable subsystem.
China MIIT enforcement of dual carbon targets through progressively tightened GB standards is reshaping calibration priorities. The regulation mandates fleet-average fuel consumption reductions that force OEMs to specify lower stall speeds and earlier lock-up engagement. Passenger vehicle segments above 2.0L displacement face the steepest compliance penalties, driving demand for electronically modulated clutch strategies that optimize across urban and highway duty cycles simultaneously.
Buyer concentration among transmission system integrators is consolidating procurement leverage. Tier 1 suppliers now specify converter subassemblies as complete mechatronic modules rather than discrete hydraulic components, displacing independent converter specialists from direct OEM relationships. This pattern is most visible in Germany and the United States, where ZF and BorgWarner captive converter operations absorb volume previously available to merchant suppliers.
Automatic Transmission Torque Converter Market Segmentation
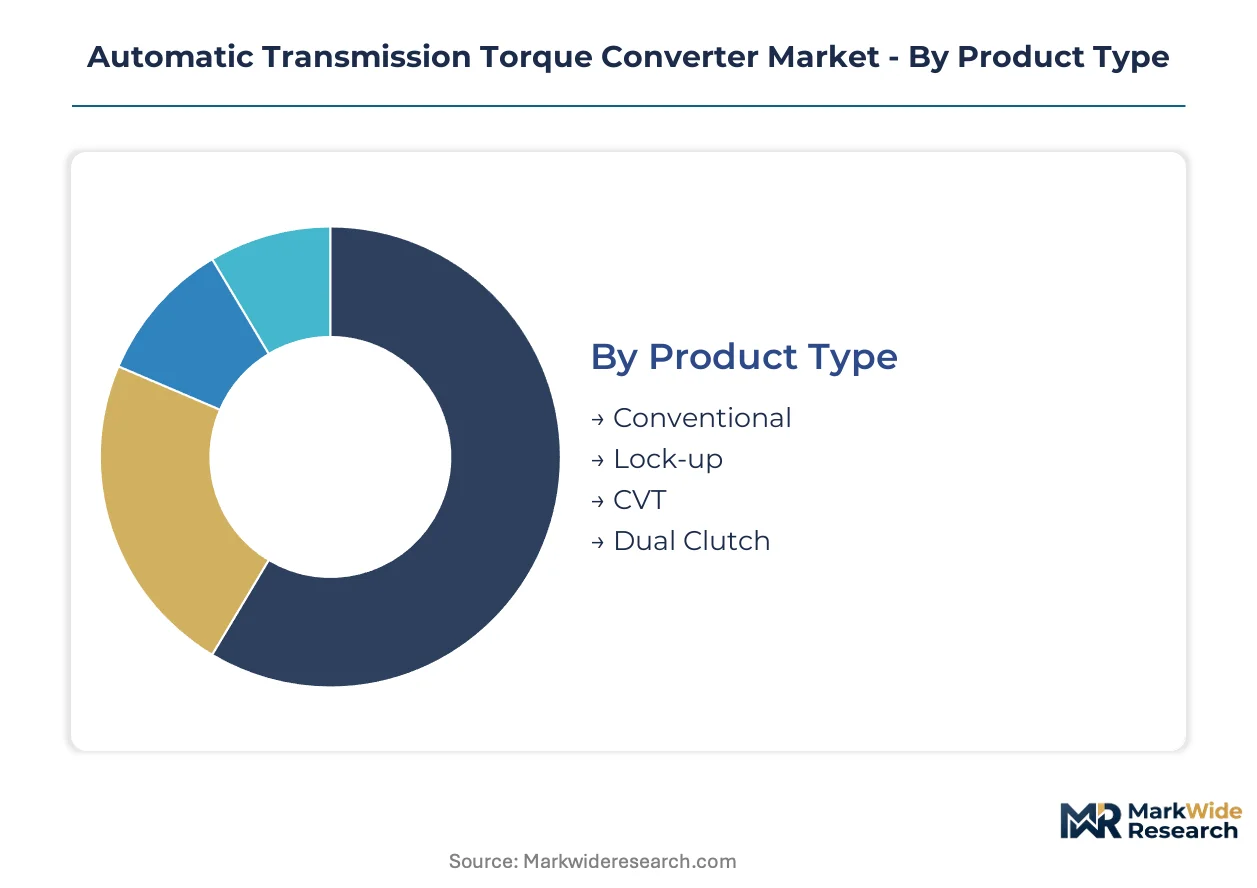
Segmentation in the automatic transmission torque converter market reveals divergent replacement cycles and value capture patterns across product architectures and customer channels. Understanding these temporal dynamics helps suppliers align inventory positioning with demand velocity and margin durability.
Product Type:
Lock-up torque converters turn over fastest as EPA and China MIIT regulations force model-year recalibrations, while conventional hydraulic designs persist longest in cost-sensitive fleet applications.
- Lock-up:Multi-plate clutch assemblies enable rigid engine-transmission coupling above calibrated speed thresholds. Passenger hybrid powertrains in the United States and China specify these designs to eliminate slip losses during electric-only cruising, compressing development cycles to 18-24 months.
- Conventional:Open fluid coupling without mechanical lock-up retains dominance in emerging-market commercial vehicles where mechanical simplicity outweighs highway efficiency penalties. Fleet operators in India and Brazil specify these units for their lower upfront acquisition cost and field-serviceability.
- CVT:Belt-pulley transmissions with integrated torque dampers serve compact passenger vehicles requiring seamless ratio variation.
- Dual Clutch:Wet-clutch architectures displace torque converters entirely in performance-oriented European passenger segments.
Conventional designs anchor the volume base while lock-up configurations gain share at the steepest rate.
Application:
Passenger vehicles concentrate the highest absolute unit volumes, though heavy-duty trucks generate superior per-unit value through larger diameters and reinforced stator assemblies.
- Passenger Vehicles:Units measuring 240-350 mm in diameter transmit engine torque through three-element fluid coupling architectures. United States and German OEM procurement emphasizes integrated electronic-hydraulic modules for adaptive lock-up control across urban-highway duty cycles.
- Heavy-Duty Trucks:Torque converters exceeding 400 mm diameter manage thermal loads from sustained high-torque operation. North American long-haul specifications demand reinforced turbine hubs and enhanced bearing packages for million-mile durability targets.
- Commercial Vehicles:Light and medium-duty trucks balance payload capacity with fuel efficiency across mixed urban delivery routes.
- Off-Road Vehicles:Mining and construction equipment requires stall-torque multiplication for loaded starts on steep grades.
Passenger vehicles anchor the volume base while heavy-duty truck applications command the highest per-unit value expansion.
End User:
OEM procurement exhibits the longest design-in cycles but secures multi-year volume commitments, whereas aftermarket channels turn inventory faster with less predictable demand patterns.
- OEMs:Transmission system integrators specify complete mechatronic modules rather than discrete hydraulic components. ZF Friedrichshafen AG and Aisin Corporation captive converter operations absorb volume previously available to merchant suppliers in Germany and Japan.
- Aftermarket Providers:Independent rebuilders compete against OEM-captive remanufacturing programs with core return incentives. United States distributors face margin compression as original equipment producers extend lifecycle value control.
- Fleet Operators:Commercial vehicle aggregators prioritize total cost of ownership over upfront acquisition expense.
- Rental Services:Turnover-sensitive vehicle lessors specify refurbished units for secondary market placement.
OEM channels anchor the volume base while aftermarket providers expand most quickly through remanufacturing program proliferation.
Technology:
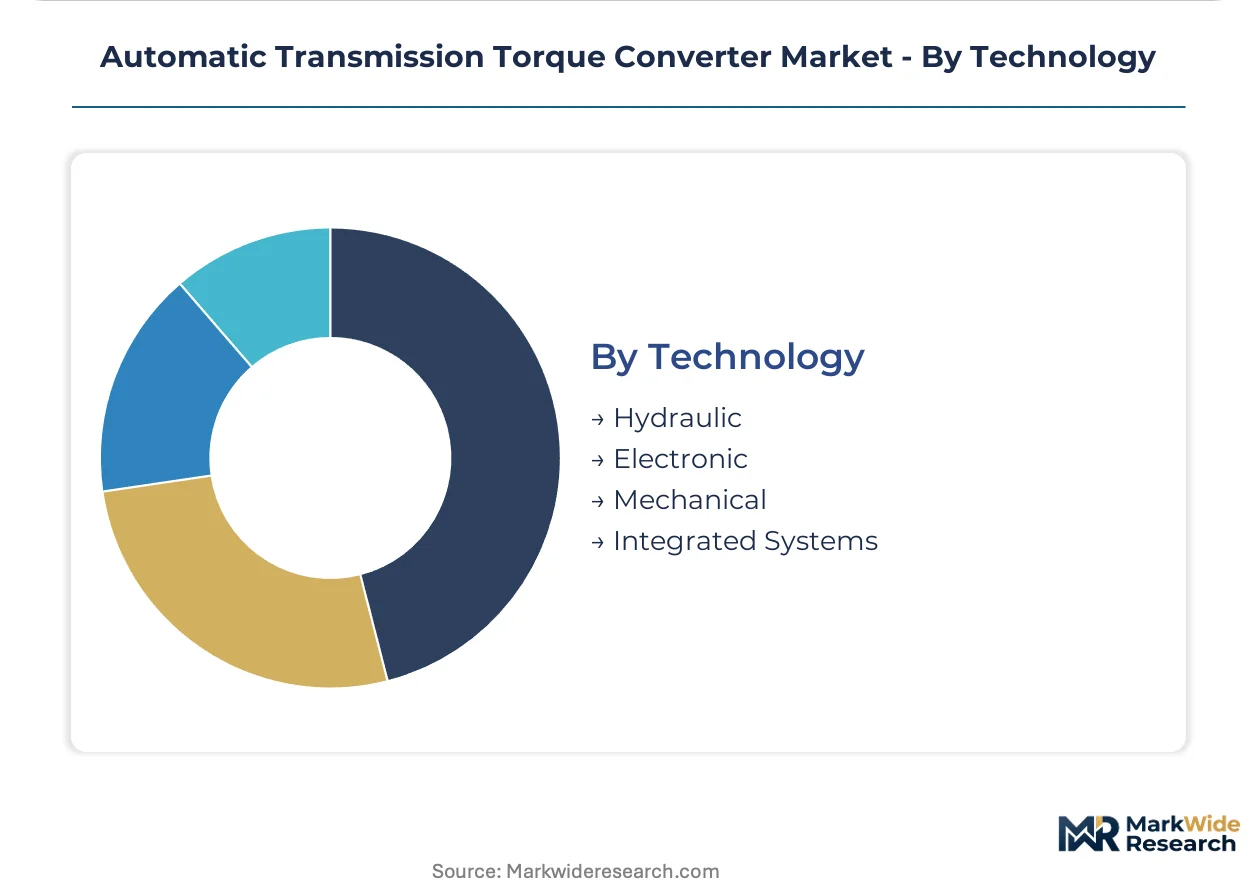
Hydraulic architectures retain the longest production runs due to mechanical simplicity, while electronic systems command premium positioning through real-time adaptive calibration capabilities.
- Electronic:Solenoid valve bodies, position sensors, and adaptive control modules enable clutch engagement optimization across varying load conditions. Luxury and performance segments in Germany and the United States specify these systems for tiered performance calibration.
- Integrated Systems:Convergence of clutch actuation with motor-generator thermal management serves hybrid powertrain packaging requirements. China MIIT dual carbon compliance drives specification for compact housings managing combined ICE-electric heat rejection.
- Hydraulic:Mechanical pressure modulation persists in emerging-market segments where electronic cost premiums exclude adoption.
- Mechanical:Fixed-geometry stators without electronic modulation serve basic torque multiplication functions.
Hydraulic technology anchors the volume base while integrated systems climb the fastest on hybrid powertrain penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb premium electronic-hydraulic systems without price elasticity, while procurement in India and Brazil remains acutely sensitive to upfront cost differentials between conventional and lock-up architectures.
United States
Long-haul trucking fleets and domestic OEMs drive demand for reinforced turbine hubs and million-mile durability packages. EPA Corporate Average Fuel Economy standards mandate multi-plate lock-up engagement maps that expand converter complexity. Detroit-Warren transmission manufacturing clusters absorb volume from adjacent vehicle assembly plants serving North American markets.
Germany
Luxury passenger vehicle producers and performance marques specify integrated mechatronic modules with real-time adaptive calibration. EU Green Deal frameworks accelerate electrified transmission adoption, creating compliance pathways for hybrid motor-generator integration. Stuttgart and Munich engineering centers concentrate development resources for next-generation stator geometries.
China
Domestic OEM procurement of compact high-stall designs surges as hybrid powertrain penetration accelerates. MIIT dual carbon enforcement through progressively tightened GB standards forces recalibration of K-factor curves for fleet-average compliance. Shanghai and Yangtze River Delta transmission manufacturing hubs serve adjacent vehicle assembly operations.
India
Cost-sensitive commercial vehicle operators and entry-level passenger segments sustain demand for conventional hydraulic designs with mechanical simplicity. BIS fuel efficiency labeling mandates create competitive pressure for lock-up adoption in domestic vehicles previously specified with open converters. Pune and Chennai automotive corridors concentrate transmission component sourcing for subcontinent assembly networks.
Japan
Precision stamping and captive foundry operations anchor supply security for thin-gauge high-strength steel laminations. METI industrial policy supports hybrid powertrain component localization requirements. Aichi Prefecture manufacturing complexes integrate converter production with adjacent transmission system assembly.
Automatic Transmission Torque Converter Market Competitive Landscape
Vertically integrated transmission system integrators and specialized hydraulic component fabricators split the market into distinct capability tiers. Consolidation around captive converter operations limits independent supplier access to direct OEM relationships. Three archetypes dominate: integrated transmission-converter architects, precision metalworking specialists, and electronic-hydraulic module integrators. Capacity expansion in Asian manufacturing corridors and strategic partnerships for hybrid thermal management define current competitive maneuvering.
Within the integrated architect tier, ZF Friedrichshafen AG and Aisin Corporation occupy positions where transmission-torque converter bundling secures multi-year OEM commitments. BorgWarner Inc. exemplifies the electronic integration archetype, embedding control systems into broader mechatronic offerings. Schaeffler AG and Valeo SA sit within the precision component specialist category, supplying friction materials and actuation hardware to system integrators.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Aisin Corporation |
| BorgWarner Inc. |
| Schaeffler AG |
| Valeo SA |
| Allison Transmission Holdings |
| EXEDY Corporation |
| Continental AG |
| JATCO Ltd. |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta port congestion transmits cost volatility through thin-gauge high-strength steel laminations, compressing margins for independent stampers while amplifying pricing power for Aisin Corporation and ZF Friedrichshafen AG with captive foundry operations. This logistics chokepoint forces downstream differentiation between electronic-hydraulic modules commanding premium positioning and conventional hydraulic units serving cost-sensitive fleet operators.
Pricing Analysis
Aftermarket refurbishment revenue streams anchor lifetime value capture as OEM-captive remanufacturing programs with core return incentives displace independent rebuilders. Three-tier pricing structure across premium electronic-hydraulic, standard lock-up, and economy conventional designs reflects certification grade and after-sales bundling intensity. Pricing pressure stems from motor-generator thermal management integration costs extending validation timelines. Fleet operators in India and Brazil exhibit highest price sensitivity, while German luxury OEMs absorb electronic premiums without elasticity.
Supply Chain Analysis
Extended payment terms from transmission system integrators strain working capital for precision stamping specialists serving as tier-two suppliers. Manufacturing concentrates in Germany, China, and Japan where Aichi Prefecture complexes integrate converter production with adjacent transmission assembly. Supply chains draw from thin-gauge high-strength steel, friction plate substrates, and solenoid valve bodies. Single-source vulnerability concentrates in captive foundry operations limiting independent access to critical laminations. Distribution runs through OEM-direct channels and aftermarket remanufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lock-up torque converter penetration sits at early-cycle expansion as EPA and China MIIT fuel economy mandates force recalibration across hybrid architectures previously specified with open converters.
For Market Incumbents: Build captive remanufacturing moats through core return incentives and lifecycle value control that insulate aftermarket revenue from independent rebuilder competition. Deepen backward integration into thin-gauge high-strength steel stamping to secure supply security against Aisin Corporation and ZF Friedrichshafen AG foundry dominance. Address electrified transmission substitution threat by embedding converter thermal management into motor-generator packaging for hybrid powertrain retention. For New Entrants and Emerging Players: Pursue India BIS fuel efficiency labeling compliance as a wedge for lock-up adoption in domestic passenger vehicles previously specified with conventional open converters. Target commercial vehicle aftermarket channels where OEM-captive programs remain underdeveloped and field-serviceability demands favor mechanical hydraulic designs. Anchor go-to-market strategy through fleet operator direct relationships emphasizing total cost of ownership over upfront acquisition cost. For Investors and Strategic Acquirers: Carve-out targets emerge from transmission system integrators divesting non-core hydraulic component operations to focus on software-defined vehicle investments. Long-term viability hinges on hybrid powertrain component localization requirements under METI industrial policy and China MIIT dual carbon enforcement. Monitor K-factor recalibration cycle frequency as inflection indicator for replacement demand velocity in stator geometry upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Thermal Management Integration | Combines motor-generator heat rejection with converter housing coolant circuits under China MIIT dual carbon compliance pathways. |
| Captive Foundry Capacity Expansion | Secures thin-gauge high-strength steel laminations for impeller turbine efficiency against Aisin Corporation supply dominance. |
| OEM-Captive Remanufacturing Network | Captures lifecycle value through core return incentives that displace independent aftermarket rebuilders in United States distribution. |
| Electronic-Hydraulic Module Convergence | Embeds solenoid valve bodies and adaptive algorithms for real-time lock-up clutch calibration in German luxury segments. |
| India BIS Compliance Positioning | Enables lock-up specification in domestic passenger vehicles responding to mandatory fuel consumption disclosure requirements. |
Research Methodology
Desk research of SEC 10-K filings, EPA regulatory dockets, and MIIT GB standard publications preceded structured interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and captive remanufacturing program directors. Primary fieldwork combined with secondary validation from vehicle production databases and customs trade records. Bottom-up unit economics triangulated against top-down transmission production forecasts.
Assumptions held fixed include EPA Corporate Average Fuel Economy standard stringency and China MIIT dual carbon enforcement timelines, while hybrid powertrain penetration rates and motor-generator thermal load specifications varied across sensitivity scenarios. Segmentation dimensions modeled encompass product architecture, vehicle class, propulsion system type, and regional manufacturing cluster. CAGRs derived from regression analysis of historical transmission production against torque converter content per vehicle trajectories.
Sensitivities concentrate around electrified transmission substitution rates and precision steel stamping capacity expansion timelines. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and hybrid architecture retention of torque converter functionality. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Drivetrain Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Automotive Carburetor Market
Powertrain
Global Automotive Torque Converter Market
Powertrain
North America Automotive Engine Oils Market
Powertrain
Global Automotive Fuel Delivery and Injection Systems Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Turbine Housing for Automobile Market
Powertrain
Transmission Control System Market
Powertrain
Automotive Half Shaft Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
Drive Shaft Market
Powertrain
Turbocharger Actuators Market
Powertrain
India Automotive Engine Oils Market
Powertrain
United States Electro Hydraulic Power Steering Market