
 Global Automotive Engine Valves Market | 2026-2036
Global Automotive Engine Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Engine Valves Market Analysis
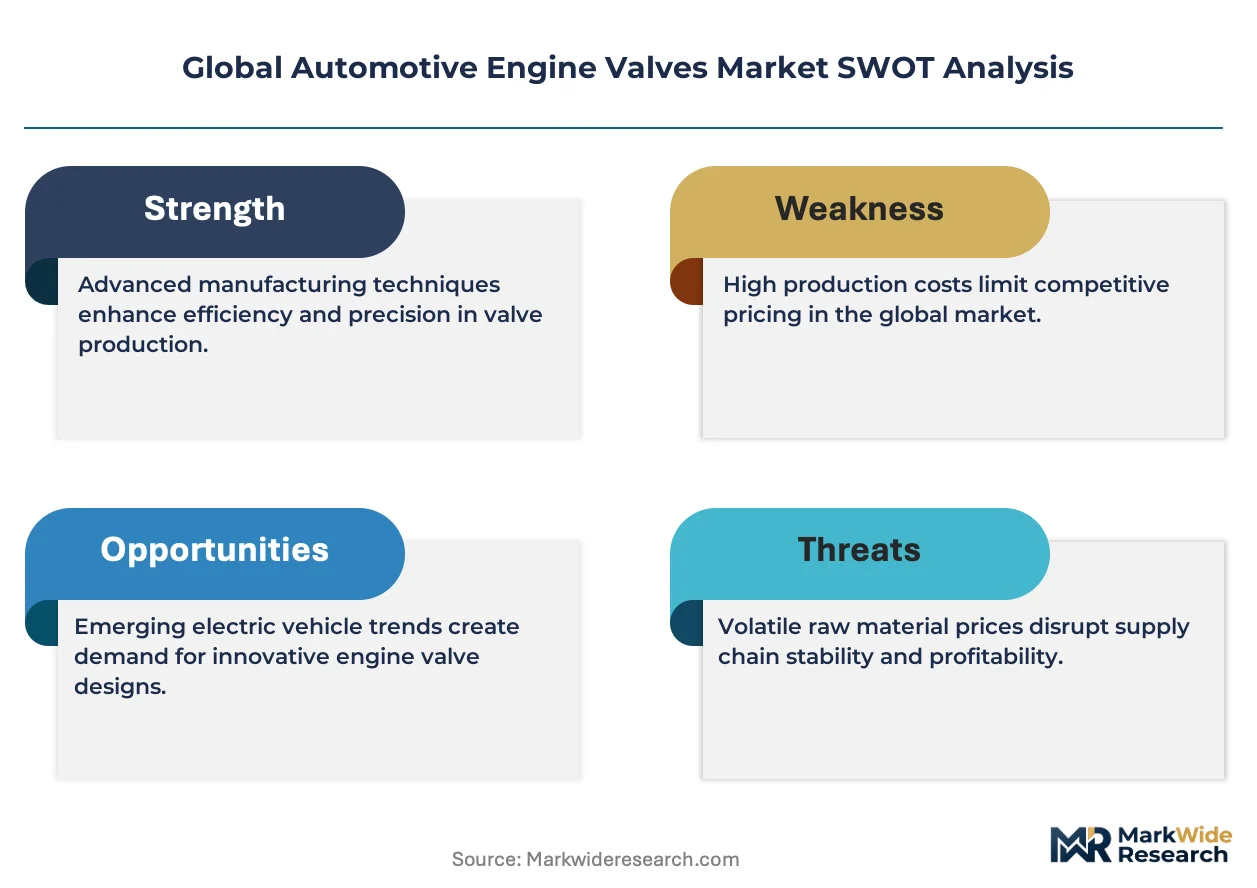
Hollow stem specification upgrades across passenger car and light truck platforms is rotating procurement priorities toward weight-reduction engineering. MAHLE GmbH leverages captive forging capacity in Europe and Asia to sustain margin control on high-performance valve trains. BorgWarner Inc anchors its position through integrated camshaft-actuator systems that bundle valve timing with lift control. Denso Corporation differentiates via precision machining tolerances for direct-injection cylinder heads.
Automotive engine valves are mechanical devices that seal combustion chambers and regulate gas exchange cycles in reciprocating internal combustion engines, typically manufactured from heat-resistant austenitic steels or titanium alloys via precision forging, stem grinding, and seat hardening to withstand cyclic temperatures exceeding 700°C and pressures above 150 bar. Their primary commercial purpose is to enable controlled intake of air-fuel mixtures and exhaust evacuation while maintaining compression integrity across millions of operating cycles. Intake valves in titanium alloys represent the fastest-growing material-product intersection as OEMs pursue thermal efficiency gains, while exhaust valve assemblies for commercial vehicles retain the largest absolute volume pool due to replacement frequency in heavy-duty cycles. Steel alloys across all product categories constitute the mature cost-optimized baseline where margin compression is most acute.
The US EPA and NHTSA coordinate corporate average fuel economy standards that tighten combustion efficiency requirements and indirectly mandate valve train precision upgrades, while the EU Green Deal and forthcoming Euro 7 limits on particulate and NOx emissions force redesigns of valve seat profiles and materials to reduce blow-by and oil consumption. China's MIIT enforces dual carbon goals that push domestic automakers toward lighter valve trains in downsized turbocharged engines. Stakeholders must monitor divergence between EPA and Euro 7 certification timelines to avoid stranded engineering investments in valve platforms that fail cross-border harmonization.
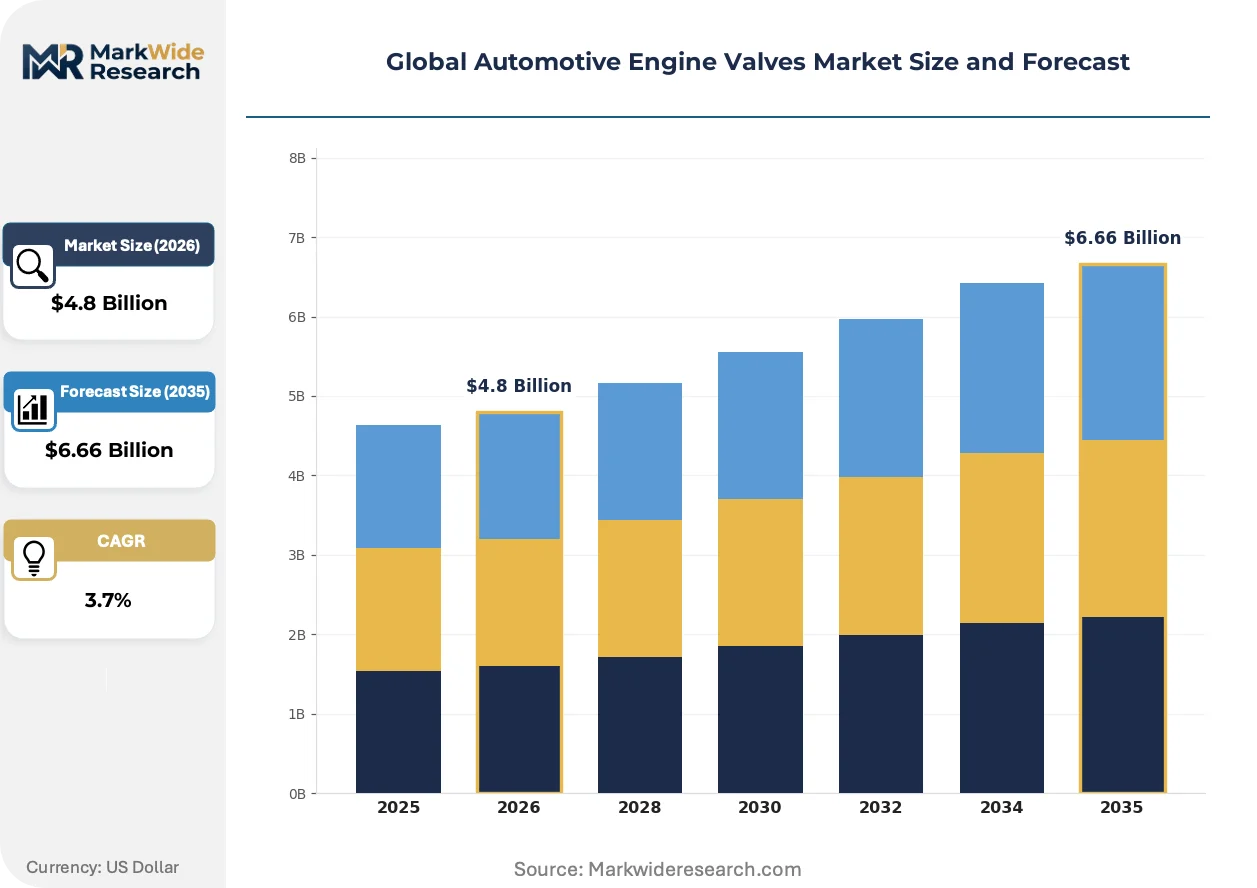
Market Dynamics
Downsized turbocharged engines are forcing valve train architectures toward hollow stem and sodium-filled designs that withstand higher thermal loads while reducing reciprocating mass. This engineering pivot concentrates procurement power among forgers capable of precision stem grinding and seat hardening at scale.
Growth Catalysts
- Euro 7 Pre-Compliance:European OEMs are redesigning valve seat profiles and materials to reduce blow-by and oil consumption ahead of 2025 implementation timelines.
- China's Dual Carbon Goals:MIIT mandates push domestic automakers toward lighter valve trains in downsized turbocharged engines, accelerating titanium alloy intake valve adoption.
- Southeast Asia Fleet Expansion:Light commercial vehicle operators in Indonesia, Thailand, and Vietnam are compressing replacement intervals for exhaust valve assemblies in high-duty cycles.
Market Restraints
- Raw Material Volatility:Nickel and cobalt price swings in heat-resistant austenitic steels compress margin predictability for precision forging operations.
- Forging Capacity Concentration:Captive forging assets cluster in Germany, Japan, and select Chinese provinces, creating geographic supply risk for non-integrated valve specialists.
- Thermal Barrier Limits:Existing seat hardening techniques face hard ceilings above 750°C in next-generation lean-burn architectures.
Strategic Opportunities
- India Manufacturing Belt:Two-wheeler and compact car production clusters around Chennai and Pune lack localized high-performance valve forging capacity.
- Direct-Injection Convergence:Precision machining tolerances for gasoline direct-injection cylinder heads create demand for integrated valve-actuator systems.
- US IRA Industrial Policy:Domestic content incentives for automotive component manufacturing could reshore valve train assembly operations.
Industry Challenges
- Cross-Border Certification Divergence:Misaligned EPA and Euro 7 compliance timelines risk stranded engineering investments in valve platforms that fail harmonization.
- Precision Grinding Talent Scarcity:Stem grinding operations requiring sub-micron tolerances face shortages of specialized machinists and metrology technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Engine Valves Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exhaust Valves, Intake Valves, Overhead Valves, Engine Valves Assemblies Material: Steel, Titanium, Aluminum, Alloys Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles End User: OEMs, Aftermarket Providers, Dealerships, Repair Shops |
| Companies Covered | Denso Corporation, Fuji Oozx Inc, BorgWarner Inc, Schaeffler AG, Delphi Technologies, MAHLE GmbH, NITTAN Corporation, Aisin Corporation, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Engine Valves Market Emerging Trajectories
Titanium alloy intake valves are actively reshaping material procurement priorities as thermal efficiency targets harden. Regulatory clocks in Europe and China are compressing development cycles for emission-compliant valve seat designs. Distribution channels are fragmenting as powertrain electrification splits aftermarket demand between legacy internal combustion service and hybrid thermal management components.
Hollow stem valve architectures with internal sodium cooling channels are supplanting solid stem designs in passenger car and light truck applications. Tier 1 suppliers in Germany and Japan are adopting these specifications for 2026 model year turbocharged engines. The shift is compressing demand for conventional forged steel intake valves in displacement segments below 2.0 liters.
The EU Green Deal and forthcoming Euro 7 particulate limits are forcing redesigns of valve seat insert materials and surface treatments. OEM engineering teams are testing plasma-transferred wire arc coatings to replace traditional stellite overlays. Exhaust valve assemblies for commercial vehicles face the most stringent retesting requirements, with German and Italian powertrain divisions leading validation protocols.
Fleet operators in Southeast Asia are unbundling valve replacement from full engine overhaul contracts, creating direct procurement relationships with component manufacturers. Independent service channels in Indonesia and Thailand are capturing volume previously routed through OEM captive parts networks. This disintermediation is most visible in light commercial vehicle segments where downtime costs exceed brand loyalty premiums.
Global Automotive Engine Valves Market Segmentation
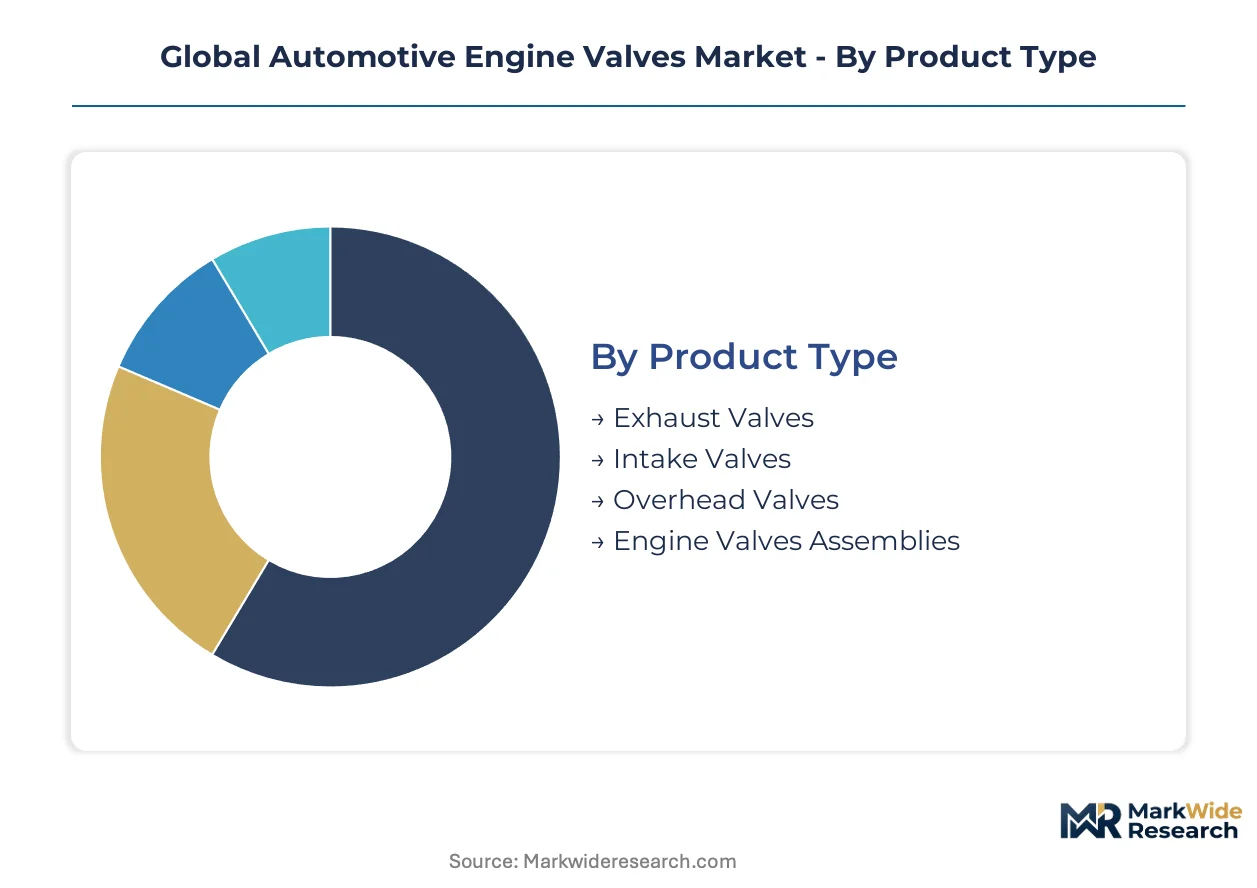
Valve procurement patterns diverge sharply across material grades and thermal duty cycles. OEMs optimize valve train architectures by matching stem geometry to engine displacement and combustion pressure regimes.
Product Type:
Margin pools concentrate in assemblies that bundle hollow stem valves with precision seat inserts and sodium cooling channels.
- Exhaust Valves:Solid or hollow stem designs forged from heat-resistant austenitic steels endure cyclic temperatures exceeding 700°C and corrosive combustion byproducts. Fleet operators in Indonesia and Thailand are compressing replacement schedules for light commercial vehicle exhaust valves as thermal loads intensify in downsized turbocharged engines.
- Intake Valves:Titanium alloy specifications dominate thermal efficiency-focused architectures due to reduced reciprocating mass and improved heat dissipation. China's MIIT mandates for lighter valve trains in downsized engines are accelerating procurement of hollow stem titanium intake valves across domestic automaker supply chains.
- Overhead Valves:Pushrod-actuated designs persist in commercial vehicle and small-displacement motorcycle engines where cost optimization outweighs DOHC complexity.
- Engine Valves Assemblies:Pre-integrated valve-spring-retainer modules reduce assembly line labor for OEMs but require precision tolerance matching.
The dominant share belongs to exhaust valves, while intake valves are closing the gap fastest.
Material:
Raw material cost volatility creates tiered margin structures across forging operations.
- Steel:Austenitic and martensitic grades remain the cost-optimized baseline for exhaust valves in heavy-duty commercial cycles. Nickel and cobalt price swings compress margin predictability for European and Japanese forgers supplying heat-resistant steel specifications.
- Titanium:Ti-6Al-4V and Ti-6242 alloys enable hollow stem architectures that reduce reciprocating mass by 40% versus steel equivalents. German and Japanese Tier 1 suppliers are locking in long-term titanium sponge contracts to secure capacity for 2026 model year turbocharged engines.
- Aluminum:Limited to low-load auxiliary valve applications where thermal exposure remains below 300°C.
- Alloys:Inconel and Nimonic superalloys address extreme thermal environments in high-performance and racing applications.
Steel commands volume leadership, though titanium alloys are expanding share most aggressively.
Vehicle Type:
Replacement frequency and specification complexity vary by duty cycle intensity.
- Passenger Cars:Hollow stem and sodium-filled valve adoption is accelerating across turbocharged gasoline and diesel platforms below 2.0 liters. Euro 7 pre-compliance efforts by German and Italian OEMs are forcing seat profile redesigns that favor precision-machined valve assemblies.
- Commercial Vehicles:Heavy-duty exhaust valves face the shortest replacement intervals due to sustained high-temperature operation. Fleet operators in Vietnam are unbundling valve procurement from full engine overhaul contracts, creating direct supplier relationships.
- Motorcycles:Two-wheeler production clusters around Chennai and Pune in India generate concentrated demand for compact valve trains in single and twin-cylinder architectures.
- Electric Vehicles:Pure battery electric platforms eliminate conventional valve trains, though range-extender and hybrid thermal engines retain intake and exhaust valve requirements.
Commercial vehicles generate the highest replacement revenue, while passenger cars are driving specification upgrades fastest.
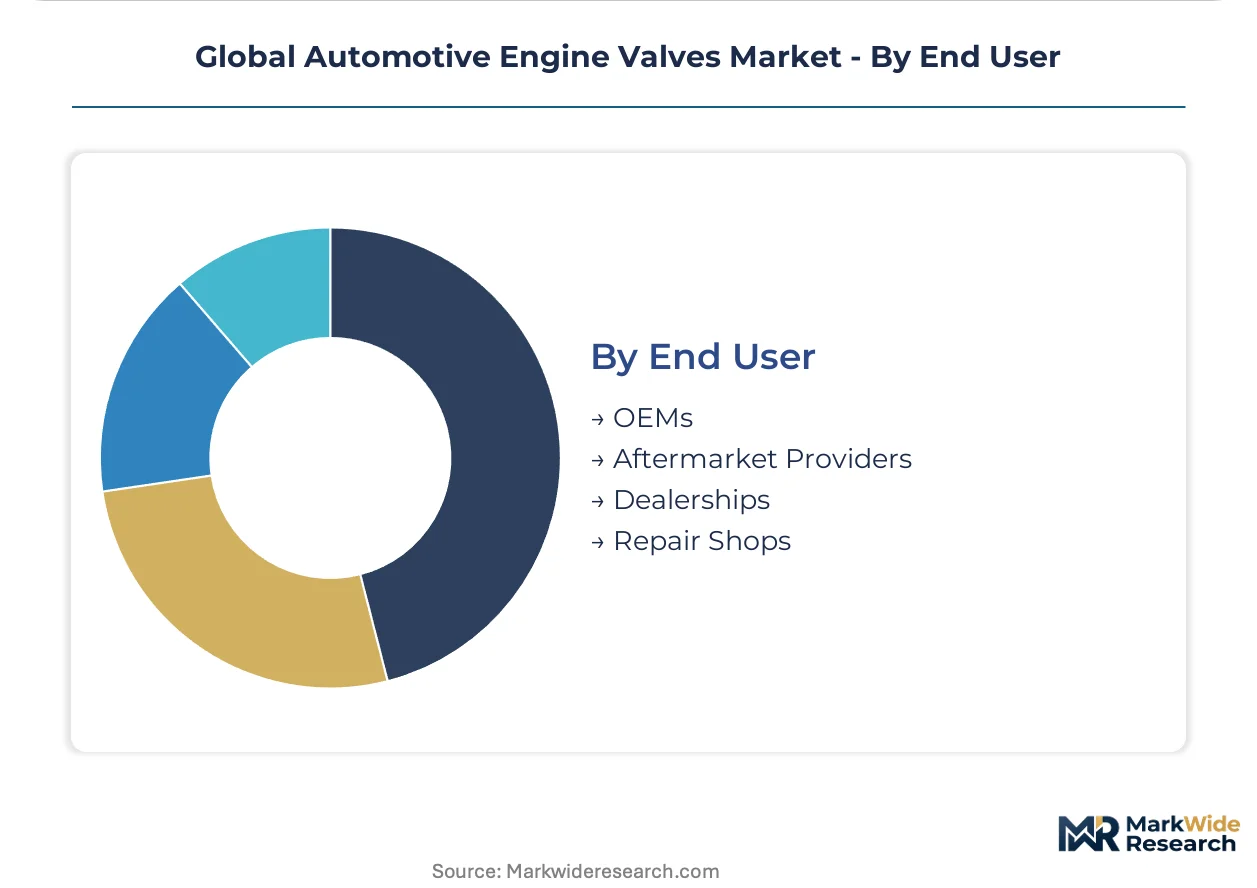
End User:
Channel power is fragmenting as fleet operators bypass traditional OEM captive networks.
- OEMs:Integrated valve train specifications are tightening tolerance requirements for direct-injection cylinder heads. BorgWarner and Denso are bundling valve timing with lift control systems to anchor OEM relationships.
- Aftermarket Providers:Independent distributors in Southeast Asia are capturing volume previously routed through OEM parts networks. Indonesian service channels now source exhaust valve assemblies directly from component forgers.
- Dealerships:Warranty service operations maintain OEM-specified valve replacement protocols but face margin pressure from independent competitors.
- Repair Shops:Small garages rely on regional distributors for standard steel valve inventory, limiting access to hollow stem and titanium specifications.
OEMs retain specification control, though aftermarket providers are gaining procurement volume most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive forging assets cluster most densely in Germany, Japan, and select Chinese provinces, creating geographic supply risk for valve specialists lacking integrated production. Demand dispersion across manufacturing belts in India, Southeast Asia, and North America is reshaping procurement routing.
China
MIIT dual carbon mandates accelerate titanium alloy intake valve adoption across domestic automaker supply chains. Downsized turbocharged engines dominate new vehicle platforms. Manufacturing concentrates in Yangtze River Delta forging clusters serving BYD, Geely, and SAIC powertrain divisions.
Germany
Euro 7 pre-compliance forces valve seat profile redesigns at BMW, Mercedes-Benz, and Volkswagen powertrain divisions. KBA certification timelines compress development cycles. Baden-Württemberg and Bavaria host precision grinding operations supplying hollow stem specifications for 2026 model year engines.
United States
EPA-NHTSA coordinated fuel economy standards tighten combustion efficiency requirements. IRA domestic content incentives could reshore valve train assembly. Midwest manufacturing corridors in Michigan and Ohio anchor Detroit Three procurement for light truck and SUV platforms.
India
Two-wheeler and compact car production clusters around Chennai and Pune generate concentrated valve demand. BIS quality mandates tighten tolerance requirements for export-bound engines. Localized high-performance forging capacity remains underdeveloped, creating import dependency for hollow stem specifications.
Japan
METI efficiency regulations push Toyota, Honda, and Nissan toward sodium-filled exhaust valve architectures. Precision machining tolerances for direct-injection cylinder heads concentrate procurement among integrated Tier 1 suppliers. Aichi and Kanagawa prefectures host captive forging assets serving domestic and Southeast Asian export markets.
Global Automotive Engine Valves Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. German and Japanese integrated suppliers dominate hollow stem and sodium-filled specifications through captive forging capacity. Mid-scale specialists compete on steel valve volume for commercial vehicle replacement cycles. Consolidation pressure intensifies as OEMs reduce supplier counts for integrated valve-actuator systems.
Among German-based integrated suppliers, MAHLE GmbH and Schaeffler AG exemplify the precision-forging archetype with captive European and Asian production assets. BorgWarner Inc occupies a position representing the bundled-systems approach, anchoring OEM relationships through integrated camshaft-actuator offerings. Denso Corporation exemplifies the Asia-based precision machining specialist, differentiating via tolerance control for direct-injection cylinder head applications.
| Leading Market Players |
|---|
| Denso Corporation |
| Fuji Oozx Inc |
| BorgWarner Inc |
| Schaeffler AG |
| Delphi Technologies |
| MAHLE GmbH |
| NITTAN Corporation |
| Aisin Corporation |
| Eaton Corporation |
| Others |
Supply Flow & Price Mechanics
Euro 7 pre-compliance certification gates both supplier qualification and price differentiation in automotive engine valves, forcing OEMs to pay premiums for seat-hardened hollow stem specifications that satisfy KBA validation protocols while marginalizing conventional forged steel suppliers lacking plasma coating capabilities.
Pricing Analysis
Euro 7 dictates the pricing tier structure across European valve procurement, separating plasma-transferred wire arc coated assemblies from traditional stellite overlay specifications. Three-tier pricing structure across premium, standard, and economy levels reflects thermal duty ratings, with sodium-filled hollow stem designs commanding top positioning. Cost compression in steel valve tiers is intensifying because nickel and cobalt volatility erodes forging margin predictability. Fleet operators in Southeast Asia exhibit highest price sensitivity, while German OEM powertrain divisions remain least sensitive due to warranty-driven specification rigidity.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for titanium sponge shipments from Russian and Ukrainian feedstock sources, compressing just-in-time delivery windows for German and Japanese forgers. Manufacturing concentrates in Germany, Japan, and China's Yangtze River Delta provinces. Precision stem grinding equipment and heat-resistant austenitic steel billets constitute critical input dependencies. Single-source vulnerability haunts sub-micron tolerance machining capacity, with Aichi and Baden-Württemberg hosting irreplaceable specialist operations. Distribution runs through OEM captive parts networks and independent aftermarket channels in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Downsized turbocharged engine proliferation is disrupting valve train procurement, with hollow stem and sodium-filled architectures displacing solid steel designs across displacement segments below 2.0 liters.
For Market Incumbents: Fortify captive forging positions in Germany and Japan through precision grinding capacity additions that secure hollow stem qualification for 2026 model year platforms. MAHLE GmbH and Schaeffler AG must defend against titanium alloy intake valve substitution by locking long-term sponge contracts. Certification investment in KBA and MIIT dual carbon compliance represents the critical lever for margin preservation.
For New Entrants and Emerging Players: KBA fast-track certification for plasma-transferred wire arc coatings creates entry pathways for specialized seat hardening specialists. India's Chennai-Pune manufacturing belt offers the most penetrable geography, with localized hollow stem forging capacity absent despite concentrated two-wheeler demand. Direct procurement relationships with Indonesian fleet operators bypass entrenched OEM captive networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European forging specialists possessing hollow stem capabilities but lacking sodium-filled exhaust valve integration. Five-to-ten year viability hinges on Euro 7 and MIIT mandate durability rather than pure battery electric displacement. Watch titanium sponge contract tenor compression as inflection signal for supply security stress.
| Strategic Initiative | Industry Significance |
|---|---|
| Hollow Stem Capacity Expansion | Captures Euro 7 pre-compliance procurement from BMW and Volkswagen powertrain divisions. |
| Titanium Sponge Supply Agreement | Locks raw material security for Ti-6Al-4V intake valve production at Japanese Tier 1 suppliers. |
| Plasma Coating Certification | Qualifies seat hardening operations for KBA validation protocols ahead of competitor stellite overlays. |
| India Manufacturing Footprint | Addresses localized forging gap in Chennai-Pune two-wheeler and compact car production clusters. |
| Aftermarket Channel Partnership | Captures Indonesian and Thai fleet operator volume disintermediating OEM captive parts networks. |
Methodological Framework
Cross-validation between OEM platform engineer interviews and Tier 1 supplier procurement data anchors the qualitative findings in this study. Primary fieldwork engaged valve train engineering directors, forging plant managers, aftermarket distribution heads, and fleet maintenance operators across Germany, Japan, China, India, and Indonesia. Secondary sources encompassed KBA type-approval databases, MIIT vehicle fuel consumption announcements, EPA-NHTSA coordinated rulemaking dockets, and IHS Markit powertrain production forecasts. Bottom-up segment sizing triangulated against top-down macroeconomic automotive demand indicators.
Sensitivity analysis tested forecast robustness across nickel price volatility scenarios and Euro 7 implementation timing variations over the projection horizon. Segmentation dimensions modeled include valve type, material grade, vehicle class, propulsion architecture, and regional manufacturing cluster. CAGRs derived from regression analysis of historical production volumes against regulatory mandate intensity indices. Industry-specific inputs incorporated thermal efficiency target trajectories and downsized turbocharged engine penetration curves.
Decision-makers should treat outputs as directional under sustained internal combustion engine production assumptions; material deviation toward accelerated electrification would warrant model refresh. Forecasts reflect base-case regulatory implementation timelines and raw material supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Air Suspension Systems Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
Rammer Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Passenger Car Accessories Market
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
Transfer Case Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
VVT Actuators Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Egypt Automotive Engine Oils Market