
 Automotive Water Pump Market | 2026-2036
Automotive Water Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Water Pump Market Insights
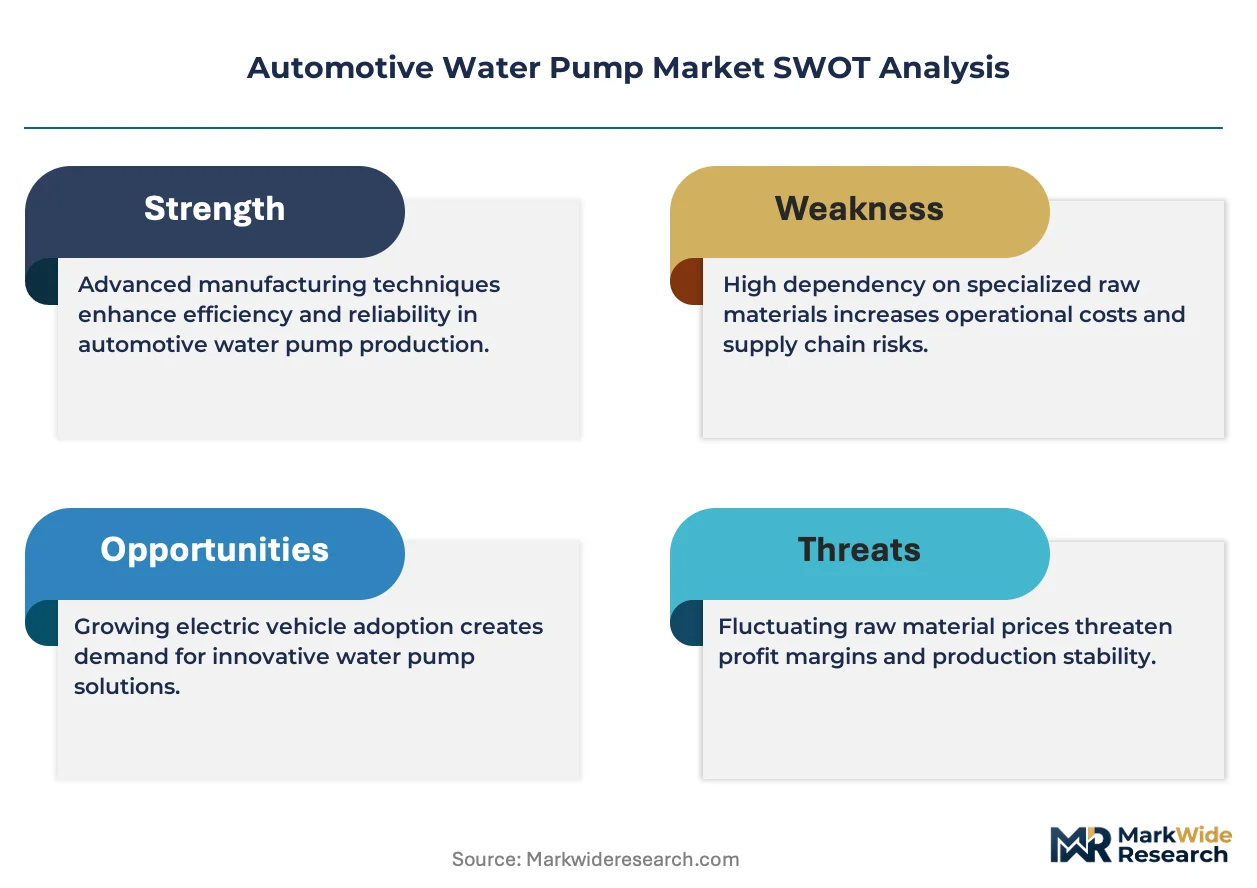
The automotive water pump supply base is restructuring around a sharp split between premium electric pump architectures and commodity mechanical replacements. Robert Bosch GmbH leverages its integrated electronics capability to dominate the high-voltage thermal management tier. Continental AG anchors its position through scalable modular platforms that span hybrid and battery-electric vehicle programs. Aisin Corporation competes on manufacturing scale, sustaining cost leadership across belt-driven and mechanical pump categories for internal combustion engine residual demand.
An automotive water pump is a fluid circulation device, typically cast from aluminum alloy or engineered polymer composite, that maintains optimal engine or battery pack operating temperature by forcing coolant through radiator, heater core, and thermal management circuit channels. Electric pumps, drawing 50-400 watts through brushless DC motors with CAN-bus control, now displace mechanical belt-driven units in electrified powertrains where precise thermal profiling protects lithium-ion cell integrity. Mechanical pumps retain volume leadership across legacy internal combustion fleets but face margin compression as OEM procurement shifts toward integrated thermal modules; the material segment shows aluminum still dominating structural housings while composite adoption advances in weight-sensitive electric vehicle platforms where pump assemblies mount directly on battery pack enclosures.
EPA tailpipe standards and the EU F-Gas Regulation are tightening coolant circuit efficiency mandates, forcing suppliers to redesign pump hydraulics for lower parasitic losses and leak-free lifespans exceeding 240,000 kilometers. China's MIIT new energy vehicle technical roadmap adds parallel pressure for localized thermal component certification. Stakeholders must monitor how OEM thermal system integration strategies reshape standalone pump procurement versus captive in-house production decisions.
Market Dynamics
The automotive water pump market is bifurcating around powertrain electrification, as electric pumps displace mechanical units in thermal management architectures while legacy internal combustion engine fleets sustain residual mechanical demand through replacement cycles.
Growth Catalysts
- EU F-Gas Regulation:Mandates on coolant circuit leak rates and lifecycle efficiency are forcing OEMs to specify sealed electric pump designs with brushless DC motor architectures.
- Powertrain electrification in passenger vehicles:Battery-electric and hybrid platforms require precise thermal profiling for lithium-ion cell integrity, creating specification pull for electronically controlled pump systems.
- China MIIT new energy vehicle roadmap:Localization requirements for thermal component certification are accelerating domestic supply base development for electric pump manufacturing.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings in Chinese processing centers compress margins on brushless DC motor subassemblies.
- Aluminum alloy supply concentration:Primary smelting capacity clusters in specific geographies expose housing foundries to energy cost spikes and export restriction risks.
- Mechanical pump substitution ceiling:Belt-driven architectures face technical limitations in variable-flow precision, capping their addressable market to legacy ICE residual demand.
Strategic Opportunities
- Commercial vehicle electrification:Heavy-duty battery-electric trucks and buses in North America and Europe represent underpenetrated demand for high-flow-rate electric thermal pumps.
- Integrated thermal module convergence:Combining pumps with heat exchangers, valves, and sensors into single subassemblies creates value-capture opportunities for system-level suppliers.
- US Inflation Reduction Act:Domestic content incentives for electric vehicle supply chains are reshaping sourcing geography for pump motor and controller manufacturing.
Industry Challenges
- Embedded software certification:Functional safety validation to ISO 26262 ASIL ratings for pump control electronics extends development timelines and requires specialized automotive firmware engineering talent.
- Thermal system integration complexity:Coordinating pump specifications with battery management systems, HVAC loops, and power electronics cooling demands cross-functional engineering alignment that strains traditional component supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Water Pump Market |
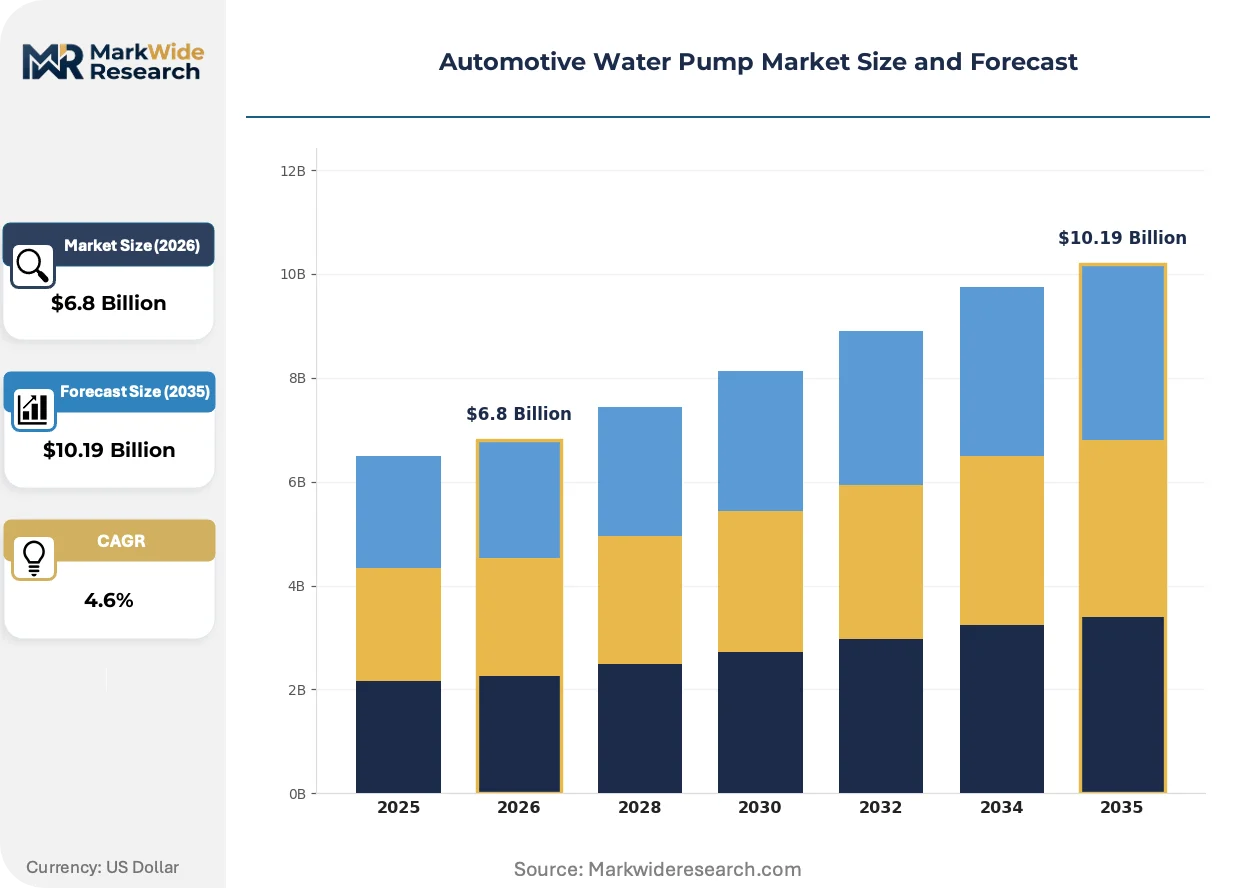
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Pumps, Electric Pumps, Belt-driven Pumps, Variable Displacement Pumps End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Material: Aluminum, Cast Iron, Plastic, Composite Installation Type: Integrated, Standalone, Removable, Fixed |
| Companies Covered | Robert Bosch GmbH, Continental AG, Schaeffler Technologies AG & Co. KG, Denso Corporation, Aisin Corporation, Gates Corporation, Valeo SA, Rheinmetall AG, Hitachi Astemo Americas, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Water Pump Market Trends and Innovations
Electrification is fragmenting the water pump value chain into distinct technology tiers, with smart thermal management systems demanding new competencies in electronics integration and predictive control algorithms.
Brushless DC pump technology with CAN-bus control interfaces is decentralizing thermal management architecture away from engine-centric mechanical drive systems. Passenger vehicle OEMs in Germany, China, and the United States are specifying these units for battery-electric platforms where precise coolant flow modulation protects cell longevity. This shift is compressing the addressable market for standalone mechanical pump suppliers while expanding specification scope for electronics-capable tier ones.
The EU F-Gas Regulation is tightening coolant circuit efficiency mandates with phased reduction targets for fluorinated greenhouse gas emissions. Suppliers must redesign pump hydraulics for parasitic loss minimization and validate leak-free performance across 240,000-kilometer service intervals. Battery-electric vehicle programs face the steepest compliance burden, as their thermal loops operate at higher pressures and broader temperature ranges than legacy ICE cooling circuits.
Aftermarket procurement for replacement pumps is consolidating around certified remanufacturing programs and direct OEM channel relationships. Independent distributors and traditional jobber networks are losing share to captive parts operations and authorized service chains, particularly for electric vehicle thermal components where warranty compliance requires traceable sourcing. This pattern is most pronounced in Germany and the United States, where fleet electrification is compressing replacement cycles and elevating technical service requirements.
Automotive Water Pump Market Segmentation
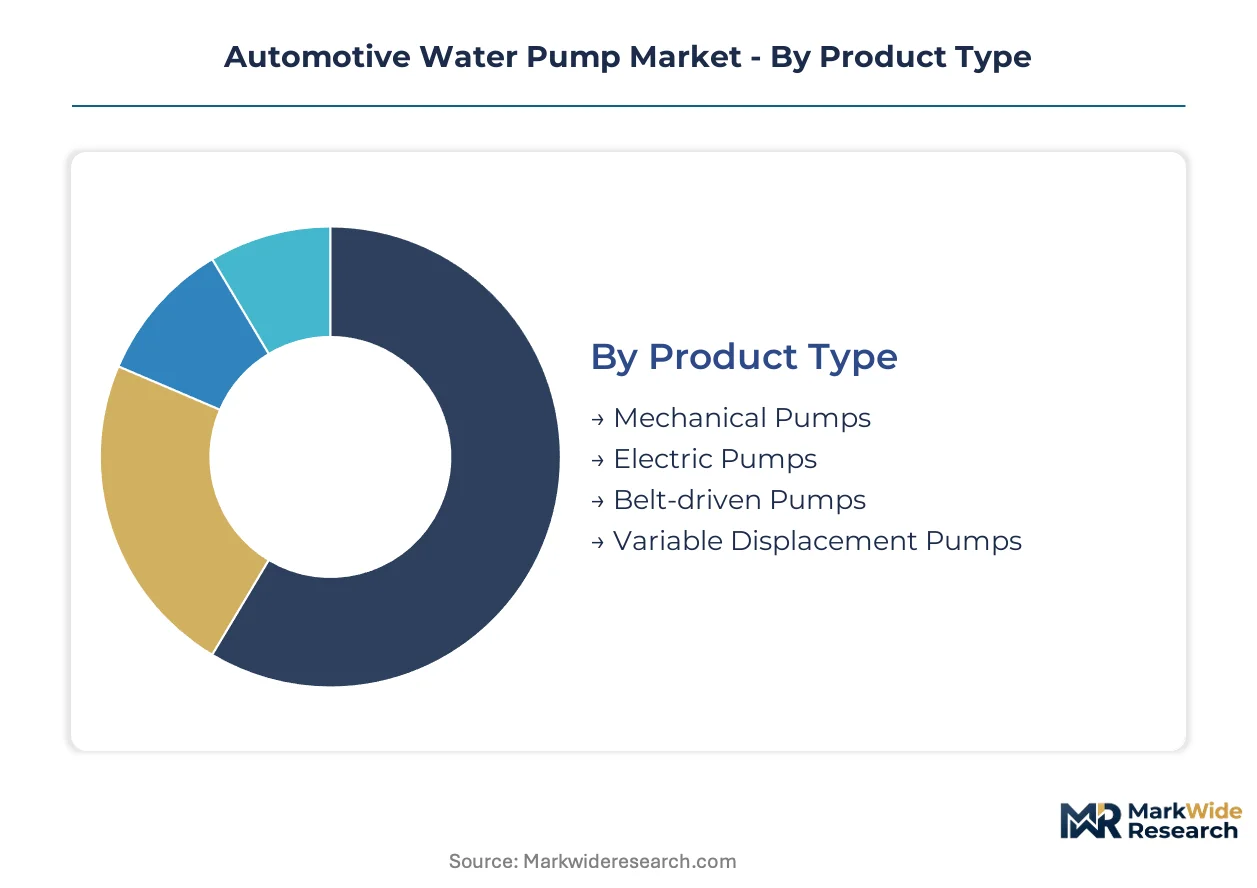
Segmentation in the automotive water pump market reveals how thermal management architectures split between legacy mechanical systems and precision electric designs. Each dimension exposes different competitive dynamics, from material substitution pressures to channel control battles between OEMs and aftermarket networks.
Product Type:
Integration depth varies sharply across pump architectures, with standalone mechanical units serving residual ICE fleets while embedded electric pumps merge into battery thermal management systems.
- Mechanical Pumps:Cast aluminum or iron housings with impeller shafts driven directly by crankshaft belts, delivering fixed coolant flow rates proportional to engine RPM. Demand concentrates in legacy internal combustion fleets across the United States and India where replacement cycles sustain volume; EPA tailpipe standards compress margins by shortening service intervals.
- Electric Pumps:Brushless DC motor assemblies with CAN-bus control interfaces enabling variable flow modulation independent of engine speed. Germany and China OEMs specify these for battery-electric platforms where precise thermal profiling protects lithium-ion cell integrity; EU F-Gas Regulation mandates sealed designs with leak-free lifespans exceeding 240,000 kilometers.
- Belt-driven Pumps:Mechanical architectures using serpentine belt systems common to hybrid powertrains requiring auxiliary cooling during electric-only operation.
- Variable Displacement Pumps:Hydraulic designs adjusting output through internal vane positioning, bridging cost and precision for mid-hybrid applications.
Mechanical pumps lead volumes today; electric pumps are gaining share fastest.
End User:
Channel structure determines pricing power, with captive OEM relationships commanding specification control while aftermarket networks compete on availability and technical service reach.
- OEMs:Direct procurement relationships with tier-one thermal system suppliers for new vehicle programs, specifying pump performance curves, interface protocols, and validation testing protocols. German and Chinese passenger vehicle manufacturers consolidate sourcing around integrated thermal module suppliers; MIIT certification requirements for new energy vehicles add localization pressure.
- Aftermarket Providers:Independent distributors and remanufacturing specialists serving replacement demand across aging vehicle populations. United States fleet electrification compresses replacement cycles as thermal components require traceable sourcing for warranty compliance; authorized service chains displace traditional jobber networks.
- Vehicle Assemblers:Contract manufacturing operations integrating pump subassemblies into complete powertrain or battery pack modules.
- Tier-1 Suppliers:Thermal system specialists sourcing standalone pumps or producing captive designs for OEM customers.
OEMs dominate value capture; aftermarket providers face margin compression from channel consolidation.
Material:
Weight and thermal conductivity requirements pull material selection in opposing directions, with aluminum retaining structural dominance while composites advance in electric vehicle platforms.
- Aluminum:Die-cast A380 or AlSi10Mg alloys dominating pump housings for structural rigidity and heat dissipation. Foundry capacity concentrates in China and Germany; energy cost spikes at primary smelters expose supply chains to margin volatility.
- Cast Iron:Gray iron grades for heavy-duty commercial vehicle pumps requiring maximum durability under thermal cycling stress.
- Plastic:Glass-reinforced nylon and PPS compounds for impellers and non-structural housings in cost-sensitive applications.
- Composite:Carbon-fiber or glass-fiber reinforced polymers enabling direct mounting on battery pack enclosures where mass reduction outweighs material cost premiums.
Aluminum leads volumes today; composite adoption is climbing the fastest in electric vehicle programs.
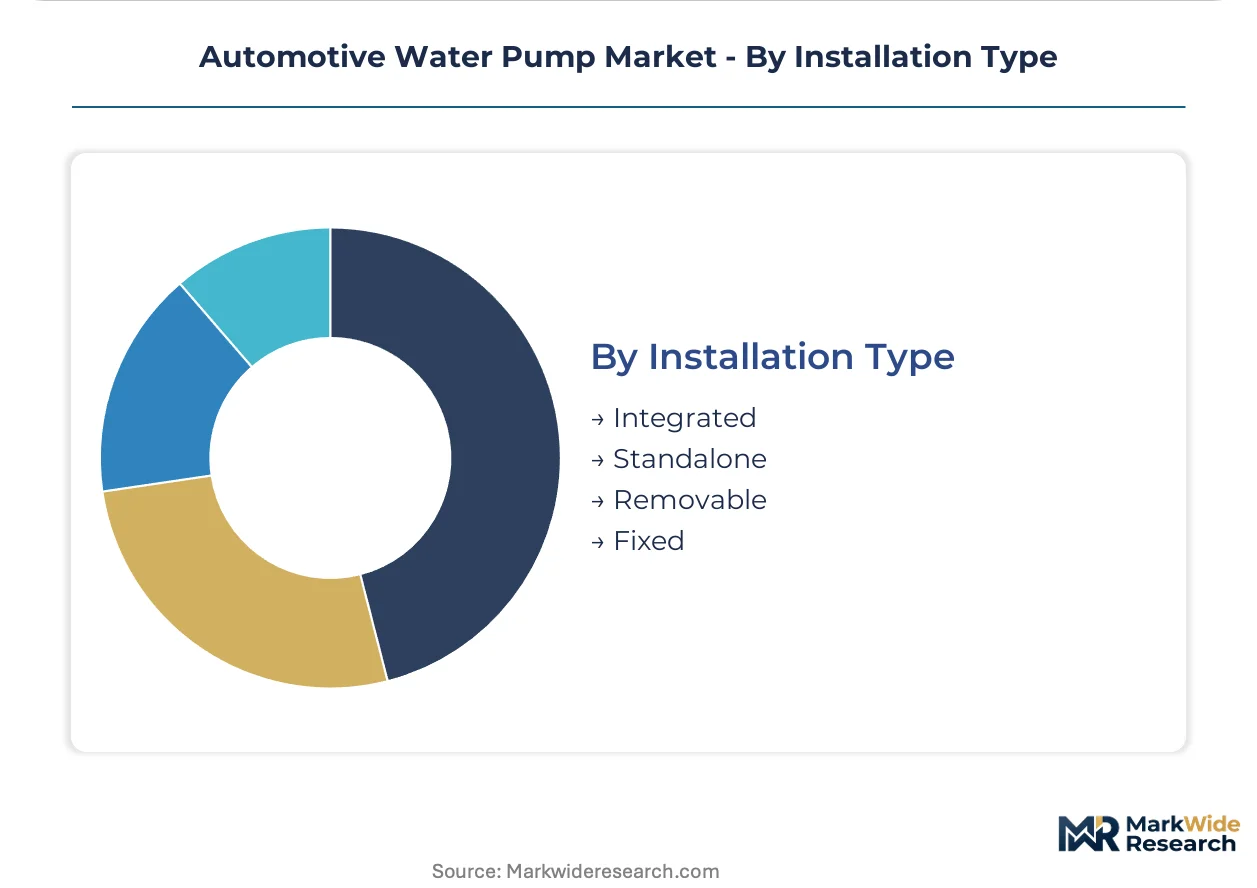
Installation Type:
Physical mounting configuration signals where value migrates in thermal system architecture, from standalone replaceable units to embedded subsystem integration.
- Integrated:Pump subassemblies permanently joined with heat exchangers, valves, and sensors into single thermal modules. OEMs in Germany and the United States specify these designs to reduce assembly complexity and leak points; system-level suppliers capture margin from combined component sourcing.
- Standalone:Discrete pump units serviceable without disturbing adjacent thermal components, preserving aftermarket replacement economics.
- Removable:Quick-connect designs enabling field service without specialized tooling, common to fleet maintenance protocols.
- Fixed:Permanent mounting configurations for sealed electric vehicle battery packs where service access is engineered out.
Standalone configurations lead replacement volumes today; integrated designs show the steepest expansion trajectory in new vehicle specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Stuttgart, Shanghai, and Detroit anchor thermal management innovation for electrified powertrains. Foundry workers in Ningxia and smelter technicians in Quebec concentrate aluminum supply for pump housings. Software engineers in Bangalore and Munich write CAN-bus control firmware for brushless DC architectures.
United States
EPA tailpipe standards and the Inflation Reduction Act drive OEM procurement toward integrated electric thermal modules. The NHTSA coordinates with EPA on vehicle efficiency mandates affecting coolant circuit design. Detroit's automotive engineering corridor concentrates tier-one supplier R&D facilities for battery-electric pump validation.
Germany
KBA certification requirements and EU F-Gas Regulation enforcement create specification pull for sealed electric pump architectures. The EU Green Deal's carbon border adjustments pressure housing foundries to source low-carbon aluminum. Stuttgart's powertrain engineering cluster hosts thermal system integration centers for premium OEM programs.
China
MIIT new energy vehicle technical roadmaps mandate localized thermal component certification for electric pump suppliers. SAMR oversees quality standards for brushless DC motor subassemblies in automotive applications. Yangtze River Delta manufacturing zones concentrate die-casting capacity for aluminum pump housings serving domestic OEMs.
Japan
METI carbon neutrality roadmaps accelerate hybrid and battery-electric vehicle thermal system development. JIS standards govern material specifications for composite pump components in weight-sensitive platforms. Nagoya's automotive supplier corridor maintains precision manufacturing expertise for variable displacement pump mechanisms.
South Korea
MFDS automotive component safety frameworks align with global thermal management certification trends. Government battery-electric vehicle subsidies expand domestic demand for precision coolant flow control systems. Seoul Capital Area engineering centers specialize in brushless DC motor controller firmware for export markets.
Automotive Water Pump Market Competitive Landscape
Top-tier vendors anchor integrated thermal module supply, while mid-scale specialists occupy standalone pump fabrication. The market structures around three tiers: electronics-capable system integrators, scale-driven mechanical pump producers, and regional foundry operations serving aftermarket channels. Strategic archetypes include integrated module suppliers capturing OEM specification control, aluminum foundries defending cost positions through energy hedging, and software-enabled pump specialists licensing CAN-bus control algorithms. Competitive moves concentrate on backward integration into rare earth magnet sourcing and captive controller semiconductor procurement.
Within the electronics-integrated tier, Robert Bosch GmbH and Continental AG exemplify system-level positioning through combined pump-controller-software architectures. Aisin Corporation occupies a scale-driven archetype spanning mechanical heritage and electric transition portfolios. These three entities represent divergent strategic postures: German engineering conglomerates leveraging automotive electronics ecosystems against Japanese manufacturing scale adapting from belt-drive legacy to brushless DC production.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Schaeffler Technologies AG & Co. KG |
| Denso Corporation |
| Aisin Corporation |
| Gates Corporation |
| Valeo SA |
| Rheinmetall AG |
| Hitachi Astemo Americas, Inc. |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation leak-rate mandates and lifecycle efficiency thresholds gate qualified supply access, restricting premium-tier electric pump procurement to suppliers with validated brushless DC architectures and ISO 26262 ASIL certification. OEMs in Germany and China pay structural premiums for sealed designs meeting 240,000-kilometer leak-free warranties, while aftermarket mechanical replacements compete on spot aluminum pricing and foundry proximity.
Pricing Analysis
Bundled thermal module contracts versus standalone pump procurement splits the pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates integrated electric systems with CAN-bus controllers from belt-driven mechanical units and commodity remanufactured replacements. Cost compression in mechanical tiers intensifies because foundry energy hedging erodes margin buffers. Fleet operators show highest price sensitivity; premium OEMs absorb certification premiums for cell-integrity protection.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and Chinese passenger vehicle manufacturers, while authorized service chains distribute replacement units under warranty compliance protocols. Aluminum smelting concentrates in China, Germany, and Quebec; rare earth magnet processing clusters in Chinese refining centers. The supply chain draws from neodymium-dysprosium alloys, A380 die-cast aluminum, and glass-reinforced polymer compounds. Single-source vulnerability in magnet supply exposes brushless DC motor subassemblies to export restriction shocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive water pump market functions as a stable compounder, with powertrain electrification programs in passenger vehicles driving replacement cycle compression and specification upgrades across OEM thermal portfolios.
For Market Incumbents: Anchor module integration capabilities by acquiring controller firmware specialists in Seoul or Munich, then deepen backward integration into rare earth magnet sourcing to offset Chinese processing volatility. Defend against mechanical pump margin erosion by converting foundry capacity to composite housing production for battery-electric platforms. For New Entrants and Emerging Players: The Inflation Reduction Act in the United States opens a window for domestic electric pump motor manufacturing serving Detroit-area OEMs. Target heavy-duty commercial vehicle electrification in North America as the most penetrable white space, then enter through remanufacturing partnerships with fleet maintenance networks seeking traceable thermal component sourcing. For Investors and Strategic Acquirers: Roll-up economics work for regional foundry operations with energy hedging infrastructure because aluminum supply concentration creates captive margin capture for integrated thermal module suppliers. Five-to-ten-year viability hinges on electric vehicle production ramp rates. Watch MIIT localization enforcement intensity as the inflection signal for Chinese supply base restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Scalable modular designs reduce OEM validation cycles across hybrid and battery-electric programs. |
| Battery Supply Agreement | Long-term cell contracts secure thermal management specification pull from lithium-ion pack integrators. |
| Software-Defined Vehicle Investment | CAN-bus control algorithms enable predictive coolant flow modulation for cell longevity optimization. |
| Geographic Manufacturing Footprint | Yangtze River Delta foundries serve MIIT localization mandates for Chinese OEM procurement. |
| Charging Infrastructure Partnership | Fast-charging thermal load profiles drive high-flow-rate electric pump demand in commercial fleets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, foundry operations managers, and thermal system integration specialists. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA tailpipe standard filings, and EU F-Gas Regulation implementation reports. Bottom-up pump shipment modeling and top-down thermal system value triangulation anchored volume estimates.
Segment-weighting across propulsion architecture, vehicle class, content per vehicle, and regional production clusters shaped the analytical framework. CAGRs derived from installed base turnover rates and electrification program timelines across the projection horizon. Modeled inputs included OEM thermal module integration roadmaps, rare earth magnet price trajectories, and foundry capacity utilization by geography.
Revisions become necessary when EPA efficiency mandates accelerate, EU carbon border adjustments reshape aluminum sourcing economics, or Chinese export restrictions on processed rare earths materialize. Forecasts reflect documented assumptions on electric vehicle penetration curves and thermal system architecture consolidation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Yaw Damper Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Electrically Powered Hydraulic Steering Market
Powertrain
Global Industrial Turbocharger Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Transmission Control System Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Global Automotive Clutch Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
Carburetor Market
Powertrain
Timing Belt Kits Market
Powertrain
Automotive Fluid Reservoir Market