
 Automotive Torque Vectoring System Market | 2026-2036
Automotive Torque Vectoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Torque Vectoring System Market Analysis
Mechatronics engineering talent is bifurcating the competitive landscape between legacy drivetrain suppliers and emerging EV-native developers. GKN Automotive leverages decades of all-wheel-drive expertise to sustain its position in mechanical torque-vectoring differentials. ZF Friedrichshafen AG anchors its growth in integrated electro-hydraulic systems that serve both ICE and electric platforms. Bosch Group differentiates through its broad semiconductor and sensor portfolio that feeds electronic control architectures.
An automotive torque vectoring system modulates drive torque between individual wheels to enhance traction, stability, and cornering agility, typically operating through clutch packs, electric motors, or brake-based interventions within milliseconds. The technology serves primarily to improve vehicle dynamics safety margins and extract maximum performance from multi-motor electric drivetrains. Active Torque Vectoring commands the steepest engineering investment as automakers demand real-time predictive control algorithms for EV applications. Electronic Control technology leads adoption curves while Hydraulic Control retains relevance in heavy commercial vehicles where pneumatic-electric integration remains cost-prohibitive. Electric Vehicles as an application segment is attracting disproportionate R&D allocation from Tier-1 Suppliers seeking long-term OEM partnerships.
NHTSA Federal Motor Vehicle Safety Standards and EU type-approval frameworks under UNECE WP.29 mandate stability-enhancing systems that torque vectoring satisfies or exceeds. EPA fleet efficiency targets and the EU Green Deal's CO2 reduction pathways indirectly accelerate adoption by rewarding driveline architectures that recuperate energy through selective wheel braking. Stakeholders must monitor how cybersecurity regulations from ISO/SAE 21434 reshape electronic control validation costs and supplier qualification timelines.
Market Dynamics
The transition from mechanical differentials to software-defined torque modulation is compressing supplier margins while elevating semiconductor and algorithmic capabilities as the primary value pools in vehicle dynamics control.
Growth Catalysts
- Dual-motor EV architectures:Battery electric platforms from Tesla, Rivian, and BYD require torque vectoring as standard equipment to manage independent wheel control, creating baseline demand across price segments.
- NHTSA Federal Motor Vehicle Safety Standard 126:Mandates for electronic stability control on all passenger vehicles effectively require active yaw-control capabilities that torque vectoring systems deliver.
- Silicon carbide inverters:Wider bandgap semiconductors enable faster switching frequencies for motor control, reducing latency in torque redistribution algorithms.
Market Restraints
- Neodymium price volatility:Rare earth magnet costs in electric motor rotors create input cost unpredictability for dual-motor and quad-motor drivetrain suppliers.
- Semiconductor foundry concentration:Taiwan Semiconductor Manufacturing and Samsung Foundry control advanced node production for automotive-grade microcontrollers, creating single-source vulnerability.
- Hydraulic system legacy lock-in:Heavy commercial vehicle manufacturers retain pneumatic-electric architectures due to brake system commonality, limiting electronic torque vectoring penetration in freight applications.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives for advanced automotive technology manufacturing attract torque vectoring module assembly to Chennai and Pune industrial corridors.
- ISO/SAE 21434 cybersecurity certification:Vehicle-type approval frameworks increasingly mandate secure electronic control architectures, creating qualification barriers that favor established suppliers with validation resources.
- Software-over-the-air monetization:Subscription-enabled performance upgrades for torque vectoring calibration allow OEMs to extract recurring revenue from hardware already installed at production.
Industry Challenges
- Embedded systems cybersecurity engineering:Vehicle manufacturers face acute shortages of engineers capable of implementing ISO/SAE 21434 threat analysis and risk assessment methodologies.
- Functional safety validation timelines:ASIL-D certification for torque vectoring control units extends development cycles by 18-24 months, compressing model-year integration windows.
- Legacy CAN bus integration:Older vehicle electrical architectures lack bandwidth for real-time torque command arbitration, forcing expensive gateway module redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Torque Vectoring System Market |
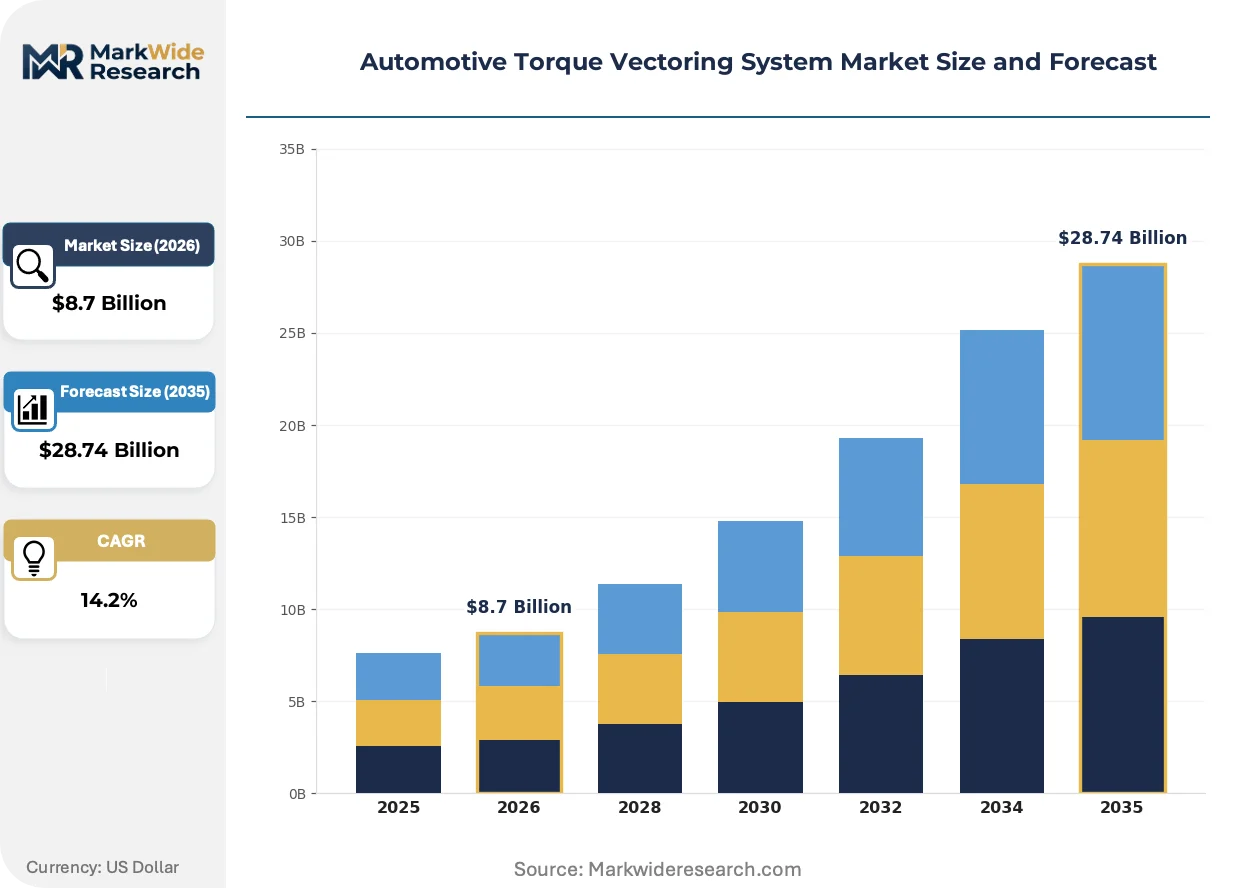
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Torque Vectoring, Passive Torque Vectoring, Hybrid Systems, Differential Systems Technology: Electronic Control, Mechanical Control, Hydraulic Control, Integrated Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Performance Cars |
| Companies Covered | GKN Automotive, BorgWarner Inc., ZF Friedrichshafen AG, Continental AG, Dana Incorporated, Bosch Group, Aisin Corporation, JTEKT Corporation, American Axle & Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Torque Vectoring System Market Emerging Trajectories
Electrification is collapsing the distinction between powertrain and chassis control, merging torque distribution with brake-by-wire and steer-by-wire into unified vehicle dynamics computers.
Multi-physics simulation platforms are supplanting physical prototype testing for torque vectoring calibration. Porsche Engineering and McLaren Automotive now validate 90 percent of dynamic behavior through virtual environments before metal prototyping. This compression of development cycles is shifting competitive advantage toward suppliers with captive simulation talent and cloud-computing partnerships.
EU type-approval frameworks under UNECE WP.29 now explicitly reference cybersecurity management systems for electronic control units. The regulation forces torque vectoring suppliers to maintain documented software bills of materials and vulnerability monitoring across 15-year vehicle lifecycles. German KBA and Dutch RDW type-approval authorities are enforcing these provisions most stringently on premium EV platforms.
Fleet procurement of torque vectoring calibration services is fragmenting traditional Tier-1 supply relationships. Rental and mobility operators now demand seasonal tire-and-terrain packages delivered through over-the-air updates rather than fixed factory settings. This behavioral shift is most visible in Nordic markets where fleet managers rotate between summer asphalt and winter ice calibrations on shared electric vehicle pools.
Automotive Torque Vectoring System Market Segmentation
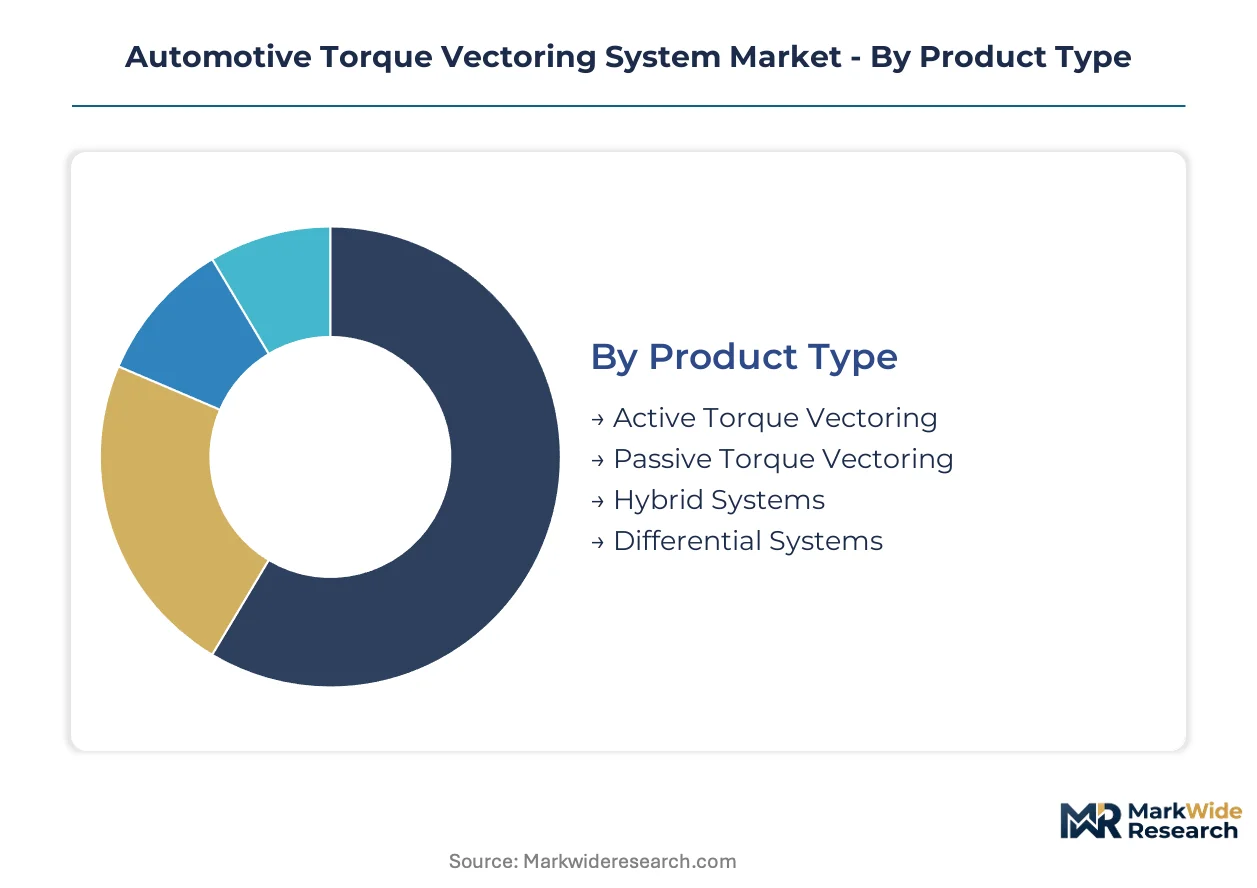
Segmentation in torque vectoring reveals how technology substitution pressures reshape supplier portfolios. Each dimension—product architecture, control methodology, customer channel, and vehicle application—carries distinct margin profiles and competitive barriers.
Product Type:
Active Torque Vectoring faces the most acute substitution pressure from brake-based torque modulation systems that deliver comparable yaw control at lower hardware cost.
- Active Torque Vectoring:Deploys clutch packs or dedicated motors to redistribute torque between wheels in real-time. Dual-motor EV platforms from Tesla and Rivian require this architecture as baseline equipment, though silicon carbide inverter costs constrain mass-market penetration.
- Passive Torque Vectoring:Relies on mechanical limited-slip differentials without electronic intervention. Demand concentrates in entry-level all-wheel-drive vehicles where OEMs prioritize system simplicity over predictive control capabilities.
- Hybrid Systems:Combine mechanical differentials with electronic brake intervention for cost-optimized performance.
- Differential Systems:Traditional torque-biasing differentials serve legacy internal combustion platforms with minimal electronic content.
Passive Torque Vectoring anchors the volume base while Active Torque Vectoring gains share at the steepest rate.
Technology:
Cost tier stratification separates premium electro-hydraulic integration from commodity mechanical implementations.
- Electronic Control:Microprocessor-driven torque commands execute within 10 milliseconds using wheel-speed sensors and inertial measurement units. Passenger EVs in China and Germany concentrate demand as NHTSA and EU regulations mandate stability-enhancing electronic architectures.
- Mechanical Control:Helical gear or viscous coupling differentials respond to speed differentials without software intervention. Emerging market OEMs favor this tier for price-sensitive compact SUVs where electronic validation costs prove prohibitive.
- Hydraulic Control:Piston-actuated clutch packs serve heavy commercial vehicles with existing pneumatic infrastructure.
- Integrated Systems:Unified vehicle dynamics computers merge torque vectoring with brake-by-wire and steer-by-wire.
Mechanical Control retains the largest installed base while Integrated Systems expand most quickly through premium EV platforms.
End User:
Customer type determines validation burden and contract tenure, with OEM direct relationships demanding ASIL-D certification that excludes smaller suppliers.
- OEMs:Vehicle manufacturers specify torque vectoring modules for platform integration during architectural design phases. Volkswagen Group and Hyundai Motor Group concentrate procurement in Germany and South Korea, requiring 15-year software maintenance commitments under UNECE WP.29 cybersecurity mandates.
- Tier-1 Suppliers:Bosch, ZF, and GKN Automotive package torque vectoring into complete axle assemblies for OEM customers.
- Aftermarket Providers:Performance tuning specialists retrofit mechanical limited-slip differentials to enthusiast vehicles.
- Vehicle Assemblers:Contract manufacturers integrate supplier-furnished modules without design authority.
OEMs dominate procurement value while Tier-1 Suppliers capture the steepest expansion trajectory through subsystem integration contracts.
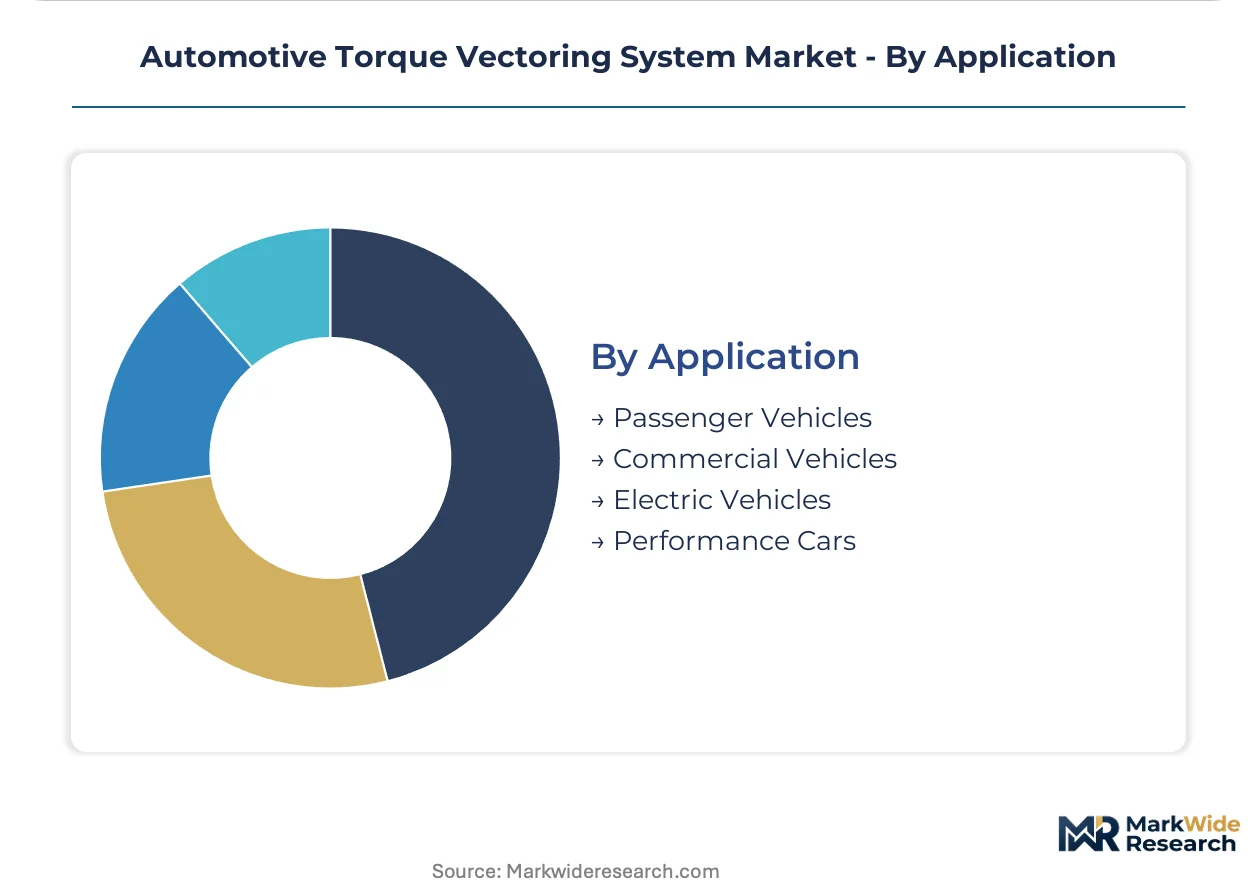
Application:
Vehicle application maps directly to motor count and control complexity, with electric platforms requiring fundamentally different engineering than internal combustion architectures.
- Electric Vehicles:Dual-motor and quad-motor drivetrains make torque vectoring standard equipment rather than optional performance upgrade. BYD, Tesla, and Rivian production volumes in China, the United States, and Germany drive disproportionate R&D allocation from control system suppliers.
- Performance Cars:Porsche and McLaren deploy torque vectoring to extract lap time advantages from mechanical grip limits.
- Passenger Vehicles:Mass-market crossovers adopt brake-based torque vectoring for regulatory compliance.
- Commercial Vehicles:Freight applications retain hydraulic architectures due to pneumatic brake system commonality.
Passenger Vehicles provide the volume foundation while Electric Vehicles climb the fastest as battery platform production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA Federal Motor Vehicle Safety Standard 126 anchors United States demand, mandating electronic stability control architectures that torque vectoring systems satisfy across passenger and commercial vehicle fleets.
United States
Tesla and Rivian production volumes in California and Texas drive dual-motor EV platform adoption. EPA fleet efficiency targets reward driveline architectures with selective wheel braking energy recuperation. Detroit's automotive engineering corridor concentrates legacy supplier R&D facilities transitioning toward electro-hydraulic integration.
Germany
Volkswagen Group and Porsche anchor premium EV torque vectoring procurement for performance and mass-market platforms. KBA type-approval authorities enforce UNECE WP.29 cybersecurity mandates most stringently on electronic control units. Stuttgart and Munich host ZF Friedrichshafen AG and Bosch Group vehicle dynamics engineering centers.
China
BYD and domestic EV manufacturers scale quad-motor drivetrains requiring standard torque vectoring equipment. MIIT regulations under dual carbon goals accelerate electrification timelines for automotive component suppliers. Shanghai and Shenzhen industrial corridors concentrate silicon carbide inverter and electric motor manufacturing clusters.
Japan
Toyota and Honda hybrid platforms sustain demand for integrated mechanical-electronic torque distribution systems. METI industrial policy supports domestic semiconductor supply chain resilience for automotive microcontroller production. Nagoya and Tokyo metropolitan areas anchor JTEKT Corporation and Aisin Corporation drivetrain engineering operations.
South Korea
Hyundai Motor Group and Kia Corporation procure torque vectoring modules for E-GMP dedicated EV platform architectures. MFDS-aligned vehicle safety frameworks incorporate electronic stability control requirements for domestic type approval. Seoul Capital Area and Busan-Ulsan industrial zones concentrate Hyundai Mobis and Tier-1 supplier integration facilities.
Automotive Torque Vectoring System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the torque vectoring system supply base. The market structure tiers between integrated vehicle dynamics specialists and component-focused suppliers serving specific control methodologies. European and Asian conglomerates anchor the premium electro-hydraulic segment while North American and Japanese firms compete on mechanical differential volume. Dominant competitive moves include strategic partnerships for silicon carbide inverter sourcing and geographic expansion toward Indian and Southeast Asian EV production corridors.
Among European-based diversified suppliers, ZF Friedrichshafen AG and Continental AG exemplify the integrated systems archetype, occupying positions that merge torque vectoring with brake-by-wire and steer-by-wire architectures. GKN Automotive represents the legacy all-wheel-drive specialist tier, leveraging decades of mechanical differential expertise toward electro-hydraulic transitions. Bosch Group anchors the semiconductor-enabled control tier, feeding electronic architectures through captive sensor and microcontroller portfolios.
| Leading Market Players |
|---|
| GKN Automotive |
| BorgWarner Inc. |
| ZF Friedrichshafen AG |
| Continental AG |
| Dana Incorporated |
| Bosch Group |
| Aisin Corporation |
| JTEKT Corporation |
| American Axle & Manufacturing |
| Others |
Supply Flow & Price Mechanics
Ninety-day semiconductor inventory cycles at automotive Tier-1 suppliers compress margin buffers for torque vectoring module producers, linking Taiwan foundry output directly to German OEM pricing power in electro-hydraulic systems.
Pricing Analysis
China-to-Germany price spreads for silicon carbide inverters exceed three-to-one ratios across equivalent automotive-grade specifications. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified integrated systems from mechanical differentials and brake-based yaw control modules. Cost compression in commodity electronic control units is intensifying because Chinese EV manufacturers negotiate volume offtakes exceeding 500,000 units annually. Fleet procurement managers at rental operators exhibit highest price sensitivity, while Porsche and McLaren engineering divisions prioritize predictive algorithm performance over per-unit cost.
Supply Chain Analysis
China and Germany anchor electric motor and inverter manufacturing clusters feeding torque vectoring assembly lines in Stuttgart, Shanghai, and Detroit. Neodymium permanent magnets draw from Chinese rare earth processing facilities, silicon carbide wafers rest on Taiwanese and South Korean fabrication capacity, and aluminum die-cast housings source from Mexican maquiladora operations. Single-source vulnerability concentrates in TSMC automotive microcontroller production at 7-nanometer nodes. Distribution runs through just-in-sequence delivery contracts directly to OEM final assembly plants rather than Tier-1 warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual-motor EV platform standardization represents a high-growth disruption as NHTSA Federal Motor Vehicle Safety Standard 126 mandates electronic stability control architectures across all passenger vehicle classes.
For Market Incumbents: Fortify semiconductor supply security through captive sourcing agreements with Taiwanese foundries or backward integration into silicon carbide substrate production. Defend margin position against brake-based torque modulation substitutes by accelerating ASIL-D certification timelines for integrated vehicle dynamics computers. Prioritize software-over-the-air monetization capabilities to extract recurring revenue from hardware installations. For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors at Chennai and Pune where production-linked incentives offset capital costs for torque vectoring module assembly. Target aftermarket calibration services for Nordic fleet operators demanding seasonal terrain packages delivered through over-the-air updates. Pursue white-label subsystem contracts with contract vehicle assemblers lacking in-house dynamics engineering. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core automotive electronics divisions with stranded mechanical differential assets. Five-to-ten year viability hinges on successful electro-hydraulic transition rather than legacy mechanical lock-in. Monitor silicon carbide inverter price convergence as the inflection signal for mass-market EV torque vectoring penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Sourcing Partnership | TSMC and Samsung Foundry supply agreements reduce latency in torque redistribution algorithms for dual-motor platforms. |
| ASIL-D Certification Acceleration | Functional safety validation compresses development cycles for OEM integration at Volkswagen Group and Hyundai Motor Group. |
| Software-Defined Vehicle Investment | Unified vehicle dynamics computers merge torque vectoring with brake-by-wire architectures at Porsche Engineering centers. |
| Geographic Manufacturing Footprint Expansion | Chennai and Pune assembly corridors capture PLI scheme incentives for Indian domestic EV production scaling. |
| Over-the-Air Calibration Monetization | Subscription-enabled performance upgrades extract recurring revenue from hardware already installed at Tesla and Rivian production. |
Methodological Framework
Desk research of vehicle production databases, IHS Markit registration data, and SEC 10-K filings preceded structured interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and dealership operations managers. Primary fieldwork combined with secondary validation from NHTSA regulatory filings and UNECE WP.29 type-approval documentation. Bottom-up unit economics triangulated against top-down market sizing across propulsion architecture and vehicle class segmentation.
Variance decomposition separates volume growth from content-per-vehicle expansion across the modeling period. Segmentation dimensions include propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from S-curve adoption modeling calibrated to dual-motor EV platform ramp schedules. Forecast inputs incorporate silicon carbide inverter cost trajectories and rare earth magnet price volatility assumptions.
Underlying assumptions cover NHTSA stability control mandate enforcement, EU Green Deal electrification timelines, and Chinese dual carbon policy implementation, with deviation risk concentrated in semiconductor foundry capacity allocation and cybersecurity regulation stringency. Recalibration cycles align with material shifts in EV platform standardization and ISO/SAE 21434 certification adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Turbocharger Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Powertrain Testing Market
Powertrain
Automotive Water Pump Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Fuel Injection Systems Market
Powertrain
Transmission Shift Actuator Market
Powertrain
Global Automotive Clutch Market
Powertrain
Global Automotive Tappet Market
Powertrain
Engine Support Bar Market
Powertrain
High Speed Engine Market
Powertrain
Global Automotive Torque Converter Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Torque Limiter Market