
 Global Automotive Control Panel Market | 2026-2036
Global Automotive Control Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Control Panel Market Intelligence
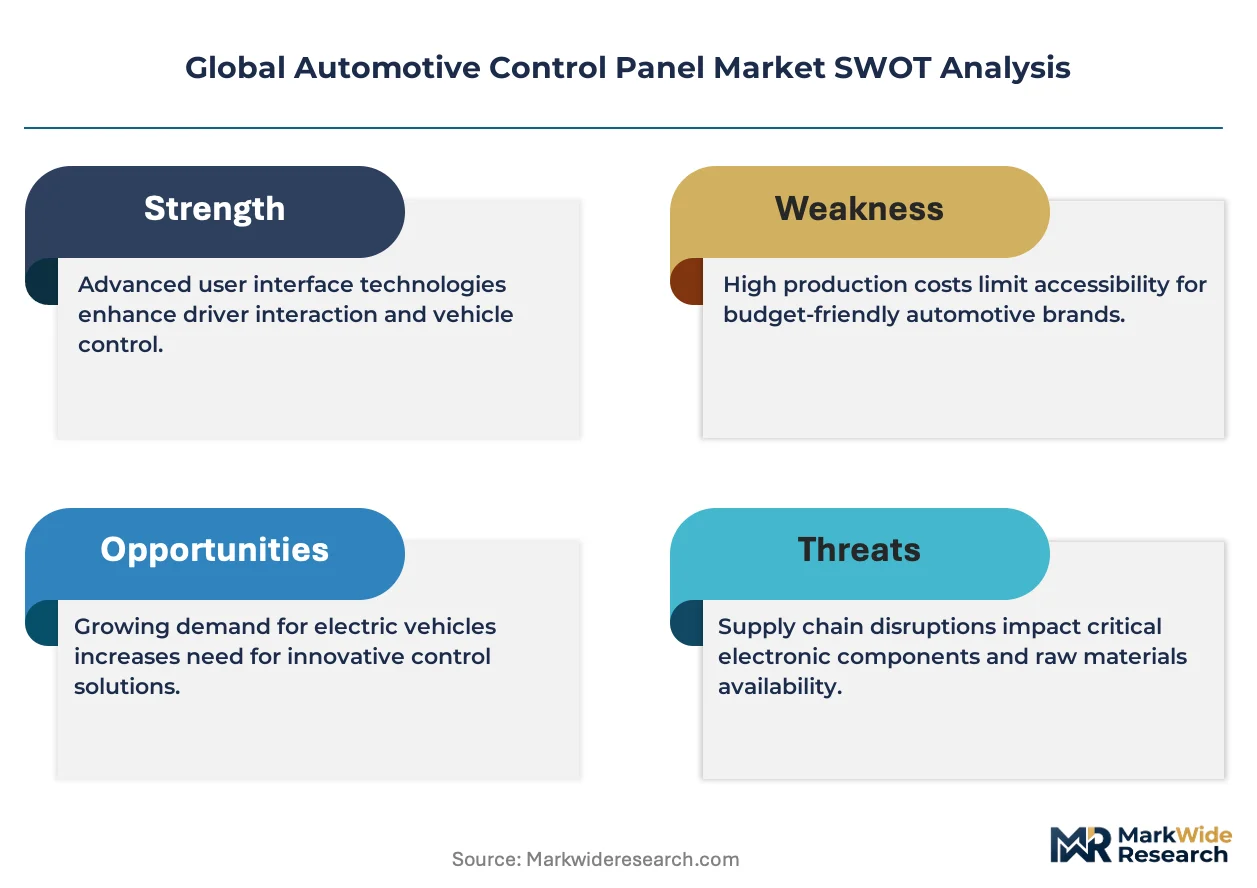
The ISO 26262 functional safety standard is unwinding the traditional separation between hardware and software development in automotive cockpits. This shift benefits large, system-focused suppliers. Continental AG leverages its expertise in domain controllers to integrate multiple HMI functions. Robert Bosch GmbH competes on the strength of its in-house semiconductor and sensor portfolio. Valeo S.A. specializes in developing intuitive user interface technologies and driver monitoring systems for next-generation vehicles.
An automotive control panel is the primary human-machine interface that allows drivers and passengers to interact with vehicle systems. These panels integrate inputs like capacitive touchscreens and physical knobs with outputs on high-resolution LCD or OLED displays. Their core purpose is to centralize control over infotainment, climate, and critical vehicle settings. Digital Instrument Clusters and Head-up Displays represent the fastest-growing product types, displacing traditional analog gauges. The application in Electric Vehicles is a major growth area, requiring unique interfaces for battery management and charging status.
Regulatory frameworks directly shape panel design and functionality. In the United States, NHTSA rules govern driver distraction and the display of mandatory safety information, such as rearview camera feeds. The European Union's General Safety Regulation (GSR) requires interfaces for new advanced driver-assistance systems. In China, GB standards dictate the cybersecurity and electronic compatibility requirements for all in-vehicle components. Supplier success now depends on mastering software integration and achieving functional safety certification across diverse vehicle platforms.
Market Dynamics
The transition toward software-defined vehicles (SDVs) is the central force governing the automotive control panel market. This shift elevates software as the primary determinant of functionality, user experience, and brand differentiation, compelling suppliers to pivot from hardware-centric to software-first development models.
Growth Catalysts
- Digital Cockpit Adoption:The replacement of analog gauges with Digital Instrument Clusters and Head-up Displays is a primary catalyst. Automakers are using these high-resolution screens as a key differentiator to enhance the in-cabin experience and display advanced driver-assistance system information.
- Electric Vehicle Expansion:Demand from the Electric Vehicles segment provides significant momentum. EVs require unique HMI functionalities for monitoring battery state-of-charge, managing regenerative braking settings, and locating charging infrastructure, all integrated within the central control panel.
- Regulatory Mandates for Safety:The European Union's General Safety Regulation (GSR) mandates the inclusion of interfaces for new safety systems like intelligent speed assistance and driver drowsiness detection. This directly stimulates demand for more advanced and integrated panel designs.
Market Restraints
- Semiconductor Supply Volatility:The market is highly sensitive to fluctuations in the supply and cost of automotive-grade microcontrollers, display drivers, and memory chips. Any disruption in the semiconductor supply chain directly impacts control panel production schedules and manufacturing costs for OEMs.
- Display Panel Sourcing Risks:A high concentration of advanced LCD and OLED panel manufacturing in China, South Korea, and Taiwan creates a structural bottleneck. This exposes the supply chain to geopolitical risks, trade policy shifts, and localized capacity constraints affecting global availability.
- Functional Safety Compliance Burden:Achieving ISO 26262 certification for safety-critical software and hardware is a complex and expensive restraint. The rigorous validation and verification processes required for certification extend development timelines and increase engineering overhead for suppliers.
Strategic Opportunities
- Driver Monitoring System Integration:A key opportunity lies in combining driver monitoring systems with infotainment controls into a single, cohesive unit. This allows for features like attention tracking and personalization, creating a more intuitive and safer human-machine interface for next-generation vehicles.
- Commercial Vehicle Modernization:The commercial truck and off-highway equipment segments represent an underpenetrated market. Developing ruggedized, function-specific control panels for these applications offers a significant avenue for growth beyond the saturated passenger car segment.
- Software and Feature Monetization:The shift to SDVs opens opportunities for suppliers to create platforms that support over-the-air (OTA) updates. This enables automakers to sell new features, user interface themes, and application upgrades to vehicle owners post-purchase, creating new revenue streams.
Industry Challenges
- Specialized Talent Scarcity:A persistent challenge is the shortage of software engineers who possess dual expertise in modern user interface development and stringent automotive functional safety standards. This talent gap can slow down project timelines and inhibit innovation across the industry.
- Cybersecurity Vulnerability Management:Protecting connected control panels from remote hacking and malicious attacks is a critical operational hurdle. Suppliers must invest continuously in threat modeling and security patching to comply with regulations like the UN R155 and maintain vehicle integrity.
- Cross-Platform Software Complexity:Integrating a single control panel software stack across multiple vehicle models with different underlying hardware and electronic architectures presents a major challenge. It requires substantial investment in abstraction layers and modular software design to manage complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Control Panel Market |
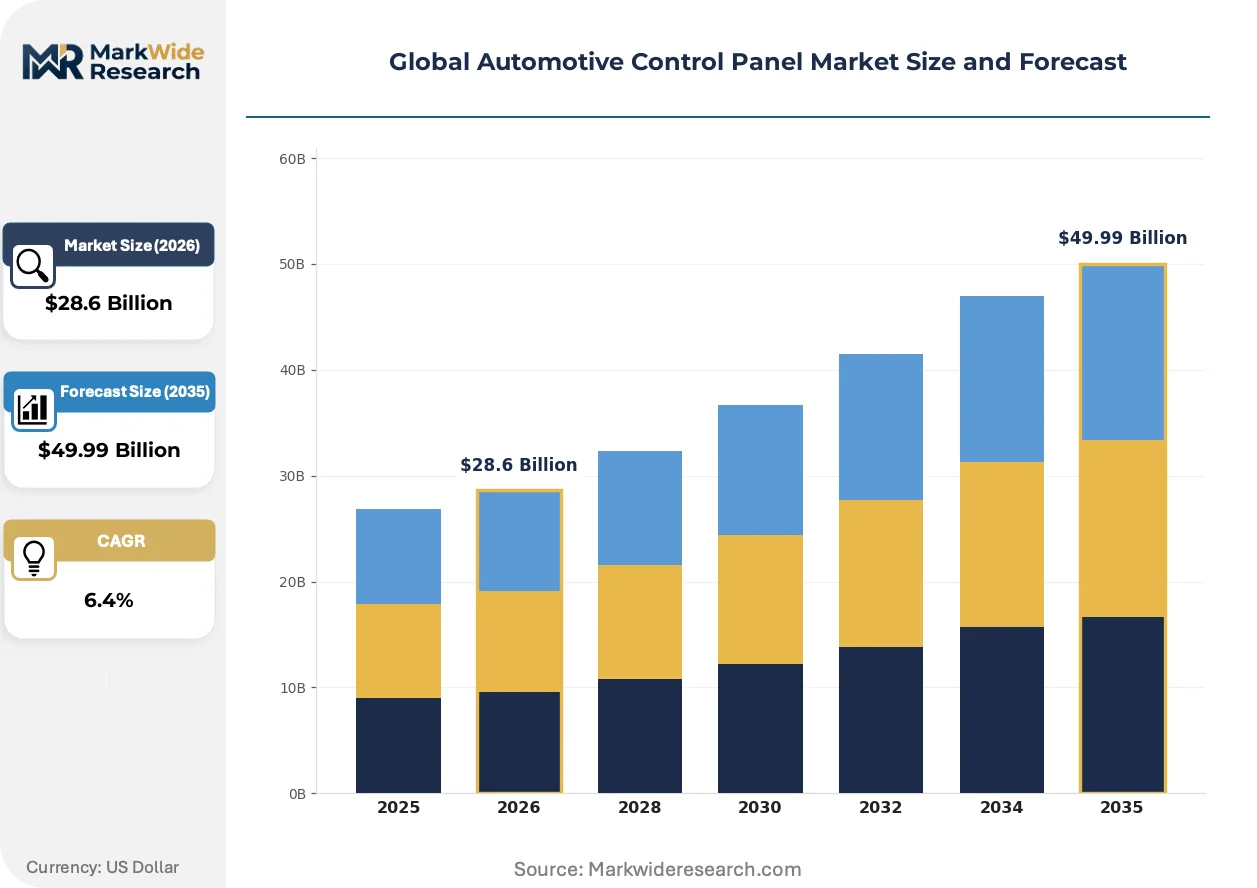
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Instrument Cluster, Analog Instrument Cluster, Hybrid Instrument Cluster, Head-up Display Technology: Resistive Touchscreen, Capacitive Touchscreen, OLED Display, LCD Display, LED Backlight Application: Passenger Vehicles, Commercial Trucks, Specialty Vehicles, Electric Vehicles, Autonomous Vehicles End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Denso Corporation, Faurecia Clarion, Continental AG, Magna International Inc., Hyundai Mobis Co., Ltd., ZF Friedrichshafen AG, Robert Bosch GmbH, MinebeaMitsumi Inc., Valeo S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Control Panel Market Strategic Shifts & Innovations
The user experience is becoming the primary axis of competition, with software and HMI design overtaking traditional metrics of performance. Innovations focus on creating seamless, intuitive, and upgradable interactions between the driver, passengers, and the vehicle.
Zonal architectures are fundamentally altering how control panels connect to the wider vehicle network. This design paradigm consolidates processing power into a few high-performance domain controllers rather than dozens of individual ECUs. Automakers in the premium and EV segments are rapidly adopting this model. This trend is decomposing the legacy one-function-per-box hardware model, forcing panel suppliers to develop software that can interface with centralized computing platforms.
New rules from the United States' NHTSA regarding driver distraction are directly influencing HMI design philosophies. These regulations compel designers to carefully balance the richness of touchscreen interfaces with the need to minimize the cognitive load on the driver. Consequently, many automakers are reintroducing physical knobs or haptic feedback for critical functions like volume and climate control, especially in vehicles equipped with large, expansive displays.
Consumer expectations for smartphone-like connectivity and upgradability are driving a behavioral shift in the market. This disrupts the traditional model of a fixed-feature vehicle, pushing automakers toward offering over-the-air (OTA) software updates. This trend is most advanced in China, where buyers prioritize vehicles that can receive new functions, interface enhancements, and third-party applications long after the initial purchase.
Global Automotive Control Panel Market Segmentation
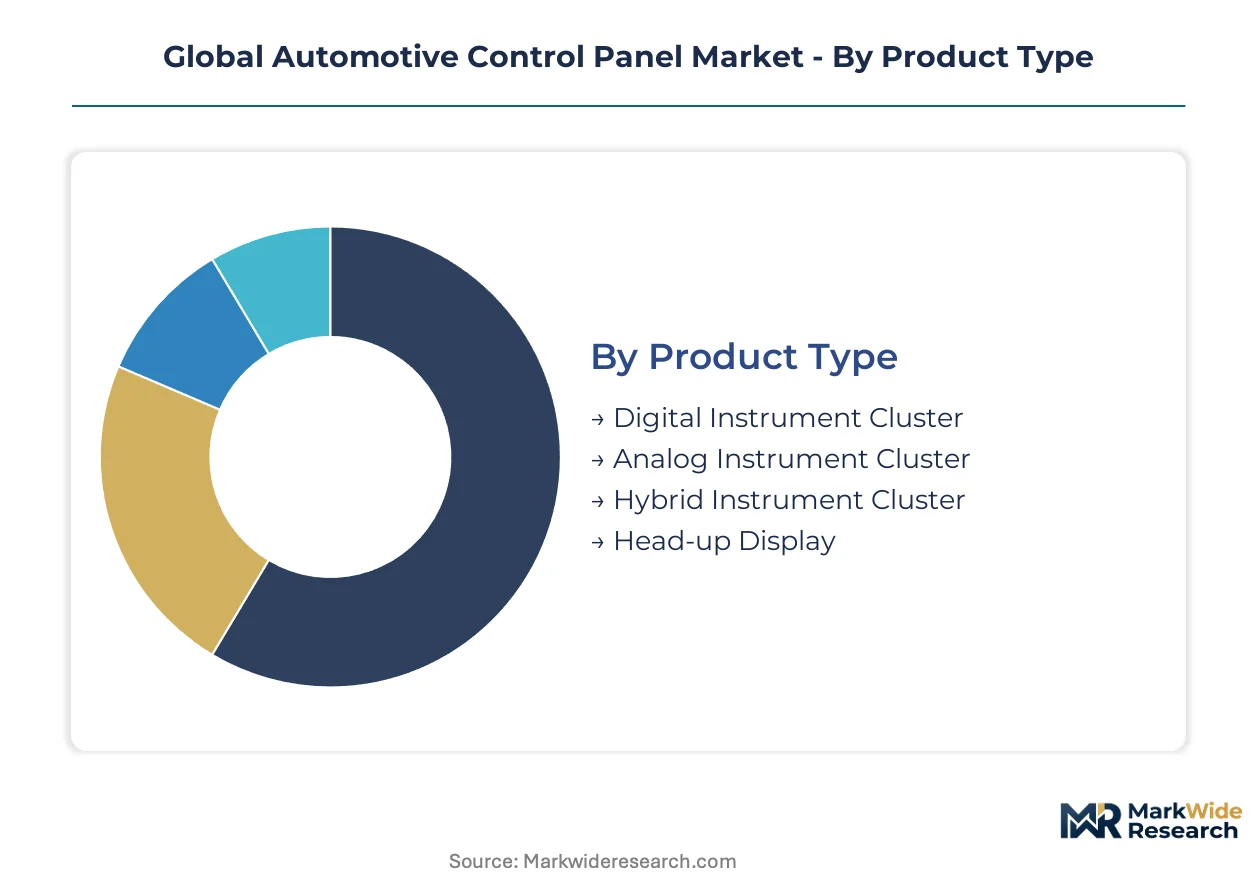
The global automotive control panel market segments offer insight into the diverse technological and application landscapes shaping vehicle interiors. Understanding these distinctions helps pinpoint specific growth opportunities and areas of intense competition within the evolving automotive ecosystem, particularly as software-defined vehicles become standard.
Product Type:
Regulatory frameworks, such as NHTSA guidelines on driver distraction, directly influence the design and adoption of various control panel product types in vehicles.
- Digital Instrument Cluster:These high-resolution displays replace traditional analog gauges, offering customizable information, navigation, and advanced driver-assistance system data. Demand concentrates in premium passenger vehicles and Electric Vehicles, driven by the desire for enhanced user experience and flexible information delivery.
- Head-up Display:Projecting critical information like speed and navigation directions onto the windshield, these systems minimize driver distraction by keeping eyes on the road. Adoption is accelerating in luxury and performance vehicles, spurred by safety mandates and the integration of augmented reality features.
- Analog Instrument Cluster:Traditional mechanical gauges display basic vehicle information, characterized by their simplicity and lower production cost. This product type primarily serves entry-level and older vehicle models in cost-sensitive markets.
- Hybrid Instrument Cluster:Combining physical gauges with integrated digital displays, these panels offer a transitional solution. They balance traditional aesthetics with modern information presentation in mid-range vehicle segments.
Established volume favors Analog Instrument Cluster; emerging adoption favors Head-up Display.
Technology:
Technological maturity and cost structures differentiate control panel components, impacting their prevalence across vehicle tiers and functionalities.
- Capacitive Touchscreen:Utilizing electrical properties of the human body, these screens offer highly responsive, multi-touch gesture recognition, mirroring smartphone interfaces. Demand is widespread across all vehicle segments, particularly in infotainment and climate control systems, due to superior user experience.
- OLED Display:Organic Light Emitting Diode displays offer superior contrast, true blacks, and flexible form factors, enabling innovative cockpit designs. Adoption is concentrating in high-end luxury vehicles and premium Electric Vehicles, where visual fidelity and design flexibility are paramount.
- Resistive Touchscreen:These screens detect touch through pressure, offering durability and operation with gloves or styluses. They find application in commercial vehicles and industrial equipment where ruggedness is prioritized over multi-touch capabilities.
- LCD Display:Liquid Crystal Displays are a widely adopted and cost-effective technology for instrument clusters and central displays. Their versatility and established manufacturing infrastructure ensure broad usage across most vehicle types.
- LED Backlight:Light Emitting Diode backlighting enhances the brightness and energy efficiency of LCD panels. This technology is a standard component in modern automotive displays, improving readability and extending panel lifespan.
Innovation in display technology drives new user interaction paradigms.
Application:
Varying operational environments and user requirements dictate the design and feature sets of control panels across different vehicle applications.
- Passenger Vehicles:This segment represents the largest volume market for control panels, driven by consumer demand for advanced infotainment, navigation, and comfort features. Panel designs prioritize aesthetics, connectivity, and intuitive interaction for a broad user base.
- Electric Vehicles:Requiring unique interfaces for battery management, charging status, and regenerative braking, this segment offers significant growth for specialized control panels. The rapid expansion of EV manufacturing, particularly in China, drives demand for advanced digital cockpits.
- Commercial Trucks:Control panels for commercial trucks emphasize ruggedness, clear readability, and integration with fleet management systems. Focus areas include navigation, driver assistance, and vehicle diagnostics for long-haul and heavy-duty operations.
- Specialty Vehicles:This category includes vehicles like agricultural machinery, construction equipment, and emergency vehicles, requiring highly durable and function-specific control panels. Customization for extreme conditions and specialized operational data is a key requirement.
- Autonomous Vehicles:Future autonomous vehicles will require advanced human-machine interfaces for monitoring automated driving systems and facilitating seamless transitions between human and machine control. This application demands redundant displays and intuitive feedback mechanisms.
The shift toward electrification and autonomy redefines panel functionality across vehicle applications.
End User:
The automotive supply chain structure influences how control panels are designed, manufactured, and integrated into final vehicles.
- OEMs:Original Equipment Manufacturers integrate control panels directly into their vehicle designs, often working closely with Tier-1 suppliers to customize features and aesthetics. OEMs are the primary decision-makers for panel specifications and user experience.
- Tier-1 Suppliers:These companies design, develop, and manufacture complete control panel systems, including hardware and software, for direct supply to OEMs. Robert Bosch GmbH and Continental AG exemplify this role, leveraging their system integration expertise.
- Aftermarket Suppliers:These entities provide replacement or upgrade control panel units for vehicles already on the road. Their offerings often focus on enhancing existing functionalities or adding new features like improved navigation or connectivity.
- Vehicle Assemblers:These companies are responsible for the final assembly of vehicles, integrating components from various suppliers, including control panels. Their role involves ensuring proper fit, function, and testing of the integrated systems.
Collaboration and integration across the supply chain are critical for market success.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for electric vehicle adoption and stringent safety mandates are significantly shaping the global automotive control panel market. These regulatory pushes accelerate demand for advanced digital cockpits and integrated HMI solutions. Investments in smart manufacturing hubs further support the localized production of these sophisticated components.
China
China's massive domestic EV market drives substantial demand for advanced digital instrument clusters and large touchscreens. GB standards dictate cybersecurity and electronic compatibility for in-vehicle components, influencing panel design. Major automotive manufacturing centers like Shenzhen and Shanghai are hubs for HMI and display technology development.
Germany
Germany's premium automotive sector prioritizes sophisticated HMI solutions and functional safety compliance. The KBA oversees vehicle type approval, including safety-critical control panel features. Stuttgart and Munich host significant R&D activities for advanced cockpit systems and software-defined vehicle architectures.
United States
Demand in the United States concentrates on intuitive infotainment systems and head-up displays, driven by consumer preference for connectivity. NHTSA rules govern driver distraction, influencing the integration of physical controls with touch interfaces. Silicon Valley and Detroit are centers for automotive software development and HMI innovation.
Japan
Japan's automotive industry emphasizes high-quality displays and robust functional safety, particularly for advanced driver-assistance systems. METI policies support research into next-generation in-vehicle electronics and display technologies. Nagoya and Yokohama feature strong concentrations of automotive component suppliers and technology firms.
India
India's market shows a growing appetite for feature-rich control panels in mid-range and premium vehicles. BIS standards ensure the quality and safety of automotive electronic components. Chennai and Pune are emerging as manufacturing and R&D hubs for automotive electronics.
Global Automotive Control Panel Market Key Industry Players
Player mix skews toward large, established Tier-1 automotive suppliers with deep system integration capabilities for complex cockpit systems. The market structure is tiered, featuring a few dominant players providing comprehensive hardware and software solutions alongside specialized hardware and software providers. Strategic archetypes include integrated system providers, display technology specialists, and software-centric HMI developers. Dominant competitive moves involve strategic partnerships for technology co-development, expanding into new geographical markets, and portfolio diversification into software-defined vehicle solutions.
Within the integrated system provider archetype, Continental AG and Robert Bosch GmbH exemplify broad expertise spanning hardware, software, and functional safety across diverse vehicle platforms. These large German-based entities integrate multiple HMI functions through advanced domain controllers and leverage in-house semiconductor and sensor portfolios. Valeo S.A., a French S.A. entity, represents a specialist in developing intuitive user interface technologies and driver monitoring systems for next-generation vehicles. These companies leverage extensive R&D capabilities and global manufacturing footprints to serve major automotive OEMs with complex, safety-critical control panel solutions.
| Leading Market Players |
|---|
| Denso Corporation |
| Faurecia Clarion |
| Continental AG |
| Magna International Inc. |
| Hyundai Mobis Co., Ltd. |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| MinebeaMitsumi Inc. |
| Valeo S.A. |
| Others |
Cost & Logistics Intelligence
ISO 26262 functional safety certification gates both supply qualification and price differentiation for automotive control panels. This rigorous standard mandates extensive validation, directly impacting component costs and market entry barriers for suppliers.
Pricing Analysis
Cost-plus contract patterns, often indexed to semiconductor and display panel prices, dominate the automotive control panel market. Price differentiation stems from the level of functional safety certification and the integration complexity of advanced HMI features. Automakers demand cost efficiency in high-volume segments, leading to pricing pressure. Entry-level vehicle segments exhibit the highest price sensitivity, while premium and EV segments prioritize feature sets, connectivity, and design flexibility over absolute cost.
Supply Chain Analysis
Just-in-time inventory strategies, prevalent in automotive manufacturing, expose control panel suppliers to significant production risks. Geographic supply concentration for advanced LCD and OLED panels centers heavily in China, South Korea, and Taiwan, creating a structural bottleneck. Raw material dependencies include automotive-grade microcontrollers, display drivers, and specialized memory chips, vulnerable to market fluctuations. Geopolitical risks and trade policy shifts further exacerbate supply chain vulnerability. Distribution runs through Tier-1 suppliers directly to Original Equipment Manufacturers for integration into final vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around functional safety standards and cybersecurity requirements creates a defensive moat for established automotive control panel suppliers. This structural advantage limits new entrants and reinforces market leaders.
For Market Incumbents: Compound existing expertise in domain controllers by investing in software-defined vehicle architectures. This move addresses the threat of software-centric competitors and leverages established hardware integration capabilities. Deepen vertical integration into specialized semiconductor manufacturing to mitigate supply volatility and secure critical components. Focus R&D on advanced driver monitoring systems to enhance safety and personalization features, differentiating offerings in a competitive landscape.
For New Entrants and Emerging Players: Underserved niche applications in commercial vehicle modernization offer a significant white-space target. Focus on ruggedized, function-specific control panels for off-highway equipment, a segment less saturated than passenger cars. A go-to-market angle involves offering modular, customizable software platforms that can adapt to diverse vehicle types. Target regional markets with less stringent regulatory barriers initially for faster adoption.
For Investors and Strategic Acquirers: The European Union's General Safety Regulation (GSR) reshapes the acquisition landscape, favoring companies with certified advanced driver-assistance system interfaces. Long-term viability hinges on suppliers capable of delivering integrated hardware-software solutions for software-defined vehicles. Target mid-cap specialists with strong intellectual property in HMI software or display technology. The signal to watch is the acceleration of automotive OEM platform consolidation toward zonal architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Platform Development | Enables over-the-air updates and new feature monetization for automakers, enhancing vehicle lifecycle value. |
| Advanced Display Technology Integration | Delivers superior user experience and supports augmented reality features in premium vehicle cockpits. |
| Functional Safety Certification Expansion | Ensures compliance with stringent regulations like ISO 26262, critical for safety-critical HMI components. |
| Commercial Vehicle HMI Customization | Addresses specialized needs for ruggedness and function-specific data in an underpenetrated market segment. |
| Driver Monitoring System Co-development | Integrates attention tracking with infotainment, creating safer and more personalized in-cabin experiences. |
Research Approach
Initial hypotheses were tested against primary input from automotive OEM platform engineers, Tier-1 procurement leads, HMI software developers, and functional safety consultants, and refined through iterative feedback. This approach combined in-depth interviews with secondary validation from vehicle production databases, regulatory filings, and industry association reports. Bottom-up market sizing was triangulated with top-down revenue projections.
Variance decomposition models were employed to disaggregate market drivers across the analysis window. Segmentation dimensions modeled included product type, display technology, application, and regional EV manufacturing clusters. Compound Annual Growth Rates were derived from historical trends and projected adoption rates for digital cockpits. Key forecast inputs included projected EV sales volumes and regulatory implementation timelines.
Forecasts assume regulatory continuity in the United States (NHTSA), European Union (GSR), and China (GB standards); material policy shifts would require re-modeling. Geopolitical events impacting semiconductor supply chains and changes in consumer preference for physical controls represent specific risk factors. Revision becomes warranted when these conditions cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Automotive V2X Antenna Market
Automotive Circuit Systems
Automotive Accelerator Pedal Module Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Automotive Oil Pressure Control Valve Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Automotive Steering Wheel Switch Market
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Automotive Ethernet Switches Market
Automotive Circuit Systems
Automotive Digital Isolators Market
Automotive Circuit Systems
Automotive Body Control Module Market