
 Automotive Accelerator Pedal Module Market | 2026-2036
Automotive Accelerator Pedal Module Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Accelerator Pedal Module Market Analytics
Modularization of accelerator pedal assemblies is decoupling sensor hardware from mechanical linkage housings, letting OEMs swap electronic control units across vehicle platforms without redesigning footwell architecture. Robert Bosch GmbH leverages its sensor integration expertise to supply drive-by-wire modules to European and Asian OEMs. Continental AG anchors its position through captive production of contactless Hall-effect sensors for premium vehicle lines. Magna International competes on manufacturing scale, operating pedal module plants across multiple continents to serve just-in-sequence vehicle assembly.
An automotive accelerator pedal module translates driver foot input into throttle control signals through electronic sensors, mechanical linkages, or pneumatic actuators, typically incorporating Hall-effect or potentiometric position sensing with signal outputs ranging from analog voltage to digital SENT protocol. The assembly's primary purpose is to deliver precise, redundant throttle commands to engine management systems while meeting functional safety standards for unintended acceleration prevention. Electronic product type segments lead unit volume as drive-by-wire architectures displace cable-actuated designs, while sensor-based technology segments capture expanding margin pools through multi-function integration that combines throttle request with vehicle mode switching. OEM end-user channels dominate direct procurement volumes, though Tier-1 Suppliers sustain significant bargaining power by controlling module design and validation cycles.
The EPA enforces emissions compliance thresholds that tighten throttle response precision requirements, indirectly mandating electronic accelerator modules with closed-loop feedback. NHTSA's Federal Motor Vehicle Safety Standards govern pedal placement and unintended acceleration prevention, shaping module redundancy architectures and fail-safe logic design. The EU AI Act and CSRD disclosure rules are extending traceability requirements into automotive subsystems, compelling suppliers to document sensor algorithm provenance and material sourcing. Stakeholders must monitor how functional safety standard ISO 26262 evolves for drive-by-wire systems as software-defined vehicle architectures redefine hardware-software boundaries in pedal module procurement.
Market Dynamics
Drive-by-wire mandates are dissolving mechanical linkages between driver input and throttle response, forcing Tier-1 suppliers to rearchitect pedal modules around redundant sensor arrays and ASIL-D functional safety compliance.
Growth Catalysts
- EU F-Gas Regulation:Stringent fluorinated gas controls are accelerating sensor-based module adoption as automakers eliminate pneumatic actuator systems from vehicle platforms.
- Passenger vehicle OEM procurement:European and Asian manufacturers are expanding electronic pedal module orders to satisfy impending drive-by-wire compliance deadlines.
- Hall-effect sensing technology:Contactless position detection is displacing potentiometric designs across premium and mass-market vehicle lines due to superior durability and signal precision.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependencies in China create input cost volatility for Hall-effect sensor production.
- ISO 26262 validation timelines:ASIL-D certification requirements extend module development cycles by 18-24 months, compressing supplier margins on fixed-price contracts.
- Mechanical linkage aftermarket:Legacy cable-actuated pedal systems in aging vehicle fleets sustain replacement demand that delays full electronic module penetration.
Strategic Opportunities
- Commercial vehicle electrification:Battery-electric truck platforms in Germany and the United States require redesigned pedal modules with regenerative braking integration.
- EU AI Act traceability mandates:Algorithm provenance documentation requirements are creating service revenue streams for suppliers with embedded software audit capabilities.
- Sensor fusion convergence:Accelerator pedal modules are converging with brake-pedal sensors and steering-column controls into unified driver-input domain controllers.
Industry Challenges
- Functional safety engineering talent scarcity:ASIL-D certified firmware developers and systems engineers command premium compensation, constraining supplier scaling capacity.
- Legacy vehicle platform integration:Retrofitting electronic pedal modules into architectures designed for mechanical linkages requires custom mechanical adapters and recalibrated ECU mappings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Accelerator Pedal Module Market |
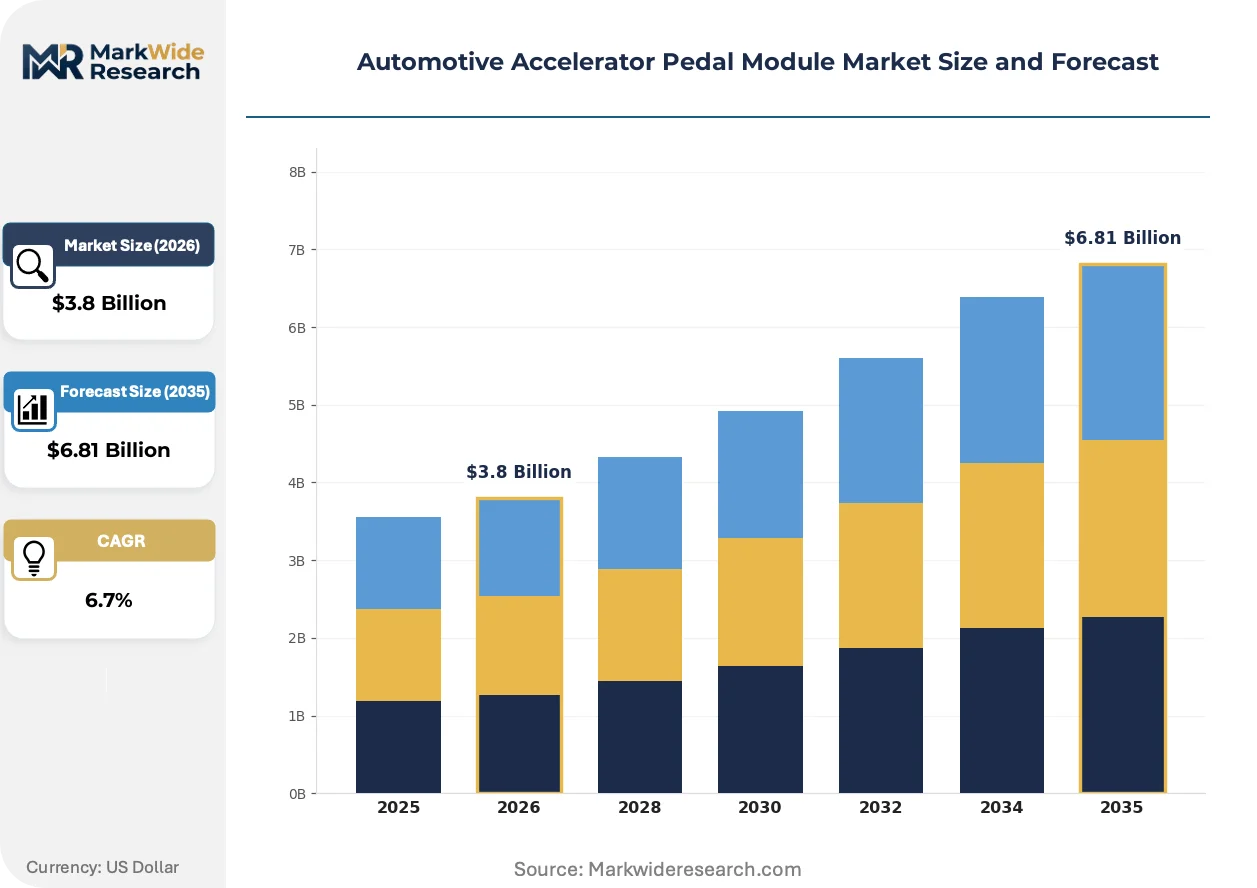
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Hydraulic, Pneumatic, Mechanical End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Sensor-Based, Contactless, Multi-Function, Drive-by-Wire Installation Type: Integrated, Retrofit, Standard, Custom |
| Companies Covered | HELLA GmbH & Co. KGaA, Magna International, Robert Bosch GmbH, Hitachi Astemo, Ltd., ZF Friedrichshafen AG, Denso Corporation, CTS Corporation, KSR International Co., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Accelerator Pedal Module Market Evolving Landscape
Accelerator pedal modules are transitioning from discrete mechanical-electronic assemblies to software-defined input devices whose functionality expands through over-the-air updates and cross-domain integration.
Redundant Hall-effect sensor architectures are converging with capacitive touch detection to enable multi-function pedal surfaces that distinguish between deliberate throttle commands and accidental foot contact. European OEMs are piloting these intelligent pedals on electric vehicle platforms where single-pedal driving modes require nuanced input interpretation. The structural consequence is compression of discrete switch component counts as gesture recognition migrates onto pedal hardware.
EPA emissions compliance thresholds are tightening throttle response precision requirements, indirectly mandating closed-loop electronic accelerator modules with millisecond-level signal latency. Engine management systems now require pedal position data streams synchronized with oxygen sensor feedback to optimize combustion efficiency. Powertrain calibration teams in the United States are responding by specifying digital SENT protocol outputs over legacy analog voltage signals.
Fleet operators are consolidating direct procurement relationships with Tier-1 suppliers, bypassing traditional OEM service parts channels for aftermarket pedal module replacements. Large rental and logistics companies in Japan are negotiating volume contracts for standardized electronic modules across mixed-vehicle fleets. This channel disintermediation is most visible in commercial vehicle segments where uptime metrics override brand-loyalty considerations in parts sourcing decisions.
Automotive Accelerator Pedal Module Market Segmentation
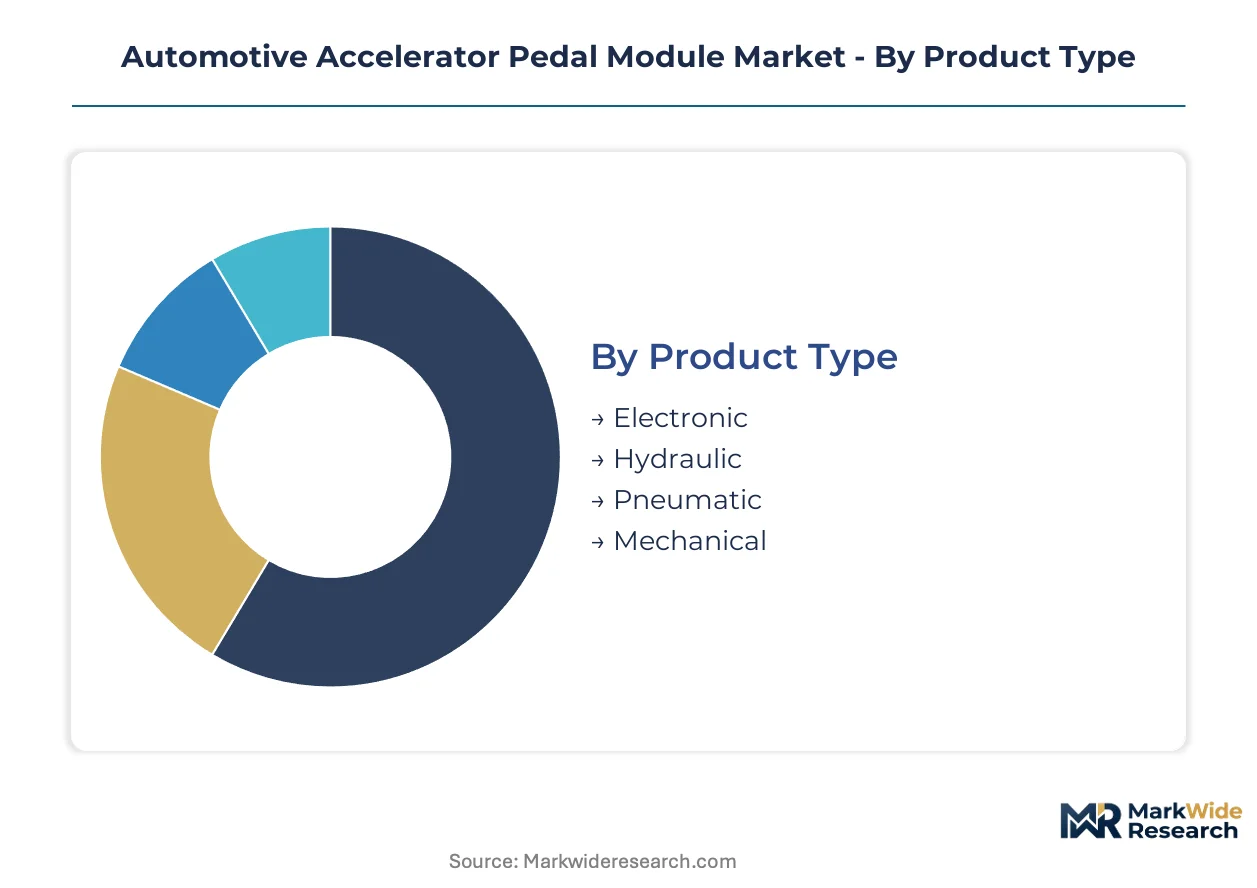
Accelerator pedal module procurement splits sharply across electronic and mechanical architectures, with sourcing patterns diverging by vehicle program maturity and regulatory compliance deadlines. Tier-1 suppliers configure production lines differently for each segment, creating distinct margin profiles and validation timelines.
Product Type:
Supply concentration in Hall-effect sensor manufacturing tilts procurement leverage toward electronic module specialists with captive semiconductor integration.
- Electronic:Solid-state architectures deploy redundant Hall-effect or inductive position sensors with ASIL-D functional safety compliance. Demand concentrates in Germany and Japan where OEM drive-by-wire mandates are tightening fastest; EPA emissions precision requirements are accelerating analog-to-digital signal protocol transitions.
- Hydraulic:Fluid-actuated pedal modules persist in commercial vehicle applications requiring high-force feedback. Fleet operators in the United States specify these for heavy-duty truck platforms where pedal resistance modulation supports driver fatigue management.
- Pneumatic:Compressed air systems face phase-out pressure from EU F-Gas Regulation fluorinated gas controls.
- Mechanical:Cable-actuated designs sustain aftermarket replacement demand in aging vehicle populations.
Electronic modules absorb the bulk of installed capacity; hydraulic configurations are expanding most quickly in commercial vehicle electrification programs.
End User:
Cost tier stratification separates direct OEM procurement from aftermarket channels, with validation burden and price sensitivity inversely correlated across the hierarchy.
- OEMs:Direct vehicle manufacturer procurement specifies custom pedal module architectures aligned with platform electrical systems. German and Japanese passenger vehicle OEMs dominate volume, integrating modules during body-in-white assembly sequences.
- Tier-1 Suppliers:These intermediaries control design validation cycles and software calibration, capturing margin through embedded firmware and sensor algorithm development.
- Aftermarket Providers:Standardized replacement modules serve independent repair networks with reduced functional safety documentation.
- Vehicle Assemblers:Contract manufacturers in emerging production regions procure pre-validated modules for knock-down assembly operations.
OEM channels command the highest unit values; Tier-1 Suppliers are gaining share fastest through software-defined module differentiation.
Technology:
Application requirements in electric vehicle platforms are forcing convergence between throttle input and regenerative braking control functions.
- Sensor-Based:Potentiometric and Hall-effect position detection systems output analog voltage or digital SENT protocol signals to engine management units. European premium OEMs specify these for millisecond-level throttle response precision under EPA emissions thresholds.
- Contactless:Inductive and capacitive sensing eliminates mechanical wear surfaces, extending service life in high-cycle commercial applications. Battery-electric truck deployments in the United States favor these for single-pedal driving mode integration.
- Multi-Function:Pedal surfaces incorporating capacitive touch zones distinguish deliberate throttle from accidental contact.
- Drive-by-Wire:Fully electronic architectures sever mechanical linkage to throttle bodies, requiring ASIL-D redundancy and fail-safe logic.
Sensor-Based technology holds the largest installed base; Contactless systems are climbing the fastest on commercial vehicle electrification demand.
Installation Type:
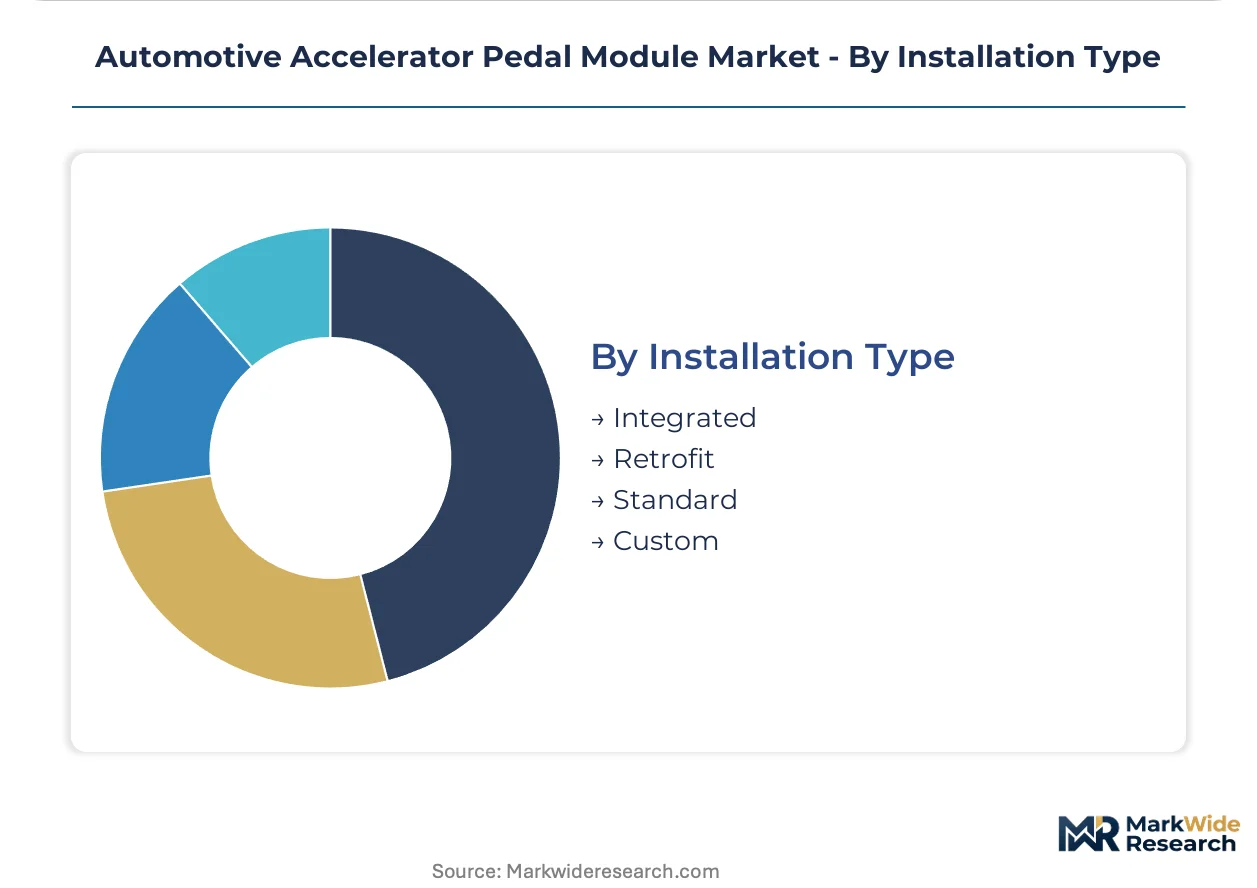
Customer type and vehicle program lifecycle stage determine whether modules ship as original equipment or post-production retrofits.
- Integrated:Pedal modules engineered into footwell structural assemblies during vehicle platform development. Japanese OEMs favor these for just-in-sequence delivery to assembly plants, minimizing line-side inventory.
- Retrofit:Electronic conversion kits replace mechanical cable systems in legacy vehicle fleets. United States commercial operators deploy these to extend fleet compliance with evolving emissions regulations.
- Standard:Catalog configurations serving multiple vehicle platforms with minimal customization.
- Custom:Bespoke architectures for low-volume specialty vehicles or motorsport applications.
Integrated installations dominate production volumes; Retrofit demand is gaining share fastest in commercial fleet sustainability programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Accelerator pedal module production clusters in Germany, Japan, and the United States while consumption spreads across vehicle assembly hubs worldwide. Supply chain geography diverges from end-market demand as Tier-1 suppliers concentrate manufacturing near OEM engineering centers.
Germany
Drive-by-wire mandates from the KBA and EU F-Gas Regulation are accelerating sensor-based module procurement by domestic OEMs. The EU Green Deal tightens emissions thresholds that electronic throttle systems must satisfy. Stuttgart and Munich host dominant supplier engineering clusters where Continental AG and Robert Bosch GmbH validate ASIL-D compliant architectures.
Japan
Passenger vehicle manufacturers are expanding electronic pedal module orders to meet domestic functional safety deadlines. METI standards govern automotive electronics certification, shaping supplier validation protocols. Toyota City and Hiroshima concentrate assembly capacity where Denso Corporation and Hitachi Astemo integrate pedal modules into just-in-sequence production.
United States
EPA emissions precision requirements are mandating closed-loop electronic accelerator modules with digital SENT protocol outputs. NHTSA Federal Motor Vehicle Safety Standards govern pedal placement and unintended acceleration prevention. Detroit and Tennessee assembly corridors source modules from Magna International plants serving domestic OEM electrification programs.
China
Domestic OEM procurement of electronic pedal modules is climbing as MIIT enforces stricter vehicle emissions and safety standards. Dual carbon goals accelerate displacement of cable-actuated designs in new energy vehicle platforms. Shanghai and Guangzhou supplier parks concentrate Hall-effect sensor production for local drive-by-wire adoption.
South Korea
Battery-electric vehicle platforms from domestic OEMs require redesigned pedal modules with regenerative braking integration. MFDS automotive safety guidelines influence module redundancy specifications. Ulsan and Hwaseong manufacturing belts host Hyundai-Kia supplier networks where contactless sensing technologies gain production scale.
Automotive Accelerator Pedal Module Market Competitive Landscape
The competitive structure tilts toward diversified Tier-1 automotive suppliers with captive sensor manufacturing capabilities. Market concentration remains moderate as specialized pedal module producers coexist with diversified chassis system integrators. Two strategic archetypes dominate: diversified global suppliers leveraging manufacturing scale across continents, and focused sensor technology specialists controlling Hall-effect semiconductor integration. Capacity expansion and strategic partnerships with OEM engineering centers represent the dominant competitive moves as suppliers position for drive-by-wire platform wins.
Among diversified global suppliers, Robert Bosch GmbH, Continental AG, and Magna International exemplify the scale-driven archetype. Bosch represents integrated sensor-to-system capability spanning semiconductor fabrication through module assembly. Continental AG occupies a position within the premium-tier supplier segment, anchoring Hall-effect sensor production for European OEM lines. Magna International sits within the manufacturing-scale tier, operating multi-continent production networks to serve just-in-sequence vehicle assembly programs.
| Leading Market Players |
|---|
| HELLA GmbH & Co. KGaA |
| Magna International |
| Robert Bosch GmbH |
| Hitachi Astemo, Ltd. |
| ZF Friedrichshafen AG |
| Denso Corporation |
| CTS Corporation |
| KSR International Co. |
| Continental AG |
| Others |
Value Network & Pricing Analysis
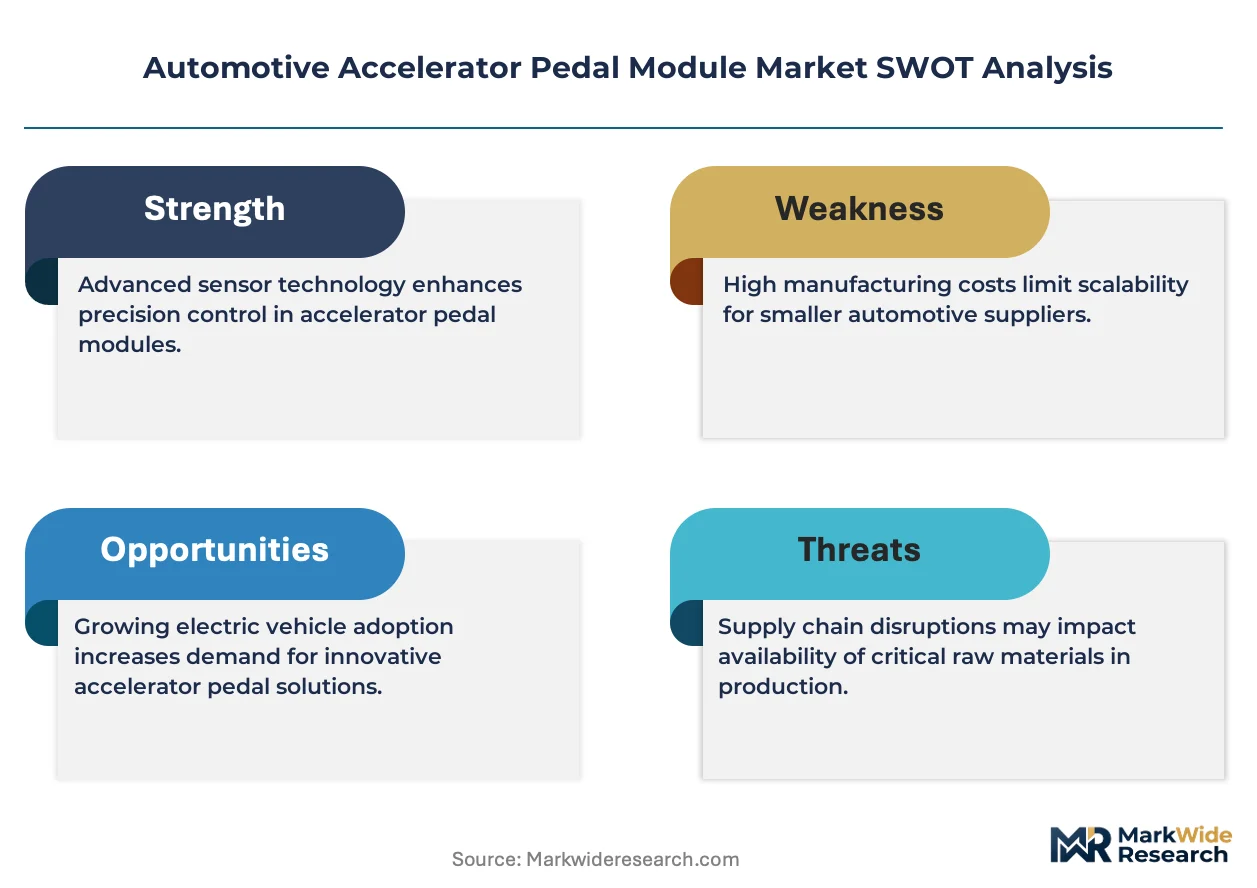
OEM procurement of ASIL-D certified electronic modules is concentrating demand among Tier-1 suppliers with captive Hall-effect sensor production, forcing smaller competitors toward mechanical linkage aftermarket segments where pricing power collapses.
Pricing Analysis
Margin tightening in standard electronic modules reflects ASIL-D validation cost absorption by suppliers locked into fixed-price OEM contracts. Three-tier pricing structure across premium, standard, and economy levels separates drive-by-wire architectures with redundant sensor arrays from single-sensor economy configurations and mechanical cable-actuated legacy systems. Cost-down pressure on standard-tier modules accelerates because Chinese Hall-effect sensor producers are expanding capacity. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while German premium OEMs prioritize certification grade over unit cost.
Supply Chain Analysis
EU F-Gas Regulation and domestic-content mandates in China and the United States are reshaping sourcing patterns for neodymium-dependent Hall-effect sensor production. Supply concentrates in Germany, Japan, and China where Robert Bosch GmbH, Denso Corporation, and domestic Chinese suppliers operate captive semiconductor fabrication. Raw material dependencies rest on rare earth magnet supply from China, copper winding stock from Chile, and epoxy molding compounds from South Korea. Single-source vulnerability in neodymium processing creates structural risk. Distribution runs through just-in-sequence delivery networks directly to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASIL-D certified firmware engineering talent scarcity props pricing for qualified suppliers, creating a supply-constrained market where validation capacity determines competitive position.
For Market Incumbents: Acquire Hall-effect semiconductor fabrication assets to secure magnet supply and sensor integration capability against rare earth price volatility. Lock in multi-year OEM platform wins through embedded software audit capabilities that satisfy EU AI Act traceability mandates. Expand captive production in Tennessee and Ulsan to serve electrification programs at domestic OEMs. For New Entrants and Emerging Players: Launch via direct fleet procurement relationships that bypass OEM service parts channels, targeting United States commercial vehicle operators with standardized electronic conversion kits for legacy mechanical systems. Focus white-space capture on retrofit installations for aging cable-actuated fleets facing EPA emissions compliance deadlines. Emphasize regenerative braking integration as the go-to-market differentiator for battery-electric truck platforms. For Investors and Strategic Acquirers: The window for entry favors sensor technology specialists with ISO 26262 validation infrastructure and existing Hall-effect patent portfolios. Long-term viability hinges on software-defined module architectures that expand functionality through over-the-air updates. Monitor NHTSA rulemaking on unintended acceleration prevention as the inflection signal for ASIL-D compliance mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces validation burden across vehicle programs for Tier-1 suppliers serving multiple OEMs. |
| Battery Supply Agreement | Secures pedal module integration slots on electric vehicle platforms with regenerative braking requirements. |
| Software-Defined Vehicle Investment | Enables over-the-air functional updates that extend module lifecycle and create recurring revenue streams. |
| Geographic Manufacturing Footprint | Positions suppliers for just-in-sequence delivery to assembly corridors in Germany, Japan, and Tennessee. |
| Charging Infrastructure Partnership | Aligns pedal module producers with fleet electrification programs requiring single-pedal driving calibration. |
Research Methodology
Vehicle production databases, IHS Markit registration data, and SEC filings from Tier-1 suppliers formed the secondary backbone of this analysis. Primary interviews with OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distributors, and dealership operations specialists validated demand assumptions. Bottom-up unit volume estimates triangulated against top-down market value assessments across electronic, hydraulic, pneumatic, and mechanical product segments.
Historical trendline analysis of drive-by-wire adoption rates informed projection modeling across the analysis window. Segmentation dimensions included propulsion architecture, vehicle class, sensor technology type, and regional production cluster. CAGRs derived from fitted growth curves applied to OEM procurement pipeline data and regulatory compliance deadline schedules. Forecast inputs incorporated MIIT enforcement timelines in China and KBA functional safety mandate progression in Germany.
The model assumes a particular technology adoption path; alternative pathways for contactless inductive sensing would alter the outlook if Hall-effect magnet supply disruptions accelerate substitution. Forecasts reflect assumptions about ASIL-D certification timeline stability and rare earth supply chain continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Global Automotive VVT System Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Cell Contact System Carrier Market
Automotive Circuit Systems
Automotive Horn Systems Market
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Automotive Launch Control System Market
Automotive Circuit Systems
Automotive Ethernet Switches Market
Automotive Circuit Systems
Vehicle Roof Control Module Market