
 Automotive Ultrasonic Technologies Market | 2026-2036
Automotive Ultrasonic Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ultrasonic Technologies Market Analysis
ISO 26262 functional safety qualification is unwinding the competitive landscape for automotive ultrasonic component suppliers. Robert Bosch GMBH leverages its in-house semiconductor and sensor packaging capabilities to control cost positions across European OEM programs. Valeo SA anchors its portfolio around integrated parking assistance modules that bundle ultrasonic sensors with ECU software. Texas Instruments Inc competes through dedicated ultrasonic analog front-end ICs that reduce signal processing latency for Tier-1 module makers.
Automotive ultrasonic technologies encompass piezoelectric transducers, signal conditioning electronics, and embedded firmware that emit and receive acoustic waves above 20 kHz to detect object proximity, typically operating at 40-58 kHz frequencies with detection ranges from 0.2 to 10 meters depending on vehicle application. These systems serve primarily as cost-effective near-field sensing layers within multi-modal ADAS architectures, complementing radar and camera systems where short-range precision matters. Ultrasonic sensors dominate unit shipments within the product type landscape, while Advanced Driver Assistance Systems applications command the highest value per vehicle as OEMs bundle parking assistance with automated emergency braking functions. Pulse Echo Technology retains the largest installed base, though Frequency Modulation variants are gaining traction for improved resolution in blind spot monitoring configurations.
NHTSA mandates on rear visibility and automatic emergency braking in the US, combined with EU General Safety Regulation requirements for intelligent speed assistance and reversing detection, are expanding mandatory fitment scopes for ultrasonic modules across vehicle classes. CE marking under the EU's Radio Equipment Directive and EMC standards further conditions market access for non-European suppliers. Stakeholders must monitor how software-defined vehicle architectures reshape the interface between discrete ultrasonic hardware and centralized compute platforms.
Market Dynamics
Software-defined vehicle architectures are collapsing the traditional boundary between discrete ultrasonic hardware and centralized compute platforms, forcing Tier-1 suppliers to renegotiate their role in ADAS value chains.
Growth Catalysts
- NHTSA Rear Visibility Mandate:US regulations requiring backup cameras and proximity detection systems have standardized ultrasonic fitment across light vehicle classes, creating baseline volume for parking assistance modules.
- Piezoelectric MEMS Transducers:Advanced ceramic manufacturing processes are shrinking sensor form factors while extending detection ranges, enabling integration into bumper fascias with reduced aesthetic compromise.
- German OEM Sourcing Concentration:Premium passenger vehicle manufacturers in Stuttgart and Munich are specifying multi-sensor arrays per vehicle, driving per-unit sensor counts above twelve in luxury segments.
Market Restraints
- Raw Material Concentration:Lead zirconate titanate ceramic supply chains concentrate in East Asian foundries, exposing European module makers to input cost volatility and logistics friction.
- Frequency Interference Limitations:Ultrasonic systems operating at 40-58 kHz suffer cross-talk degradation in dense parking environments where multiple vehicles emit concurrent acoustic pulses.
- LiDAR Substitution Pressure:Solid-state optical sensors are compressing the addressable market for high-resolution short-range detection in premium automated parking applications.
Strategic Opportunities
- India PLI Scheme for Automotive Components:Production-linked incentives for advanced driver assistance hardware are attracting module assembly investments to serve domestic OEMs and export markets.
- Frequency Modulation Convergence:FM-coded ultrasonic waveforms combined with machine learning inference at the edge are opening resolution capabilities previously reserved for millimeter-wave radar.
- Aftermarket Retrofit Channels:Independent service networks in Brazil and Mexico are deploying universal parking assistance kits for vehicle parcs lacking factory-installed proximity systems.
Industry Challenges
- ISO 26262 ASIL Certification Timelines:Functional safety qualification for ultrasonic signal processing firmware extends development cycles by eighteen to twenty-four months for new platform introductions.
- Legacy CAN Bus Integration:Module suppliers must maintain backward compatibility with decade-old vehicle network architectures while supporting Ethernet-based zonal compute topologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ultrasonic Technologies Market |
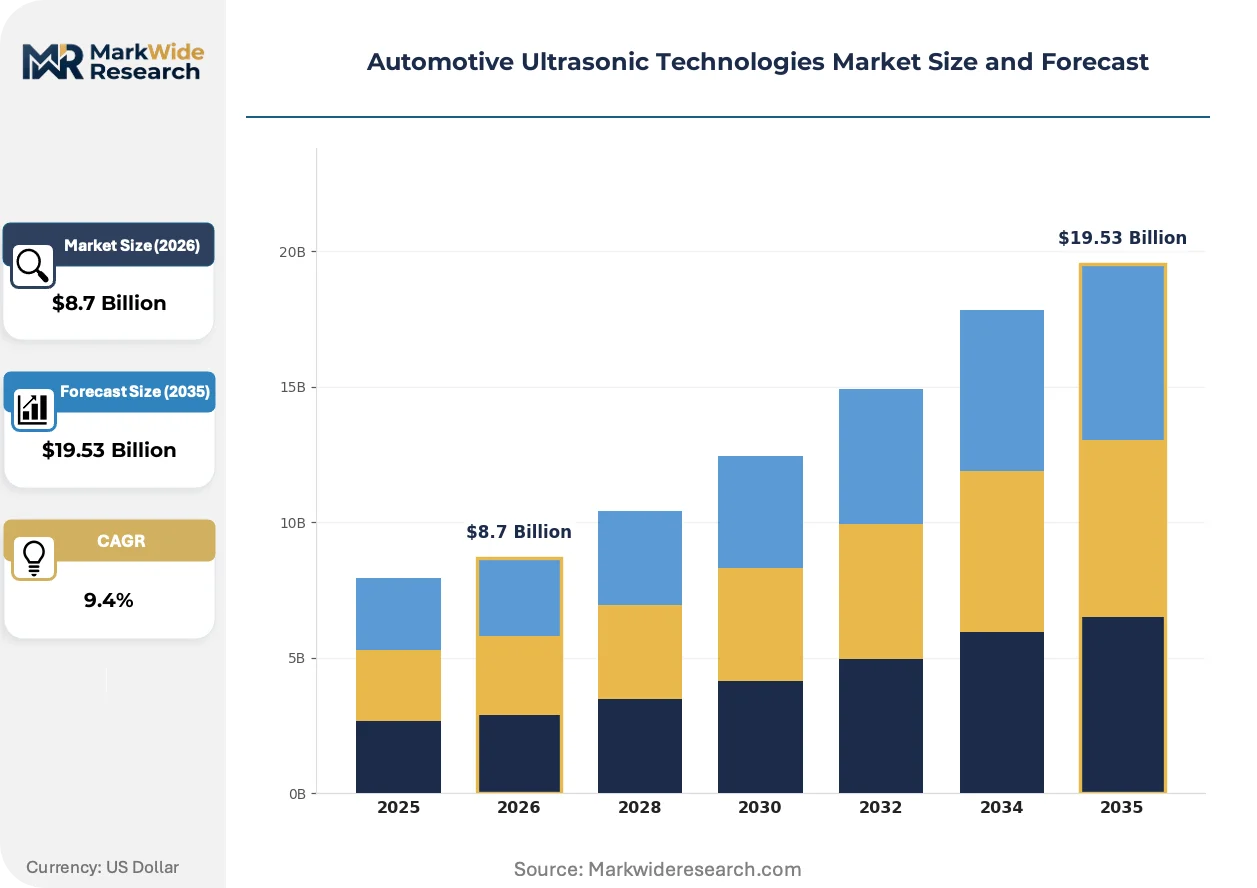
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Ultrasonic Actuators, Ultrasonic Cleaning Systems, Ultrasonic Welders Application: Collision Detection, Parking Assistance, Blind Spot Monitoring, Advanced Driver Assistance Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Ultrasonic Imaging, Pulse Echo Technology, Through-Transmission Technology, Frequency Modulation |
| Companies Covered | Valeo SA, Hyundai Mobis Co. Ltd, Robert Bosch GMBH, Texas Instruments Inc, Magna International Inc, Continental AG, Aisin Corporation, Elmos Semiconductor AG, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ultrasonic Technologies Market Emerging Trajectories
Acoustic sensing modalities are bifurcating into commodity parking assistance and precision perception layers, with signal processing intelligence migrating from distributed ECUs to domain controllers.
Air-coupled ultrasonic transducer arrays are fragmenting the traditional single-point sensor paradigm. Multi-element phased arrays now enable beam steering without mechanical articulation, permitting OEMs to reduce part counts while expanding coverage zones. Tier-1 integrators are adopting these configurations first in premium electric vehicle platforms where packaging space constraints are most severe.
EU General Safety Regulation requirements for reversing detection and intelligent speed assistance are compressing compliance timelines for vehicle homologation. The regulation mandates uniform performance standards across vehicle classes, compelling suppliers to standardize firmware architectures rather than maintaining market-specific variants. Japanese OEMs exporting to Europe are accelerating their adoption of unified sensor calibration protocols to streamline type approval processes.
Fleet operators are consolidating sensor procurement under multi-year platform agreements that bundle ultrasonic hardware with predictive maintenance analytics. Commercial vehicle lessors in North America are displacing transactional component purchasing with integrated sensing subscriptions that include remote diagnostics and over-the-air performance optimization. This model concentrates buyer power among a handful of national fleet management companies while marginalizing traditional distributor networks.
Automotive Ultrasonic Technologies Market Segmentation
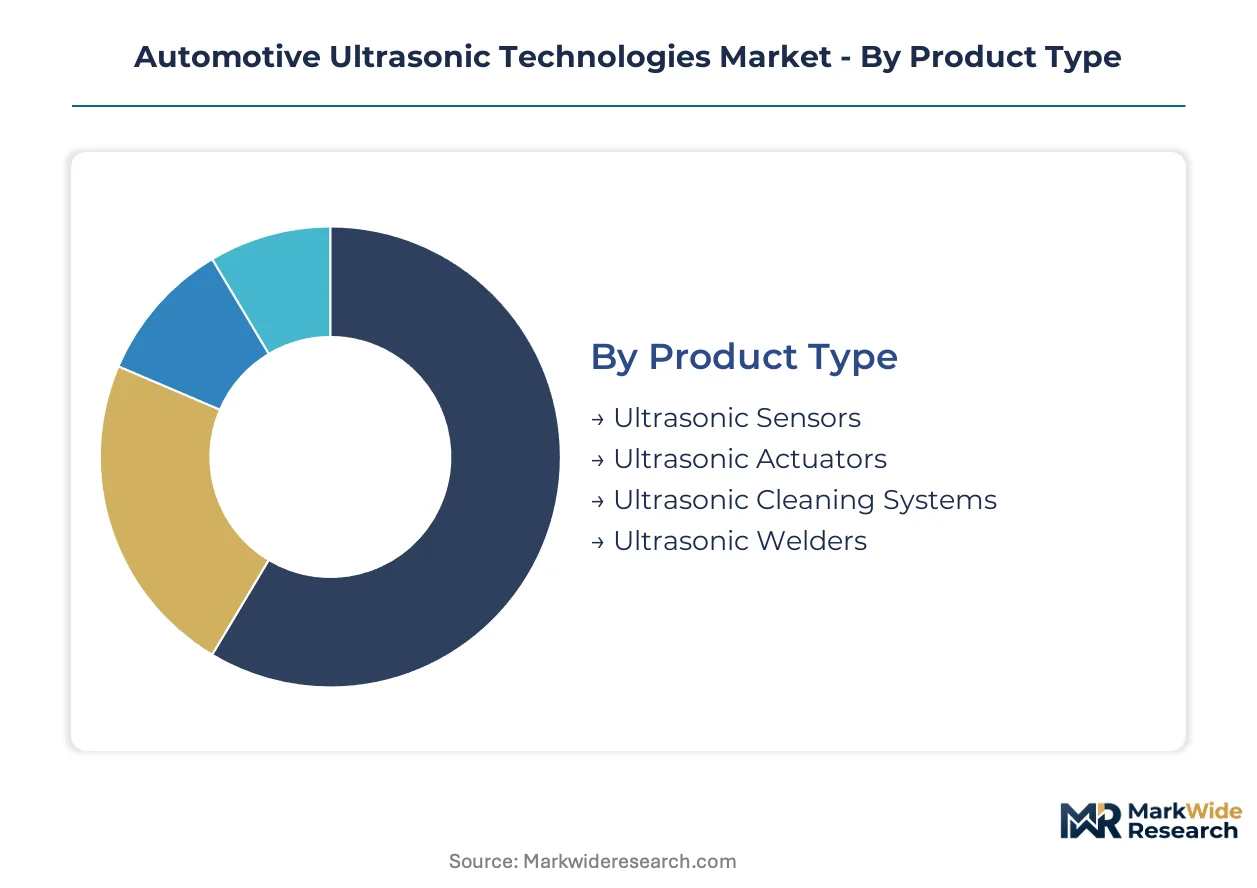
Automotive ultrasonic technologies fragment across hardware form factors, signal processing methods, and supply chain tiers. Each dimension carries distinct certification requirements and margin structures that shape supplier positioning.
Product Type:
CE marking under the EU Radio Equipment Directive and NHTSA rear visibility mandates differentiate compliance burdens across hardware categories, with sensing elements facing stricter EMC validation than actuation components.
- Ultrasonic Sensors:Piezoelectric transducers operating at 40-58 kHz dominate unit economics, with lead zirconate titanate ceramic cores sourced primarily from East Asian foundries. Parking assistance and collision detection modules in German and Japanese OEM programs drive procurement concentration for these components.
- Ultrasonic Actuators:Electromechanical conversion devices enable haptic feedback and active grille shutter control, with demand concentrating in premium electric vehicle platforms from Stuttgart and Munich manufacturers seeking reduced mechanical complexity.
- Ultrasonic Cleaning Systems:High-frequency cavitation units serve manufacturing line applications for component surface preparation, with Tier-1 suppliers in the United States adopting these for sensor module pre-assembly cleaning protocols.
- Ultrasonic Welders:Thermoplastic bonding equipment supports bumper fascia integration of sensor housings, with adoption concentrated among vehicle assemblers in Mexico serving North American OEM export programs.
Established volume favors Ultrasonic Sensors; emerging adoption favors Ultrasonic Actuators.
Application:
Cost tier stratification separates mandated fitment from discretionary premium features, with baseline parking assistance commanding lower per-unit pricing than integrated ADAS bundles.
- Collision Detection:Near-field object recognition systems trigger automatic emergency braking interventions, with NHTSA mandates standardizing fitment across light vehicle classes in the United States. OEMs in Japan integrate these with millimeter-wave radar for redundant coverage.
- Parking Assistance:Distance measurement arrays using pulse echo technology represent the most mature application, with EU General Safety Regulation requirements for reversing detection expanding mandatory scope across vehicle segments.
- Blind Spot Monitoring:Side-object detection configurations employ frequency modulation waveforms for improved resolution, gaining traction in premium segments from German manufacturers specifying multi-sensor arrays per vehicle.
- Advanced Driver Assistance Systems:Multi-modal fusion architectures combine ultrasonic layers with camera and radar inputs, with Tier-1 suppliers bundling ECU software and sensor hardware under long-term platform agreements.
Revenue concentration sits with Advanced Driver Assistance Systems; unit volume leadership remains with Parking Assistance.
End User:
Supply chain position determines technical specification authority, with OEMs retaining architecture control while delegating module integration to Tier-1 partners.
- OEMs:Original equipment manufacturers in Germany, Japan, and the United States define sensor count specifications and calibration protocols, with premium segments demanding twelve-plus ultrasonic units per vehicle.
- Tier-1 Suppliers:Module integrators such as Robert Bosch GMBH and Valeo SA combine transducer hardware with signal conditioning electronics and embedded firmware, managing ISO 26262 functional safety qualification timelines.
- Aftermarket Providers:Independent service networks in Brazil and Mexico deploy universal retrofit kits for vehicle parcs lacking factory-installed proximity systems, bypassing OEM procurement channels.
- Vehicle Assemblers:Contract manufacturing facilities in India leverage PLI scheme incentives for advanced driver assistance hardware assembly, serving domestic OEMs and export markets simultaneously.
Procurement authority concentrates with OEMs; volume expansion is climbing the fastest among Aftermarket Providers.
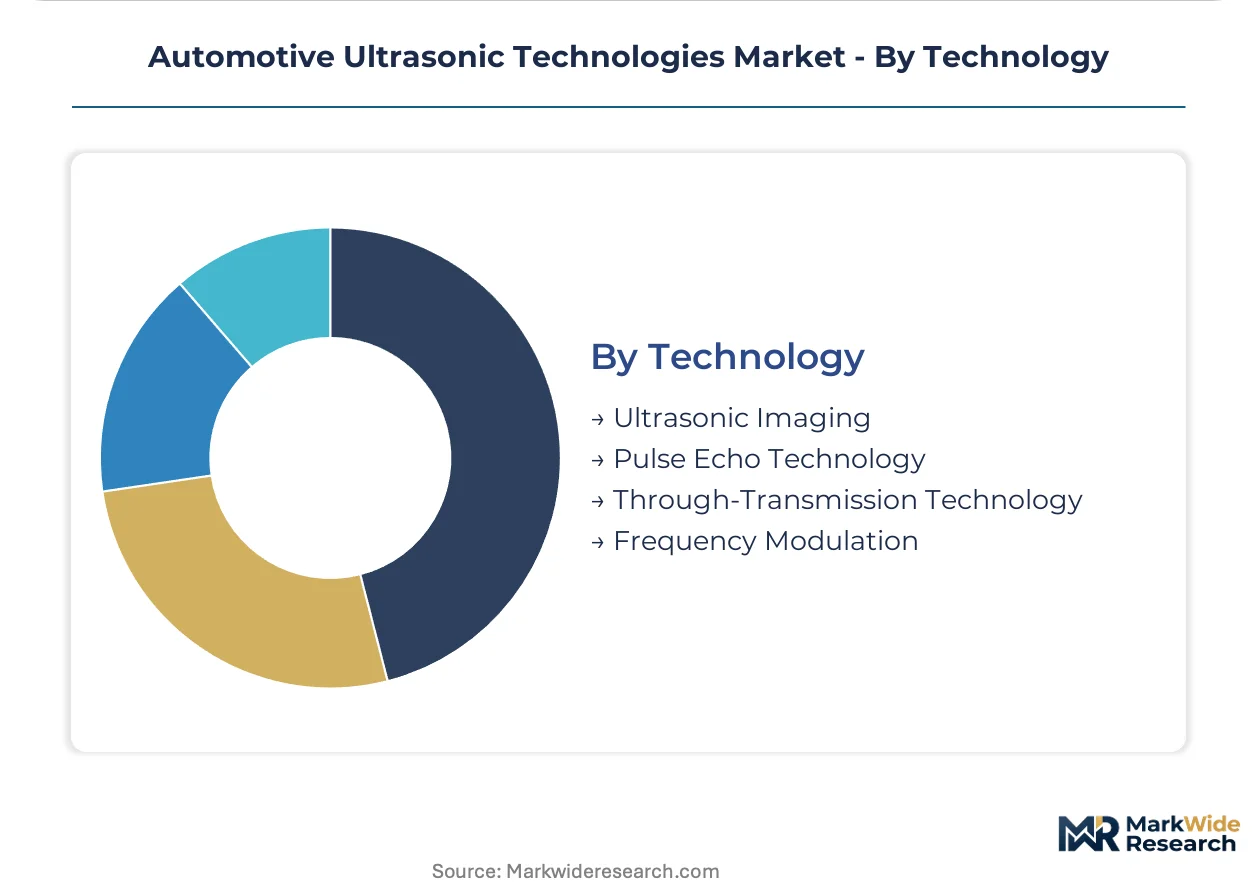
Technology:
Maturity gradients separate established pulse-based methods from emerging waveform encoding approaches, with signal processing intelligence migrating from distributed ECUs to centralized domain controllers.
- Ultrasonic Imaging:Phased array beam steering without mechanical articulation enables reduced part counts, with premium electric vehicle platforms from German manufacturers adopting these configurations first due to packaging constraints.
- Pulse Echo Technology:Time-of-flight measurement at 40-58 kHz retains the largest installed base, with standardized firmware architectures replacing market-specific variants to streamline EU type approval processes.
- Through-Transmission Technology:Opposed sensor pairs measure acoustic attenuation for material characterization, with limited automotive adoption concentrated in quality control applications during manufacturing.
- Frequency Modulation:FM-coded waveforms combined with edge-based machine learning inference open resolution capabilities previously reserved for radar, with Japanese OEMs exporting to Europe accelerating unified calibration protocol adoption.
Installed base dominance belongs to Pulse Echo Technology; technical migration favors Frequency Modulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German premium OEMs and Japanese vehicle assemblers concentrate procurement authority for ultrasonic modules, while Tier-1 suppliers in Stuttgart and Nagoya negotiate multi-year platform agreements. Fleet operators in the United States are consolidating sensor purchasing under integrated sensing subscriptions.
United States
NHTSA mandates on rear visibility and automatic emergency braking have standardized ultrasonic fitment across light vehicle classes. The regulator's compliance timelines compress homologation schedules for parking assistance modules. Detroit-area OEMs specify multi-sensor arrays per vehicle, driving per-unit counts above eight units in mid-range segments.
Germany
EU General Safety Regulation requirements for reversing detection and intelligent speed assistance expand mandatory fitment scopes. KBA type approval processes condition market access for non-European suppliers. Stuttgart and Munich manufacturers anchor procurement concentration, with premium segments demanding twelve-plus ultrasonic units per vehicle.
Japan
METI industrial policy supports domestic sensor module production for export-oriented OEM programs. JIS standards govern electromagnetic compatibility validation for automotive ultrasonic components. Nagoya-based Tier-1 integrators manage ISO 26262 functional safety qualification timelines for European market entry.
India
PLI scheme production-linked incentives for advanced driver assistance hardware attract module assembly investments. BIS certification requirements shape compliance pathways for domestic OEM sourcing. Tamil Nadu and Gujarat vehicle assemblers leverage incentive structures to serve export markets simultaneously.
South Korea
MFDS regulatory frameworks align with international EMC standards for automotive component validation. Domestic OEMs integrate ultrasonic layers with camera and radar inputs for multi-modal ADAS architectures. Seoul Capital Area module suppliers negotiate long-term platform agreements with German and US automakers.
Automotive Ultrasonic Technologies Market Vendor Landscape
Player mix skews toward diversified Tier-1 automotive suppliers with in-house semiconductor capabilities. The vendor base concentrates around module integrators combining transducer hardware with signal conditioning electronics and embedded firmware. Two strategic archetypes dominate: diversified automotive component conglomerates with captive sensor production, and specialized semiconductor suppliers providing analog front-end ICs. Competitive moves center on ISO 26262 ASIL certification acceleration and backward integration into piezoelectric ceramic manufacturing.
Within the diversified Tier-1 tier, Robert Bosch GMBH and Valeo SA exemplify archetypes controlling cost positions through in-house capabilities. Texas Instruments Inc occupies a position among semiconductor specialists providing dedicated ultrasonic analog front-end ICs. Hyundai Mobis Co. Ltd anchors the Asia-Pacific supplier vector. Continental AG and Denso Corporation sit within the established module integrator cluster.
| Leading Market Players |
|---|
| Valeo SA |
| Hyundai Mobis Co. Ltd |
| Robert Bosch GMBH |
| Texas Instruments Inc |
| Magna International Inc |
| Continental AG |
| Aisin Corporation |
| Elmos Semiconductor AG |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization rates above 85 percent at East Asian lead zirconate titanate foundries create asymmetric pricing power for ceramic core suppliers, compressing module assembler margins while establishing floor prices for European Tier-1 integrators serving Stuttgart and Munich OEM programs.
Pricing Analysis
Cost-plus contracts indexed to lead zirconate titanate ceramic feedstock prices dominate procurement between East Asian foundries and European module makers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262 ASIL-D certified units from baseline parking assistance modules and aftermarket retrofit kits. Pricing pressure stems from LiDAR substitution in premium automated parking applications, with German OEMs demanding sensor count reductions. Aftermarket providers in Brazil and Mexico exhibit highest price sensitivity, while luxury German manufacturers remain least sensitive due to bundled ADAS platform economics.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane elevate inbound logistics costs for European module assemblers dependent on East Asian ceramic inputs. Manufacturing concentrates in China, Japan, and Germany, with lead zirconate titanate ceramics, analog front-end ICs, and ECU firmware constituting critical dependencies. Single-source vulnerability concentrates in East Asian piezoelectric material production, exposing Bosch and Valeo supply chains to geopolitical friction. Distribution runs through OEM captive networks and Tier-1 platform agreements, with aftermarket channels gaining share in Latin American retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
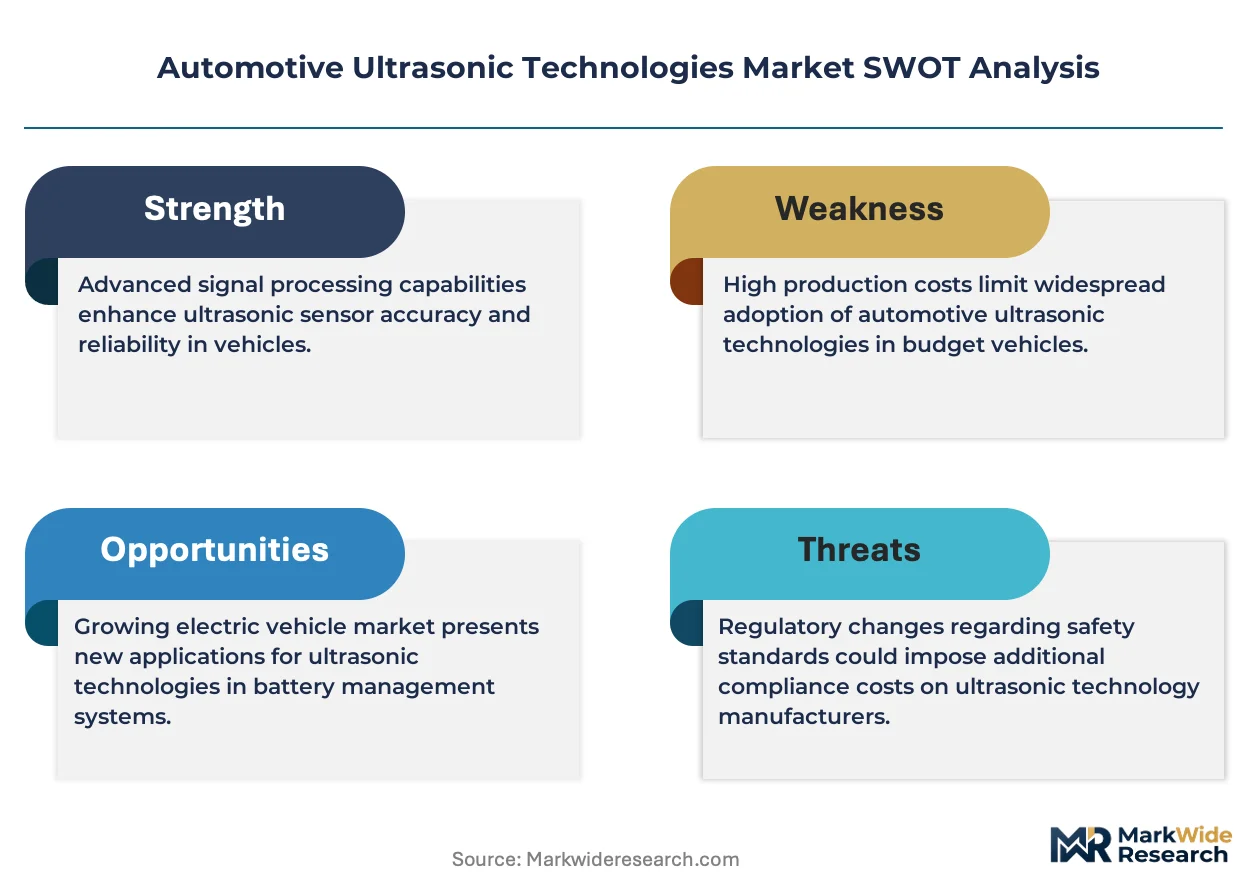
Qualified ISO 26262 firmware engineers and in-house piezoelectric ceramic production capabilities constitute the binding constraints separating viable competitors from margin-challenged assemblers in this market.
For Market Incumbents: Compound defensive positioning through backward integration into lead zirconate titanate ceramic manufacturing and accelerated ASIL-D certification timelines to outpace emerging semiconductor specialists. LiDAR substitution in premium segments threatens parking assistance module volumes, requiring capacity reallocation toward frequency modulation architectures for blind spot monitoring applications. For New Entrants and Emerging Players: Differentiate on edge-based machine learning inference for frequency modulation waveforms, targeting the India PLI scheme assembly corridor where domestic OEM sourcing lacks established Tier-1 relationships. Aftermarket retrofit channels in Brazil and Mexico offer the most penetrable entry vector, with universal parking assistance kits bypassing OEM procurement gatekeepers through independent service networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors module integrators with captive semiconductor packaging capabilities and established European type approval pathways. Long-term viability hinges on software-defined vehicle architecture adaptation, with acquisition targets clustering among analog front-end IC specialists and phased array transducer developers. Watch for NHTSA mandate expansion beyond rear visibility as the inflection signal for sensor count acceleration across mid-range vehicle segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Manufacturing | Captive lead zirconate titanate supply insulates Bosch and Valeo from East Asian feedstock volatility. |
| ISO 26262 ASIL-D Certification Acceleration | Shortened functional safety timelines enable faster platform wins with Stuttgart and Munich OEMs. |
| Frequency Modulation Waveform Development | FM-coded ultrasonic layers displace radar in blind spot monitoring for German premium segments. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu and Gujarat assembly positions serve domestic OEMs and European export markets simultaneously. |
| Software-Defined Vehicle Architecture Adaptation | Ethernet-based zonal compute compatibility preserves Tier-1 relevance amid centralized domain controller migration. |
Methodological Framework
Cross-validation between Tier-1 supplier procurement data and OEM platform engineering specifications anchors the qualitative findings in this analysis. Primary interviews with automotive platform engineers, Tier-1 module procurement leads, aftermarket distribution network managers, and semiconductor analog design directors combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA regulatory filings, and EU General Safety Regulation implementation guidance. Bottom-up sensor unit economics and top-down ADAS content per vehicle trajectories undergo iterative reconciliation.
Sensitivity analysis around LiDAR substitution rates, lead zirconate titanate price volatility, and software-defined vehicle adoption timelines shapes the forecast framework. Segmentation dimensions span product type, application, technology, and end user, with vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster constituting automotive-specific modeling layers. CAGRs derive from fitted growth curves against historical fitment rate trajectories, with NHTSA mandate compliance schedules and EU General Safety Regulation phase-in dates serving as structural anchors.
Forecasts assume regulatory continuity in NHTSA and EU General Safety Regulation regimes; material policy shifts would require re-modeling. Technology substitution risks from solid-state LiDAR, supply chain disruptions in East Asian ceramic foundries, and software-defined vehicle architecture acceleration constitute primary revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Automotive Smart Antenna Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
India ECU Market
Automotive Electronics & Wiring
Australia Automotive Camera Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Global Phone Car Mounts Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market