
 Driveline Control Systems and Devices Market | 2026-2036
Driveline Control Systems and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Driveline Control Systems and Devices Market Foresight
Fleet operators are collapsing their historical preference for mechanical driveline controls in favor of integrated electronic architectures. Robert Bosch GmbH leverages its embedded software competency to dominate torque-vectoring controllers. Continental AG anchors European supply through captive semiconductor sourcing. Denso Corporation specializes in compact actuator designs for hybrid powertrains.
Driveline control systems and devices encompass torque management hardware, clutch actuators, differential controllers, and stability modules operating across voltage classes from 12V to 800V in electrified platforms. These systems govern power distribution between axles and wheels to optimize traction, efficiency, and vehicle dynamics under variable load conditions. Active Control Systems capture the dominant margin pool as OEMs spec multi-clutch torque vectoring for premium platforms. Electrical Systems within the technology dimension outpace mechanical alternatives as 48V mild-hybrid architectures proliferate. Aftermarket Providers face compressed service intervals as sealed electronic units replace serviceable mechanical components.
NHTSA stability mandates, EPA emissions benchmarks, and EU Green Deal fleet-average CO2 targets collectively force hardware-software integration at the driveline layer. ECE R13-H braking and stability regulations in Europe and FMVSS 126 in the United States define minimum performance thresholds for electronic stability control deployment across vehicle classes. Stakeholders must monitor how cybersecurity certification under UNECE R155 reshapes supplier qualification timelines and architecture choices.
Market Dynamics
Electrification voltage tiers from 48V mild-hybrid to 800V full-electric architectures are fragmenting control system specifications and forcing suppliers to maintain parallel development tracks across incompatible electrical domains.
Growth Catalysts
- NHTSA FMVSS 126 mandates:Heavy-duty vehicle stability control requirements in the United States expand addressable hardware volumes for electronic modules across commercial fleets.
- EU Green Deal fleet-average CO2 targets:OEMs deploy torque-vectoring differentials and multi-clutch architectures to recover efficiency losses from electrification weight penalties.
- Semiconductor integration:Silicon carbide power electronics enable faster actuator response times, improving traction control precision in high-torque electric powertrains.
Market Restraints
- Neodymium and dysprosium price volatility:Rare earth magnet costs in electric motor actuators create margin compression for driveline control suppliers locked into fixed-price OEM contracts.
- Foundry concentration in Taiwan and South Korea:Automotive-grade microcontroller supply bottlenecks extend lead times for differential controller production.
- Thermal management limitations:Power electronics packaging constraints restrict continuous torque vectoring duty cycles in 800V architectures below commercial vehicle load requirements.
Strategic Opportunities
- Software-defined vehicle architectures:Centralized domain controllers create openings for torque management algorithms to displace discrete hardware modules.
- India's PLI scheme for automotive components:Localized production incentives attract driveline control assembly for domestic commercial vehicle and export markets.
- UNECE R155 cybersecurity certification:Mandatory security-by-design requirements favor suppliers with embedded cryptography competency in controller firmware development.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates among Tier-1 suppliers, constraining validation capacity for new market entrants.
- Legacy CAN bus integration friction:Mixed-voltage platforms must bridge 12V mechanical systems with 800V electrified architectures without protocol translation failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driveline Control Systems and Devices Market |
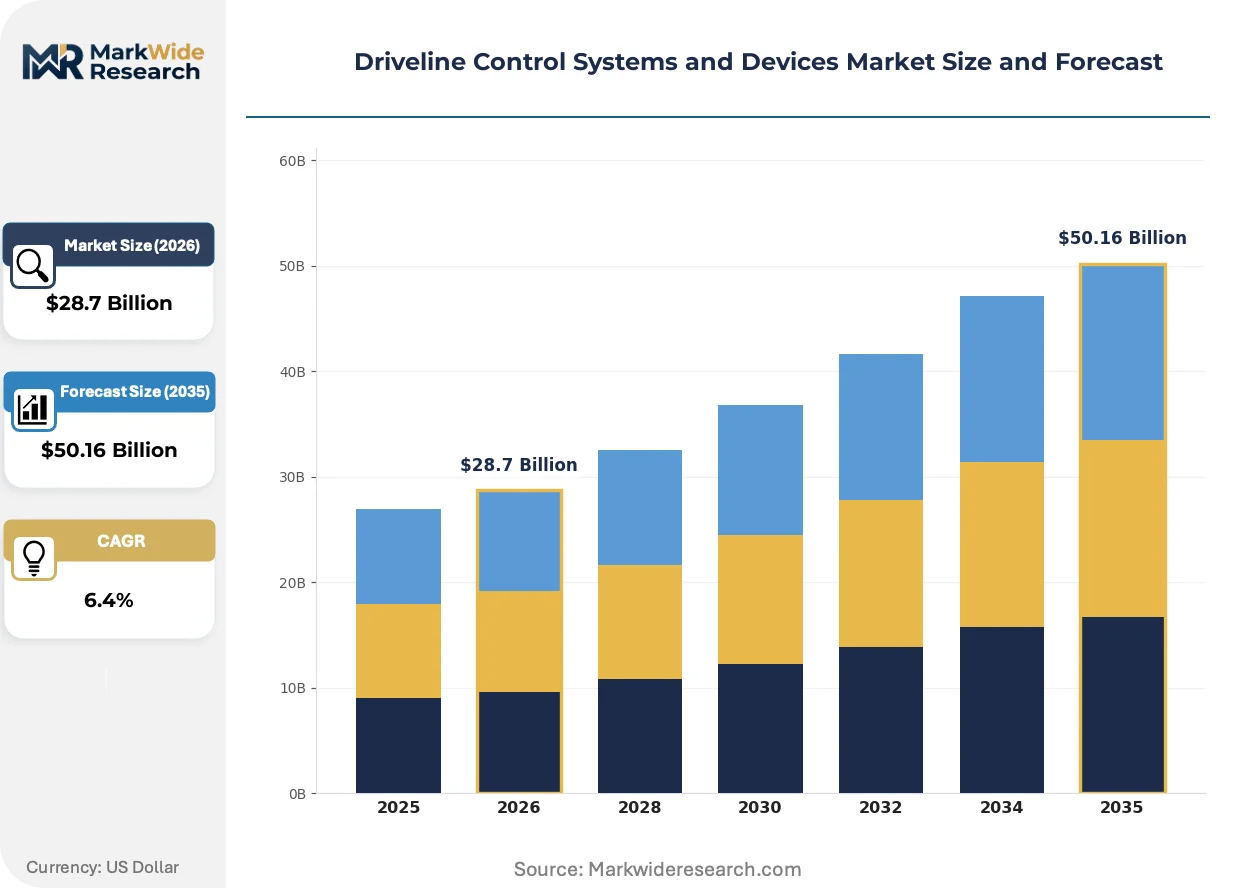
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Control Systems, Passive Control Systems, Electronic Stability Control, Differential Locking Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Off-Road Vehicles Technology: Mechanical Systems, Electrical Systems, Hydraulics, Advanced Driver-Assistance Systems End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers |
| Companies Covered | Continental AG, Denso Corporation, Robert Bosch GmbH, GKN Automotive, Schaeffler AG, BorgWarner Inc., ZF Friedrichshafen AG, Nexteer Automotive, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driveline Control Systems and Devices Market Shifts & Advancements
Control system architectures are migrating from distributed electromechanical units toward consolidated domain controllers, compressing supplier tiers and reallocating value capture toward software-integrated hardware stacks.
Multi-physics simulation platforms are decomposing traditional hardware prototyping cycles for clutch actuators and differential controllers. Tier-1 suppliers now validate torque vectoring algorithms through virtual vehicle dynamics modeling before physical commissioning. This approach compresses development timelines and reduces late-stage calibration failures in integrated driveline modules.
EPA emissions benchmarks for medium and heavy-duty vehicles are tightening hardware-software co-design requirements. Engine control and driveline management systems must now optimize jointly for CO2 and NOx targets across transient load cycles. Powertrain divisions in Detroit and Stuttgart are merging controller development teams to meet combined efficiency mandates.
Fleet procurement departments now specify total cost of ownership metrics rather than unit hardware pricing for stability control retrofits. Leasing companies and logistics operators in Germany's Rhine-Ruhr corridor bundle predictive maintenance software with hardware installations. This shifts supplier relationships from component sales toward performance-guaranteed service agreements spanning vehicle lifecycles.
Driveline Control Systems and Devices Market Segmentation
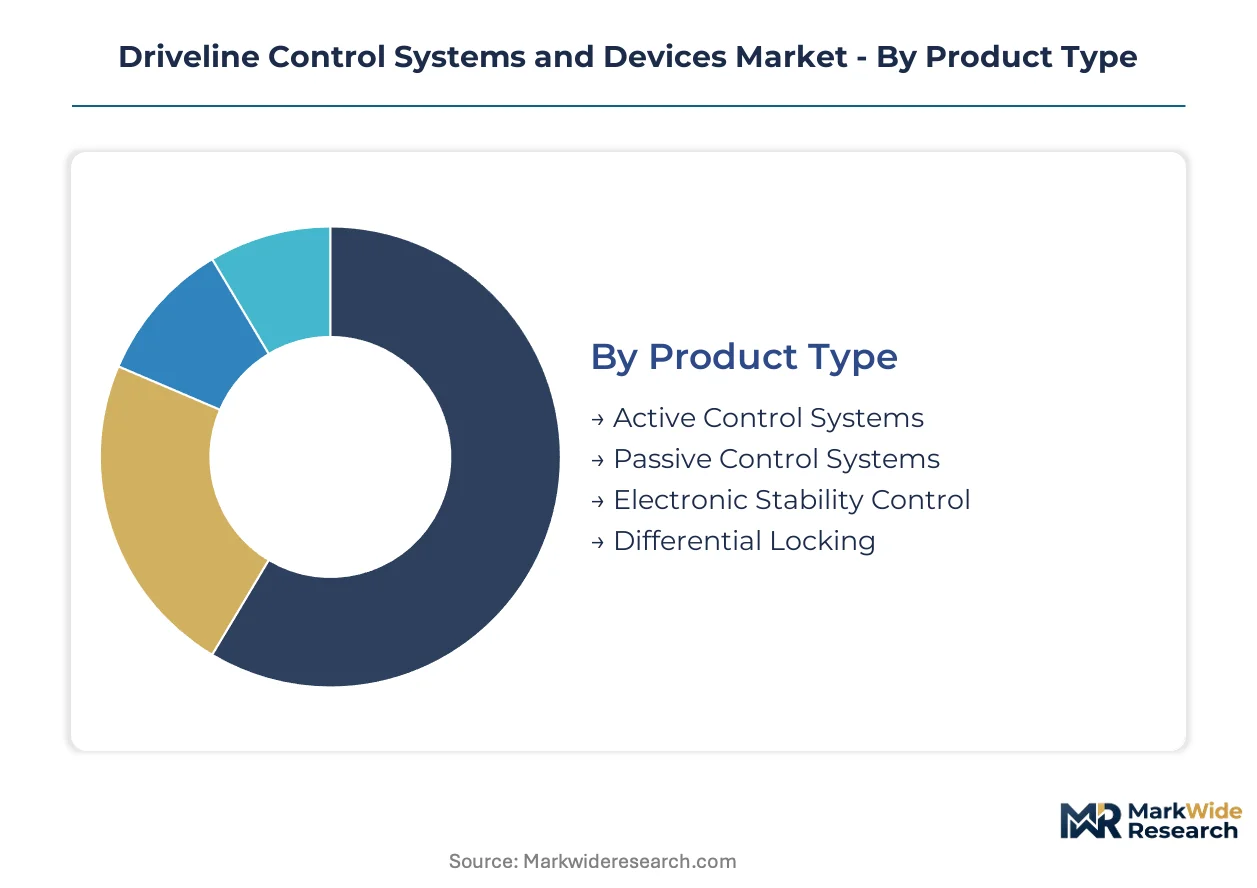
Driveline control architectures fragment across voltage classes and duty cycles, forcing suppliers to maintain parallel qualification tracks. Channel strategy diverges sharply between sealed electronic modules for OEM assembly lines and serviceable mechanical units for aftermarket retrofit. Understanding segment boundaries reveals where margin pools concentrate versus where volume commoditization threatens returns.
Product Type:
Channel mix splits between multi-year OEM supply agreements for integrated electronic stacks and spot-market procurement for mechanical replacement parts. Active Control Systems and Electronic Stability Control dominate OEM direct channels, while Passive Control Systems and Differential Locking flow heavily through distributor networks serving independent repair facilities.
- Active Control Systems:Multi-clutch torque vectoring hardware with embedded position sensors and real-time calibration firmware. Demand concentrates in Germany's premium passenger vehicle platforms where NHTSA FMVSS 126 compliance mandates drive specification of electronic stability modules with predictive load sensing.
- Electronic Stability Control:Yaw-rate sensors combined with brake-actuated traction management processors operating across 12V to 48V architectures. Fleets in the United States commercial vehicle corridor specify these modules under federal heavy-duty stability mandates, compressing retrofit timelines for legacy mechanical systems.
- Passive Control Systems:Limited-slip differentials and viscous couplings without electronic actuation serve emerging market price-sensitive segments and legacy fleet maintenance.
- Differential Locking:Electromechanical and pneumatic engagement mechanisms for off-road and heavy machinery applications requiring manual or automated terrain response.
By volume, Passive Control Systems leads through replacement cycle density in aging commercial fleets. By growth pace, Active Control Systems is ahead as electrified platforms demand precision torque management.
Application:
Cost tier stratification separates premium integrated stacks from economy mechanical alternatives, with mid-tier hybrid architectures capturing expanding share. Passenger Vehicles and Commercial Vehicles anchor development investment, while Heavy Machinery and Off-Road Vehicles operate on extended refresh cycles with specialized durability requirements.
- Passenger Vehicles:Integrated domain controllers consolidating driveline, braking, and steering functions under centralized software architectures. European OEMs in Stuttgart and Munich specify multi-clutch vectoring systems to recover efficiency losses from battery weight penalties under EU Green Deal fleet-average CO2 targets.
- Commercial Vehicles:Heavy-duty stability modules with CAN bus integration for tractor-trailer articulation management. United States fleet operators face NHTSA mandates requiring electronic stability control retrofit across Class 8 trucks, accelerating hardware replacement cycles.
- Heavy Machinery:High-torque hydraulic actuators and sealed electronic controllers for construction and mining equipment operating in contaminated environments.
- Off-Road Vehicles:Ruggedized differential locking and terrain-selectable traction systems for agricultural and recreational applications with intermittent high-load duty cycles.
By volume, Commercial Vehicles leads through fleet-scale procurement and regulatory retrofit mandates. By margin contribution, Passenger Vehicles is climbing the fastest as software-integrated stacks capture value from centralized vehicle architectures.
Technology:
Volume concentration favors Electrical Systems as 48V mild-hybrid architectures proliferate, though Mechanical Systems retain replacement demand in legacy fleet maintenance. Maturity curves diverge sharply between established hydraulic actuation and emerging ADAS-integrated predictive control.
- Electrical Systems:Brushless DC actuators, silicon carbide power electronics, and position-feedback sensors operating from 48V to 800V. Germany's automotive engineering corridor drives specification of these systems for torque-vectoring precision in electrified powertrains.
- Advanced Driver-Assistance Systems:Sensor fusion platforms integrating camera, radar, and vehicle dynamics data for predictive traction management. United States premium OEMs deploy these architectures to satisfy NHTSA stability performance thresholds while enabling over-the-air calibration updates.
- Mechanical Systems:Cable-actuated clutch controls and viscous limited-slip differentials serving price-sensitive segments and aftermarket replacement channels.
- Hydraulics:High-pressure fluid actuation for commercial vehicle and heavy machinery applications requiring sustained torque capacity beyond electric motor thermal limits.
By installed base, Mechanical Systems leads through decades of fleet accumulation. By expansion trajectory, Electrical Systems is gaining share fastest as voltage architecture proliferation fragments supplier qualification requirements.
End User:
Customer type determines contract structure: OEMs negotiate multi-year platform supply with engineering co-development clauses, while Fleet Operators increasingly demand performance-guaranteed service agreements spanning vehicle lifecycles. Aftermarket Providers face compressed margins as sealed electronic units reduce serviceable content.
- OEMs:Tier-1 suppliers engage in hardware-software co-development for platform-specific torque management calibration. Robert Bosch GmbH and Continental AG anchor European supply through captive semiconductor sourcing and embedded firmware competency.
- Fleet Operators:Leasing companies and logistics operators in Germany's Rhine-Ruhr corridor bundle predictive maintenance software with hardware installations, shifting procurement from unit pricing to total cost of ownership metrics.
- Aftermarket Providers:Distributor networks and independent repair facilities sourcing mechanical replacement units and retrofit electronic modules for regulatory compliance.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations procuring pre-calibrated driveline subsystems for integration into localized vehicle production.
By contract value, OEMs leads through multi-year platform supply agreements. By relationship model transformation, Fleet Operators is expanding most quickly as outcome-based procurement displaces component transactional purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's automotive logistics terminals channel precision driveline components into European OEM assembly networks. Germany's Rhine-Ruhr freight corridors distribute torque-vectoring controllers to Stuttgart and Munich engineering centers. These infrastructure assets concentrate procurement authority for 48V to 800V electrified architectures.
United States
Class 8 commercial fleets in Michigan and Ohio retrofit electronic stability modules under NHTSA FMVSS 126 mandates. The EPA tightens medium-duty emissions benchmarks, forcing hardware-software co-design between Detroit powertrain divisions and Silicon Valley domain controller specialists. Interstate 75 manufacturing corridors anchor torque management assembly for domestic pickup and heavy-duty platforms.
Germany
Premium passenger OEMs in Stuttgart specify multi-clutch vectoring systems to offset battery weight penalties under EU Green Deal fleet-average CO2 targets. ECE R13-H braking and stability regulations enforce electronic control deployment across vehicle classes. Bavaria's automotive engineering corridor hosts embedded firmware development for centralized vehicle architectures.
China
Domestic EV manufacturers in Shanghai and Shenzhen procure 800V differential controllers for high-torque electric powertrains. MIIT dual carbon goals accelerate silicon carbide power electronics adoption in driveline actuators. Yangtze River Delta foundries supply automotive-grade microcontrollers for torque management modules.
Japan
Hybrid powertrain specialists in Aichi Prefecture source compact actuator designs for 48V mild-hybrid integration. METI industrial policy supports semiconductor packaging for high-voltage control systems. Nagoya's automotive supplier cluster validates multi-physics simulation platforms for clutch calibration algorithms.
India
Commercial vehicle assemblers in Pune and Chennai expand driveline control sourcing under PLI scheme production incentives. BIS certification requirements localize electronic module assembly for domestic fleet retrofit. Tamil Nadu's automotive corridor attracts torque-vectoring controller manufacturing for export to Southeast Asian markets.
Driveline Control Systems and Devices Market Competitive Landscape
Concentration sits with diversified automotive suppliers possessing captive semiconductor sourcing and embedded firmware competency. Three to four German and Japanese conglomerates anchor OEM direct supply through multi-year platform agreements. Strategic archetypes separate software-integrated hardware stacks from mechanical replacement specialists. Competitive moves center on domain controller consolidation and cybersecurity certification capacity under UNECE R155.
Within the diversified automotive supplier tier, Continental AG, Robert Bosch GmbH, and Denso Corporation exemplify contrasting geographic and structural positioning. Continental AG represents European captive sourcing strategies. Robert Bosch GmbH anchors German embedded software competency. Denso Corporation occupies Japanese compact actuator specialization for hybrid architectures.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Robert Bosch GmbH |
| GKN Automotive |
| Schaeffler AG |
| BorgWarner Inc. |
| ZF Friedrichshafen AG |
| Nexteer Automotive |
| Hitachi |
| Others |
Supply & Pricing Matrix
Foundry-scale economies in automotive-grade microcontroller production concentrate supply leverage among Tier-1 suppliers with captive semiconductor sourcing, compressing price floors for independent module manufacturers while elevating margin capture for integrated hardware-software stacks.
Pricing Analysis
Volume-discount tiering structures dominate OEM procurement, with multi-year platform agreements commanding 15-25% unit cost reductions against spot-market mechanical replacement parts. Price differentiation hinges on ISO 26262 ASIL-D certification grade and embedded firmware customization depth. Pricing pressure intensifies in the Passive Control Systems tier as sealed electronic units displace serviceable mechanical components in fleet retrofit cycles. Fleet Operators exhibit highest price sensitivity due to total cost of ownership procurement mandates, while premium Passenger Vehicle OEMs prioritize performance-guaranteed service agreements over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for automotive microcontrollers, while Germany concentrates precision actuator manufacturing and embedded firmware development. Raw material dependencies span silicon carbide substrates, neodymium-dysprosium rare earth magnets, and high-temperature epoxy packaging compounds. Single-source vulnerability concentrates in 800V power electronics packaging capacity below commercial vehicle thermal load thresholds. Distribution runs through captive Tier-1 supplier networks directly into OEM assembly plants, with aftermarket channels fragmenting across regional distributor networks serving independent repair facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Driveline Control Systems and Devices Market enters a cyclical recovery phase as NHTSA FMVSS 126 retrofit mandates exhaust legacy fleet mechanical inventories and electrification platform launches accelerate controller replacement cycles.
For Market Incumbents: Consolidate semiconductor sourcing through backward integration into silicon carbide packaging capacity or joint ventures with Yangtze River Delta foundries. Deepen embedded firmware competency to defend against software-defined vehicle architectures displacing discrete hardware modules. Prioritize UNECE R155 cybersecurity certification investment to extend OEM qualification timelines beyond new entrant reach.
For New Entrants and Emerging Players: UNECE R155 cybersecurity certification fast-tracks offer regulatory arbitrage against incumbents burdened by legacy CAN bus integration debt. Target India's PLI scheme localized assembly incentives for commercial vehicle differential controller production serving Southeast Asian export markets. Pursue predictive maintenance software bundling with hardware installations to capture Fleet Operator outcome-based procurement contracts.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors suppliers with 48V-to-800V voltage class coverage and centralized domain controller software stacks. Long-term viability concentrates in firms bridging mechanical legacy integration with electrified architecture calibration competency. Monitor silicon carbide power electronics adoption rates in high-torque electric powertrains as inflection indicator for controller margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Electronics Integration | Enables faster actuator response in 800V architectures, improving traction control precision under NHTSA stability mandates. |
| UNECE R155 Cybersecurity Certification | Mandatory security-by-design requirements favor suppliers with embedded cryptography competency in controller firmware development. |
| India PLI Scheme Manufacturing Localization | Production incentives attract driveline control assembly for domestic commercial vehicle and Southeast Asian export markets. |
| Software-Defined Vehicle Domain Consolidation | Centralized controllers create openings for torque management algorithms to displace discrete hardware modules. |
| Predictive Maintenance Service Bundling | Fleet Operators in Germany's Rhine-Ruhr corridor shift procurement from unit pricing to lifecycle performance guarantees. |
Research Methodology
The analysis maps torque management hardware, clutch actuators, differential controllers, and stability modules across voltage classes from 12V to 800V, each validated through Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and fleet maintenance managers. Primary interview intelligence triangulates against vehicle production databases, IHS Markit registration data, SEC filings of listed automotive suppliers, and customs trade records for rare earth magnet and semiconductor imports. Bottom-up segment sizing cross-checks with top-down market reconstruction across electrification architecture penetration assumptions.
Consistency checks validate volume and value outputs against external benchmarks including NHTSA heavy-duty vehicle registration data for retrofit mandate compliance tracking and EU CO2 fleet-average performance disclosures. The analytical framework models product type, application, technology, and end user dimensions across the projection horizon, with propulsion architecture fragmentation and content per vehicle serving as primary forecast drivers. CAGRs derive from segment-level unit economics and replacement cycle compression in electrified platforms.
Underlying assumptions cover NHTSA mandate enforcement timelines, rare earth magnet price stability, and foundry capacity expansion trajectories, with deviation risk concentrated in semiconductor supply bottlenecks and thermal management packaging constraints in 800V architectures. Recalibration cycles align with material shifts in regulatory compliance deadlines and electrification platform launch schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Automotive Steering Wheel Switch Market
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Global Automotive VVT System Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market