
 Automotive V2X Antenna Market | 2026-2036
Automotive V2X Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive V2X Antenna Market Analysis
Market Context
Software-defined antenna tuning is recalibrating what automotive suppliers monetize, shifting revenue from hardware shipments to recurring calibration services and over-the-air performance updates. Continental AG leverages its integrated electronics portfolio to bundle antenna modules with telematics control units, while Qualcomm Technologies anchors its position through chipset-antenna co-design for cellular V2X platforms. Robert Bosch GmbH competes by extending its manufacturing scale across European and Asian production hubs.
Technical Definition and Segment Structure
An automotive V2X antenna is a specialized radio-frequency transducer engineered to operate across the 5.9 GHz ITS band and adjacent cellular spectra, typically fabricated from low-loss dielectric substrates with integrated low-noise amplifiers to enable vehicle-to-vehicle and vehicle-to-infrastructure communication with sub-millisecond latency. Cellular V2X antennas command premium positioning due to their dependence on 5G NR sidelink protocols and carrier certification complexity, while DSRC-based dedicated short-range communications segments face structural contraction as regulatory momentum shifts toward C-V2X standards. Fleet operators represent the fastest-growing end-user channel, driven by mandates for commercial vehicle platooning and collision-avoidance systems in mining and logistics corridors.
Regulatory Frame and Outlook
The FCC governs spectrum allocation and equipment authorization for V2X deployments in the United States, while the EU AI Act and delegated regulations on cooperative intelligent transport systems impose cybersecurity and interoperability requirements on antenna-integrated systems sold in member states. ETSI and 3GPP standards shape global product conformance, with regional divergence in DSRC versus C-V2X preference directly determining antenna architecture selection for suppliers. Stakeholders must monitor spectrum auction outcomes and cross-border harmonization negotiations to anticipate which radio configurations will secure type approval across major automotive markets.
Market Dynamics
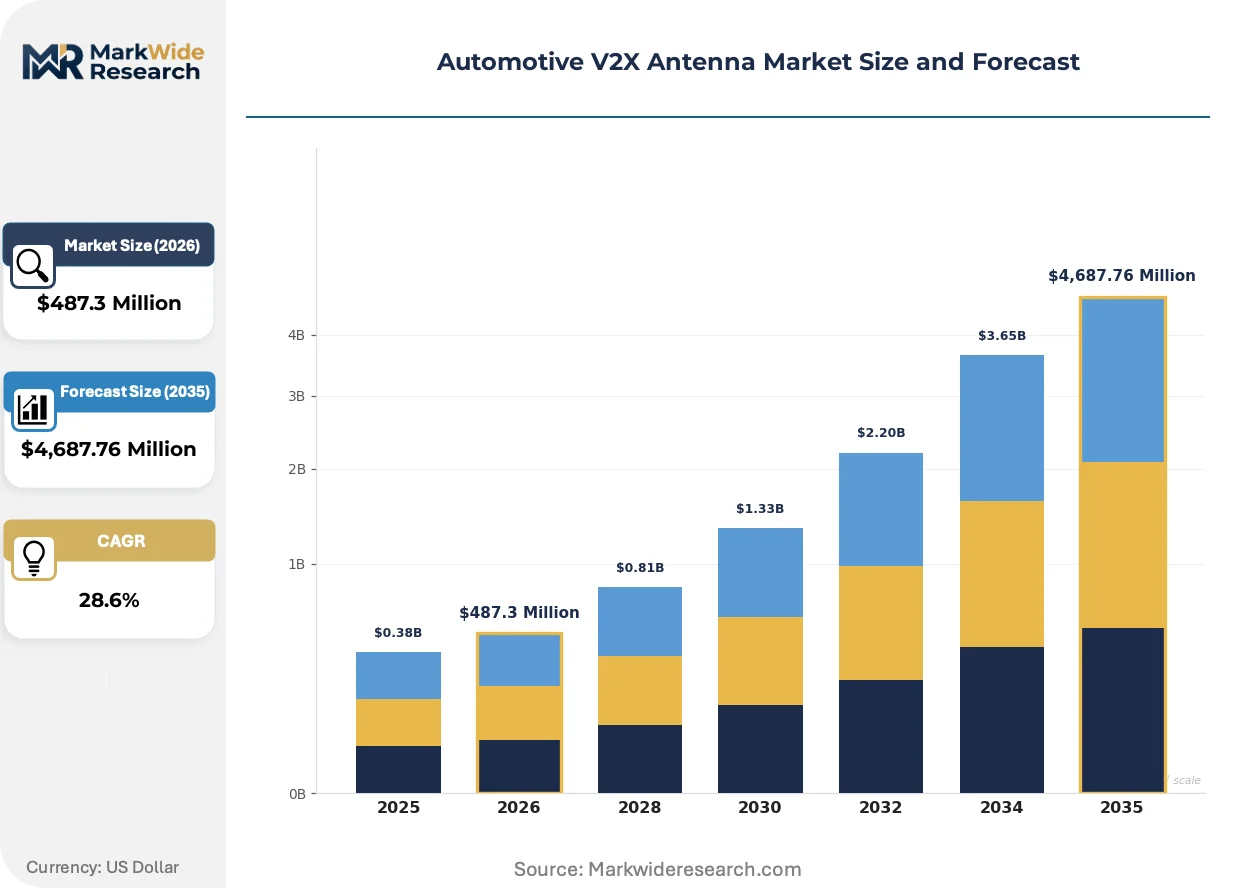
The FCC's 5.9 GHz spectrum reallocation and the EU's delegated regulation on cooperative intelligent transport systems are compressing antenna architecture timelines, forcing suppliers to dual-certify DSRC and C-V2X configurations while automotive OEMs consolidate module sourcing.
Growth Catalysts
- Cellular V2X protocol adoption:5G NR sidelink deployment by automotive OEMs is mandating multi-band antenna integration for advanced driver-assistance systems across passenger and commercial platforms.
- Fleet operator mandates:Commercial vehicle platooning requirements in mining and logistics corridors are accelerating dedicated short-range communications hardware procurement for collision-avoidance systems.
- Germany's Tier-1 integration:Automotive suppliers in Baden-Württemberg and Bavaria are embedding V2X antennas into next-generation vehicle architectures ahead of EU-wide cooperative intelligent transport system rollout.
Market Restraints
- Low-loss dielectric substrate concentration:Specialized ceramic and PTFE laminate supply chains cluster in East Asian manufacturing hubs, exposing antenna fabricators to single-source fragility.
- DSRC standard obsolescence risk:Regulatory momentum shifting toward C-V2X is stranding dedicated short-range communications R&D investments and forcing parallel development costs.
- Carrier certification complexity:5G NR sidelink approval processes through national telecommunications regulators extend product qualification timelines by 12-18 months.
Strategic Opportunities
- Software-defined antenna tuning:Over-the-air calibration services are creating recurring revenue streams as automotive suppliers monetize performance updates rather than one-time hardware shipments.
- India's automotive electronics corridor:Tamil Nadu and Karnataka state incentive schemes for automotive component manufacturing are attracting antenna module assembly investments.
- ETSI-3GPP convergence:Harmonized standards for cooperative intelligent transport systems are reducing regional variant costs for suppliers serving multiple certification regimes.
Industry Challenges
- RF engineering talent scarcity:Millimeter-wave antenna design expertise concentrates in aerospace and telecommunications sectors, complicating automotive supplier hiring.
- Multi-protocol integration complexity:Simultaneous DSRC and C-V2X support requirements are expanding firmware validation matrices and test automation capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive V2X Antenna Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $4,687.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dedicated Short-Range Communications, Cellular V2X, Satellite Antennas, Multi-band Antennas Technology: 5G, LTE, DSRC, WLAN End User: Vehicle Manufacturers, Fleet Operators, Government Authorities, Telecom Providers Application: Safety Communication, Traffic Management, Infotainment, Remote Vehicle Monitoring |
| Companies Covered | Ficosa Internacional SA, HARMAN International, Continental AG, Laird Connectivity, Qualcomm Technologies, Denso Corporation, Robert Bosch GmbH, Huawei Technologies, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive V2X Antenna Market Emerging Trajectories
Antenna module architecture is pivoting from passive hardware to active electronically steered systems, with software control displacing fixed-beam designs and automotive OEMs demanding chipset-antenna co-design capabilities from suppliers.
Metamaterial-engineered substrates with artificial magnetic conductor layers are rewriting thermal and electrical performance trade-offs for 5.9 GHz ITS band operation. Tier-1 suppliers in Germany and Japan are qualifying these substrates for 2027 vehicle programs. The technology is compressing form-factor requirements while maintaining gain specifications, enabling roofline integration without shark-fin protrusions.
The EU AI Act's cybersecurity requirements for cooperative intelligent transport systems are mandating hardware-rooted trust anchors in antenna-integrated telematics units. Automotive suppliers must demonstrate end-to-end encryption between V2X transceivers and vehicle gateways. Cellular V2X antenna modules destined for EU type approval now require security certification from notified bodies before mass production authorization.
Fleet procurement departments are consolidating antenna module sourcing through telematics platform providers rather than direct component purchasing. Commercial vehicle operators in North American and European logistics corridors now specify antenna performance through their telematics service providers. This channel shift is compressing supplier margins while elevating chipset-antenna bundle requirements for module vendors seeking fleet volume.
Automotive V2X Antenna Market Segmentation
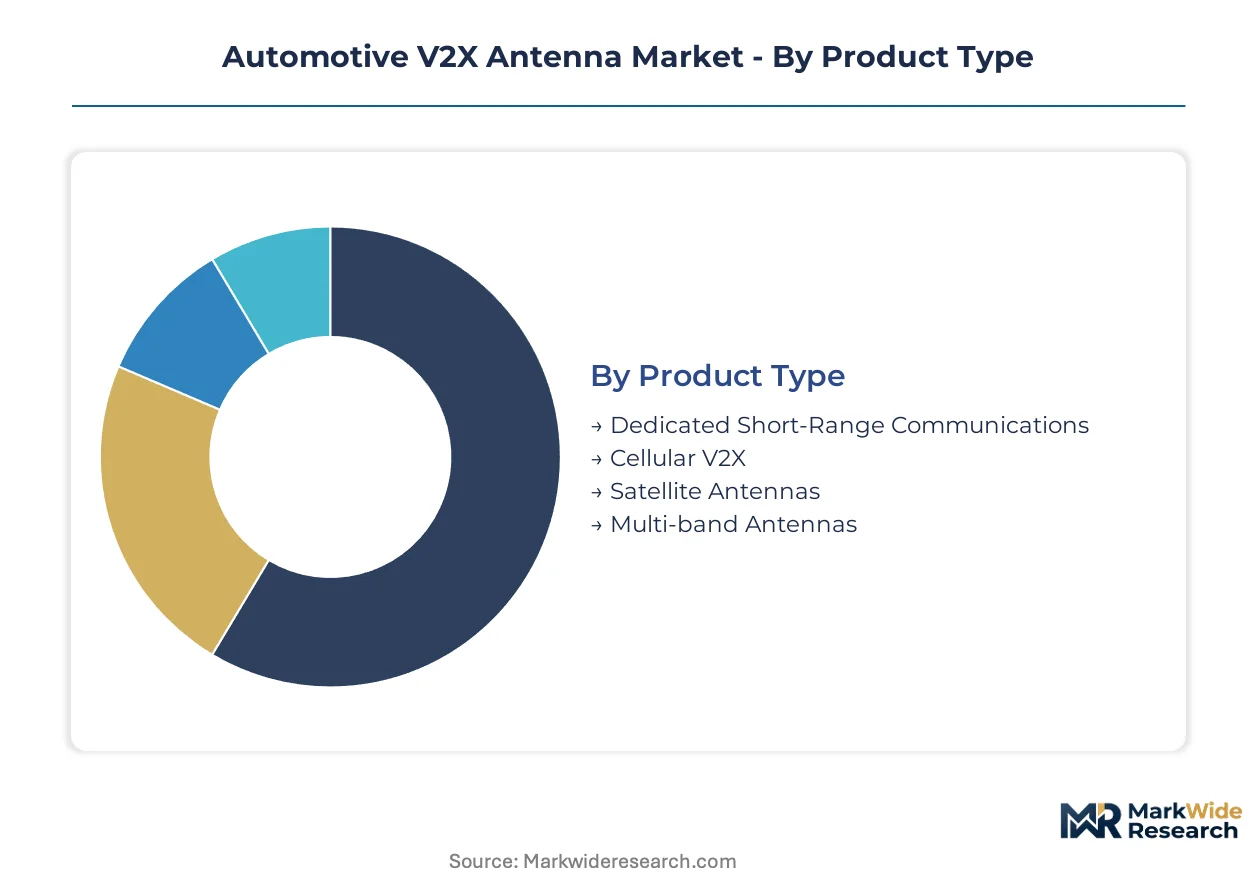
Antenna architecture selection in V2X markets hinges on integration depth—standalone modules serve retrofit fleets while embedded designs dominate OEM production lines. Understanding segment boundaries clarifies where suppliers compete on hardware margins versus recurring service revenue.
Product Type:
Integration depth separates standalone roof-mount units from embedded telematics-integrated modules, with the latter commanding design-in relationships and longer contract cycles.
- Cellular V2X:Multi-band arrays fabricated on low-loss dielectric substrates support 5G NR sidelink protocols with integrated LNAs for sub-millisecond latency. German Tier-1 suppliers in Baden-Württemberg are embedding these into next-generation vehicle architectures ahead of EU-wide cooperative intelligent transport system mandates. These modules dominate premium passenger vehicle platforms where carrier certification complexity creates supplier stickiness.
- Multi-band Antennas:Hybrid architectures combining 5.9 GHz ITS band with cellular spectra enable simultaneous DSRC and C-V2X operation during regulatory transition periods. Fleet operators in North American logistics corridors specify these for collision-avoidance systems to hedge against standard obsolescence risk. The FCC's 5.9 GHz spectrum reallocation is accelerating procurement of dual-protocol hardware.
- Dedicated Short-Range Communications:Single-protocol 5.9 GHz designs face structural contraction as regulatory momentum shifts toward C-V2X standards.
- Satellite Antennas:L-band and Ku-band modules provide redundant connectivity in remote mining corridors beyond cellular coverage.
Cellular V2X leads volumes today; multi-band antennas are gaining share fastest.
Technology:
Protocol selection determines antenna electrical specifications, with newer standards demanding active electronically steered architectures over passive fixed-beam designs.
- 5G:Millimeter-wave-capable arrays with beamforming ICs support 3GPP Release 16 sidelink for vehicle-to-vehicle direct communication without network infrastructure. Japanese automotive electronics suppliers are qualifying metamaterial-engineered substrates for these modules to compress form factors. Carrier certification timelines extend 12-18 months, creating qualification barriers for new entrants.
- DSRC:IEEE 802.11p-based implementations face stranded investment risk as the FCC reallocates 5.9 GHz spectrum and EU regulators favor cellular alternatives.
- LTE:Category M1 and NB-IoT variants serve cost-constrained fleet telematics where bandwidth requirements remain modest.
- WLAN:802.11ax modules support high-throughput infotainment backhaul in captive vehicle-area networks.
5G dominates new program wins; LTE retains installed base longevity.
End User:
Procurement authority concentration varies sharply—OEMs source through Tier-1 integrators while fleets increasingly delegate specification to telematics platform providers.
- Fleet Operators:Commercial vehicle procurement departments in mining and logistics corridors now specify antenna performance through telematics service providers rather than direct component purchasing. This channel shift elevates chipset-antenna bundle requirements while compressing standalone module margins. Platooning mandates in specific freight corridors are accelerating dedicated hardware procurement.
- Vehicle Manufacturers:Passenger and commercial OEMs consolidate module sourcing with suppliers offering integrated telematics control units. Continental AG and Robert Bosch GmbH compete through manufacturing scale across European and Asian production hubs. Design-in relationships span multi-year vehicle program cycles.
- Government Authorities:Infrastructure deployment agencies procure roadside units for vehicle-to-infrastructure corridors.
- Telecom Providers:Carriers certify antenna modules for network compatibility, extending qualification timelines.
Vehicle manufacturers lead absolute volumes; fleet operators show steepest expansion trajectory.
Application:
Latency requirements differentiate use cases—safety-critical systems demand sub-millisecond performance while infotainment tolerates higher latency for bandwidth gains.
- Safety Communication:Collision-avoidance and cooperative maneuvering systems require deterministic latency below 10 milliseconds, mandating edge-compute integration with antenna modules. EU delegated regulations on cooperative intelligent transport systems impose cybersecurity requirements that hardware-rooted trust anchors must satisfy. Type approval from notified bodies precedes mass production authorization.
- Traffic Management:Signal phase and timing data exchange enables eco-driving optimization across urban corridors.
- Infotainment:High-definition media streaming and gaming drive WLAN and cellular bandwidth consumption without hard latency constraints.
- Remote Vehicle Monitoring:Predictive maintenance telemetry operates on intermittent connectivity with store-and-forward architectures.
Safety communication anchors current deployment; traffic management is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Tier-1 supplier density contrasts with the United States' spectrum-driven procurement patterns, while China's integrated electronics manufacturing and Japan's automotive electronics precision create distinct competitive terrains for antenna module deployment.
United States
The FCC's 5.9 GHz spectrum reallocation is accelerating dual-protocol antenna procurement for collision-avoidance corridors in Arizona and Texas freight lanes. NHTSA safety mandates for commercial vehicle platooning are compressing qualification timelines for C-V2X modules. Detroit-area automotive electronics clusters are integrating software-defined antenna tuning into next-generation vehicle architectures.
Germany
Baden-Württemberg and Bavaria host concentrated Tier-1 supplier engineering centers embedding multi-band V2X antennas into 2027 vehicle programs. The EU delegated regulation on cooperative intelligent transport systems imposes cybersecurity certification requirements through notified bodies. Stuttgart's automotive electronics corridor is qualifying metamaterial-engineered substrates for roofline-integrated antenna modules.
China
MIIT spectrum allocation for cellular V2X is driving module procurement for intelligent connected vehicle pilot zones in Shanghai and Beijing. National standards for vehicle-to-everything communication are mandating domestic certification for antenna-integrated telematics units. Yangtze River Delta electronics manufacturing hubs are scaling low-loss dielectric substrate production for regional antenna fabricators.
Japan
METI funding for automated driving systems is channeling antenna module development toward 5G NR sidelink deployment in Nagoya and Tokyo metropolitan corridors. JIS standards for automotive radio equipment shape conformance requirements for multi-band arrays. Chubu region automotive electronics suppliers are qualifying beamforming IC integration for millimeter-wave-capable antenna architectures.
India
Tamil Nadu and Karnataka state PLI schemes for automotive component manufacturing are attracting antenna module assembly investments from telematics platform providers. TRAI spectrum consultations for intelligent transport systems are creating regulatory clarity for C-V2X deployment corridors. Bangalore's automotive electronics engineering clusters are developing firmware validation capabilities for multi-protocol antenna integration.
Automotive V2X Antenna Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated Tier-1 suppliers commanding design-in relationships for OEM production while component specialists serve retrofit fleet channels through telematics platform providers. The vendor base organizes around three archetypes: diversified automotive electronics conglomerates with captive antenna capabilities, RF component specialists with carrier certification expertise, and semiconductor vendors pursuing chipset-antenna co-design. Consolidation pressure is elevating M&A activity for millimeter-wave engineering talent and strategic partnerships for dual-protocol firmware development.
Among diversified automotive electronics conglomerates, Continental AG and Robert Bosch GmbH exemplify scale-driven positioning through integrated telematics control unit offerings. Qualcomm Technologies occupies the semiconductor-architecture tier, anchoring cellular V2X ecosystem development through chipset-antenna co-design relationships with module vendors. These three entities represent distinct competitive vectors—hardware integration depth, manufacturing scale, and protocol-layer control—shaping how procurement authority concentrates across passenger OEM and commercial fleet channels.
| Leading Market Players |
|---|
| Ficosa Internacional SA |
| HARMAN International |
| Continental AG |
| Laird Connectivity |
| Qualcomm Technologies |
| Denso Corporation |
| Robert Bosch GmbH |
| Huawei Technologies |
| TE Connectivity |
| Others |
Supply Flow & Price Mechanics
Millimeter-wave RF engineering talent concentration in Baden-Württemberg and Nagoya drives labor-cost differentials that widen pricing-tier spreads between premium antenna modules and economy-grade alternatives. Certification complexity for 5G NR sidelink protocols amplifies these spreads as Tier-1 suppliers capture value from scarce design expertise.
Pricing Analysis
Capacity additions in Tamil Nadu and Karnataka are reshaping price floors for standard-grade antenna modules as Indian assembly investments introduce cost-competitive alternatives to East Asian manufacturing. Three-tier pricing structure across premium, standard, and economy levels separates carrier-certified cellular V2X modules from uncertified DSRC alternatives and basic fleet telematics units. Cost compression in standard tiers is intensifying because telematics platform providers consolidate procurement authority and demand chipset-antenna bundles. Fleet operators show highest price sensitivity due to volume procurement mandates, while passenger OEMs prioritize certification grade over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized ceramic and PTFE laminate production concentrated in Japan, South Korea, and Taiwan. Low-loss dielectric substrates, beamforming ICs, and hardware-rooted trust anchor components feed from East Asian electronics manufacturing hubs. Tariff exposure on semiconductor-grade substrates creates supply chain risk as automotive OEMs dual-source for regulatory transition periods. Distribution runs through Tier-1 integrators for OEM production lines and telematics platform providers for retrofit fleet channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as fleet procurement departments shift specification authority toward telematics service providers demanding premium-grade chipset-antenna integration with cybersecurity certification.
For Market Incumbents: Hedge against DSRC standard obsolescence by maintaining parallel C-V2X development capacity while consolidating manufacturing scale across European and Asian production hubs. Carrier certification timelines extending 12-18 months create defensive moats for suppliers with established regulatory relationships. Backward integration into low-loss dielectric substrate sourcing mitigates single-source fragility from East Asian suppliers. For New Entrants and Emerging Players: Telematics platform providers represent the most accessible channel for volume penetration without direct OEM design-in relationships. India's automotive electronics corridor offers white-space opportunity for module assembly investments serving cost-constrained fleet operators. Firmware validation capabilities for multi-protocol integration provide differentiation against hardware-only competitors. For Investors and Strategic Acquirers: Semiconductor vendors pursuing chipset-antenna co-design are the most active acquirer in this space, seeking millimeter-wave engineering talent and carrier certification expertise. Targets with established notified body relationships for EU type approval command premium positioning. Watch for spectrum auction outcomes and cross-border harmonization negotiations as inflection indicators for radio configuration standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Antenna Tuning Investment | Recurring calibration services shift revenue from hardware shipments to over-the-air performance updates for Tier-1 suppliers. |
| Metamaterial-Engineered Substrate Qualification | German and Japanese suppliers compress form-factor requirements while maintaining 5.9 GHz ITS band gain specifications. |
| Carrier Certification Pre-Positioning | Early engagement with FCC and national telecommunications regulators accelerates C-V2X module approval timelines. |
| Telematics Platform Provider Partnership | Fleet channel consolidation elevates chipset-antenna bundle requirements while compressing standalone module margins. |
| EU Cybersecurity Certification Pathway | Hardware-rooted trust anchors in antenna-integrated units satisfy AI Act mandates through notified body authorization. |
Methodological Framework
Bottom-up fleet operator and vehicle manufacturer modeling reconciled against top-down antenna module production tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement leads, OEM platform engineers, telematics service provider technical directors, and fleet operations managers combined with secondary validation from FCC equipment authorization databases, ETSI technical specifications, 3GPP release documentation, and vehicle production registries. Cross-referencing shipment data from low-loss dielectric substrate manufacturers against telematics control unit installation rates enables demand-side triangulation.
Historical trendline analysis of antenna module adoption across passenger and commercial vehicle platforms informs projection modeling. Segmentation dimensions include product integration depth, protocol technology, end-user procurement authority, and application latency requirements. CAGRs derive from curve-fitting observed adoption rates against regulatory mandate timelines and spectrum allocation decisions. Forecast inputs incorporate carrier certification queue lengths, metamaterial substrate qualification schedules, and fleet platooning mandate implementation progress.
Revisions become necessary when spectrum reallocation decisions, cybersecurity certification requirement changes, or raw material supply disruptions materialize across major automotive markets. Forecasts reflect documented assumptions about regulatory harmonization progress and technology transition timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Automotive Pressure Switch Market
Automotive Circuit Systems
Automotive Body Control Module Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market
Automotive Circuit Systems
South Korea Automotive Relay Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Automotive Oil Pressure Control Valve Market
Automotive Circuit Systems
Global Automotive VVT System Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Automotive Cell Contact System Carrier Market
Automotive Circuit Systems
Automotive Accelerator Pedal Module Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Traction Control System Market
Automotive Circuit Systems
Automotive X-By-Wire System Market