
 Automotive Windshield Market | 2026-2036
Automotive Windshield Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Windshield Market Intelligence
The shift toward electric vehicles is broadening the technical requirements for automotive windshields. These vehicles often require specialized glass with acoustic dampening and solar control properties. Saint-Gobain leverages its material science expertise to develop lightweight glazing for EV applications. Fuyao Glass Industry Group Co., Ltd. dominates the OEM supply chain in China through its large-scale manufacturing capacity, while AGC Inc. competes on technology for ADAS-integrated windshields globally.
An automotive windshield is a safety component engineered from laminated glass, which consists of two layers of glass bonded with a polyvinyl butyral (PVB) interlayer. This construction prevents the glass from shattering into sharp pieces upon impact, protecting vehicle occupants. Laminated glass constitutes the primary product type for front windshields due to safety mandates. The OEM manufacturing stage commands the largest value share, though the aftermarket segment offers higher margins on replacement units, particularly for ADAS-equipped vehicles requiring recalibration.
Safety standards from regulators like the US National Highway Traffic Safety Administration (NHTSA) and compliance with UNECE regulations in Europe dictate material and performance specifications. In China, GB standards govern glass impact resistance and optical clarity, influencing market access for all suppliers. Navigating the increasing complexity of ADAS sensor integration and calibration will be critical for suppliers to maintain profitability and market position.
Market Dynamics
The convergence of advanced driver-assistance systems (ADAS) with electric vehicle (EV) material science demands is the central force shaping the market. This transforms the windshield from a passive component into an active, high-value technology platform requiring new manufacturing capabilities.
Growth Catalysts
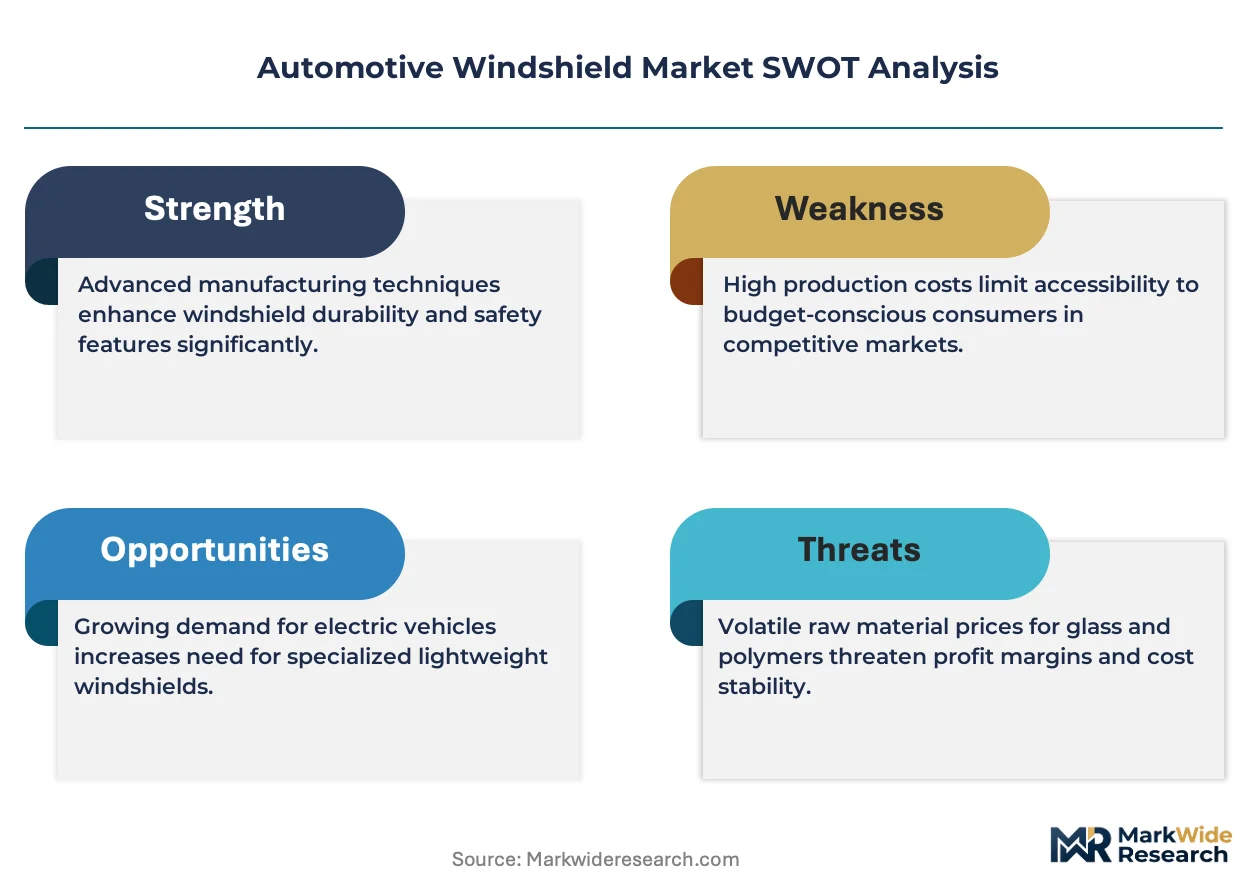
- Safety Regulations:Mandates from regulators like the US National Highway Traffic Safety Administration (NHTSA) and compliance with UNECE standards require laminated glass and drive ADAS integration.
- Electric Vehicle Growth:The EV segment demands specialized glazing with superior acoustic and solar control properties to improve battery efficiency and cabin comfort.
- HUD Technology:Rising consumer preference for Heads-Up Displays necessitates windshields with specific optical qualities, driving demand for higher-value, precision-engineered glass.
Market Restraints
- ADAS Recalibration Cost:The high cost and complexity of recalibrating ADAS sensors after a replacement acts as a significant barrier for the aftermarket segment.
- Raw Material Volatility:Price instability of key inputs like polyvinyl butyral (PVB) resin and high-purity silica compresses manufacturers' profit margins.
- Manufacturing Complexity:Producing large, complex-shaped windshields with integrated electronics requires significant capital investment, limiting the number of capable suppliers.
Strategic Opportunities
- Smart Glass Development:Integrating technologies like switchable privacy glass or transparent antennas into the laminate creates high-value differentiation opportunities for suppliers.
- Aftermarket Service Networks:Building certified networks for ADAS recalibration addresses a critical aftermarket need and allows suppliers to capture high-margin service revenue.
- Lightweighting Solutions:Creating advanced, lightweight glazing using materials like chemically strengthened glass can capture premium contracts within the growing EV sector.
Industry Challenges
- Technician Skill Gap:The aftermarket faces a shortage of technicians skilled in both physical glass installation and the electronic recalibration of diverse ADAS sensor suites.
- Lack of Standardization:No universal standard exists for ADAS sensor placement or calibration protocols across automakers, complicating aftermarket tooling and repair procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Windshield Market |
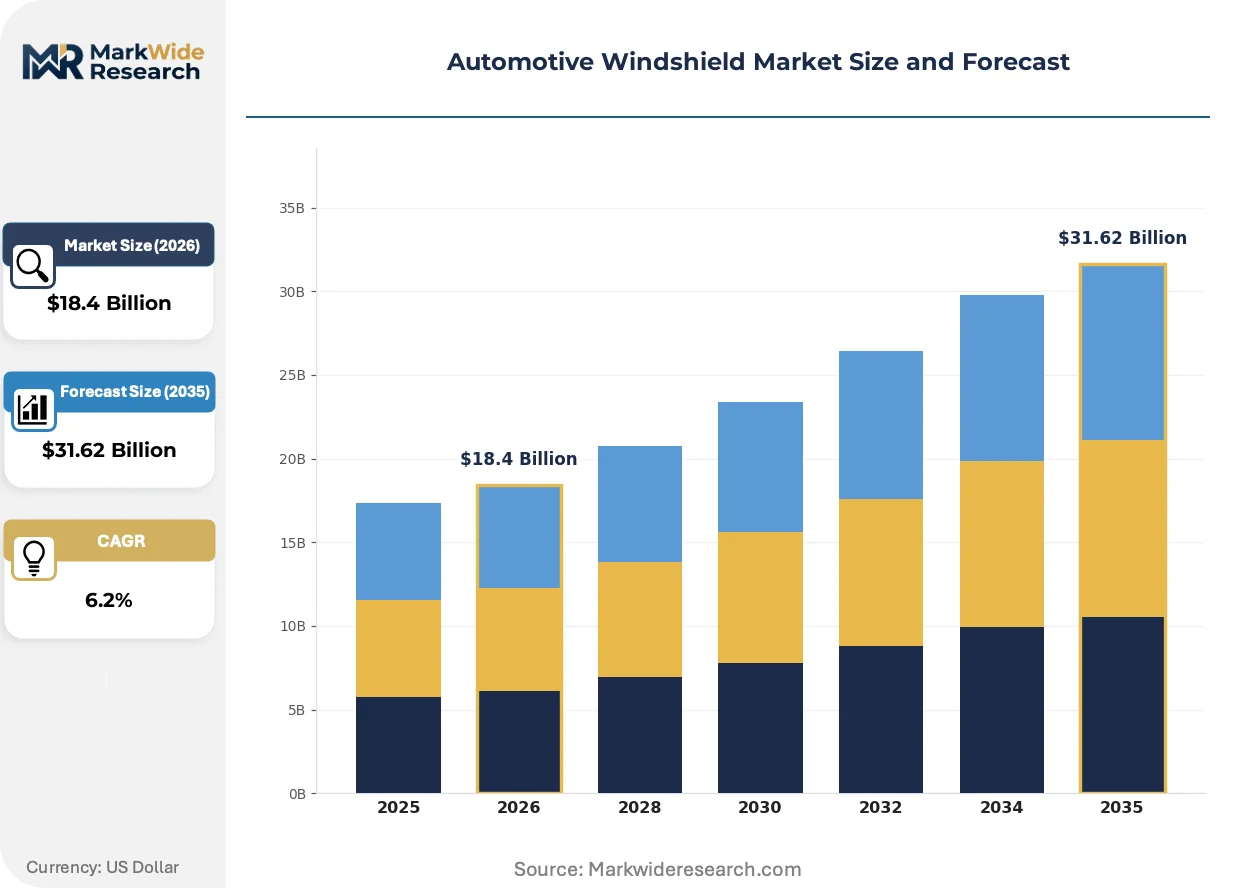
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $31.62 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laminated Glass, Tempered Glass, Acoustic Windshields, Solar Control Glass Vehicle Type: Passenger Cars, Commercial Trucks, Electric Vehicles, SUVs, Vans Manufacturing Stage: OEM, Aftermarket, Refurbished, Custom Fabricated Installation Type: Assembly Line, Service Centers, Mobile Installation, Dealerships |
| Companies Covered | AGC Inc., Saint-Gobain, Nippon Sheet Glass Co., Ltd., Fuyao Glass Industry Group Co., Ltd., Xinyi Glass Holdings Limited, PPG Industries Inc., Central Glass Co., Ltd., Şişecam, Guardian Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Windshield Market Strategic Shifts & Innovations
The automotive windshield is evolving from a passive safety component into an active, intelligent interface. This shift is driven by the integration of complex electronics for ADAS and the need for advanced materials to meet EV efficiency targets.
Lightweight glazing using materials like chemically-strengthened glass is a key product evolution. Its primary function is to reduce overall vehicle weight, which is critical for extending the range of electric vehicles. Automakers in the premium EV segment are the earliest adopters, and the technology is trickling down. This material innovation is rewriting the traditional balance between durability, weight, and cost in automotive glass production.
European Union circular economy directives are putting new pressure on the automotive supply chain. These regulations encourage the design of products for easier disassembly and recycling at their end of life. The windshield aftermarket is most affected, as suppliers must now invest in technologies to separate laminated glass from the PVB interlayer for reuse, impacting cost structures and material sourcing.
A clear shift in the aftermarket involves insurance companies directing policyholders to preferred installer networks. This model displaces independent repair shops, especially for ADAS-equipped vehicles that need proprietary calibration equipment and certified technicians. This consolidation of service channels is most visible in the United States and Germany, where ADAS features are widespread and drive the need for specialized service.
Automotive Windshield Market Segmentation
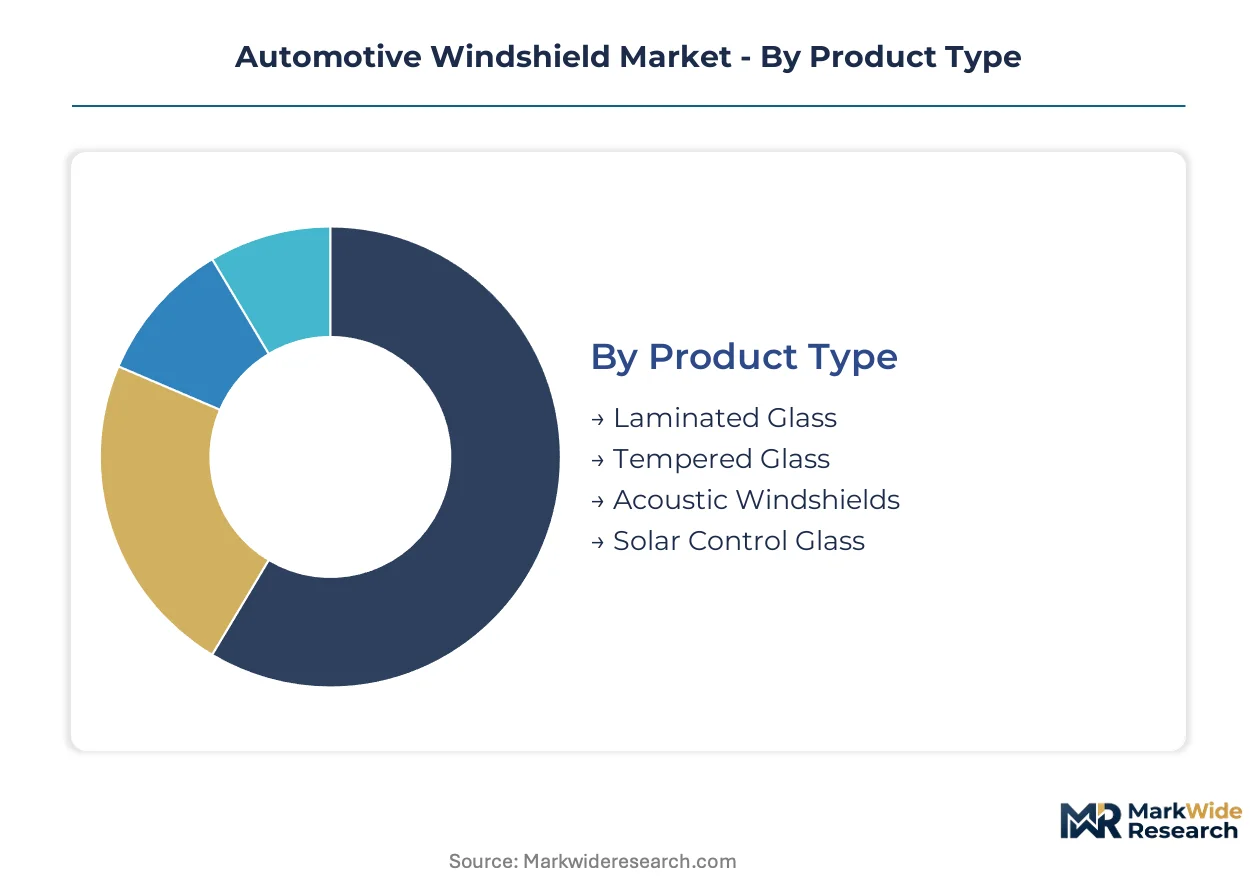
The automotive windshield market segments by critical operational characteristics, reflecting diverse manufacturing processes, end-use applications, and service requirements. Understanding these divisions helps delineate where capital investment is heaviest and where value capture is most significant across the supply chain.
Product Type:
Significant capital investment is necessary for manufacturing specialized product types, particularly those integrating advanced features and materials for performance. This ensures product integrity and compliance with stringent automotive safety standards.
- Laminated Glass:This product type consists of two layers of glass bonded by a polyvinyl butyral (PVB) interlayer, preventing shattering into sharp fragments upon impact. Demand concentrates heavily in front windshields due to stringent safety mandates from regulators like NHTSA and UNECE.
- Tempered Glass:This single-pane glass is heat-treated for strength and shatters into small, blunt pieces, commonly used for side and rear windows in automotive applications.
- Acoustic Windshields:Engineered with specialized interlayers or multiple glass plies, these windshields reduce cabin noise, improving comfort and optimizing acoustic performance for EV applications. Demand is rapidly expanding within the electric vehicles segment to enhance cabin quietness and optimize battery efficiency.
- Solar Control Glass:Incorporates coatings or interlayers to reflect solar radiation, reducing cabin heat and decreasing the load on vehicle air conditioning systems.
Most installed capacity flows through Laminated Glass. Expansion is steepest in Acoustic Windshields.
Vehicle Type:
Diverse vehicle applications dictate specific windshield requirements, influencing material selection, design complexity, and the integration of advanced driver-assistance systems. Each vehicle segment presents unique challenges and opportunities for manufacturers.
- Passenger Cars:This category represents the largest volume segment, encompassing sedans, hatchbacks, and compact vehicles, driving consistent demand for standard and advanced windshield technologies. Global demand for passenger car windshields remains foundational for the market.
- Commercial Trucks:These vehicles often require robust, durable windshields designed for demanding operational environments and extended service life, prioritizing impact resistance and longevity.
- Electric Vehicles:This segment requires specialized windshields with enhanced acoustic dampening and solar control properties to maximize battery range and cabin comfort. Demand is rapidly expanding in China and Europe, driven by government incentives and consumer adoption.
- SUVs:Sport Utility Vehicles drive demand for larger, often panoramic, windshields that may integrate advanced ADAS camera systems and provide expansive driver visibility.
- Vans:This segment includes passenger and cargo vans, requiring functional and durable windshields, sometimes with specific features for fleet applications and commercial use.
Passenger Cars represent the largest volume segment. The demand from Electric Vehicles is gaining share fastest.
Manufacturing Stage:
Profitability varies significantly across manufacturing stages, with aftermarket services often commanding higher margins than initial production due to specialized installation and recalibration needs. Each stage serves distinct customer bases and operational models.
- OEM:The Original Equipment Manufacturer stage involves direct supply to vehicle assembly lines, commanding the largest value share due to high volume and strict integration requirements. This segment demands precision manufacturing and adherence to specific automaker design specifications and ADAS integration protocols.
- Aftermarket:This segment encompasses replacement windshields for vehicles already in operation, offering higher profit margins per unit despite complexities like ADAS recalibration. Demand for aftermarket units is significant in regions with large vehicle fleets, such as the United States and Germany.
- Refurbished:This category involves reconditioning used windshields for resale, primarily targeting cost-sensitive markets or specific repair scenarios to extend product lifecycle.
- Custom Fabricated:Specialized windshields are produced for niche vehicles, unique designs, or restoration projects, requiring bespoke manufacturing processes and individual client specifications.
The OEM segment captures the largest market value. The Aftermarket segment offers superior margin potential.
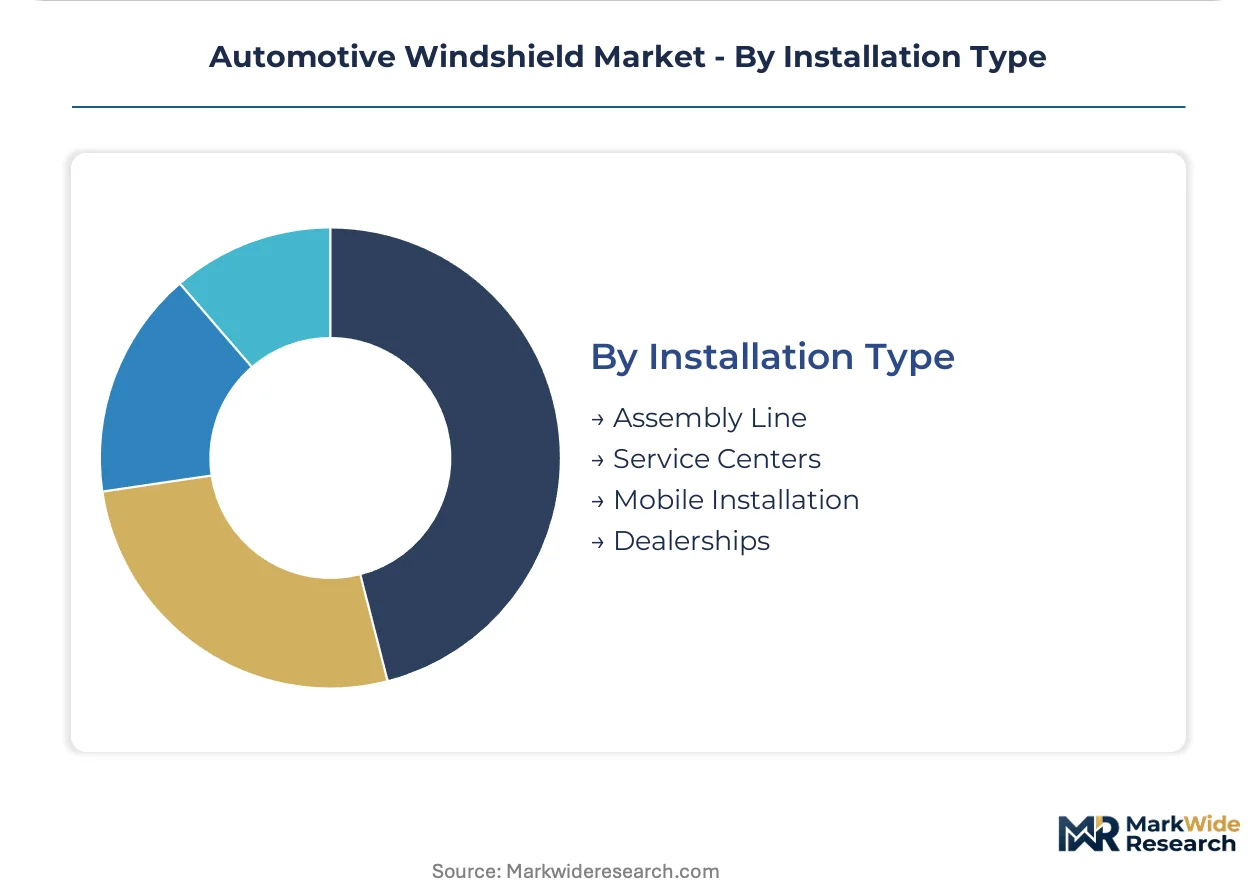
Installation Type:
Different customer types and vehicle ownership models drive varied installation preferences and service channel requirements, impacting logistics and technical expertise. The evolution of vehicle technology also influences installation complexity.
- Assembly Line:This type represents the initial installation of windshields directly onto new vehicles during the manufacturing process, characterized by high volume and automated procedures. Efficiency and precise fit are paramount to maintain production schedules and quality standards for automakers.
- Service Centers:These facilities handle replacement windshield installations, often requiring specialized equipment for ADAS sensor recalibration after glass replacement. Demand for certified service centers is concentrating in urban areas with high concentrations of ADAS-equipped vehicles.
- Mobile Installation:Technicians perform windshield replacements at the customer's location, prioritizing convenience, though often limited by complex ADAS recalibration needs.
- Dealerships:Vehicle dealerships offer windshield replacement services, often leveraging their direct access to OEM parts and specialized diagnostic tools for ADAS-equipped models.
Assembly Line installations account for the majority of new vehicle volume. Specialized Service Centers are crucial for ADAS recalibration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive windshield market experiences shifts in manufacturing concentration, often driven by cost-of-compliance gaps. Production gravitates towards regions offering favorable regulatory environments or lower operational expenses. This dynamic influences supply chain resilience and global pricing structures for automotive glass components.
China
Demand for automotive windshields in China stems from its massive domestic vehicle production and expanding EV segment. GB standards enforce strict quality and safety specifications for all automotive glass. Manufacturing hubs like the Yangtze River Delta concentrate significant production capacity, supporting both OEM and aftermarket supply.
Germany
Germany's automotive sector demands advanced windshields, driven by premium vehicle manufacturing and ADAS integration. UNECE regulations mandate specific performance criteria for laminated glass, including optical clarity. The Stuttgart region, a major automotive cluster, sees significant investment in specialized glass development for new car models.
United States
United States's market shows consistent demand for replacement windshields, especially for ADAS-equipped vehicles. NHTSA safety mandates dictate material specifications and impact resistance for vehicle glazing. Detroit's automotive corridor remains a critical hub for OEM supply, with increasing focus on advanced material integration.
Japan
Japanese automakers require high-quality windshields for their global production lines, emphasizing precision engineering. JIS standards govern the optical and mechanical properties of automotive glass, ensuring rigorous quality control. The Nagoya region, central to Japan's automotive industry, supports extensive R&D into lightweight and smart glass solutions.
India
Increasing vehicle sales and a growing middle class fuel demand for automotive windshields in India. The PLI scheme encourages local manufacturing of automotive components, including advanced glass. Chennai, a prominent automotive manufacturing hub, attracts investment in glass production facilities to serve local vehicle assembly.
Automotive Windshield Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the automotive windshield market structure. This market exhibits a tiered consolidation, with a few large global players dominating OEM supply and a fragmented landscape for aftermarket services. Strategic archetypes include vertically integrated material science companies, large-scale glass fabricators, and regional aftermarket service providers. Key competitive moves involve strategic partnerships for ADAS integration and capacity expansion in high-growth EV markets.
On the global scale-driven end, Saint-Gobain, a French materials science group, and Fuyao Glass Industry Group Co., Ltd., a prominent Chinese manufacturer, exemplify significant production capabilities for automotive glass. AGC Inc., a Japanese multinational, occupies a strong position within the premium segment, focusing on advanced ADAS-integrated windshields. These entities anchor the market's supply side through extensive manufacturing footprints and technological investments.
| Leading Market Players |
|---|
| AGC Inc. |
| Saint-Gobain |
| Nippon Sheet Glass Co., Ltd. |
| Fuyao Glass Industry Group Co., Ltd. |
| Xinyi Glass Holdings Limited |
| PPG Industries Inc. |
| Central Glass Co., Ltd. |
| Şişecam |
| Guardian Industries |
| Others |
Cost & Logistics Intelligence
Polyvinyl butyral (PVB) resin pricing, a critical raw material, influences manufacturing costs, which then filter through OEM contracts and aftermarket unit prices. This cost structure is shaped by the concentrated supply of specialized glass components and the fragmented nature of aftermarket services, affecting pricing power across the value chain.
Pricing Analysis
Direct-to-OEM discounts are significant due to high volume commitments, driving a contract-based long-term offtake pricing model for initial vehicle production. Price differentiation stems from ADAS integration complexity, acoustic dampening properties, and specialized coatings for solar control. Pricing softness runs through the standard aftermarket segment due to intense competition among installers. Aftermarket consumers for basic replacement units exhibit the highest price sensitivity, while premium EV manufacturers are less sensitive to specialized glass costs.
Supply Chain Analysis
Rigorous safety certifications like UNECE and NHTSA standards gate entry for new windshield suppliers, influencing supply chain structure. Geographic supply concentrates in China, Japan, and Germany, which are major automotive manufacturing hubs. The supply chain relies on key raw materials such as high-purity silica, PVB resin, and specialized optical coatings. A structural risk is single-source vulnerability for critical ADAS sensor components. Product distribution for new vehicles flows directly to OEM assembly lines, while aftermarket units are distributed via regional wholesalers and certified service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive windshield market functions as a stable compounder, with safety regulations consistently driving demand for advanced laminated glass. Strategic moves are essential for players to capture value from evolving vehicle technology and aftermarket service needs.
For Market Incumbents:
Anchor market share by expanding specialized manufacturing capacity for acoustic and solar control glass, particularly for the electric vehicle segment. Invest heavily in R&D for advanced ADAS integration solutions to counter the technician skill gap in aftermarket recalibration. Deepen vertical integration into specialized interlayer production to mitigate raw material volatility. Control certification pathways for new ADAS-compatible windshields.
For New Entrants and Emerging Players:
Independent aftermarket repair shops represent an underserved buyer archetype, seeking cost-effective ADAS recalibration solutions. Target specialized aftermarket service networks in regions with high ADAS-equipped vehicle penetration, such as Germany and the United States. Focus on lightweight glazing solutions for mid-range electric vehicles to offer a cost-effective alternative to premium offerings. A certified training program for technicians provides a strong go-to-market angle.
For Investors and Strategic Acquirers:
Roll-up economics work for specialized aftermarket service providers because fragmentation across ADAS recalibration creates acquisition opportunities. The market offers long-term viability, driven by consistent demand for safety-critical components over the next decade. Acquisition targets include regional ADAS calibration specialists or startups developing advanced lightweight glass materials. Standardization of ADAS protocols across automakers is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Supports the rapidly expanding electric vehicle production and domestic aftermarket demand in Asia. |
| Strategic Partnerships for ADAS Integration | Ensures seamless compatibility between windshields and complex sensor systems, crucial for active safety features. |
| Aftermarket Service Network Development | Addresses the high cost and complexity of ADAS recalibration, capturing high-margin service revenue. |
| Lightweight Material Research and Development | Reduces vehicle weight, directly enhancing electric vehicle range and overall fuel efficiency for automakers. |
| Circular Economy Compliance Investment | Prepares suppliers for new European Union directives, enabling PVB interlayer separation and material reuse. |
Research Approach
Bottom-up vehicle type modeling reconciled against top-down OEM production tracking forms the analytical core for this market study. This approach integrates primary interviews with OEM procurement managers, Tier 1 glass fabricators, aftermarket service technicians, and regulatory compliance officers. Secondary validation draws from NHTSA safety reports, UNECE regulations, national automotive production statistics, and company financial filings.
Historical trendline analysis across vehicle production volumes and material science advancements informed the forecast framework. The analytical framework projects market evolution across the analysis window, segmenting by product type, vehicle type, manufacturing stage, installation type, and regional production cluster. Compound annual growth rates were derived from quantitative models considering electric vehicle adoption rates and ADAS penetration rates as key inputs.
Inputs from OEM production data and regulatory filings were available through the study window; gaps in specific ADAS sensor cost data introduce uncertainty bands. Forecasts reflect assumptions regarding raw material price stability and ADAS standardization timelines. A model refresh is warranted upon material change in global automotive production or regulatory mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
LED Fog Lamp Market
Automotive Interior & Exterior
Global Light Vehicle (LV) Cabin AC Filters Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market