
 Automotive Rear Seat Infotainment Market | 2026-2036
Automotive Rear Seat Infotainment Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Rear Seat Infotainment Market Analysis
Modular screen bundling is repositioning how OEMs configure rear cabin packages, shifting from standalone options to integrated entertainment suites. Harman International leverages its audio heritage to anchor premium acoustic experiences within these bundles. Panasonic Corporation dominates display supply for factory-installed systems across multiple vehicle platforms. Robert Bosch GmbH competes through its control of embedded computing modules that power dual-screen architectures.
Automotive rear seat infotainment comprises display units, audio distribution systems, and connectivity modules engineered to deliver video, gaming, and streaming content to second- and third-row passengers, typically operating on 12-volt vehicle electrical architectures with electromagnetic compatibility shielding for cabin safety. The primary commercial purpose centers on occupant engagement during transit, extending vehicle differentiation beyond drivetrain performance. Dual Screen Systems lead product-type configurations as luxury and family-oriented platforms prioritize individualized viewing zones for multiple passengers. Android Auto and Apple CarPlay integration within the technology segment captures growing preference for smartphone-native content ecosystems over proprietary interfaces. Factory-Installed systems under installation type concentrate margin pools with OEMs, while Retrofit Solutions serve aging fleet segments where owners seek post-purchase upgrades.
FCC emissions standards govern wireless headphone and streaming device connectivity in the US market, while EU REACH and RoHS directives restrict hazardous substances in display manufacturing and cable assemblies. ECE R10 automotive electromagnetic compatibility regulations shape product certification requirements for systems deployed across European vehicle registrations. Stakeholders must monitor how software-over-the-air update capabilities redefine ownership models and aftermarket service boundaries.
Market Dynamics
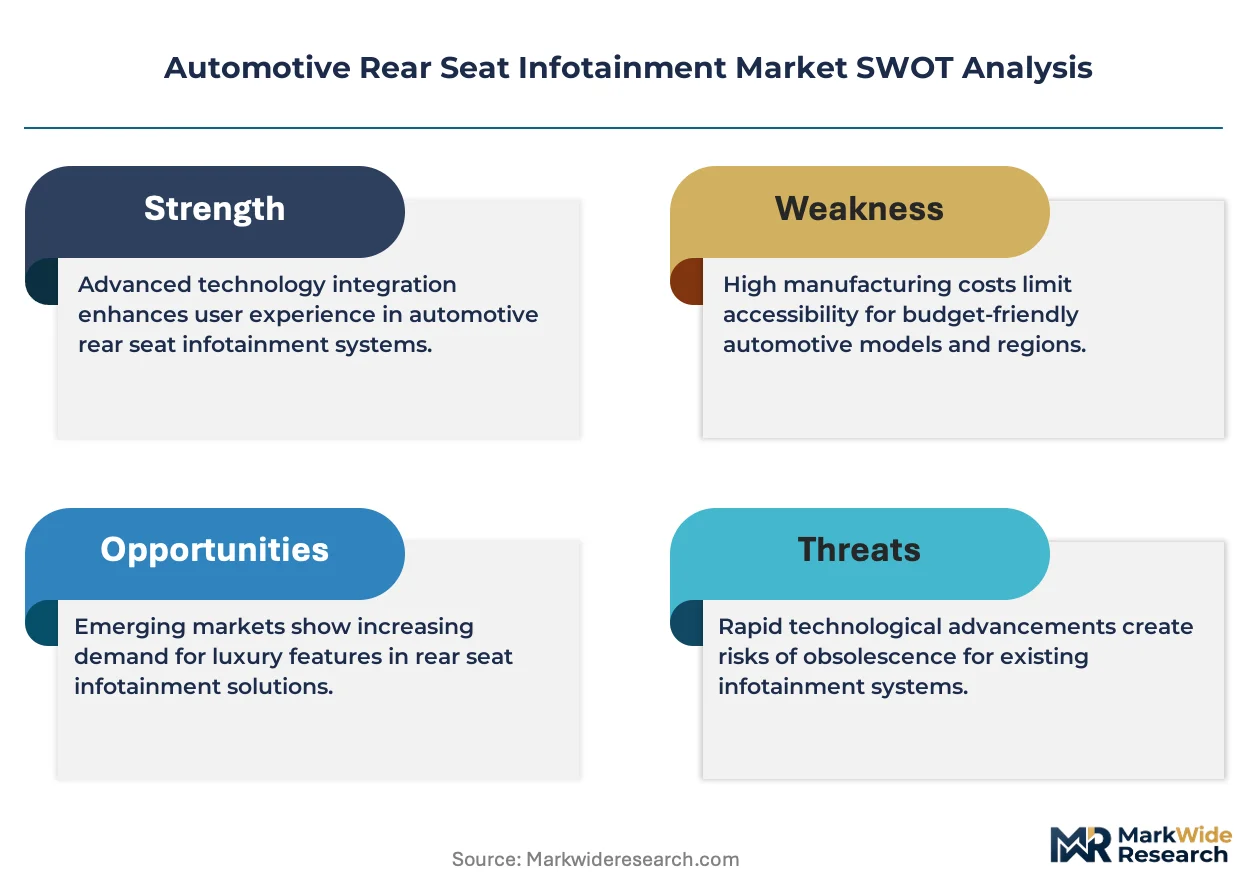
Modular screen bundling is compressing supplier margins while concentrating specification power with platform architects who control embedded computing and acoustic integration roadmaps.
Growth Catalysts
- EU Green Deal Ecodesign mandates:Energy-efficient electronics architectures are accelerating factory-installed system penetration as OEMs redesign 12-volt electrical subsystems to meet carbon intensity benchmarks.
- China domestic EV platform specifications:Native rear seat streaming is becoming standard cabin equipment on new energy vehicle architectures, creating specification pull through local supply chains.
- Dual-screen hardware commoditization:Display panel cost curves are enabling individualized viewing zones across mid-tier vehicle segments previously limited to luxury configurations.
Market Restraints
- Automotive-grade semiconductor allocation:Foundry capacity prioritization toward powertrain electronics constrains infotainment SoC availability, extending lead times for embedded computing modules.
- ECE R10 certification complexity:Electromagnetic compatibility testing for multi-screen architectures adds six to nine months to product validation cycles, delaying revenue recognition.
- Smartphone mirroring substitution:Apple CarPlay and Android Auto wireless integration reduces perceived value of proprietary rear seat content ecosystems, compressing OEM pricing power.
Strategic Opportunities
- India BIS automotive electronics standards:Formalized safety and quality protocols for cabin display systems are creating first-mover advantage for certified suppliers entering premium domestic assembly partnerships.
- Software-over-the-air unbundling:Subscription-based feature activation for rear seat gaming and streaming is shifting revenue models from hardware margin to recurring service economics.
- 5G vehicle-to-cloud convergence:Low-latency edge computing integration with rear seat displays is enabling real-time interactive content previously constrained by storage and processing limitations.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 competency gaps in display system architecture design are extending development timelines and inflating talent acquisition costs.
- Legacy 12-volt integration friction:Electromagnetic compatibility shielding requirements for multi-screen configurations conflict with existing harness routing and grounding schemes in aging vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Rear Seat Infotainment Market |
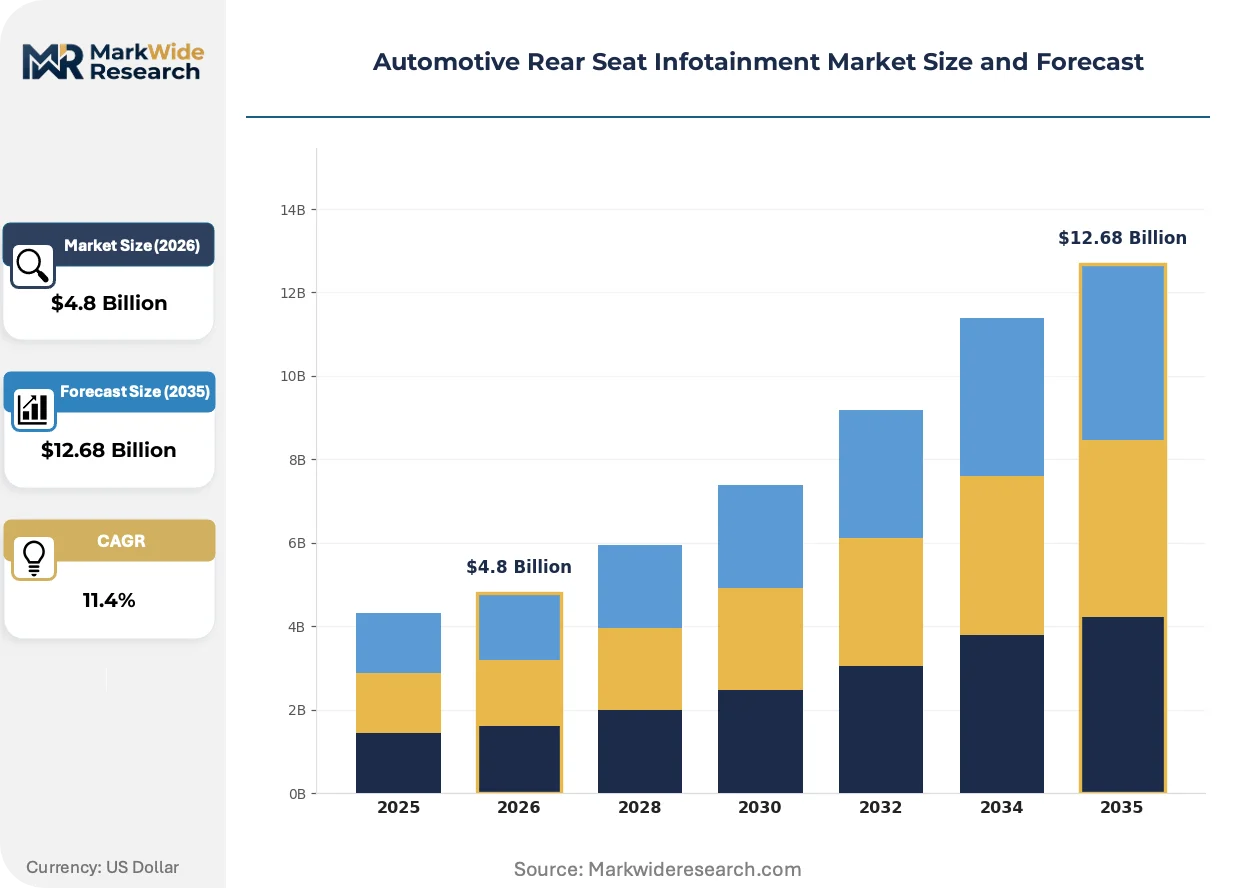
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual Screen Systems, Single Screen Systems, Wireless Headphones, Streaming Devices Technology: Android Auto, Apple CarPlay, HDMI Connectivity, Digital Media Players End User: OEMs, Aftermarket Providers, Luxury Vehicle Manufacturers, Ride-Hailing Services Installation: Integrated Systems, Retrofit Solutions, Factory-Installed, Dealer-Installed |
| Companies Covered | Robert Bosch GmbH, Visteon Corporation, Harman International, Alpine Electronics, Denso Corporation, Panasonic Corporation, Continental AG, Aptiv, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Rear Seat Infotainment Market Emerging Trajectories
Artificial intelligence inference engines are migrating from cloud dependency to edge deployment within cabin computing modules, enabling real-time content personalization without latency penalties.
AI-powered occupancy detection is automating screen orientation, brightness calibration, and content restriction enforcement based on passenger presence and seating position. Luxury OEMs are deploying this capability across dual-screen architectures to differentiate occupant experience without manual configuration. The technology is automating compliance with regional child safety content regulations while reducing driver distraction from rear seat system management.
EU REACH substance restrictions are tightening display manufacturing supply chains by restricting cadmium and lead in LED phosphors and solder alloys. Panel suppliers are accelerating gallium nitride and indium phosphide substitution programs to maintain European market access. Factory-installed system providers with captive display manufacturing are absorbing certification costs more efficiently than modular assemblers dependent on third-party sourcing.
Fleet operators and ride-hailing platforms are unbundling hardware procurement from content service agreements, prioritizing open-architecture systems compatible with multiple streaming provider applications. This procurement pattern is displacing proprietary content ecosystems in commercial vehicle segments where passenger retention metrics override brand differentiation. The shift is most pronounced in China, where domestic mobility platforms specify Android-based rear seat systems to enable rapid third-party application integration.
Automotive Rear Seat Infotainment Market Segmentation
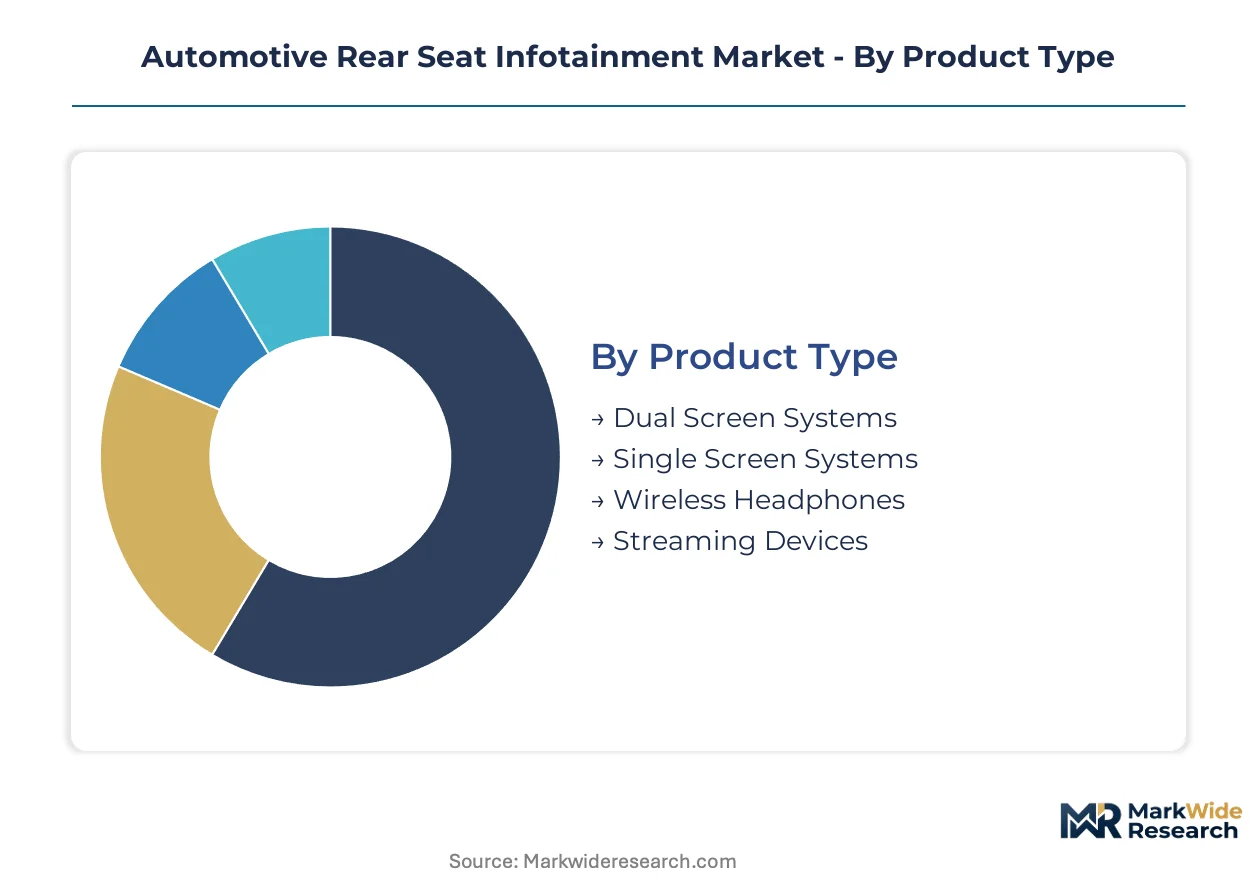
Rear seat infotainment configurations diverge sharply across vehicle price tiers and electrical architectures. Specification choices determine supplier margin pools, certification pathways, and software ecosystem lock-in.
Product Type:
Display topology and audio distribution hardware define the core physical layer of rear cabin entertainment systems.
- Dual Screen Systems:Paired high-resolution displays mounted on front seatbacks or roof consoles deliver individualized content streams to second-row occupants. Luxury and family-oriented platforms in China specify these as standard equipment on domestic EV architectures.
- Single Screen Systems:Centralized ceiling or seatback-mounted displays serve shared viewing for multiple passengers. Mid-tier vehicle segments retain this configuration where cost constraints limit electrical subsystem upgrades.
- Wireless Headphones:Bluetooth and proprietary RF audio peripherals enable private listening without cabin wiring complexity.
- Streaming Devices:Plug-in media modules and casting hardware extend smartphone content to legacy display architectures.
Dual Screen Systems lead on scale; Streaming Devices lead on momentum.
Technology:
Interface protocols determine content ecosystem access and OEM control over user experience roadmaps.
- Android Auto:Google's smartphone projection standard enables native app streaming and voice control integration. Ride-hailing platforms in China specify Android-based rear seat systems for rapid third-party application deployment.
- Apple CarPlay:Apple's proprietary interface delivers iOS-native content and services to secondary displays. Premium vehicle manufacturers prioritize this integration for customer retention in iOS-dominant demographics.
- HDMI Connectivity:Wired digital video input supports gaming consoles and external media players.
- Digital Media Players:Embedded storage and decoding hardware enable offline content playback without smartphone dependency.
Apple CarPlay commands premium positioning; Android Auto expands most quickly.
End User:
Customer procurement patterns separate captive specification control from post-vehicle-sale upgrade demand.
- OEMs:Vehicle manufacturers integrate rear seat systems during platform development, controlling embedded computing and acoustic roadmaps. Factory-installed penetration concentrates margin pools with platform architects.
- Aftermarket Providers:Independent installers serve aging fleet segments where owners seek post-purchase entertainment upgrades. FCC emissions standards govern wireless connectivity certification for US retrofit deployments.
- Luxury Vehicle Manufacturers:Premium brands differentiate through dual-screen configurations and Harman-engineered acoustic experiences.
- Ride-Hailing Services:Mobility platforms prioritize open-architecture systems compatible with multiple streaming applications for passenger retention metrics.
OEMs dominate volume capture; Ride-Hailing Services drive specification innovation.
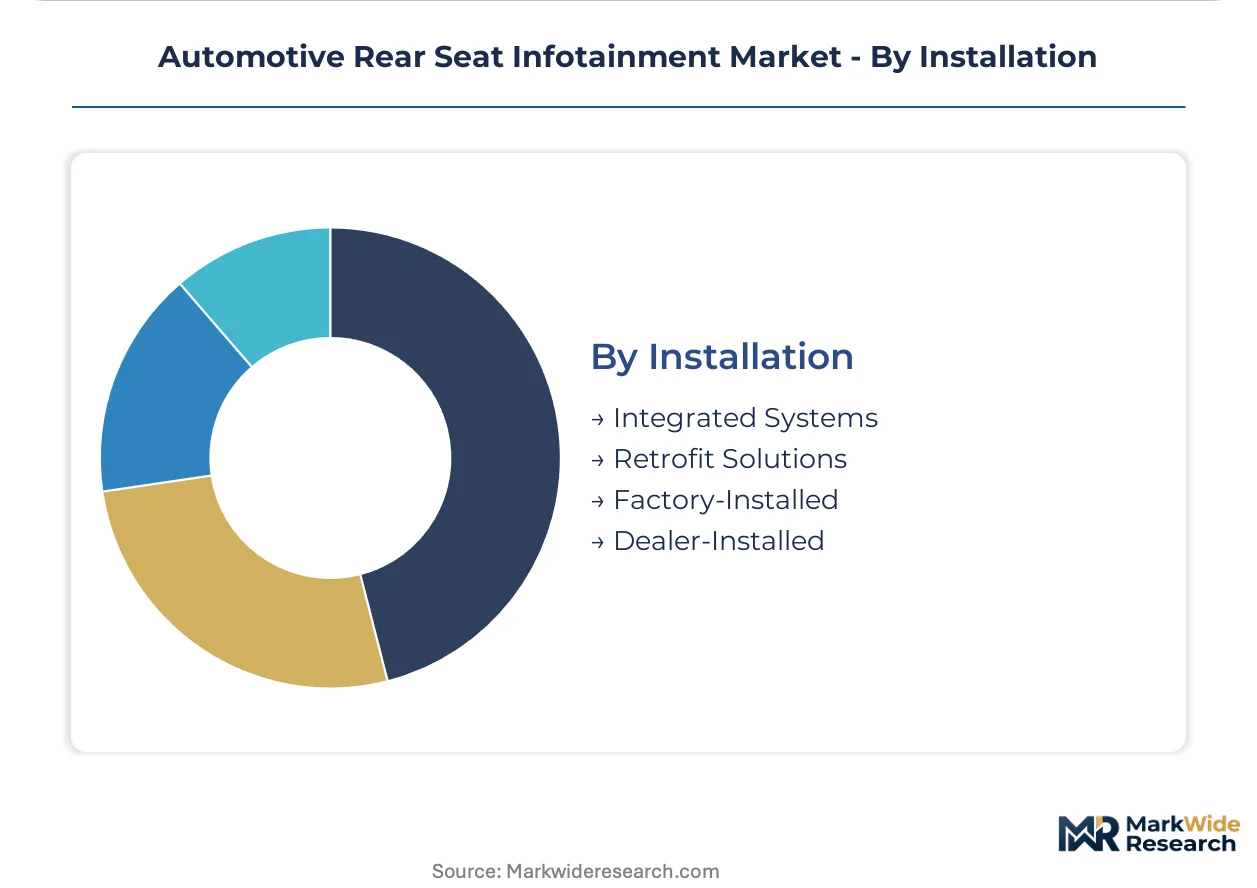
Installation:
Integration timing determines electromagnetic compatibility shielding requirements and harness routing complexity.
- Integrated Systems:Entertainment hardware engineered into vehicle electrical architectures from platform inception. ECE R10 certification requirements add six to nine months to validation cycles for European registrations.
- Retrofit Solutions:Post-manufacture installation for existing fleet vehicles. Legacy 12-volt integration friction constrains multi-screen configurations in aging platforms.
- Factory-Installed:Assembly-line integration by vehicle manufacturers before dealer delivery.
- Dealer-Installed:Authorized dealership fitting of optional entertainment packages prior to customer handover.
Factory-Installed commands margin concentration; Integrated Systems face steepest certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive rear seat infotainment systems first achieved commercial scale in German luxury vehicle platforms during the early 2000s, establishing technical architectures that later diffused into mass-market production. Manufacturing concentration now spans three continents with distinct regulatory and demand profiles.
China
Domestic EV manufacturers specify native rear seat streaming as standard cabin equipment, creating specification pull through local supply chains. MIIT's GB standards for automotive electronics govern electromagnetic compatibility certification for multi-screen architectures. Shenzhen and Shanghai clusters host display panel integration facilities serving NIO, Li Auto, and XPeng platform requirements.
Germany
Luxury OEMs anchor dual-screen configurations through Harman-engineered acoustic experiences and embedded computing roadmaps. EU Green Deal Ecodesign mandates accelerate factory-installed system penetration as OEMs redesign 12-volt electrical subsystems. Stuttgart and Ingolstadt production networks concentrate specification control with platform architects.
United States
Premium vehicle manufacturers prioritize Apple CarPlay integration for customer retention in iOS-dominant demographics. FCC emissions standards govern wireless headphone and streaming device connectivity certification. Michigan and California engineering centers shape embedded software architectures for Ford, GM, and Tesla platforms.
Japan
Automotive-grade semiconductor allocation constraints from foundry capacity prioritization toward powertrain electronics extend lead times for infotainment SoC availability. METI's JIS standards coordinate safety protocols for cabin display systems. Toyota City and Hiroshima manufacturing bases supply Denso and Panasonic production for domestic and export vehicle programs.
India
BIS automotive electronics standards formalize safety and quality protocols for cabin display systems, creating first-mover advantage for certified suppliers. Domestic premium assembly partnerships with Mahindra and Tata Motors drive specification adoption. Pune and Chennai industrial corridors concentrate retrofit installation capacity for aging fleet upgrades.
Automotive Rear Seat Infotainment Market Vendor Landscape
Premium-margin players sit above commodity-margin players across acoustic integration and embedded computing control. The vendor base stratifies between audio heritage specialists, display manufacturing conglomerates, and diversified automotive electronics suppliers. Three archetypes dominate: acoustic-experience bundlers, captive display producers, and control-module generalists. M&A activity concentrates specification power with platform architects, while strategic partnerships around software-over-the-air capabilities reshape aftermarket service boundaries.
Within the acoustic-experience tier, Harman International anchors premium positioning through heritage audio engineering. Panasonic Corporation exemplifies captive display manufacturing with factory-installed system penetration across multiple vehicle platforms. Robert Bosch GmbH occupies a position within embedded computing module supply, powering dual-screen architectures through control electronics. These three entities represent distinct competitive vectors rather than direct substitutes.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Visteon Corporation |
| Harman International |
| Alpine Electronics |
| Denso Corporation |
| Panasonic Corporation |
| Continental AG |
| Aptiv |
| LG Electronics |
| Others |
Supply Flow & Price Mechanics
Captive display manufacturing by Panasonic and integrated acoustic bundling by Harman anchor supply positions while concentrating pricing power with platform architects who control embedded computing roadmaps. This integration pattern compresses modular assembler margins and elevates specification control for factory-installed system providers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates, separating Harman-engineered acoustic suites from mid-tier Android-based configurations and entry-level single-screen retrofits. Price differentiation hinges on ECE R10 certification grade and embedded computing performance tier. Cost compression in mid-tier dual-screen configurations is intensifying because display panel commoditization outpaces SoC availability constraints. Fleet operators and ride-hailing platforms exhibit highest price sensitivity, while luxury OEMs remain least sensitive due to brand differentiation requirements.
Supply Chain Analysis
China's MIIT GB standards and local-content requirements for NEV platforms are reshaping sourcing, compelling foreign suppliers to establish Shenzhen and Shanghai integration facilities. Display panel supply concentrates in China, South Korea, and Japan, while automotive-grade SoC fabrication rests on Taiwan and South Korea foundry capacity. Single-source vulnerability in gallium nitride LED phosphor supply chains threatens European market access under REACH cadmium restrictions. Distribution runs through Tier 1 supplier networks directly into OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal Ecodesign mandates and China's MIIT GB standards accelerate factory-installed specification pull, embedding demand into vehicle platform development cycles.
For Market Incumbents: Acquire ISO 26262 functional safety engineering competency to defend against development timeline inflation from talent scarcity. Secure captive gallium nitride supply chains to maintain European market access under tightening REACH substance restrictions. Consolidate specification control through embedded computing module roadmaps that lock out modular assemblers. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass OEM procurement gatekeeping for ride-hailing and commercial vehicle segments. Target India's BIS-certified aftermarket retrofit segment where aging fleet upgrades outpace factory-installed penetration. Lead with open-architecture Android systems compatible with multiple streaming provider applications. For Investors and Strategic Acquirers: Consolidation pressure builds where acoustic heritage assets face displacement by software-defined audio processing. Long-term viability favors platform architects with embedded computing control over display manufacturing conglomerates lacking system integration capability. Watch 5G vehicle-to-cloud convergence adoption rates as inflection indicator for interactive content monetization potential.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables over-the-air feature activation for rear seat gaming and streaming subscriptions. |
| Backward Integration into SoC Design | Reduces foundry allocation vulnerability for infotainment computing modules. |
| Geographic Manufacturing Footprint | Satisfies China's MIIT local-content requirements for NEV platform qualification. |
| Platform Standardization | Compresses dual-screen hardware costs across mid-tier vehicle segments. |
| Charging Infrastructure Partnership | Creates dwell-time monetization opportunities through rear seat content engagement. |
Methodological Framework
Bottom-up OEM platform modeling reconciled against top-down display supply tracking forms the analytical core, combining primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation draws from vehicle production databases, IHS Markit registration data, MIIT GB standard filings, and EU Ecodesign directive implementation reports. Triangulation between demand-side specification tracking and supply-side capacity monitoring ensures cross-verified output integrity.
Historical trendline analysis of dual-screen adoption rates and factory-installed penetration patterns informs projection modeling across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derive from segment-level growth trajectory reconciliation against aggregate market boundary constraints. Forecast inputs incorporate foundry capacity allocation forecasts for automotive-grade semiconductors and REACH substance restriction implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for AI-powered edge inference engines would alter the outlook if cloud-dependent architectures prevail. Forecasts reflect assumptions about 5G vehicle-to-cloud convergence timing and ECE R10 certification streamlining. Regulatory acceleration in India BIS standards or EU Green Deal stringency represents material upside or downside revision triggers. A small set of named triggers—including semiconductor allocation policy shifts and streaming content licensing fragmentation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Roadside Assistance Software Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Telematics Control Unit Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Next Generation in-Vehicle Networking (IVN) Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
GCC Commercial Telematics Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Automotive OEM Telematics Market
Telematics and Infotainment
North America Automotive Infotainment System Market
Telematics and Infotainment
India Fleet Management Software Market
Telematics and Infotainment
Global Car GPS Navigation System Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market