
 Steering Thermal Systems Market | 2026-2036
Steering Thermal Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Steering Thermal Systems Market Insights
The EU Green Deal is expanding compliance requirements for thermal management across vehicle subsystems, compelling suppliers to redesign steering electronics for higher heat dissipation. Denso leverages its in-house semiconductor packaging to integrate liquid cooling directly into power steering modules. Valeo anchors European OEM relationships with localized thermal testing facilities in France and Germany. Hanon Systems competes on manufacturing scale across multiple vehicle platforms.
Steering thermal systems regulate temperature in electric power steering motors, control units, and rack-and-pinion assemblies through liquid-cooled channels, aluminum heat sinks, or phase change material layers to prevent performance degradation above 85°C operating thresholds. Active cooling dominates product type revenue as EPS torque demands rise with heavier battery-electric vehicle architectures, while thermoelectric systems represent the fastest-growing technology segment for precision temperature control in steer-by-wire prototypes. OEM end users capture the largest margin pool through long-term thermal validation contracts, whereas aftermarket providers occupy a fragmented service niche concentrated in commercial vehicle fleets.
The EPA enforces thermal durability standards for automotive electronics under vehicle emissions integration rules, while NHTSA mandates steering system reliability testing that indirectly governs thermal cycle specifications. China's MIIT imposes GB standards on electric steering efficiency that constrain thermal loss thresholds for vehicles sold domestically. Stakeholders must monitor divergent thermal test protocols across regulators to avoid redundant certification cycles.
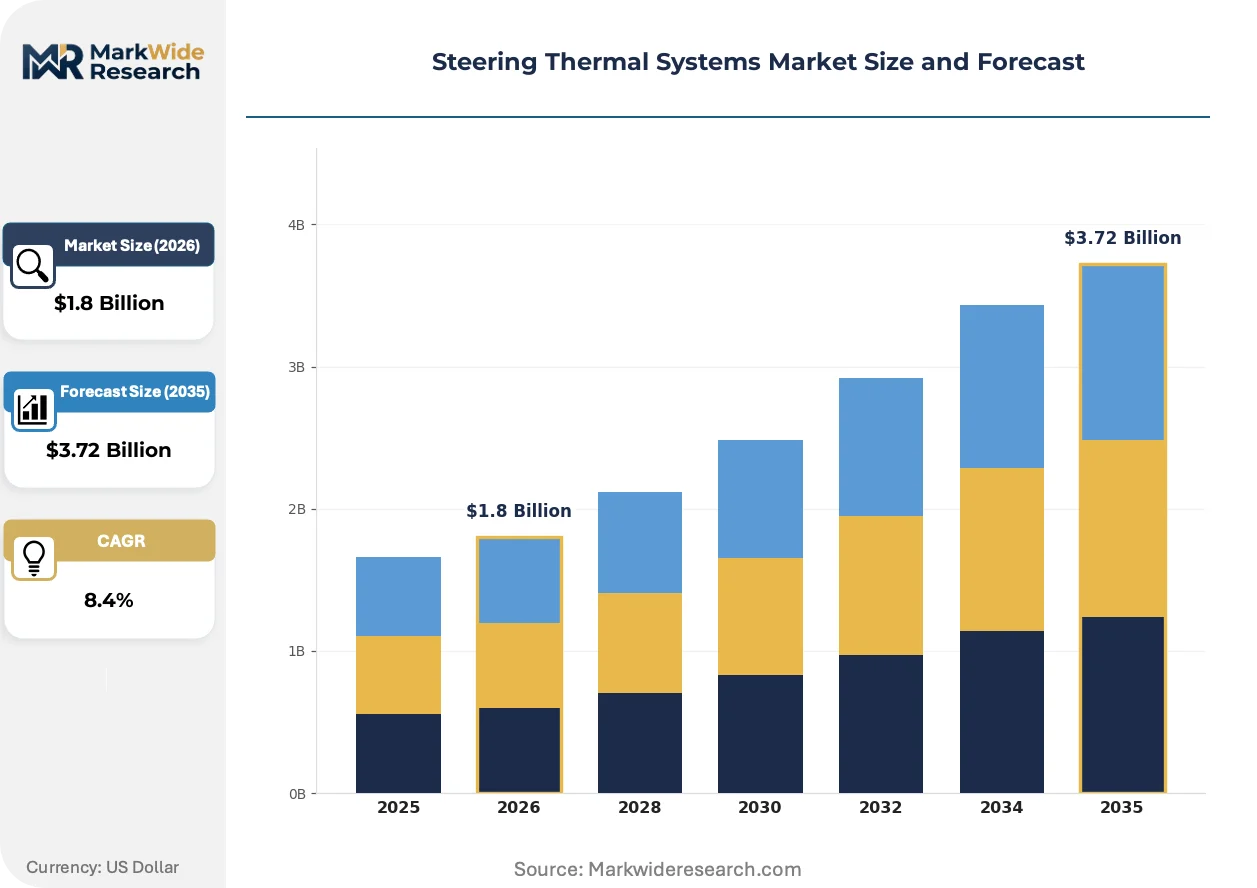
Market Dynamics
Electric power steering torque loads are rising sharply as battery-electric vehicle platforms add mass, forcing thermal management architectures to migrate from passive heat sinks toward active liquid-cooled modules integrated directly into rack-and-pinion assemblies.
Growth Catalysts
- EU Green Deal thermal efficiency mandates:Brussels' emissions integration rules now require steering electronics to maintain performance across wider temperature bands, compelling OEMs to specify active cooling in new platform designs.
- EPS motor power density escalation:Rack-assist electric power steering units now generate heat loads exceeding 85°C thresholds routinely, creating specification pull for liquid-cooled channels in mid-size and full-size vehicle segments.
- Germany's automotive corridor concentration:Stuttgart and Wolfsburg clusters anchor European demand validation, with thermal testing facilities co-located near OEM engineering centers to compress development cycles.
Market Restraints
- Aluminum heat sink supply concentration:Extruded aluminum cooling channels depend on specialized European metalworking suppliers concentrated in Northern Italy and Southern Germany, creating single-source vulnerability.
- Phase change material cost volatility:Paraffin-based thermal interface materials face feedstock price swings tied to petroleum refining margins, compressing module assembler margins.
- GB standard thermal loss thresholds:China's MIIT efficiency constraints for domestic-market electric steering systems impose design constraints that fragment platform commonality between export and China-specific vehicle programs.
Strategic Opportunities
- Steer-by-wire thermal validation contracts:Prototype steer-by-wire architectures require precision thermoelectric control for torque feedback motors, opening specification windows for advanced thermal management suppliers.
- Commercial fleet aftermarket service:Heavy-duty truck EPS units accumulate thermal cycling damage faster than passenger vehicles, creating concentrated demand for cooling system refurbishment in logistics corridors.
- REACH-compliant material substitution:European chemical regulations are accelerating adoption of bio-based phase change materials in thermal interface layers, rewarding early reformulators with OEM qualification priority.
Industry Challenges
- Thermal-fluid dynamics simulation expertise:Liquid-cooled module design requires computational fluid dynamics specialists scarce in traditional automotive steering supply bases, extending hiring timelines.
- Multi-regulator certification overlap:Suppliers must reconcile EPA durability testing, NHTSA reliability cycles, and MIIT efficiency protocols without redundant validation runs, straining program management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steering Thermal Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Cooling, Passive Cooling, Heat Exchangers, Thermal Insulation Application: Passenger Vehicles, Commercial Vehicles, Off-Road, Two-Wheelers Technology: Liquid Cooling, Air Cooling, Phase Change Materials, Thermoelectric Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Denso, Valeo, Hanon Systems, Gentherm, Johnson Electric Holdings, Dana, Eberspächer, VOSS Automotive, MAHLE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steering Thermal Systems Market Trends and Innovations
Thermal management architectures are bifurcating between scaled liquid-cooling solutions for high-torque EPS and precision thermoelectric systems for emerging steer-by-wire prototypes, with regulatory pressure compressing development timelines across both tracks.
Thermoelectric cooling modules utilizing Peltier-effect semiconductor junctions are converging with steer-by-wire development programs at German and Japanese OEMs, where torque feedback motor temperature stability directly determines steering feel quality. These systems command premium positioning in prototype contracts but remain cost-prohibitive for mass-market EPS applications.
REACH chemical registration requirements are forcing reformulation of thermal interface materials across European supply chains, with ECHA substance restrictions eliminating certain paraffin-based phase change compounds from new platform qualifications. Module assemblers are responding by accelerating bio-based alternative validation with OEM thermal testing facilities in France and Germany.
Fleet procurement of EPS thermal service is consolidating around authorized dealer networks and specialized commercial vehicle service chains, displacing independent aftermarket channels for cooling system diagnostics and refurbishment. This concentration is most visible in German long-haul logistics corridors where thermal cycling damage accumulates fastest in rack-assist units.
Steering Thermal Systems Market Segmentation
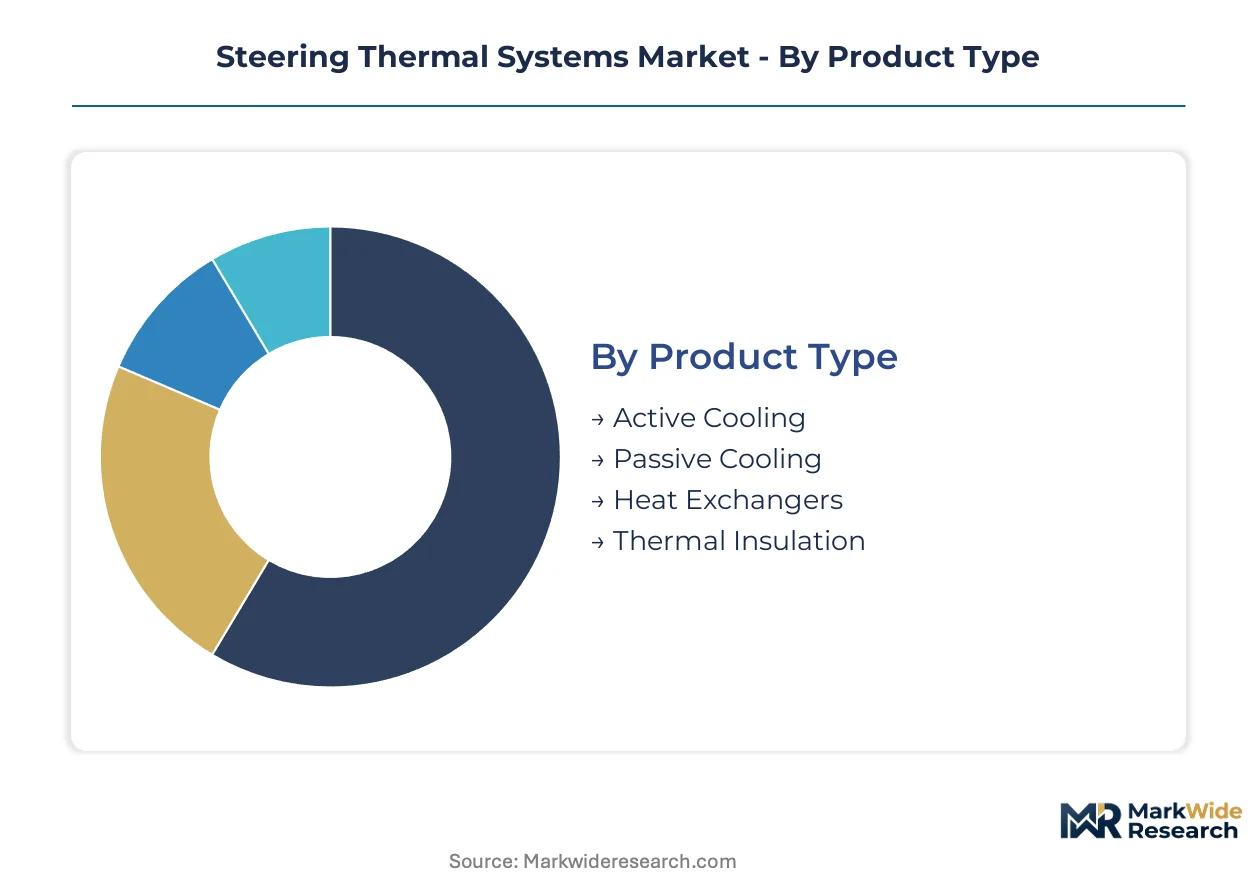
Segmentation in steering thermal systems reveals how thermal management architectures diverge across vehicle electrification levels and supply chain tiers. Specification requirements vary sharply between mass-market EPS platforms and emerging steer-by-wire prototypes, creating distinct margin pools and technical barriers.
Product Type:
Standardization dominates high-volume active cooling modules, while passive solutions retain customization for legacy platforms and cost-sensitive segments.
- Active Cooling:Liquid-cooled channels integrated directly into rack-and-pinion assemblies regulate EPS motor temperatures above 85°C thresholds. Demand concentrates in Germany's Stuttgart engineering corridor where Denso and Valeo validate thermal performance for battery-electric vehicle platforms with elevated torque loads.
- Passive Cooling:Aluminum heat sinks and natural convection designs serve lower-torque steering applications in compact vehicles and emerging markets. Procurement clusters around Northern Italian extrusion suppliers, creating single-source vulnerability for European module assemblers.
- Heat Exchangers:Plate-and-fin configurations transfer thermal loads between steering circuits and vehicle cooling loops.
- Thermal Insulation:Barrier materials protect control electronics from underhood heat soak in front-engine architectures.
Most installed capacity flows through Active Cooling. Expansion is steepest in Heat Exchangers as integrated thermal management architectures consolidate vehicle-level cooling circuits.
Application:
Vehicle mass and duty cycle intensity determine thermal load profiles, with commercial applications demanding more aggressive cooling architectures than passenger segments.
- Passenger Vehicles:Rack-assist EPS units in mid-size and full-size segments generate routine heat loads exceeding passive dissipation limits. German OEMs in Wolfsburg specify liquid-cooled modules for new battery-electric platforms, compressing development cycles through co-located thermal testing facilities.
- Commercial Vehicles:Heavy-duty truck EPS accumulates thermal cycling damage faster than passenger applications, creating concentrated refurbishment demand in long-haul logistics corridors. Fleet procurement is consolidating around authorized service networks, displacing independent aftermarket channels.
- Off-Road:Construction and agricultural equipment operates across wider ambient temperature bands, requiring robust thermal protection for steering electronics.
- Two-Wheelers:Compact EPS implementations in premium motorcycles use simplified air-cooled architectures with limited thermal margins.
Passenger Vehicles anchor current volume. Commercial Vehicles are climbing the fastest as electrification penetrates medium- and heavy-duty segments with sustained high-torque demands.
Technology:
Maturity gradients separate established liquid and air cooling from emerging thermoelectric and phase change material approaches still in qualification.
- Liquid Cooling:Circulated coolant through machined aluminum channels delivers highest heat flux capacity for high-torque EPS motors. Manufacturing scale concentrates with Hanon Systems across multiple vehicle platforms, though CFD simulation expertise remains scarce in traditional steering supply bases.
- Thermoelectric Systems:Peltier-effect semiconductor junctions enable precision temperature control for torque feedback motors in steer-by-wire prototypes. German and Japanese OEMs specify these systems for steering feel quality validation, though cost barriers exclude mass-market EPS applications.
- Air Cooling:Finned heat sinks and forced convection serve lower-power steering applications with adequate packaging space.
- Phase Change Materials:Paraffin-based thermal interface materials face REACH-driven reformulation as ECHA restrictions eliminate certain compounds from new platform qualifications.
Liquid Cooling commands the dominant share of qualified capacity. Thermoelectric Systems represent the fastest-growing technology segment as steer-by-wire architectures advance toward production intent.
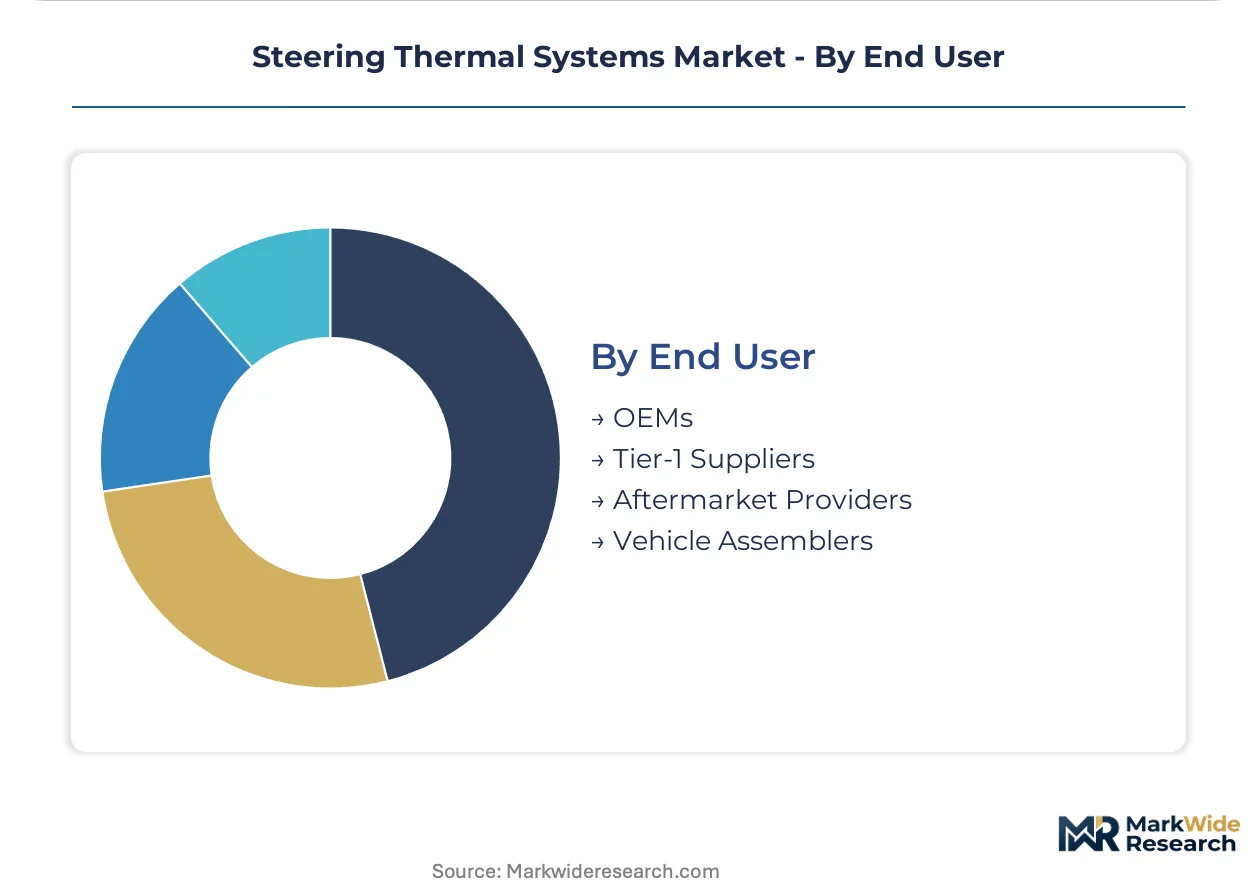
End User:
Margin capture and technical influence concentrate at the OEM level, with Tier-1 suppliers and assemblers operating under long-term thermal validation contracts.
- OEMs:Vehicle manufacturers retain specification authority for thermal management architectures and capture the largest margin pool through multi-year validation contracts. EU Green Deal emissions integration rules now require steering electronics to maintain performance across wider temperature bands, compelling direct OEM involvement in cooling system design.
- Tier-1 Suppliers:Module assemblers integrate cooling channels, heat sinks, and control electronics under platform-specific thermal performance guarantees. Denso leverages in-house semiconductor packaging to embed liquid cooling directly into power steering modules, differentiating against competitors dependent on external component sourcing.
- Aftermarket Providers:Fragmented service niche concentrated in commercial vehicle fleet refurbishment and warranty thermal system replacement.
- Vehicle Assemblers:Contract manufacturers execute thermal module installation under OEM-directed specifications with limited design autonomy.
OEMs and Tier-1 Suppliers together control specification and margin concentration. Aftermarket Providers are gaining share fastest in commercial fleet channels as thermal cycling damage accumulates in high-mileage EPS units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive corridor pioneered integrated thermal management for electric power steering, with Stuttgart and Wolfsburg engineering clusters establishing validation protocols now adopted across multiple continents.
Germany
Stuttgart and Wolfsburg anchor European demand concentration, with thermal testing facilities co-located near OEM engineering centers to compress development cycles. The EU Green Deal's emissions integration rules compel steering electronics to maintain performance across wider temperature bands. Denso and Valeo operate localized validation laboratories in these clusters to service battery-electric platform launches.
China
Domestic EV production scale drives specification demand for liquid-cooled steering modules across multiple OEM platforms. MIIT enforces GB standards on electric steering efficiency that constrain thermal loss thresholds for vehicles sold domestically. Yangtze River Delta manufacturing hubs concentrate module assembly capacity to serve both local and export vehicle programs.
United States
EPA thermal durability standards for automotive electronics under vehicle emissions integration rules shape supplier design priorities. NHTSA mandates steering system reliability testing that indirectly governs thermal cycle specifications. Michigan-based OEM engineering centers coordinate validation with Tier-1 suppliers for North American platform deployment.
Japan
Precise torque feedback requirements in steer-by-wire prototypes drive thermoelectric system qualification. METI oversees industrial standards coordination between automotive and electronics sectors. Nagoya-area manufacturing clusters integrate semiconductor packaging expertise with thermal module production for advanced steering architectures.
South Korea
Battery-electric vehicle platform investments from domestic OEMs escalate EPS torque load specifications. MFDS-equivalent automotive standards bodies coordinate thermal validation protocols with international regulators. Seoul Capital Area suppliers scale liquid-cooled channel production across multiple vehicle segments.
Steering Thermal Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the supplier base, creating a tiered structure where integrated thermal module specialists hold specification authority over component assemblers. The market consolidates around three strategic archetypes: diversified automotive thermal specialists with in-house semiconductor capabilities, focused steering subsystem suppliers leveraging manufacturing scale, and precision thermoelectric developers serving prototype steer-by-wire programs. Dominant competitive moves include co-location of thermal testing facilities near OEM engineering centers and backward integration into aluminum extrusion and coolant circuit machining.
Among diversified thermal specialists, Denso and Valeo exemplify archetypes combining semiconductor packaging expertise with localized European validation infrastructure. Hanon Systems occupies a position emphasizing manufacturing scale across multiple vehicle platforms. These three anchors demonstrate how competitive positioning diverges between technology-integrated and scale-driven business models.
| Leading Market Players |
|---|
| Denso |
| Valeo |
| Hanon Systems |
| Gentherm |
| Johnson Electric Holdings |
| Dana |
| Eberspächer |
| VOSS Automotive |
| MAHLE |
| Others |
Pricing and Supply Chain Analysis
Aluminum extrusion costs from Northern Italian and Southern German metalworking suppliers cascade through three distinct pricing tiers for steering thermal modules, with active liquid-cooled systems commanding premium positioning over passive heat sink alternatives as battery-electric vehicle torque demands intensify.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs module procurement, with differentiation driven by thermal performance certification grade and volume scale commitments from OEM platform engineers. Cost compression in economy-tier passive cooling is intensifying because REACH-compliant material reformulation is raising input costs for paraffin-based phase change compounds. Fleet operators in commercial vehicle segments exhibit highest price sensitivity due to refurbishment cycle economics, while German OEMs in Stuttgart and Wolfsburg demonstrate lowest sensitivity given thermal validation contract premiums.
Supply Chain Analysis
Refurbishment flows for thermally cycled rack-assist units are consolidating around authorized dealer networks in German long-haul logistics corridors, displacing independent aftermarket channels. Manufacturing concentration rests on Germany, China, and South Korea for module assembly, with raw material dependencies spanning extruded aluminum channels, semiconductor packaging substrates, and bio-based phase change formulations. Single-source vulnerability in Northern Italian aluminum extrusion creates structural risk exposure. Distribution runs through Tier-1 supplier direct-to-OEM contracts with limited spot market activity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The steering thermal systems market represents a late-cycle quality story where specification authority is migrating toward suppliers capable of integrating liquid cooling with in-house semiconductor packaging, as EU Green Deal mandates pull demand toward premium active cooling architectures.
For Market Incumbents: Acquire computational fluid dynamics simulation capabilities to address expertise scarcity in traditional steering supply bases. Backward integration into aluminum extrusion and coolant circuit machining defends margin position against commodity input volatility. Denso's captive semiconductor packaging model offers a template for differentiation against competitors dependent on external component sourcing. For New Entrants and Emerging Players: REACH in Europe opens a window for bio-based phase change material specialists to capture OEM qualification priority ahead of ECHA substance restrictions eliminating paraffin compounds. Commercial fleet aftermarket service channels present the most penetrable white-space target, given thermal cycling damage accumulation in heavy-duty truck EPS units. A go-to-market angle anchored on rapid thermal testing turnaround for steer-by-wire prototype validation can bypass incumbent co-location advantages. For Investors and Strategic Acquirers: Consolidation pressure builds where CFD expertise scarcity intersects with multi-regulator certification burden straining program management bandwidth. The 5-to-10-year viability window favors targets with validated thermoelectric cooling modules for steer-by-wire production intent. Acquisition target archetype: mid-cap thermal module specialists with OEM validation contracts and backward-integrated machining capacity. Monitor GB standard thermal loss threshold enforcement intensity in China as an inflection indicator for platform commonality fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of machined cooling channels reduces single-source vulnerability from Northern Italian suppliers. |
| CFD Simulation Capability Buildout | Liquid-cooled module design requires scarce thermal-fluid dynamics specialists currently concentrated outside steering supply bases. |
| REACH-Compliant Material Reformulation | Bio-based phase change alternatives secure OEM qualification priority ahead of ECHA paraffin restrictions. |
| Co-Location of Thermal Testing Facilities | Proximity to Stuttgart and Wolfsburg engineering clusters compresses development cycles for battery-electric platforms. |
| Thermoelectric System Qualification | Precision temperature control for steer-by-wire torque feedback motors commands premium prototype contract positioning. |
Research Methodology
Bottom-up OEM platform modeling reconciled against top-down Tier-1 supplier capacity tracking forms the analytical core of this study. Primary interviews with thermal module procurement managers, OEM platform engineers, aftermarket service directors, and ECHA regulatory affairs specialists combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive suppliers, and EU regulatory filings. Triangulation between demand-side specification trends and supply-side manufacturing footprints ensures cross-verification of volume and value estimates.
Input-output matrices map thermal module content per vehicle across passenger, commercial, and off-road segments, with propulsion architecture and regional production cluster as cross-cutting dimensions. CAGRs derive from segment-level build-up analysis incorporating platform launch timelines and thermal efficiency mandate phase-in schedules. Industry-specific forecast inputs include EPS torque load escalation curves from battery-electric vehicle mass trends and REACH substance restriction implementation calendars.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT GB standard enforcement intensity shifts or aluminum supply disruption scenarios. Forecasts reflect documented assumptions regarding OEM platform commonality between export and China-specific programs. Practitioners should monitor ECHA substance restriction expansion timelines and steer-by-wire production intent announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Traction Control System Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Global Automotive VVT System Market
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
South Korea Automotive Relay Market
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Automotive V2X Antenna Market