
 Electric Vehicle Regenerative Braking System Market | 2026-2036
Electric Vehicle Regenerative Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Regenerative Braking System Market Insights
Aftermarket distribution for regenerative braking components is fragmenting as OEMs tighten captive parts programs and direct-to-fleet channels multiply. Robert Bosch GmbH leverages its integrated electronics and braking portfolio to sustain long-term supply agreements with European and Asian automakers. Continental AG anchors its position through deep manufacturing scale in electromechanical actuation modules. ZF Friedrichshafen AG competes by specializing in complete brake-by-wire architectures that consolidate hydraulic and electronic functions.
An electric vehicle regenerative braking system recaptures kinetic energy during deceleration and converts it into electrical energy through motor-generator units, typically achieving recovery efficiencies between 60% and 70% depending on drive cycle and battery state of charge. The system serves the primary commercial purpose of extending vehicle range while reducing mechanical brake wear and particulate emissions in urban stop-and-go conditions. Full regenerative systems now lead product type segmentation as battery-electric platforms abandon conventional friction-dominant architectures. Passenger vehicles dominate end user demand, though commercial vehicle adoption is accelerating fastest where duty cycles maximize energy recovery potential.
The EPA tailpipe emissions framework and NHTSA fuel economy standards in the United States shape product development by penalizing fleets with poor regenerative energy capture, while China's MIIT new energy vehicle mandates require minimum energy recovery rates in domestic EV certifications. The EU Green Deal and associated CO2 fleet targets enforced by EMA coordination push OEMs toward higher-efficiency braking recuperation across all vehicle classes. Stakeholders must monitor how regulatory thresholds for brake particulate emissions converge with energy recovery mandates to determine next-generation system architectures.
Market Dynamics
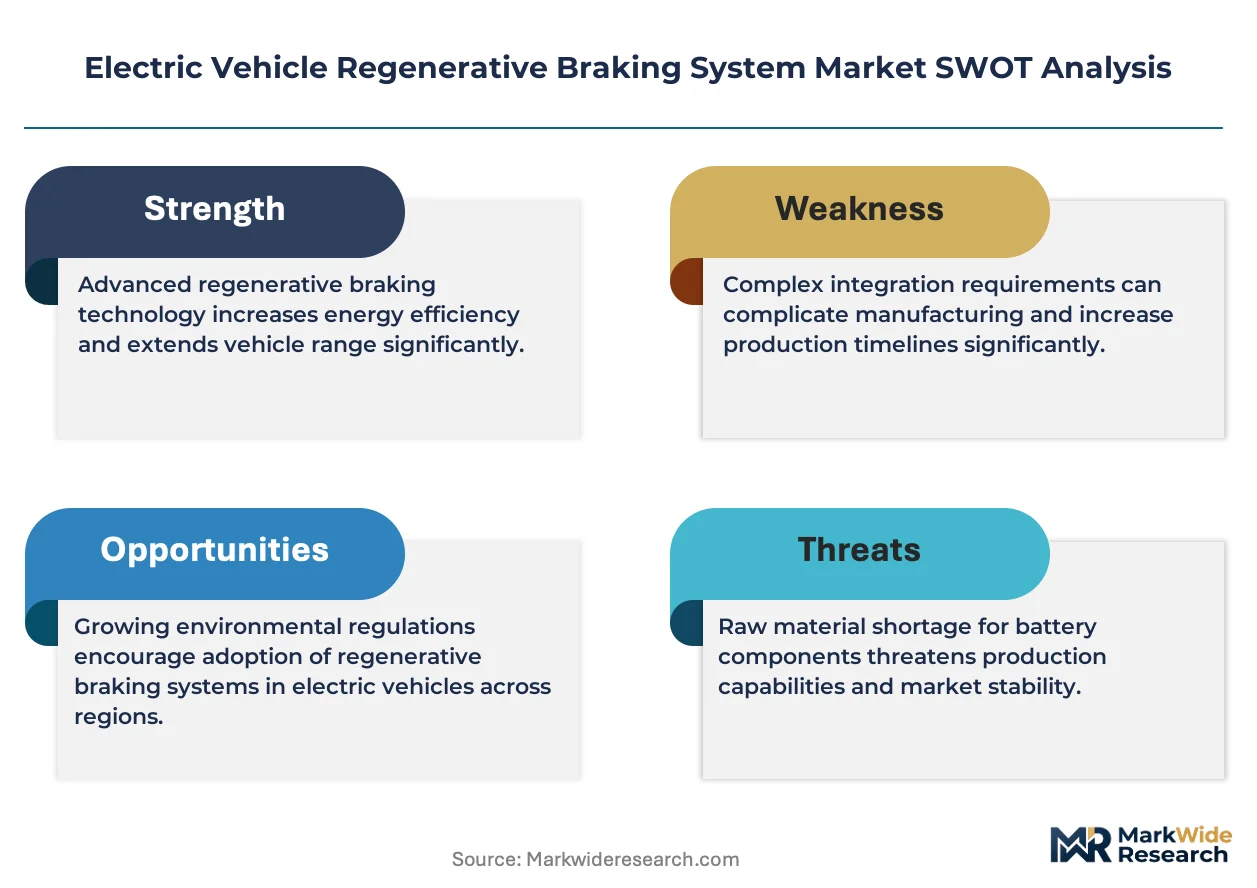
Platform electrification is compressing brake system architectures from multi-component hydraulic assemblies to integrated electromechanical modules, forcing suppliers to recalibrate engineering resources toward software-defined braking control and thermal management integration.
Growth Catalysts
- MIIT energy recovery mandates:China's minimum recuperation efficiency thresholds for NEV certification are compelling domestic OEMs to specify high-performance regenerative hardware across all battery-electric platforms.
- Urban fleet electrification:Municipal bus operators in Shenzhen, Shenzhen, and Los Angeles are specifying maximum energy recovery duty cycles to reduce charging infrastructure load and extend daily range.
- Silicon carbide inverters:Wider bandgap semiconductors are raising motor-generator conversion efficiency, enabling more aggressive regenerative braking profiles without thermal derating.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motor production for regenerative systems depends on neodymium processing concentrated in China, exposing non-Chinese automakers to export quota volatility.
- Friction brake redundancy requirements:NHTSA and UNECE regulations mandating failsafe mechanical backup systems prevent full elimination of hydraulic components, preserving cost and weight penalties.
- Battery state-of-charge limitations:Full battery packs cannot accept regenerated energy, forcing software throttling that wastes recoverable kinetic energy during downhill or highway deceleration events.
Strategic Opportunities
- India's PLI scheme for auto component manufacturing:Localization incentives are attracting brake system suppliers to establish electromechanical module production for the subcontinent's emerging EV assembly base.
- Brake-by-wire convergence with steer-by-wire:Integrated chassis control platforms combining both functions are creating new specification tiers for premium passenger vehicle platforms.
- Second-life battery integration:Partially depleted EV batteries repurposed as stationary buffers can absorb regenerated energy when vehicle packs are full, extending effective recovery rates.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL-D certification for brake control systems requires specialized hardware-software integration expertise that outstrips current talent pipelines.
- Legacy platform retrofit complexity:Internal combustion vehicle architectures lack the high-voltage bus infrastructure and motor-generator mounting provisions necessary for regenerative system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Regenerative Braking System Market |
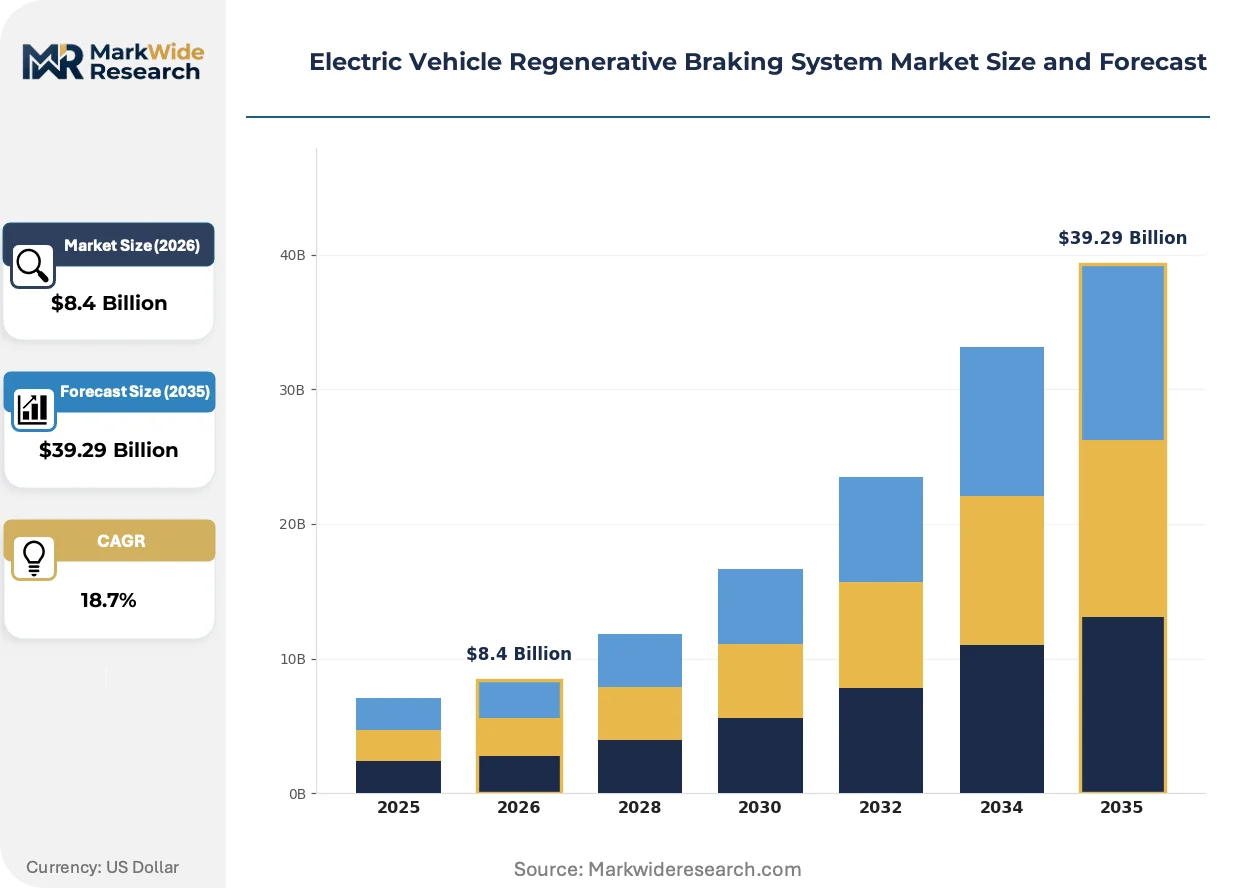
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parallel System, Series System, Hybrid System, Full Regenerative System End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles Technology: Electromechanical, Hydraulic, Pneumatic, Electronic Application: Urban Driving, Highway Driving, Off-Road Driving, Performance Driving |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Denso Corporation, ADVICS Co., Ltd., Hyundai Mobis, Aisin Corporation, BorgWarner Inc., Hitachi Astemo, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Regenerative Braking System Market Trends and Innovations
Electromechanical actuation is displacing hydraulic fluid circuits as the primary braking modality, compressing supplier value chains and elevating firmware development to parity with mechanical engineering in procurement evaluations.
Brake-by-wire architectures eliminate hydraulic lines between pedal simulator and caliper actuators, replacing them with encrypted electronic control signals. European and Asian OEMs are adopting these systems for their 800-volt platforms first. The technology is rendering obsolete the century-old paradigm of hydraulic pressure as the universal braking medium.
The EU Green Deal's CO2 fleet targets enforced by EMA coordination are tightening brake particulate emission limits alongside energy recovery mandates. Dual-compliance requirements are accelerating R&D spending on low-emission friction materials that maintain performance during blended braking events. Commercial vehicle manufacturers face the steepest certification timelines and are pre-qualifying suppliers two product cycles ahead of enforcement dates.
Fleet procurement departments are unbundling brake system sourcing from traditional tier-1 chassis contracts, creating direct purchasing relationships with electromechanical specialists. This disintermediation is most visible in California and Germany, where large commercial fleets operate sufficient vehicle counts to justify dedicated supplier development programs and custom calibration specifications.
Electric Vehicle Regenerative Braking System Market Segmentation
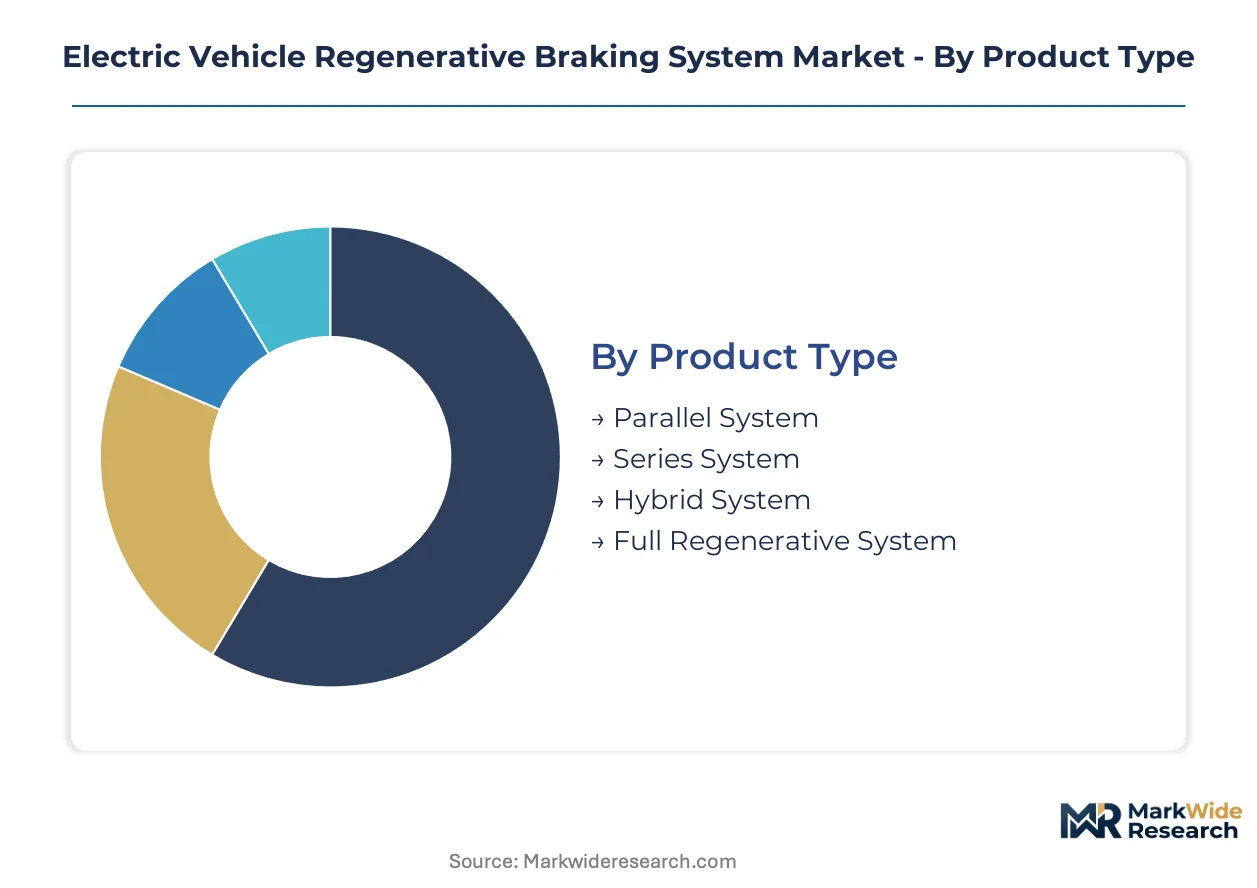
Segmentation in the EV regenerative braking market reveals how platform electrification stratifies across vehicle architectures and duty cycles. Each dimension exposes distinct technical requirements, procurement patterns, and supplier capability thresholds that shape competitive positioning.
Product Type:
Mature hydraulic-retention architectures coexist with emerging fully-electric recuperation systems as OEMs navigate transition timelines and certification requirements.
- Full Regenerative System:Eliminates conventional friction-dominant hardware entirely, relying on motor-generator units and electromechanical calipers for all deceleration events. Battery-electric platforms from premium European and Chinese OEMs are mandating this architecture to maximize range extension and minimize brake particulate emissions under tightening EU Green Deal enforcement.
- Hybrid System:Blends regenerative torque with friction braking through coordinated control algorithms, preserving hydraulic backup for safety-critical scenarios. Mass-market passenger vehicles in China dominate procurement volumes as MIIT energy recovery mandates push domestic OEMs toward higher recuperation efficiency without full brake-by-wire cost premiums.
- Parallel System:Runs regenerative and friction braking on independent paths with minimal integration.
- Series System:Sequences regenerative braking before friction engagement in deceleration events.
Full Regenerative System retains volume leadership; Hybrid System holds the steepest expansion curve.
End User:
Customer type segmentation tracks divergent duty cycle economics, where stop-and-go intensity directly correlates with energy recovery payback periods.
- Passenger Vehicles:Encompasses sedans, SUVs, and crossovers where urban commute patterns generate sufficient braking events to justify recuperative hardware costs. China accounts for the dominant share of global installations as domestic EV production scales ahead of all other geographies combined.
- Commercial Vehicles:Buses, delivery vans, and medium-duty trucks with predictable urban routes achieving maximum regeneration duty cycles. Municipal fleet operators in Los Angeles and Shenzhen are specifying custom calibration profiles to reduce charging infrastructure load and extend daily operational range.
- Two-Wheelers:Electric motorcycles and scooters with simplified single-motor architectures.
- Heavy-Duty Vehicles:Long-haul trucks and construction equipment where high mass amplifies kinetic energy recovery potential.
Passenger Vehicles command installed-base dominance; Commercial Vehicles are climbing the fastest as fleet electrification accelerates.
Technology:
Technology segmentation maps the displacement of fluid-based actuation by solid-state electromechanical control across supplier engineering roadmaps.
- Electromechanical:Replaces hydraulic fluid circuits with motor-driven caliper actuation, enabling software-defined brake torque distribution and eliminating environmental leakage risks. European tier-1 suppliers anchor manufacturing scale in Germany and Hungary to serve 800-volt platform demand from premium OEMs.
- Electronic:Encompasses sensor fusion, control algorithms, and encrypted signal transmission for brake-by-wire architectures. Asian semiconductor foundries in Taiwan and South Korea are expanding silicon carbide inverter capacity to support higher-efficiency motor-generator conversion in next-generation systems.
- Hydraulic:Retains pressurized fluid circuits for friction backup and blended braking scenarios.
- Pneumatic:Compressed-air systems limited to specific heavy-duty commercial applications.
Electromechanical captures the majority of new platform specifications; Electronic is gaining share fastest as firmware development costs decline.
Application:
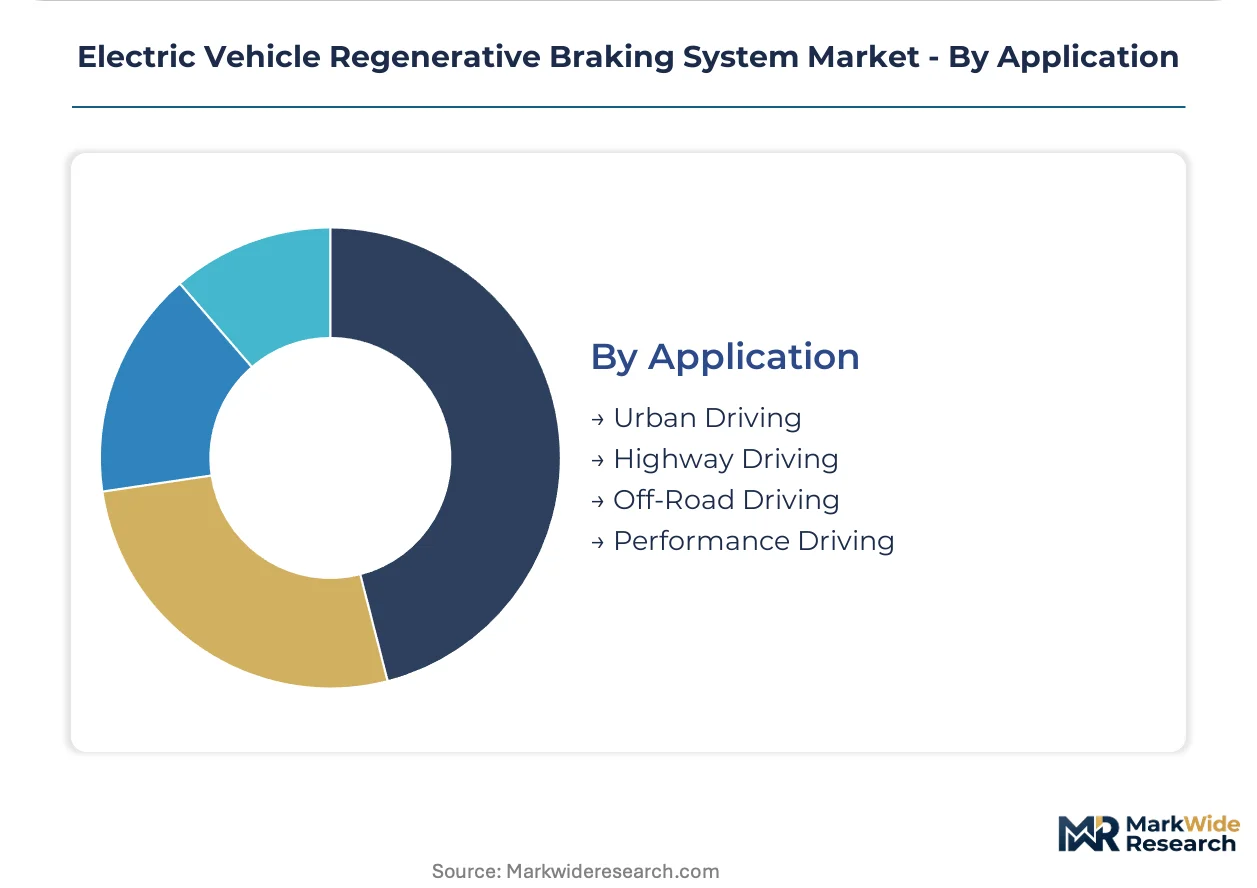
Application segmentation isolates how drive cycle characteristics dictate regenerative system sizing, thermal management requirements, and control calibration complexity.
- Urban Driving:Stop-and-go traffic patterns with frequent deceleration events maximizing energy recovery duty cycles and minimizing mechanical brake wear. City-center congestion charging zones in London and Singapore are accelerating OEM specification of high-recuperation systems to meet zero-emission zone access requirements.
- Highway Driving:Sustained-speed cruising with intermittent braking demanding efficient downhill energy capture and thermal deration management. Mountainous corridors in Norway and Switzerland expose battery state-of-charge limitations that force software throttling and waste recoverable kinetic energy.
- Off-Road Driving:Unpaved terrain with variable traction conditions requiring specialized torque vectoring integration.
- Performance Driving:Track and sport applications prioritizing thermal endurance and rapid charge acceptance.
Urban Driving retains specification frequency leadership; Highway Driving shows the steepest technology investment trajectory as thermal management integration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese supply chains while European OEMs absorb technology premiums for 800-volt platform integration. This asymmetry shapes procurement patterns across major EV manufacturing clusters.
China
Domestic EV production volumes dominate global output, with Shenzhen and Shanghai anchoring motor-generator manufacturing scale. MIIT energy recovery mandates for NEV certification compel domestic OEMs to specify high-performance regenerative hardware. Local suppliers in the Yangtze River Delta are expanding electromechanical module capacity to serve BYD, NIO, and Xpeng platform demand.
Germany
Premium passenger vehicle OEMs in Bavaria and Baden-Württemberg are mandating full regenerative architectures for battery-electric lineups. EU Green Deal CO2 fleet targets enforced by EMA coordination push suppliers toward higher-efficiency braking recuperation. Continental and ZF anchor manufacturing scale in Stuttgart and Friedrichshafen to serve Mercedes-Benz, BMW, and Volkswagen 800-volt platforms.
United States
EPA tailpipe emissions frameworks and NHTSA fuel economy standards penalize fleets with poor regenerative energy capture. Municipal bus operators in Los Angeles specify maximum energy recovery duty cycles to reduce charging infrastructure load. Silicon carbide inverter development clusters in the Pacific Northwest and Texas are raising motor-generator conversion efficiency for next-generation systems.
Japan
Denso, Aisin, and Hitachi Astemo leverage integrated electronics and precision manufacturing heritage to supply hybrid and battery-electric platforms. METI industrial policy supports domestic motor-generator production for export markets. Nagoya and Tokyo metropolitan manufacturing corridors concentrate electromechanical brake system engineering talent.
India
PLI scheme incentives for auto component manufacturing are attracting brake system suppliers to establish electromechanical module production. Domestic EV assembly is scaling in Gujarat and Tamil Nadu, creating localized demand for recuperative hardware. Tata Motors and Mahindra platform electrification timelines are compressing supplier qualification cycles.
Electric Vehicle Regenerative Braking System Market Competitive Landscape
Integrated system architects and component specialists split the market along technology depth versus manufacturing scale vectors. Consolidation pressures intensify as brake-by-wire architectures compress supplier value chains from multi-tier hydraulic assemblies to firmware-centric electromechanical modules. Three archetypes dominate: diversified automotive tier-1 conglomerates with chassis integration capabilities, electromechanical specialists with silicon carbide inverter expertise, and regional champions serving captive domestic OEM demand. Competitive moves center on strategic partnerships for 800-volt platform qualification and backward integration into rare earth magnet supply chains.
Among European diversified conglomerates, Robert Bosch GmbH and Continental AG exemplify integrated system architects with electronics and braking portfolio breadth. ZF Friedrichshafen AG occupies a position within the German industrial fabric as a complete brake-by-wire specialist. Denso Corporation and Aisin Corporation represent Japanese precision manufacturing heritage applied to motor-generator integration. These five entities anchor the competitive structure, with BorgWarner Inc. and Hyundai Mobis sitting within the tier-1 supplier tier serving regional OEM consolidation strategies.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Denso Corporation |
| ADVICS Co., Ltd. |
| Hyundai Mobis |
| Aisin Corporation |
| BorgWarner Inc. |
| Hitachi Astemo, Ltd. |
| Others |
Pricing and Supply Chain Analysis
Rare earth magnet processing concentration in China anchors margin distribution downstream, with neodymium supply quotas translating directly into cost premiums for European and North American OEMs sourcing motor-generator units. This upstream chokepoint forces brake system suppliers to absorb volatility or pass through pricing adjustments to fleet procurement departments already facing 800-volt platform cost pressures.
Pricing Analysis
Configured-to-order brake-by-wire systems command substantial premiums over standard hybrid recuperation hardware due to firmware customization and ASIL-D certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates full regenerative architectures from blended systems and parallel retrofit kits. Cost compression in the standard tier is intensifying because Chinese domestic suppliers are scaling electromechanical module production for BYD and NIO platforms. Municipal fleet operators in Los Angeles and Shenzhen exhibit the highest price sensitivity due to volume procurement mandates, while premium European OEMs absorb technology premiums with minimal negotiation leverage.
Supply Chain Analysis
Extended payment terms from European tier-1 suppliers to Asian semiconductor foundries are restructuring working capital requirements across the value chain. Motor-generator manufacturing concentrates in China, Germany, and Japan, with silicon carbide inverter fabrication anchored in Taiwan and South Korea. The supply chain draws from neodymium rare earths, copper windings, and high-grade steel forgings as critical inputs. Single-source vulnerability around Chinese rare earth export quotas poses structural risk to non-domestic automakers. Distribution runs through captive OEM supply agreements and direct-to-fleet channels, bypassing traditional aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV regenerative braking system market is entering a cyclical recovery phase as battery-electric platform volumes rebound from supply chain normalization and MIIT mandate enforcement accelerates domestic Chinese procurement.
For Market Incumbents: Harden software-defined braking control capabilities through ASIL-D certification investment to defend against emerging silicon carbide inverter specialists encroaching on electromechanical module specifications. Backward integration into rare earth magnet supply chains mitigates quota volatility exposure from Chinese processors. Capacity addition in Hungary and the Czech Republic serves European 800-volt platform demand with reduced logistics friction. For New Entrants and Emerging Players: Build out brake-by-wire firmware development capabilities targeting India's PLI scheme localization incentives, where Tata Motors and Mahindra platform electrification compresses supplier qualification cycles. The commercial vehicle segment offers the most penetrable white space as municipal fleet operators in California and Germany unbundle brake sourcing from traditional tier-1 chassis contracts. A direct purchasing relationship model with custom calibration specifications captures fleet procurement departments seeking operational range extension. For Investors and Strategic Acquirers: Capital is best deployed toward electromechanical specialists with silicon carbide inverter expertise and existing 800-volt platform qualification, positioned for long-term viability as brake-by-wire architectures consolidate supplier value chains. The acquisition target archetype combines firmware development depth with rare earth magnet supply relationships. The signal to watch is EU Green Deal brake particulate emission limit enforcement timelines, which will accelerate R&D spending and pre-qualification cycles two product cycles ahead of compliance dates.| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Platform Standardization | Consolidates hydraulic and electronic functions for Mercedes-Benz and BMW 800-volt architectures. |
| Silicon Carbide Inverter Supply Agreement | Secures Taiwan and South Korean foundry capacity for next-generation motor-generator efficiency gains. |
| Software-Defined Vehicle Investment | Aligns braking control firmware with steer-by-wire integration for premium chassis platforms. |
| Geographic Manufacturing Footprint Expansion | Establishes electromechanical module production in Gujarat and Tamil Nadu under India's PLI scheme. |
| Rare Earth Magnet Backward Integration | Reduces neodymium quota exposure through captive supply arrangements with Chinese processors. |
Research Methodology
The analysis maps full regenerative systems, hybrid architectures, electromechanical actuation modules, and brake-by-wire control electronics, each validated through OEM platform engineers, tier-1 supplier procurement leads, municipal fleet operations managers, and aftermarket distribution heads. Primary interviews with these stakeholders combined with secondary validation from vehicle production databases, MIIT NEV certification filings, EU EMA enforcement documentation, and SEC supplier filings establish demand-side triangulation. Bottom-up unit economics and top-down fleet adoption curves reconcile volume estimates across the projection horizon.
Assumption sets held battery-electric platform penetration and MIIT energy recovery mandate thresholds fixed while varying rare earth export quota volatility and silicon carbide foundry capacity expansion rates. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derive from fitted adoption curves across urban fleet electrification intensity and premium passenger vehicle 800-volt rollout pacing. Motor-generator efficiency trajectories and brake particulate emission compliance timelines serve as industry-specific forecast inputs.
Stress conditions across neodymium supply disruption severity, EU Green Deal enforcement acceleration, and battery state-of-charge limitation prevalence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
Mexico Automotive Electric Bus Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Electric Vehicle Rental Market
Electric Vehicles
E-SUV Market
Electric Vehicles
Electric Van Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Norway Electric Cars Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
One Wheel Electric Scooter Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market