
 Ignition Control Module Market | 2026-2036
Ignition Control Module Market Size, Share, and Industry Trends Forecast 2026-2036
Ignition Control Module Market Insights
East Asian semiconductor foundry capacity is hardening as a constraint on ignition control module output. Denso Corporation leverages captive chip supply to sustain delivery schedules for Toyota and Honda programs. Robert Bosch GmbH anchors European module production through its Stuttgart engineering campus. BorgWarner Inc. competes by specializing in high-energy ignition architectures for turbocharged direct-injection engines.
An ignition control module is an electronic switch that interrupts and directs current flow to ignition coils based on crankshaft position sensor input, typically operating at 300-400 volts and switching frequencies above 1,000 Hz to ensure precise spark timing. Its primary purpose is to optimize combustion efficiency, reduce emissions, and protect engine hardware from knock or misfire damage. Integrated Systems command the widest OEM fitment due to their combined coil-driver and diagnostic functionality, while Smart Controllers represent the fastest-expanding category as embedded algorithms enable cylinder-deactivation and real-time knock suppression. Analog Systems retain aftermarket dominance because repair shops prioritize plug-compatible replacements over digital upgrades.
EPA tailpipe standards and NHTSA fuel-economy mandates in the United States compel module suppliers to certify ignition precision across broader engine load maps. EMA and Euro 7 preparatory rules in Europe extend testing to cold-start hydrocarbon phases, forcing hardware redesigns. Japan's METI administers JIS quality benchmarks that govern module durability claims for domestic vehicle manufacturers. Stakeholders must monitor how EPA enforcement intensity and Euro 7 final calibration deadlines reshape R&D budgets and supplier qualification timelines.
Market Dynamics
Semiconductor foundry concentration in Taiwan and South Korea is compressing ignition control module output timelines, forcing OEMs to qualify alternative chip architectures and dual-source coil-driver ASICs to protect assembly schedules.
Growth Catalysts
- EPA Tier 3 Enforcement:United States emissions deadlines are accelerating module redesign cycles for lean-burn spark timing precision, expanding addressable hardware content per engine.
- Commercial Fleet Electrification Hybrids:Class 8 truck OEMs retain combustion ignition subsystems in range-extender architectures, sustaining module demand through powertrain transition phases.
- Euro 7 Cold-Start Hydrocarbon Limits:European preparatory testing protocols are mandating faster spark energy modulation, pulling upgraded Smart Controller volumes into 2026-2027 model years.
Market Restraints
- 300mm Wafer Allocation:Automotive-grade MOSFET and IGBT die from TSMC and Samsung Foundry face consumer electronics competition, extending lead times for high-voltage switching components.
- Legacy Analog Aftermarket Lock-In:Independent repair shops prioritize plug-compatible replacement modules over digital upgrades, constraining Smart Controller penetration in vehicle parc maintenance.
- Platinum Group Metal Volatility:Spark plug electrode costs fluctuate with palladium and rhodium mining output, pressuring total ignition system bill-of-materials for price-sensitive economy segments.
Strategic Opportunities
- India BS-VI Phase 2 Transition:Domestic two-wheeler and light commercial vehicle production is adopting electronic ignition modules to meet particulate and NOx mandates, opening greenfield supplier qualification windows.
- Cylinder Deactivation Algorithm Licensing:Embedded knock suppression software represents unmonetized IP layer atop hardware sales, enabling recurring revenue from powertrain calibration updates.
- Direct-to-Fleet Digital Distribution:Commercial vehicle operators are bypassing traditional jobber networks for module procurement, compressing channel margins but expanding addressable contract value.
Industry Challenges
- Functional Safety Certification Burden:ISO 26262 ASIL-D compliance for ignition timing fault detection demands specialized firmware validation teams, stretching engineering headcount at mid-tier suppliers.
- Legacy Powertrain Integration Friction:Smart Controller architectures must maintain backward compatibility with 1990s-era engine management protocols, complicating software stack maintenance and testing matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ignition Control Module Market |
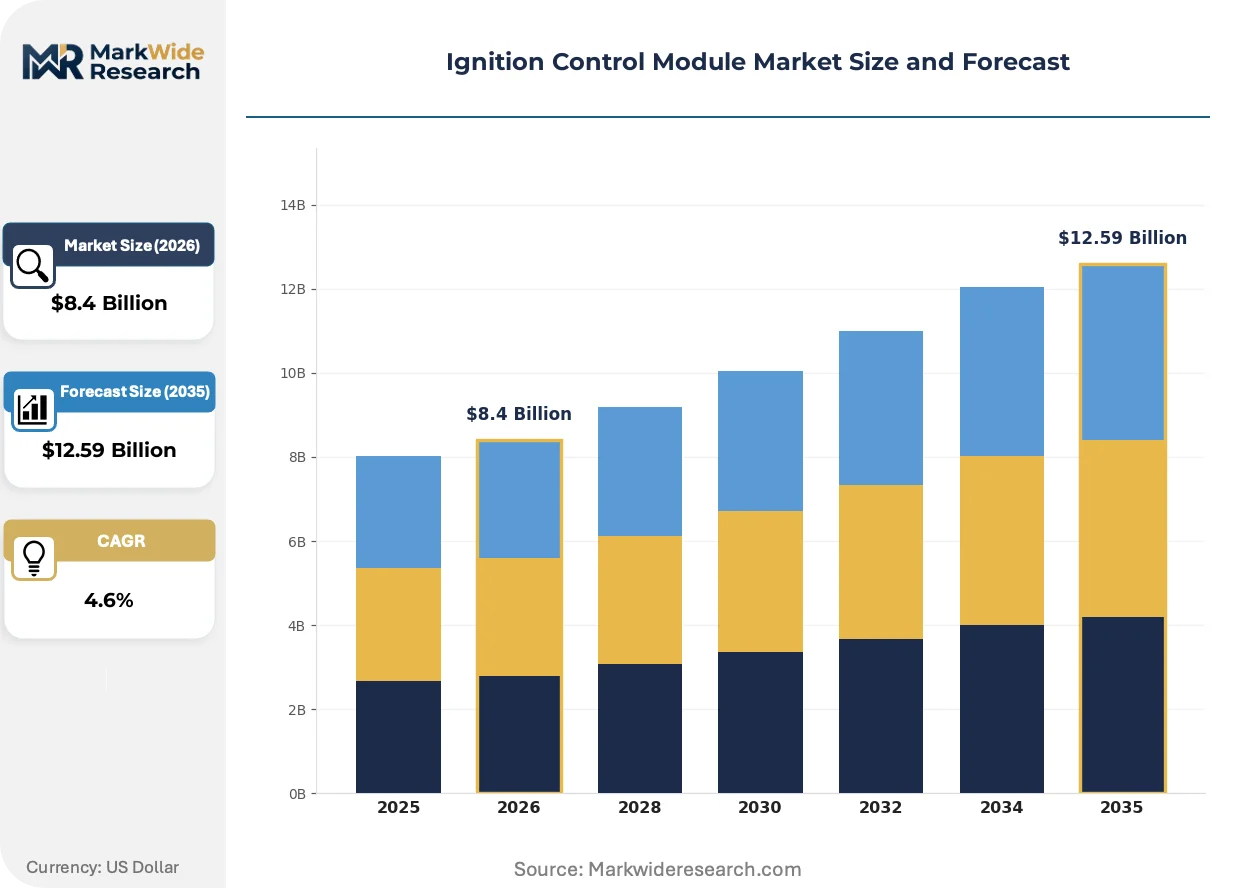
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete Modules, Integrated Systems, Smart Controllers, Standard Controllers End User: OEMs, Aftermarket Providers, Vehicle Manufacturers, Repair Shops Technology: Analog Systems, Digital Systems, Hybrid Systems, Microcontroller-Based Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks |
| Companies Covered | BorgWarner Inc., Denso Corporation, Robert Bosch GmbH, Mitsubishi Electric Corporation, Hitachi Astemo, Valeo SA, Standard Motor Products, NGK Spark Plug Co., Ltd., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ignition Control Module Market Trends and Innovations
Silicon carbide power electronics and edge-computing ignition algorithms are converging to redefine spark energy management, compressing the gap between combustion precision and electrified powertrain control fidelity.
Gallium nitride gate drivers are integrating into next-generation coil-driver circuits, replacing silicon MOSFETs in high-frequency switching applications above 1,500 Hz. Turbocharged direct-injection engine platforms from European and Japanese OEMs are adopting these architectures first to achieve sub-millisecond spark timing resolution. This integration is compressing the performance gap between discrete analog modules and full engine control units, enabling distributed ignition intelligence.
REACH substance restrictions on lead-bearing solders and halogenated flame retardants are forcing module suppliers to requalify PCB laminates and connector metallurgy for European type approval. The industrial consequence is extended validation timelines for surface-mount ignition drivers, with redesign cycles now spanning 18-24 months for Euro 7-compliant hardware. Passenger car programs targeting 2027 production slots are most affected, with several German OEMs accelerating supplier lock decisions to secure capacity.
Fleet procurement departments are consolidating ignition module purchasing into powertrain system-level contracts rather than discrete component sourcing. Tier 1 suppliers with captive electronics manufacturing are displacing standalone module vendors in commercial vehicle RFQs, bundling ignition control with fuel injection and aftertreatment hardware. This concentration is most visible in North American Class 6-8 truck segments, where vertical integration into engine manufacturing is tightening supplier panels to three approved sources per OEM.
Ignition Control Module Market Segmentation
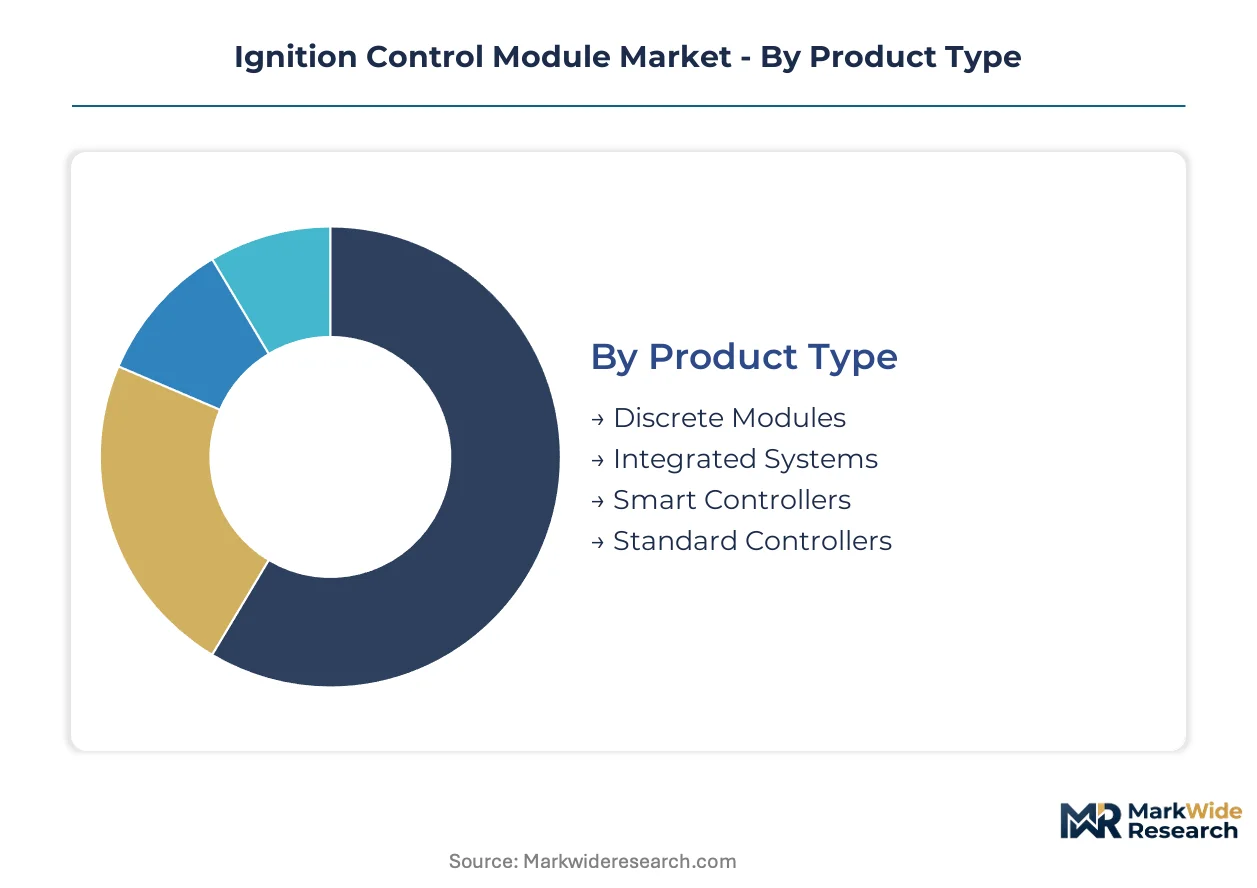
Ignition control module procurement patterns diverge sharply across product architectures and customer channels. Capital allocation, regulatory compliance burdens, and backward integration strategies vary meaningfully by segment, reshaping supplier competitive position.
Product Type:
Capital intensity concentrates in segments requiring ASIC development and functional safety certification.
- Integrated Systems:Combine coil-driver circuitry with onboard diagnostics in single-package architectures. Passenger car OEMs in Germany and Japan specify these for turbocharged direct-injection platforms to meet Euro 7 and JIS durability benchmarks.
- Smart Controllers:Embed cylinder-deactivation algorithms and real-time knock suppression via edge-computing firmware. Commercial vehicle powertrain divisions specify these for range-extender hybrid architectures to optimize spark timing across load cycles.
- Discrete Modules:Single-function switching devices for legacy distributor-based ignition systems.
- Standard Controllers:Fixed-timing modules without adaptive spark control capabilities.
Integrated Systems absorb the bulk of installed capacity; Smart Controllers are expanding most quickly.
End User:
Channel concentration determines pricing power and technical support requirements.
- OEMs:Direct supply relationships with engine manufacturers demand ISO 26262 ASIL-D certification and captive semiconductor sourcing. Toyota and Honda programs in Japan require Denso's vertically integrated chip supply to protect assembly schedules.
- Vehicle Manufacturers:Final assembly operations specify module performance parameters but increasingly delegate subsystem procurement to Tier 1 powertrain integrators.
- Aftermarket Providers:Distributors serving independent repair networks prioritize inventory breadth over technical differentiation.
- Repair Shops:Service bay operators favor plug-compatible replacements that minimize diagnostic time and technician retraining.
OEMs command the steepest supplier qualification barriers; Vehicle Manufacturers are consolidating procurement into system-level contracts.
Technology:
Semiconductor content and firmware complexity separate margin profiles.
- Digital Systems:Microprocessor-controlled spark timing with closed-loop feedback from crankshaft position sensors. EPA Tier 3 enforcement in the United States accelerates fitment for lean-burn combustion precision.
- Microcontroller-Based:Dedicated MCU architectures with embedded flash for calibration storage. European OEMs specify these for Euro 7 cold-start hydrocarbon compliance requiring sub-millisecond energy modulation.
- Analog Systems:Transistor-switched modules without programmable timing maps.
- Hybrid Systems:Mixed-signal architectures combining analog switching with digital monitoring.
Digital Systems carry the heaviest R&D burden; Microcontroller-Based architectures are climbing the fastest as embedded algorithm licensing creates recurring revenue streams.
Vehicle Type:
Engine duty cycles and emissions exposure shape module specification intensity.
- Commercial Vehicles:Class 6-8 trucks and range-extender hybrids sustain demand for high-energy ignition architectures. North American fleet electrification programs retain combustion subsystems, pulling Smart Controller volumes into heavy-duty powertrain contracts.
- Passenger Cars:Light vehicle production volumes concentrate module demand in Germany, China, and the United States, where engine manufacturing clusters align with final assembly capacity.
- Heavy-Duty Trucks:Long-haul applications prioritize durability certification under extended thermal cycling.
- Motorcycles:Two-wheeler OEMs in India adopt electronic ignition modules for BS-VI Phase 2 compliance.
Commercial Vehicles generate the highest per-unit module value; Passenger Cars dominate absolute volume consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon carbide substrate availability from Japanese and Chinese suppliers anchors geographic production capacity for ignition control module manufacturing clusters.
United States
Class 8 truck electrification programs sustain combustion ignition subsystem demand through range-extender hybrid architectures. EPA Tier 3 enforcement tightens spark timing precision requirements for lean-burn compatibility across 2026-2027 model years. Detroit-Warren manufacturing corridor concentrates module procurement decisions for Ford and General Motors powertrain divisions.
Germany
Turbocharged direct-injection engine platforms from BMW and Mercedes-Benz pull high-energy ignition module volumes. Euro 7 cold-start hydrocarbon testing protocols mandate faster energy modulation hardware for 2027 production slots. Stuttgart engineering campus anchors Continental and Robert Bosch module development and qualification timelines.
China
Domestic engine manufacturing clusters absorb incremental module volume as local OEMs electrify light commercial vehicle fleets. MIIT administered GB standards govern ignition system durability claims for domestic vehicle manufacturers. Yangtze River Delta concentration of foundry capacity shapes semiconductor allocation priorities for module suppliers.
Japan
Toyota and Honda hybrid powertrain programs retain ignition control modules in range-extender configurations. METI oversees JIS quality benchmarks that module suppliers must satisfy for domestic OEM qualification. Aichi Prefecture manufacturing belt concentrates Denso captive chip supply and module assembly operations.
India
Two-wheeler and light commercial vehicle OEMs adopt electronic ignition modules for BS-VI Phase 2 particulate compliance. Central Pollution Control Board enforcement timelines compress supplier qualification windows for domestic manufacturers. Tamil Nadu and Gujarat production corridors concentrate module demand from Hero MotoCorp and Bajaj Auto assembly plants.
Ignition Control Module Market Competitive Landscape
Global majors compete with regional champions across semiconductor sourcing and functional safety certification dimensions. The vendor base stratifies into three tiers: integrated powertrain suppliers with captive electronics, standalone ignition specialists, and aftermarket-focused analog module producers. Strategic differentiation centers on ASIC development capability and ISO 26262 ASIL-D compliance infrastructure. Competitive moves concentrate on backward integration into coil-driver semiconductor supply and algorithm licensing for cylinder-deactivation software.
Among Japanese industrial conglomerates, Denso Corporation and Mitsubishi Electric Corporation exemplify the vertically integrated archetype with captive foundry relationships and in-house semiconductor production. Robert Bosch GmbH anchors the European engineering-intensive tier through Stuttgart-based module development and qualification operations. BorgWarner Inc. occupies a position among North American powertrain integrators specializing in high-energy ignition architectures for forced-induction engine platforms.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Denso Corporation |
| Robert Bosch GmbH |
| Mitsubishi Electric Corporation |
| Hitachi Astemo |
| Valeo SA |
| Standard Motor Products |
| NGK Spark Plug Co., Ltd. |
| Continental AG |
| Others |
Pricing and Supply Chain Analysis
Semiconductor wafer costs cascade through ignition control module pricing tiers, with automotive-grade MOSFET die from Taiwan and South Korea feeding premium Smart Controller architectures while commodity analog modules absorb silicon price volatility in economy segments serving aftermarket repair networks.
Pricing Analysis
Warranty bundling separates OEM contract pricing from aftermarket transactions, with multi-year durability guarantees commanding 15-25% premiums over unbundled module sales. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 ASIL-D certification status, captive semiconductor sourcing, and algorithm licensing inclusions. Price erosion runs through economy analog modules as Chinese producers expand capacity for India BS-VI Phase 2 qualification. Fleet procurement departments exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while independent repair shops prioritize plug-compatible replacements at minimum acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Toyota, Honda, and BMW powertrain divisions, while aftermarket distribution runs through jobber networks serving independent repair shops. Manufacturing concentrates in Germany, Japan, and China, with Stuttgart and Aichi Prefecture anchoring engineering-intensive production and Yangtze River Delta foundry capacity feeding domestic Chinese OEM demand. Raw material dependencies include silicon carbide substrates, palladium-bearing spark plug electrodes, and halogen-free PCB laminates. Single-source vulnerability in Taiwan and South Korean 300mm wafer allocation presents structural risk, compelling dual-source qualification for coil-driver ASICs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ignition control module competition has become a vertical-integration race, with captive semiconductor supply and embedded algorithm IP serving as the decisive levers for margin defense and pricing power.
For Market Incumbents: Acquire foundry capacity or secure long-term wafer offtake agreements to protect against TSMC and Samsung allocation constraints. Lock Euro 7-compliant Smart Controller designs through Stuttgart or Aichi engineering campus investments before 2027 production slots close. Denso's captive chip supply model demonstrates how backward integration insulates delivery schedules from semiconductor volatility. For New Entrants and Emerging Players: Fleet procurement departments represent the most penetrable channel, as commercial vehicle operators consolidate ignition module purchasing into powertrain system-level contracts and bypass traditional jobber networks. Target India BS-VI Phase 2 qualification windows for two-wheeler and light commercial vehicle OEMs, where greenfield supplier status carries less incumbent disadvantage. Lead with cylinder-deactivation algorithm licensing to create recurring revenue streams atop hardware margins. For Investors and Strategic Acquirers: EPA Tier 3 enforcement intensity is the leading indicator that R&D budget allocation toward lean-burn spark timing precision will separate viable suppliers from commodity analog producers. Over a multi-year horizon, module suppliers with ISO 26262 ASIL-D certification infrastructure and embedded firmware capabilities will command acquisition premiums. Watch for Euro 7 final calibration deadlines as the signal for supplier panel consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Sourcing | TSMC and Samsung Foundry allocation constraints make wafer offtake agreements critical for delivery reliability. |
| Functional Safety Certification | ISO 26262 ASIL-D compliance opens OEM qualification pathways for turbocharged direct-injection platforms. |
| Algorithm Licensing Programs | Cylinder-deactivation and knock suppression software create recurring revenue beyond discrete hardware sales. |
| Dual-Source ASIC Qualification | Alternative coil-driver architectures protect assembly schedules from single-foundry dependency risk. |
| Fleet Direct Distribution | Commercial vehicle procurement consolidation rewards suppliers with powertrain system bundling capabilities. |
Research Methodology
Independent corroboration across OEM powertrain procurement directors, Tier 1 supplier engineering leads, and aftermarket distributor operations managers underwrites the qualitative findings. Primary fieldwork with semiconductor foundry account executives, EPA compliance officers, and METI standards administrators combined with secondary validation from vehicle production databases, SEC 10-K automotive segment disclosures, and IHS Markit registration data. Bottom-up module shipment estimates and top-down powertrain production forecasts were reconciled through iterative triangulation.
Comparable historical reference periods anchored the projection horizon, with growth trajectories derived from segment-specific adoption curves for Smart Controller architectures across commercial and passenger vehicle applications. Modeling incorporated product type segmentation, technology tier differentiation, vehicle class duty cycles, and regional regulatory cluster alignment. CAGRs were computed from annualized shipment value progression, with semiconductor allocation constraints and Euro 7 calibration timelines serving as key forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including unannounced EPA enforcement intensity shifts, foundry capacity expansion timelines, and palladium price volatility effects on total ignition system economics. Forecasts reflect assumptions about hybrid powertrain retention of combustion subsystems and algorithm licensing monetization rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Automotive Launch Control System Market
Automotive Circuit Systems
Traction Control System Market
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Automotive Pressure Switch Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Steering Column Control Modules Market