
 Automotive Climate Control Market | 2026-2036
Automotive Climate Control Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Climate Control Market Intelligence
The shortage of thermal systems engineers is collapsing development timelines across the supplier base. Denso Corporation leverages its integrated compressor and power electronics portfolio to anchor Japanese OEM relationships. MAHLE GmbH competes through R&D intensity in refrigerant-based architectures. Valeo sustains European market presence with manufacturing scale across France and Spain.
Automotive climate control encompasses the integrated thermal management systems that regulate cabin temperature, humidity, and air quality through heat exchange, refrigerant cycles, and electronic control modules operating at pressures up to 35 bar in R-1234yf systems. Its primary purpose is ensuring occupant comfort while optimizing energy consumption in conventional and electric powertrains. Electric technology leads investment allocation as heat pump architectures displace resistive heating in battery electric vehicles. Passenger Vehicles occupies the dominant application tier, though Electric Vehicles represents the fastest-growing demand pool for dedicated battery thermal management integration.
NHTSA cabin safety standards, EPA refrigerant compliance under SNAP rules, and EU F-Gas Regulation collectively constrain refrigerant selection and system efficiency benchmarks across major supply corridors. These frameworks force suppliers to redesign compressor architectures and validate alternative working fluids under tighter emissions envelopes. Stakeholders must monitor regulatory divergence between California Air Resources Board pathways and EU MEE enforcement timelines to avoid stranded development investments.
Market Dynamics
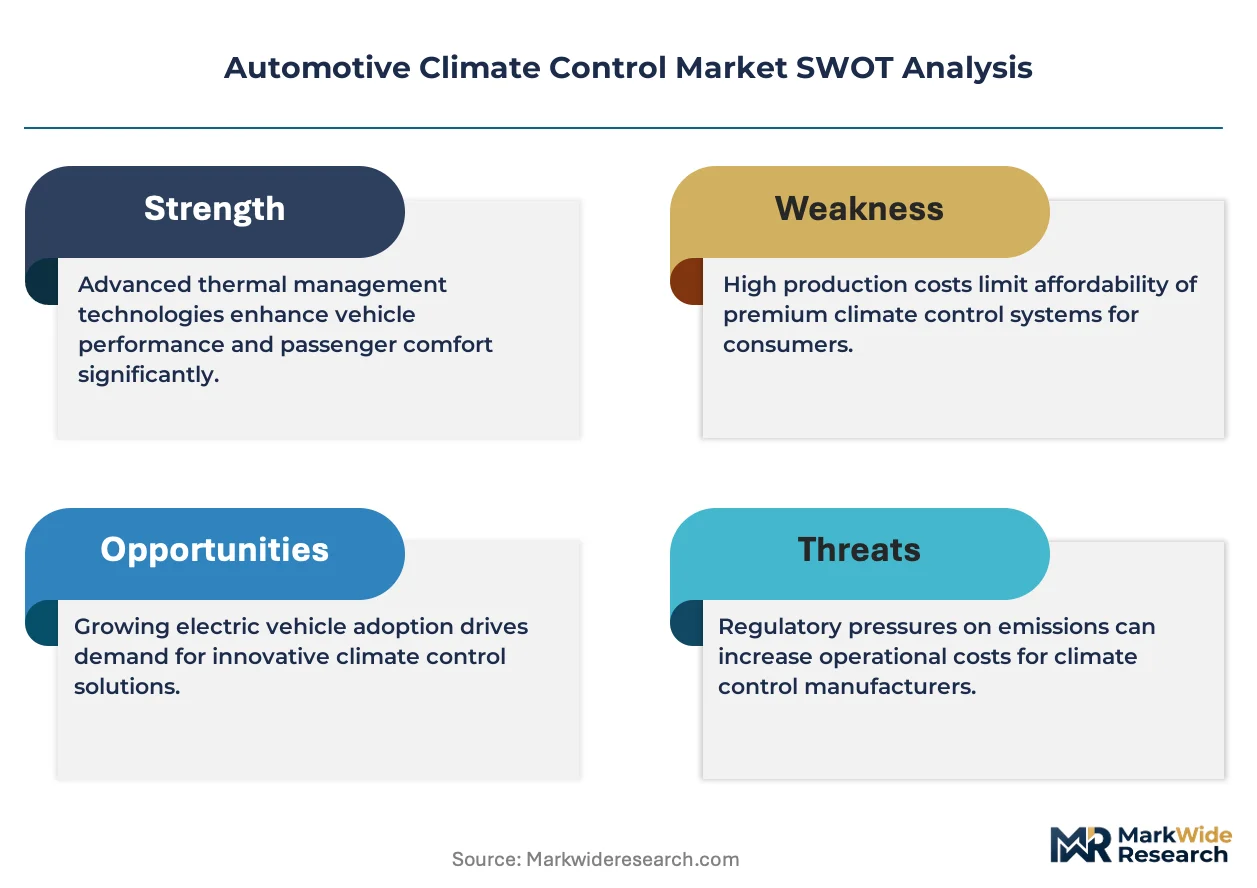
Heat pump architectures are displacing resistive heating in battery electric vehicles, forcing suppliers to redesign compressor portfolios and thermal management software stacks while OEMs consolidate procurement around integrated system vendors.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants is accelerating R-1234yf and CO₂ system deployments across European OEM supply chains, creating retrofit demand for compressor redesigns.
- Battery thermal management:Electric vehicle manufacturers require dedicated cooling circuits for lithium-ion packs, expanding the addressable hardware envelope beyond cabin comfort into powertrain protection.
- Shanghai-Shenzhen corridor:Chinese domestic OEMs are localizing climate control procurement, building captive supplier ecosystems for heat pump and intelligent HVAC modules.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger manufacturing faces margin compression from base metal price swings, constraining long-term contract pricing flexibility.
- Refrigerant supply concentration:R-1234yf production concentrates among three chemical suppliers, creating single-source vulnerability for tier-one system integrators.
- Heat pump cold-weather performance:Coefficient of performance degradation below minus fifteen degrees Celsius limits BEV adoption in Nordic and North American winter markets without supplemental resistive backup.
Strategic Opportunities
- India PLI scheme for auto components:Component suppliers can access production-linked incentives by establishing local compressor and heat exchanger capacity for domestic OEMs and export markets.
- Predictive thermal software:Integration of cabin preconditioning algorithms with navigation and charging data creates recurring revenue streams through over-the-air feature activation.
- Refrigerant reclamation infrastructure:End-of-life vehicle regulations in Germany and France mandate recovery systems, opening service network equipment sales to independent garages and dealer groups.
Industry Challenges
- Thermal systems engineering scarcity:The supplier base faces collapsed development timelines as OEMs accelerate EV platform launches without sufficient two-phase flow and controls specialists.
- Multi-refrigerant validation burden:Suppliers must maintain parallel certification tracks for R-134a, R-1234yf, and CO₂ architectures, stretching testing facility capacity and engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Climate Control Market |
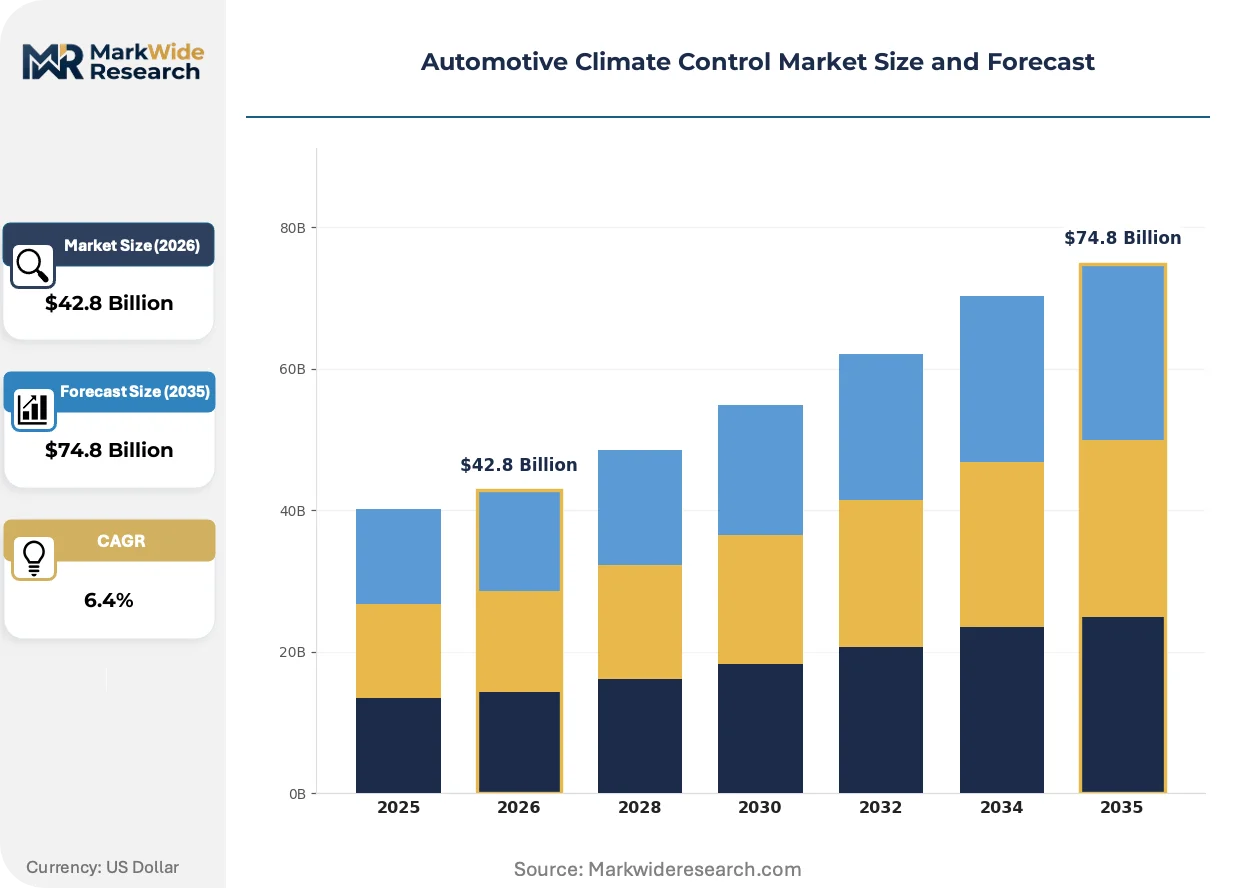
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Systems, Air Conditioning, Ventilation Systems, Climate Control Modules Technology: Electric, Mechanical, Hybrid, Refrigerant-Based End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | MAHLE GmbH, Keihin Corporation, Denso Corporation, Gentherm Incorporated, BorgWarner Inc., Valeo, Sanden Holdings Corporation, Continental AG, Hanon Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Climate Control Market Strategic Shifts & Innovations
Refrigerant chemistry, control electronics, and thermal software are converging to redefine system architecture. Suppliers now compete on integrated energy management rather than discrete component performance.
CO₂ transcritical heat pump cycles are displacing conventional refrigerant architectures in cold-climate BEV applications. Scandinavian and German OEMs have adopted the technology for flagship electric platforms. The shift is compressing development timelines for compressor suppliers and forcing new sealing and pressure vessel competencies.
The EU F-Gas Regulation mandates an eighty percent reduction in refrigerant global warming potential by 2030. System suppliers must redesign expansion valves and compressors for lower-GWP working fluids. European OEMs are accelerating validation timelines to avoid stranded inventory ahead of enforcement deadlines.
Fleet operators are unbundling climate control service contracts from vehicle procurement, selecting thermal system providers on total cost of ownership metrics including energy consumption and predictive maintenance coverage. This reconfiguration is most advanced in German commercial vehicle leasing channels, where uptime guarantees now include cabin thermal performance.
Automotive Climate Control Market Segmentation
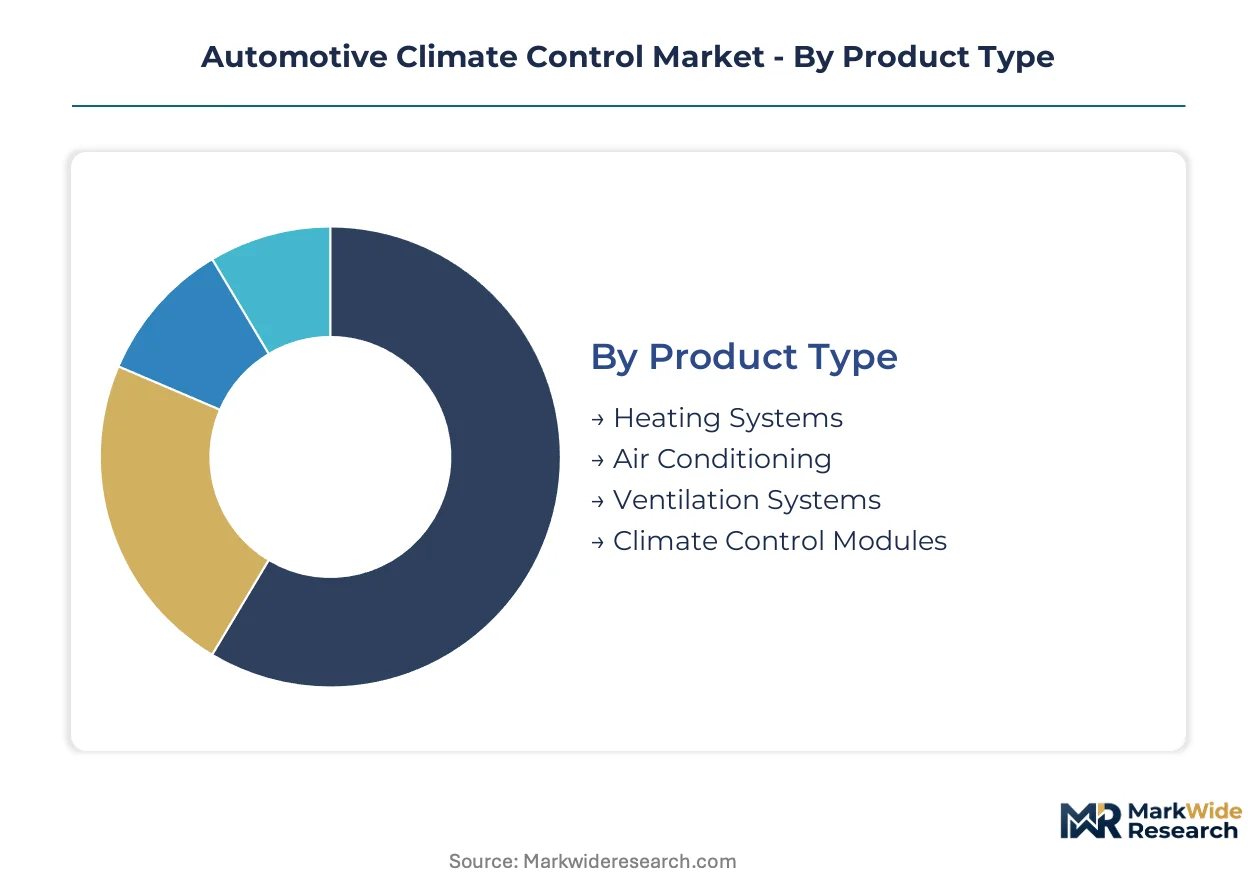
Segmentation in automotive climate control reveals how thermal management value pools are fragmenting across powertrain electrification and regulatory compliance axes. Suppliers must calibrate portfolio depth against which segments face imminent technology substitution versus incremental upgrade cycles.
Product Type:
Air Conditioning faces the strongest substitution pressure as heat pump architectures displace conventional vapor-compression systems in battery electric vehicles.
- Heating Systems:Resistive heaters and coolant-based cabin heaters dominate internal combustion engine architectures. Demand is concentrating in Nordic markets where supplemental resistive backup addresses heat pump coefficient-of-performance degradation below minus fifteen degrees Celsius.
- Air Conditioning:Vapor-compression cycles using R-1234yf or CO₂ refrigerants regulate cabin temperature through evaporator-condenser heat exchange. European OEM supply chains are accelerating R-1234yf deployments ahead of EU F-Gas Regulation phasedown deadlines, forcing compressor redesigns across German and French manufacturing footprints.
- Ventilation Systems:Air distribution ducts, blower motors, and cabin air filtration modules manage airflow rates and particulate removal.
- Climate Control Modules:Electronic control units integrating temperature sensors, servo motors, and human-machine interface logic.
Air Conditioning retains volume leadership; Climate Control Modules hold the steepest expansion curve as software-defined thermal management gains share.
Technology:
Cost tier differentiation separates premium integrated heat pump architectures from economy mechanical systems serving price-sensitive vehicle classes.
- Electric:High-voltage compressor drives and intelligent HVAC modules enable predictive cabin preconditioning. Chinese domestic OEMs along the Shanghai-Shenzhen corridor are localizing procurement of electric thermal systems, building captive supplier ecosystems for heat pump and intelligent HVAC modules.
- Mechanical:Belt-driven compressors and cable-actuated temperature controls serve entry-level internal combustion engine vehicles. Demand concentrates in India and Southeast Asian markets where production-linked incentive schemes support local compressor and heat exchanger capacity.
- Hybrid:Dual-mode systems combining engine waste heat recovery with electric auxiliary heating.
- Refrigerant-Based:Closed-loop vapor compression cycles dependent on working fluid chemistry selection.
Electric technology commands the premium cost tier; Mechanical systems anchor volume production in emerging markets.
End User:
Customer type determines specification authority, with OEMs holding design control versus aftermarket providers serving replacement demand.
- OEMs:Vehicle manufacturers specifying system architecture and validating supplier designs against platform requirements. German and Japanese OEMs are consolidating procurement around integrated system vendors capable of delivering compressor, power electronics, and thermal management software stacks.
- Aftermarket Providers:Independent distributors and service networks supplying replacement compressors, condensers, and refrigerant recharge services. German and French end-of-life vehicle regulations mandate refrigerant recovery systems, opening service network equipment sales to independent garages and dealer groups.
- Tier-1 Suppliers:System integrators managing sub-tier component sourcing and vehicle-level assembly integration.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations purchasing complete HVAC modules.
OEMs retain specification authority; Aftermarket Providers are gaining share fastest as vehicle parc expansion extends replacement cycles.
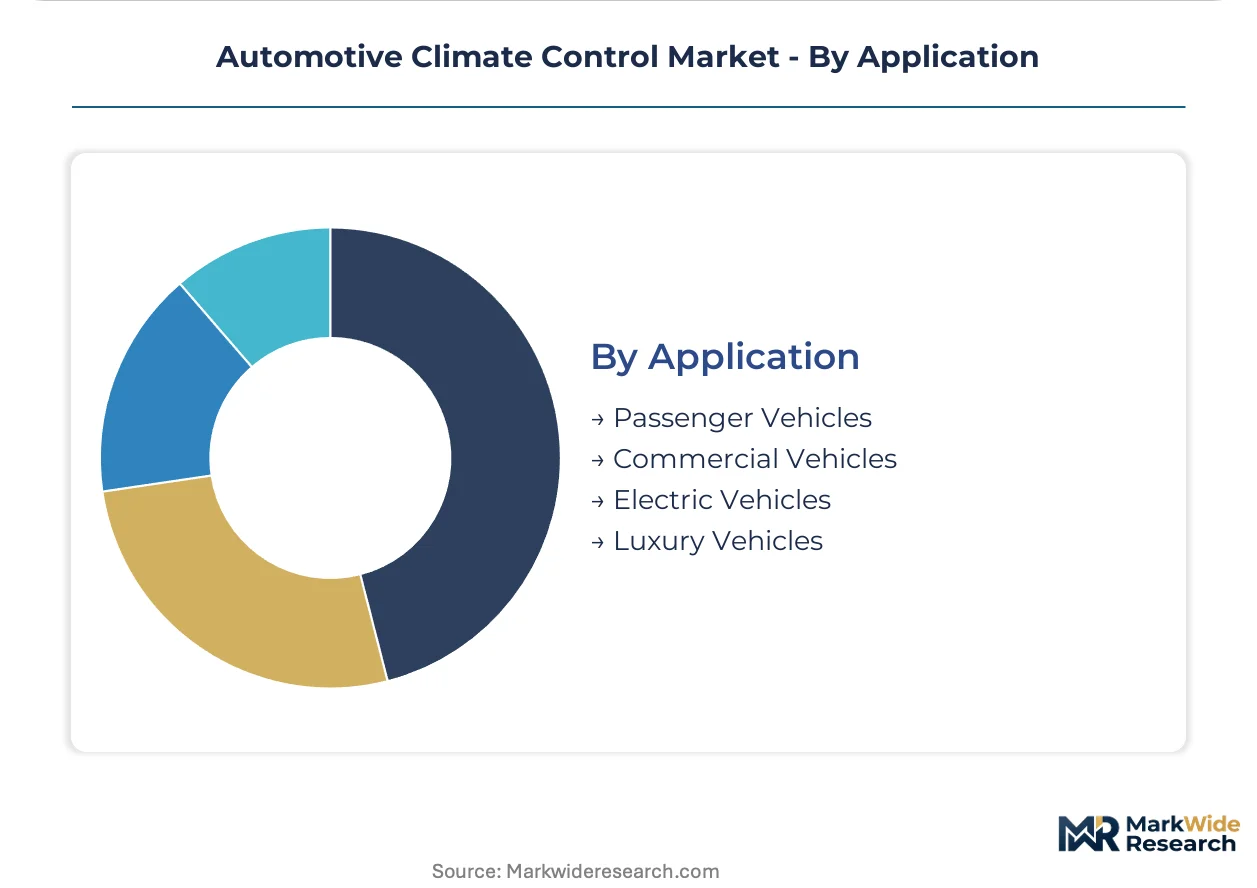
Application:
Volume concentration varies sharply across vehicle classes, with passenger vehicles representing installed base scale versus electric vehicles driving technology refresh rates.
- Passenger Vehicles:Light-duty cars and SUVs representing the dominant installed base for cabin thermal management. United States and Chinese markets concentrate bulk demand, with supplier manufacturing footprints anchored in Michigan, Ohio, and the Yangtze River Delta.
- Electric Vehicles:Battery electric platforms requiring dedicated battery thermal management circuits beyond cabin comfort. Scandinavian and German OEMs have adopted CO₂ transcritical heat pump cycles for flagship electric platforms, compressing development timelines for compressor suppliers.
- Commercial Vehicles:Medium and heavy-duty trucks with extended duty cycles and sleeper cab climate requirements.
- Luxury Vehicles:Premium segments specifying multi-zone climate control and air quality management.
Passenger Vehicles retain volume leadership; Electric Vehicles are expanding most quickly as heat pump architectures penetrate battery electric platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European OEMs prioritize low-GWP refrigerant transitions under regulatory deadlines. Chinese manufacturers emphasize localized heat pump procurement for cost control. North American demand concentrates on cold-climate performance validation.
China
Domestic OEMs along the Shanghai-Shenzhen corridor are localizing climate control procurement for battery thermal management integration. The MIIT enforces dual carbon goals that accelerate electric vehicle platform launches. Yangtze River Delta manufacturing clusters now host captive supplier ecosystems for intelligent HVAC modules.
Germany
Scandinavian and domestic OEMs have adopted CO₂ transcritical heat pump cycles for flagship electric platforms. The EU F-Gas Regulation mandates eighty percent GWP reduction by 2030, compressing compressor redesign timelines. Manufacturing footprints concentrate in Bavaria and Baden-Württemberg for R-1234yf system validation.
United States
Fleet operators in Michigan and Ohio are unbundling climate control service contracts from vehicle procurement. NHTSA cabin safety standards constrain refrigerant selection alongside EPA SNAP rules. The Midwest manufacturing corridor anchors supplier assembly capacity for integrated thermal management systems.
Japan
Integrated compressor and power electronics portfolios anchor relationships with domestic OEMs. METI industrial policy supports heat pump R&D intensity for export competitiveness. Nagoya-based manufacturing clusters specialize in high-pressure sealing competencies for next-generation refrigerant architectures.
India
Entry-level internal combustion engine vehicles sustain mechanical system demand in price-sensitive segments. The PLI scheme for auto components incentivizes local compressor and heat exchanger capacity. Tamil Nadu and Maharashtra industrial corridors attract tier-one suppliers establishing export-oriented manufacturing.
Automotive Climate Control Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around system-level procurement. Japanese and German conglomerates anchor the upper tier through captive electronics and compressor integration. Mid-tier specialists compete on refrigerant architecture R&D or regional manufacturing scale. Dominant competitive moves include strategic partnerships for software-defined thermal management and geographic expansion into Chinese domestic OEM supply chains.
Within the integrated systems tier, Denso Corporation and MAHLE GmbH occupy anchor positions representing Japanese and German engineering archetypes respectively. Valeo exemplifies European manufacturing scale concentration. These entities sit within a competitive set where portfolio breadth determines OEM consolidation patterns rather than discrete component performance alone.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Keihin Corporation |
| Denso Corporation |
| Gentherm Incorporated |
| BorgWarner Inc. |
| Valeo |
| Sanden Holdings Corporation |
| Continental AG |
| Hanon Systems |
| Others |
Cost & Logistics Intelligence
Compressor manufacturing scale in the Yangtze River Delta and Bavaria anchors cost structures across the supplier base, concentrating pricing power among integrated system vendors while fragmenting margin capture for component specialists serving price-sensitive mechanical segments.
Pricing Analysis
Long-term offtake agreements dominate procurement between German and Japanese OEMs and tier-one system integrators, compressing spot market liquidity for discrete components. Three-tier pricing structure across premium electric heat pump, standard hybrid architectures, and economy mechanical systems differentiates on software integration depth and refrigerant architecture certification. Cost compression in entry-level segments intensifies as Indian domestic OEMs leverage PLI scheme localization for compressor procurement. Fleet operators exhibit lowest price sensitivity, prioritizing total cost of ownership metrics including energy consumption and predictive maintenance coverage over upfront system cost.
Supply Chain Analysis
R-1234yf refrigerant synthesis capacity concentrates among three chemical suppliers in the United States and China, creating single-source vulnerability for tier-one climate system integrators. Heat exchanger manufacturing draws from copper and aluminum feedstocks sourced through Chilean mining operations and Chinese smelter capacity. Tariff exposure on processed aluminum from key trading partners elevates input cost volatility for European and North American assembly footprints. Distribution runs through just-in-time module delivery to OEM platform assembly lines, with aftermarket service networks maintaining regional refrigerant reclamation equipment inventories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM procurement consolidation around integrated thermal management vendors has shifted bargaining power toward buyers, compressing margin capture for discrete component suppliers and elevating scale requirements for competitive participation.
For Market Incumbents: Compound software-defined thermal management capabilities through predictive cabin preconditioning algorithms to defend against emerging pure-play thermal software entrants. Anchor manufacturing scale in the Shanghai-Shenzhen corridor to match Chinese domestic OEM localization mandates. Prioritize R-1234yf and CO₂ architecture certification investment ahead of EU F-Gas Regulation enforcement timelines to avoid stranded development capacity. For New Entrants and Emerging Players: Lead with refrigerant reclamation infrastructure sales to independent garages and dealer groups under German and French end-of-life vehicle mandates as the most penetrable aftermarket entry point. Target predictive thermal software integration with navigation and charging data as a white-space recurring revenue stream. Deploy over-the-air feature activation as the primary go-to-market mechanism to bypass capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated compressor and power electronics portfolios over discrete component specialists as heat pump architectures displace conventional systems. Long-term viability concentrates in suppliers capable of spanning refrigerant chemistry, high-voltage drive electronics, and thermal software stacks. Monitor EU MEE enforcement timelines against California Air Resources Board pathway divergence as the critical inflection signal for stranded asset risk in single-refrigerant certification tracks.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Architecture Standardization | CO₂ transcritical cycle adoption by Scandinavian and German OEMs compresses supplier development timelines for cold-climate BEV performance. |
| Battery Thermal Management Integration | Dedicated cooling circuits for lithium-ion packs expand hardware envelopes beyond cabin comfort into powertrain protection for electric platforms. |
| Refrigerant Reclamation Infrastructure | German and French end-of-life regulations mandate recovery systems, opening equipment sales to independent garages and dealer service networks. |
| Predictive Thermal Software Development | Cabin preconditioning algorithms integrated with navigation and charging data create recurring revenue through over-the-air feature activation. |
| Geographic Manufacturing Footprint Expansion | India PLI scheme incentives attract tier-one suppliers establishing local compressor and heat exchanger capacity for domestic OEM and export markets. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with thermal systems engineers, OEM platform procurement managers, tier-one supplier R&D directors, and aftermarket distribution channel heads; and secondary validation against vehicle production databases, IHS Markit registration data, EPA SNAP refrigerant compliance filings, and EU F-Gas Regulation implementation schedules. Bottom-up component demand modeling triangulated against top-down OEM platform thermal content estimates to anchor volume projections.
Across the projection horizon, the analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from installed base turnover rates, technology substitution curves for heat pump displacement of resistive heating, and regulatory compliance-driven system refresh cycles. Forecast inputs incorporated battery electric vehicle platform launch timelines, refrigerant phasedown enforcement schedules, and raw material price elasticity assumptions for copper and aluminum intensive heat exchanger manufacturing.
Underlying assumptions cover technology adoption curves, regulatory enforcement consistency, and base metal price stability, with deviation risk concentrated in multi-refrigerant validation burden stretching supplier testing capacity and thermal systems engineering scarcity collapsing OEM development timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Automotive Seating Systems Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Tinting Film Market