
 Automotive Oil Pressure Control Valve Market | 2026-2036
Automotive Oil Pressure Control Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Oil Pressure Control Valve Market Outlook
Tier-1 suppliers and direct OEM procurement teams are redrawing the traditional aftermarket-dominant demand pattern for automotive oil pressure control valves. Bosch leverages its integrated powertrain electronics portfolio to bundle electronic valve solutions with engine management systems. Continental sustains competitive pressure through captive manufacturing of solenoid-actuated variants across European assembly plants. Schaeffler anchors its position via specialized cam phaser integration that ties oil pressure modulation directly into valvetrain architecture.
An automotive oil pressure control valve regulates lubricant flow and pressure within internal combustion engine galleries, typically operating across pressure ranges of 2–10 bar with response times under 50 milliseconds to prevent bearing wear and optimize thermal management. Electronic control technology commands expanding share as torque-driven actuation replaces legacy hydraulic architectures in downsized turbocharged engines. Variable valve product types concentrate margin pools where precision electromagnetic coils and hardened steel valve bodies require specialized machining competencies that limit supplier entry.
NHTSA fuel economy enforcement and EPA emissions certification protocols in the United States compel OEMs to specify valves with tighter pressure tolerances and onboard diagnostic capabilities. EMA and EU Green Deal frameworks in Europe extend this trajectory through embedded CO2 tracking requirements that penetrate lubrication system design. REACH substance restrictions further constrain seal and coating material selections. Stakeholders must weigh backward integration into solenoid coil winding against semiconductor supply exposure as valve electronics deepen their share of bill-of-material costs.
Market Dynamics
Powertrain electrification is compressing the addressable base for conventional hydraulic valves while simultaneously elevating specifications for remaining internal combustion applications. This structural tension forces suppliers to defend margin pools in a shrinking volume envelope.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:OEMs specify electronically actuated valves with onboard diagnostic capabilities to meet tightening lubrication efficiency mandates in the United States.
- Cam phaser integration:Valvetrain architectures now embed oil pressure modulation directly into timing systems, creating demand for precision electromagnetic coil assemblies.
- China:Domestic passenger vehicle OEMs accelerate procurement of variable valve technology to support downsized turbocharged engine production.
Market Restraints
- Semiconductor supply exposure:Valve electronics deepen their share of bill-of-material costs, tying component availability to silicon wafer allocation cycles.
- Precision machining concentration:Hardened steel valve body production clusters in Germany and China, creating geographic supply risk.
- Powertrain electrification:Battery electric vehicle penetration eliminates lubrication system demand entirely in affected vehicle platforms.
Strategic Opportunities
- Aftermarket channel digitization:Direct-to-workshop platforms bypass traditional distributor networks for replacement valve procurement.
- EU Green Deal embedded CO2 tracking:Lubrication system design must incorporate monitoring capabilities, opening specification windows for smart valve variants.
- Hybrid powertrain architectures:Dual-mode engines require more sophisticated thermal management, expanding addressable valve content per vehicle.
Industry Challenges
- Solenoid coil winding expertise:Backward integration into electromagnetic component manufacturing demands capital and talent pools distinct from legacy machining operations.
- REACH substance compliance:Seal and coating material selections face continuous reformulation as ECHA restricts chemical classes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Oil Pressure Control Valve Market |
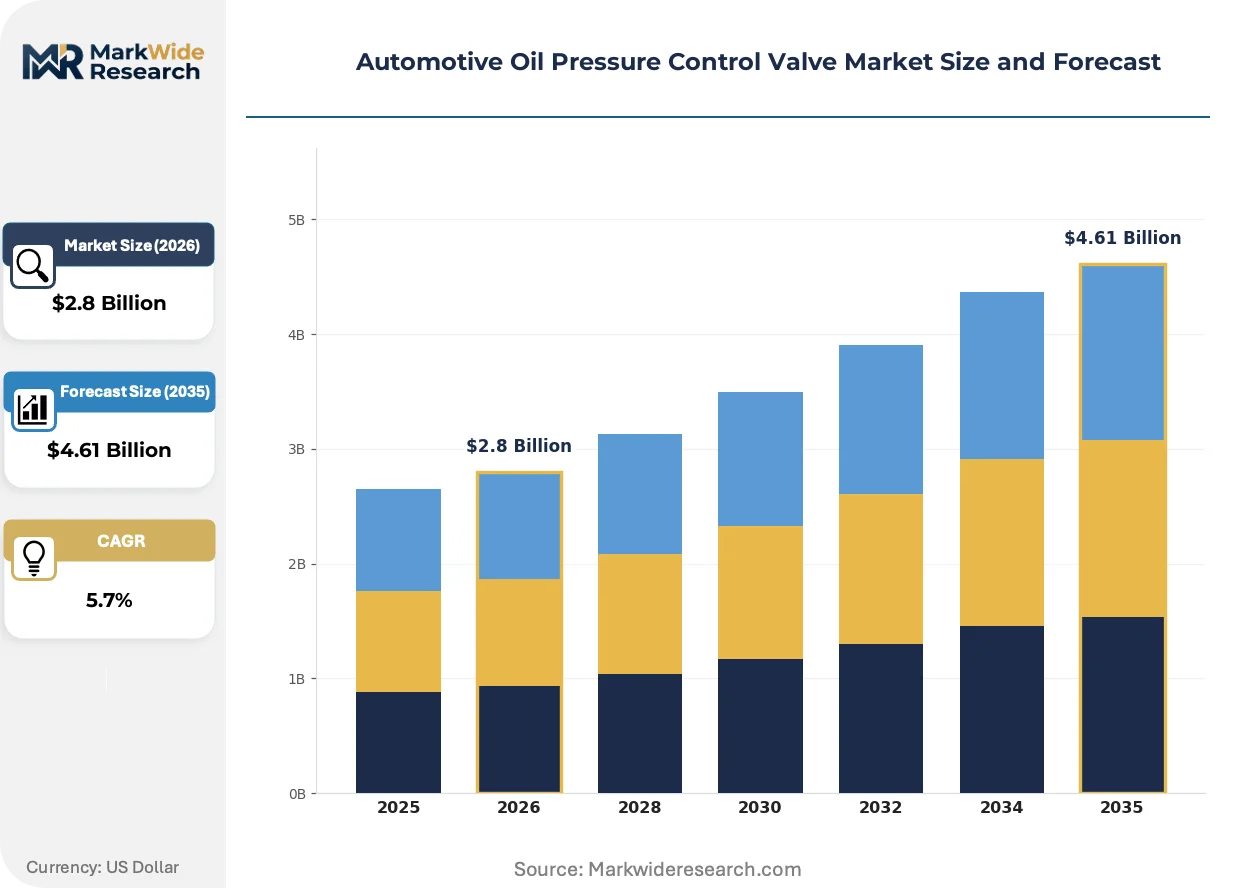
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Variable Valve, Fixed Valve, Solenoid Valve, Electronic Valve Technology: Hydraulic Control, Pneumatic Control, Electronic Control, Hybrid Control End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Motorsport |
| Companies Covered | Valeo, Schaeffler, Continental, Bosch, Denso, Aisin, Mahle, Delphi Technologies, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Oil Pressure Control Valve Market Strategic Shifts
Actuation architectures are splitting into parallel development tracks as torque-driven electronic systems diverge from legacy hydraulic designs. This technological fork creates distinct competitive arenas with incompatible capability requirements.
Electronic valve actuation is bifurcating the supplier landscape into electronics-capable integrators and pure-play mechanical specialists. Passenger vehicle OEMs in Germany and Japan now specify torque-driven response systems for downsized turbocharged engines. The technology is compressing margins for hydraulic-only suppliers while opening premium positioning for coil-and-controller bundlers.
EMA and EU Green Deal frameworks extend CO2 tracking requirements into lubrication system design across European markets. Embedded emissions monitoring now penetrates valve specification sheets as a compliance-enabling feature. Tier-1 suppliers respond by integrating pressure sensors and diagnostic firmware directly into valve housings.
Direct OEM procurement teams now bypass traditional aftermarket-dominant distribution for electronically actuated variants. Tier-1 suppliers capture volume through bundled engine management system contracts rather than discrete component sales. This pattern concentrates most visibly in North American and German assembly plant supply agreements.
Automotive Oil Pressure Control Valve Market Segmentation
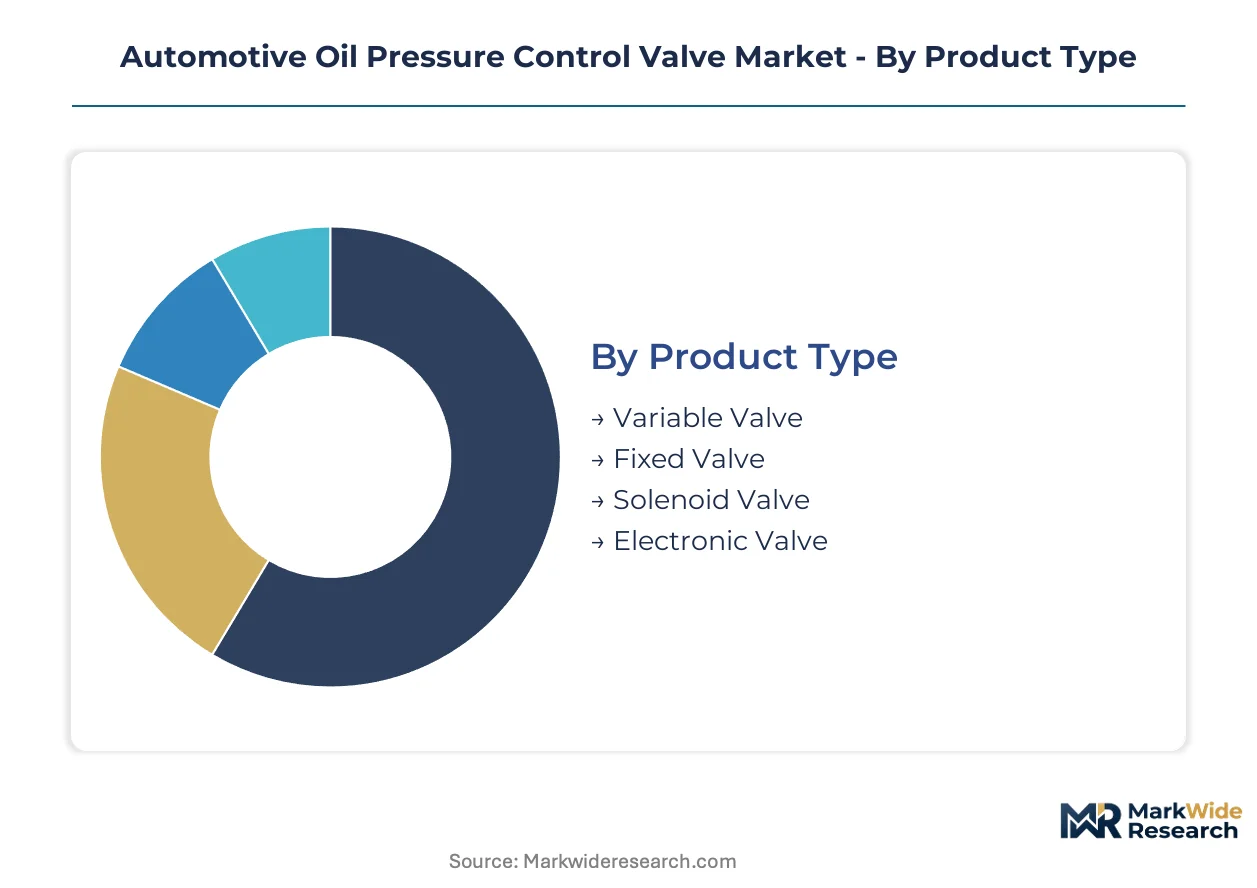
Segmentation in the automotive oil pressure control valve market reveals how powertrain electrification is fragmenting demand across incompatible technical architectures. Suppliers must now choose between defending legacy hydraulic positions or capturing premium share in electronically actuated systems.
Product Type:
Electronic and solenoid variants face the most acute substitution pressure as battery electric vehicle penetration eliminates lubrication system demand entirely in affected platforms.
- Variable Valve:Precision electromagnetic coil assemblies modulate oil pressure across multiple engine operating modes. Chinese passenger vehicle OEMs accelerate procurement of these systems to support downsized turbocharged engine production, though REACH substance restrictions constrain seal material selections.
- Electronic Valve:Torque-driven actuation with onboard diagnostic capabilities replaces legacy hydraulic architectures in downsized turbocharged engines. German and Japanese OEMs specify these systems for valvetrain integration, creating margin compression for hydraulic-only suppliers.
- Solenoid Valve:Electromagnetic coil winding expertise limits supplier entry.
- Fixed Valve:Legacy mechanical designs face volume erosion.
Variable valve anchors the volume base while electronic valve gains share at the steepest rate.
Technology:
Cost tier stratification separates premium electronic control from commoditized hydraulic alternatives.
- Electronic Control:Integrated pressure sensors and diagnostic firmware enable embedded CO2 tracking compliance under EU Green Deal frameworks. Tier-1 suppliers bundle these with engine management systems, bypassing traditional aftermarket distribution.
- Hybrid Control:Dual-mode thermal management architectures expand addressable valve content per vehicle in electrified powertrains. North American OEM procurement teams specify these for hybrid platforms requiring sophisticated lubrication modulation.
- Hydraulic Control:Legacy architectures face margin compression.
- Pneumatic Control:Niche applications in specific commercial vehicle segments.
Electronic control commands the premium tier while hybrid control expands most quickly in electrified platforms.
End User:
Customer type concentration shifts procurement leverage toward direct OEM engagement and away from aftermarket intermediaries.
- OEMs:Direct procurement teams now bypass traditional aftermarket-dominant distribution for electronically actuated variants, concentrating volume through bundled engine management system contracts rather than discrete component sales.
- Tier-1 Suppliers:Bosch, Continental, and Schaeffler capture share through integrated powertrain electronics portfolios and captive manufacturing of solenoid-actuated variants across European assembly plants.
- Aftermarket Providers:Channel digitization pressures traditional distributor networks.
- Dealerships:Workshop-level replacement demand faces platform consolidation.
OEMs anchor the volume base while Tier-1 suppliers gain share at the steepest rate.
Application:
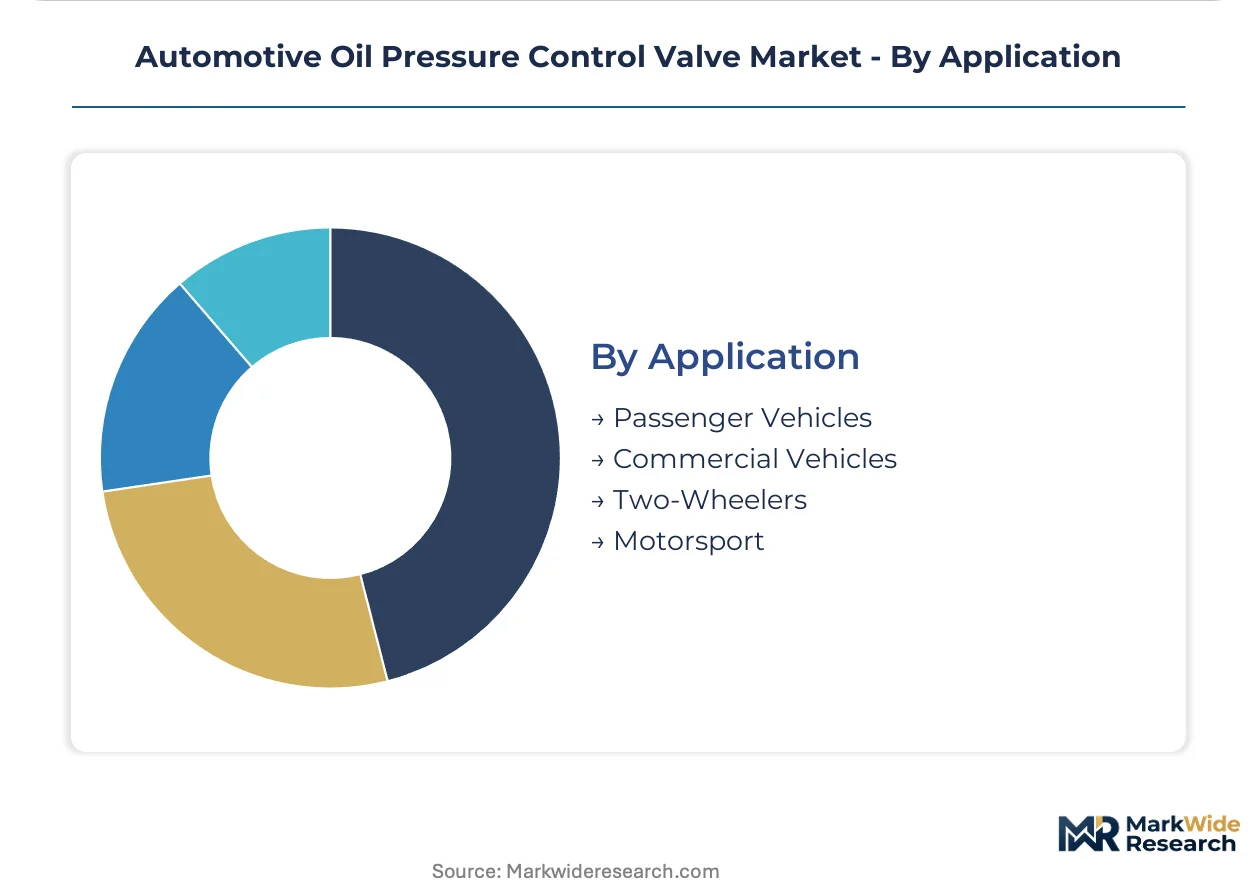
Application maturity varies sharply as passenger vehicle electrification outpaces commercial vehicle transition timelines.
- Passenger Vehicles:EPA Corporate Average Fuel Economy standards and Euro 7 emissions protocols tighten lubrication system requirements, compelling specification of valves with tighter pressure tolerances and diagnostic capabilities in the United States and European markets.
- Commercial Vehicles:Slower electrification preserves hydraulic system demand while elevating durability specifications for long-haul applications. NHTSA fuel economy enforcement extends to heavy-duty segments.
- Two-Wheelers:Cost-sensitive markets resist electronic actuation premiums.
- Motorsport:Extreme performance specifications drive precision machining demand.
Passenger vehicles anchor the volume base while commercial vehicles gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision machining exports supply valve bodies to North American and Chinese assembly plants, while Japanese electromagnetic component shipments feed European Tier-1 integration programs.
United States
EPA Corporate Average Fuel Economy standards and NHTSA fuel economy enforcement compel Detroit OEMs to specify electronically actuated valves with onboard diagnostic capabilities. The Inflation Reduction Act channels investment toward domestic powertrain component manufacturing. Michigan and Ohio machining clusters expand capacity for hardened steel valve body production serving regional assembly plants.
Germany
EMA and EU Green Deal frameworks mandate embedded CO2 tracking capabilities in lubrication systems, elevating specification requirements for precision electromagnetic coil assemblies. REACH substance restrictions continuously reformulate seal and coating material selections. Stuttgart and Munich industrial corridors anchor captive manufacturing of solenoid-actuated variants for European vehicle production.
China
Domestic passenger vehicle OEMs accelerate procurement of variable valve technology to support downsized turbocharged engine production under MIIT fuel consumption regulations. SAMR quality certification protocols tighten precision machining standards. Yangtze River Delta manufacturing bases concentrate electromagnetic coil winding capacity for regional supply integration.
Japan
METI energy efficiency directives drive specification of torque-driven response systems for hybrid powertrain architectures. JIS standards govern valve pressure tolerance and response time benchmarks. Nagoya and Osaka industrial zones maintain specialized cam phaser integration capabilities for domestic and export markets.
South Korea
MFDS automotive component certification aligns with Euro 7-equivalent emissions protocols, compelling valve diagnostic capability adoption. Government R&D programs under the Ministry of Trade, Industry and Energy support electromagnetic actuator development. Seoul Capital Area electronics clusters supply coil assemblies to domestic and international Tier-1 suppliers.
Automotive Oil Pressure Control Valve Market Competitive Environment
Player mix skews toward integrated powertrain electronics specialists with captive solenoid manufacturing capabilities. The supplier base concentrates around three strategic tiers: full-system integrators bundling valve solutions with engine management electronics, electromagnetic component specialists controlling coil winding and controller production, and precision machining houses supplying hardened steel valve bodies. Dominant competitive moves include backward integration into semiconductor-dependent controller production and geographic co-location with major OEM assembly plants.
Among European full-system integrators, Bosch, Continental, and Schaeffler represent the integrated powertrain electronics archetype, each anchoring distinct competitive positions through bundled engine management contracts and captive European manufacturing. These firms exemplify the electronics-capable tier that is displacing hydraulic-only specialists as electronic valve actuation gains specification share in downsized turbocharged engines.
| Leading Market Players |
|---|
| Valeo |
| Schaeffler |
| Continental |
| Bosch |
| Denso |
| Aisin |
| Mahle |
| Delphi Technologies |
| Eaton |
| Others |
Value Chain & Pricing Dynamics
Electromagnetic coil assemblies replacing legacy hydraulic actuators are redrawing procurement geography toward Yangtze River Delta and Stuttgart industrial corridors while compressing margins for mechanical-only suppliers. This substitution dynamic simultaneously elevates electronics-dependent pricing tiers and concentrates supply leverage with coil-winding specialists possessing captive semiconductor controller access.
Pricing Analysis
Technology-generation pricing gaps separate torque-driven electronic systems from legacy hydraulic architectures and emerging smart-valve prototypes. Three-tier pricing structure across premium electronic, standard hybrid, and economy hydraulic levels reflects certification grade differentiation under EPA and Euro 7 protocols. Cost compression in hydraulic tiers is intensifying because powertrain electrification erodes volume leverage, while OEM procurement teams show lowest price sensitivity for embedded diagnostic variants bundling with engine management systems.
Supply Chain Analysis
Inventory lead-times for precision-machined hardened steel valve bodies stretch from German and Chinese machining clusters to North American and European assembly plants. Electromagnetic coil winding draws from South Korean and Japanese electronics corridors, while semiconductor controller sourcing rests on Taiwan and USA wafer fabrication exposure. Single-source vulnerability concentrates in solenoid-grade silicon steel and rare-earth magnet feedstocks. Distribution runs through Tier-1 bundled engine management contracts rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection is compressing standalone component margins as Bosch, Continental, and Schaeffler bundle valve solutions with powertrain electronics ecosystems. Interoperability requirements with engine management firmware are raising switching costs and consolidating procurement leverage.
For Market Incumbents: Consolidate electromagnetic coil winding capabilities through backward integration into solenoid manufacturing or captive supply agreements with Yangtze River Delta specialists. Defend against margin erosion from battery electric vehicle penetration by embedding CO2 tracking firmware that locks in specification continuity under EU Green Deal frameworks. Priority lever: co-locate precision machining with OEM hybrid powertrain assembly plants in Michigan and Bavaria. For New Entrants and Emerging Players: Lead with aftermarket channel digitization targeting independent workshops bypassing traditional distributor networks for electronic valve replacement procurement. White-space concentrates in commercial vehicle long-haul applications where slower electrification preserves hydraulic system demand and elevates durability specifications. Go-to-market angle: direct-to-workshop platforms with diagnostic tool bundling for embedded sensor variants. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed precision machining houses in Germany's Baden-Württemberg region lacking electronics integration capabilities. Long-term viability hinges on 5-10 year powertrain electrification trajectory and remaining internal combustion volume envelope. Signal to watch: MIIT fuel consumption regulation tightening in China accelerating variable valve procurement beyond domestic coil-winding capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solenoid Manufacturing | Captive coil winding secures semiconductor allocation cycles against wafer fabrication bottlenecks. |
| Embedded CO2 Tracking Firmware Development | EU Green Deal compliance specification opens premium positioning for diagnostic-capable valve variants. |
| Geographic Co-location with Hybrid Assembly Plants | Michigan and Bavaria proximity reduces logistics exposure for OEM bundled contract fulfillment. |
| Aftermarket Channel Digitization Platform | Direct-to-workshop procurement bypasses distributor margin extraction in replacement valve segments. |
| REACH-Compliant Seal Material Reformulation | ECHA substance restriction anticipation prevents specification disqualification in European markets. |
Study Parameters
The analysis maps electronic valve, solenoid valve, variable valve, and fixed valve sub-sectors, each validated through Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and precision machining plant managers. Primary interview findings triangulate against vehicle production databases, IHS Markit registration data, EPA certification filings, and EMA regulatory submissions. Bottom-up unit economics and top-down market sizing converge through iterative stakeholder feedback loops.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions model product type, technology tier, end-user channel, and application class against vehicle propulsion architecture and regional production cluster variables. CAGRs derive from regression analysis of historical procurement patterns and forward-looking OEM platform roadmaps, incorporating semiconductor supply cycle assumptions and powertrain electrification scenario weighting.
Underlying assumptions cover EPA and Euro 7 regulatory enforcement continuity, semiconductor allocation normalization, and REACH substance restriction implementation timelines, with deviation risk concentrated in battery electric vehicle penetration rates and China domestic supplier substitution acceleration. Revision becomes warranted when hybrid powertrain production mix crosses inflection thresholds altering valve content per vehicle calculations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Traction Control System Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Global Automotive Intelligent Dashboard System Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Automotive Accelerator Pedal Module Market
Automotive Circuit Systems
Automotive Ethernet Switches Market
Automotive Circuit Systems
Automotive Cell Contact System Carrier Market