
 Automotive Digital Isolators Market | 2026-2036
Automotive Digital Isolators Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Digital Isolators Market Insights
The capability gap between captive fab operators and fabless designers is unwinding competitive dynamics across the supply base. Texas Instruments Incorporated leverages its vertically integrated 300mm analog fabrication to sustain cost advantages in integrated isolator production. Analog Devices Inc. anchors its position through magnetic coupling IP developed for silicon-on-insulator processes. Infineon Technologies AG competes by extending its isolation portfolio into gate-driver modules for traction inverters.
Automotive digital isolators are semiconductor devices that transfer electrical signals between isolated circuit domains using capacitive, magnetic, or optical coupling techniques, typically achieving isolation ratings of 2.5 kVrms to 5 kVrms to protect low-voltage control electronics from high-voltage power stages. These components serve the primary commercial purpose of enabling safe signal communication in electrified powertrains, battery management systems, and advanced driver-assistance platforms where ground potential differences and transient voltages threaten system integrity. Capacitive coupling dominates volume shipments for high-speed data links in infotainment and battery management applications, while magnetic coupling captures margin pools in safety-critical powertrain segments requiring reinforced isolation. Integrated isolators that combine power conversion with signal isolation are expanding fastest among tier-1 suppliers seeking to reduce bill-of-materials complexity.
FDA medical device standards, EPA emissions testing protocols for electrified vehicles, and ISO 26262 functional safety requirements collectively shape product certification pathways and design validation cycles for automotive isolator suppliers. NHTSA crashworthiness and electromagnetic compatibility mandates in the United States, alongside ECE R10 automotive EMC regulations in Europe, further constrain allowable leakage currents and transient immunity thresholds. Stakeholders must monitor how evolving battery voltage architectures above 800V and emerging wireless charging topologies redefine isolation barrier specifications before committing to long-term process technology roadmaps.
Market Dynamics
High-voltage platform architectures above 800V are forcing wholesale redesigns of isolation barrier specifications across electrified powertrains, compressing validation cycles and redrawing competitive boundaries between capacitive and magnetic coupling technologies.
Growth Catalysts
- ISO 26262 functional safety mandates:Automotive OEMs in Germany and the United States now require ASIL-D rated isolation for traction inverter control loops, expanding addressable demand for reinforced digital isolators.
- Silicon carbide power module adoption:Faster switching frequencies in traction inverters necessitate sub-10 nanosecond propagation delay isolators, pulling capacitive coupling architectures into safety-critical powertrain segments previously dominated by magnetic alternatives.
- China's EV manufacturing corridor concentration:Domestic semiconductor sourcing policies intersect with the world's largest electric vehicle production base, creating captive demand for locally qualified isolator suppliers.
Market Restraints
- 300mm analog wafer supply concentration:Captive fab operators in Japan and the United States control critical silicon-on-insulator substrate availability, constraining fabless designer expansion.
- Copper and magnetic core input volatility:Rare earth element price swings for transformer-grade ferrites compress margin pools in magnetic coupling isolator production.
- Optical isolator residual substitution:Legacy optocoupler architectures retain cost advantages in low-speed, non-safety-critical body electronics, delaying full digital isolator penetration.
Strategic Opportunities
- Wireless charging topology emergence:Ground pad-to-vehicle coil isolation requirements in China and Germany are creating new specification categories for high-frequency, high-voltage barrier devices.
- Integrated power-and-signal isolators:Tier-1 suppliers seeking bill-of-materials reduction are pulling combined DC-DC converter and data isolation modules into battery management architectures.
- India's PLI scheme for automotive electronics:Localized isolator qualification pathways for domestic EV programs offer first-mover positioning ahead of production scale-up.
Industry Challenges
- ISO 26262 tool chain certification timelines:Functional safety documentation requirements extend new product introduction cycles by 18-24 months, straining R&D resource allocation.
- Electromagnetic compatibility validation complexity:ECE R10 and NHTSA EMC mandates demand simultaneous radiated and conducted immunity testing across temperature extremes, multiplying qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Digital Isolators Market |
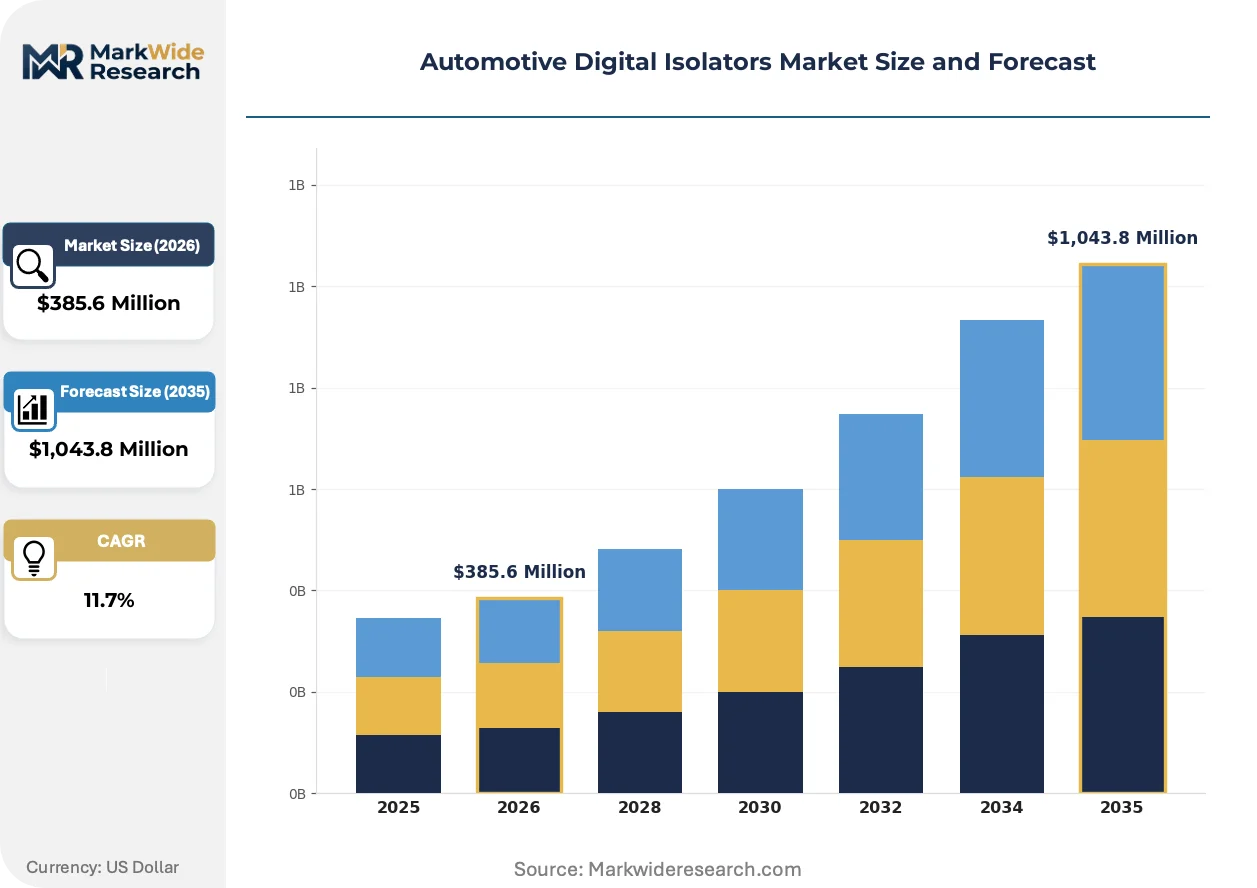
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,043.8 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed Isolators, Low-Speed Isolators, Integrated Isolators, Isolator Modules Technology: Capacitive Coupling, Magnetic Coupling, Optical Coupling, Resistive Coupling Application: Powertrain, Infotainment, Safety Systems, Body Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, System Integrators |
| Companies Covered | Texas Instruments Incorporated, Analog Devices Inc., Infineon Technologies AG, NXP Semiconductors N.V., Broadcom Inc., STMicroelectronics N.V., Skyworks Solutions Inc., ON Semiconductor, Vicor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Digital Isolators Market Trends and Innovations
Signal isolation architectures are fragmenting along voltage-tier lines, with component suppliers racing to deliver integrated solutions that collapse multiple discrete functions into single-package devices.
Capacitive coupling technology is decomposing traditional boundaries between high-speed data and power isolation domains. Battery management system designers in Tesla and BYD platforms are adopting single-chip solutions combining signal isolation with isolated power conversion. This convergence is compressing the addressable market for standalone isolator vendors while expanding margin pools for integrated solution suppliers.
REACH substance restrictions and EU Green Deal circularity mandates are forcing material transitions in encapsulant chemistries. European automotive tier-1 suppliers must now qualify halogen-free molding compounds for isolation barriers, extending validation timelines but creating specification differentiation for compliant suppliers. German OEMs are driving the fastest adoption curves for these environmentally qualified isolator variants.
Consolidated procurement frameworks are displacing fragmented supplier relationships among battery management system integrators. Tier-1 suppliers in China's EV corridor are mandating single-source qualification for isolator families across platform generations, compressing vendor lists and locking in volume commitments. This concentration is most visible in Shenzhen and Shanghai manufacturing clusters, where domestic semiconductor sourcing policies intersect with scale procurement mandates.
Automotive Digital Isolators Market Segmentation
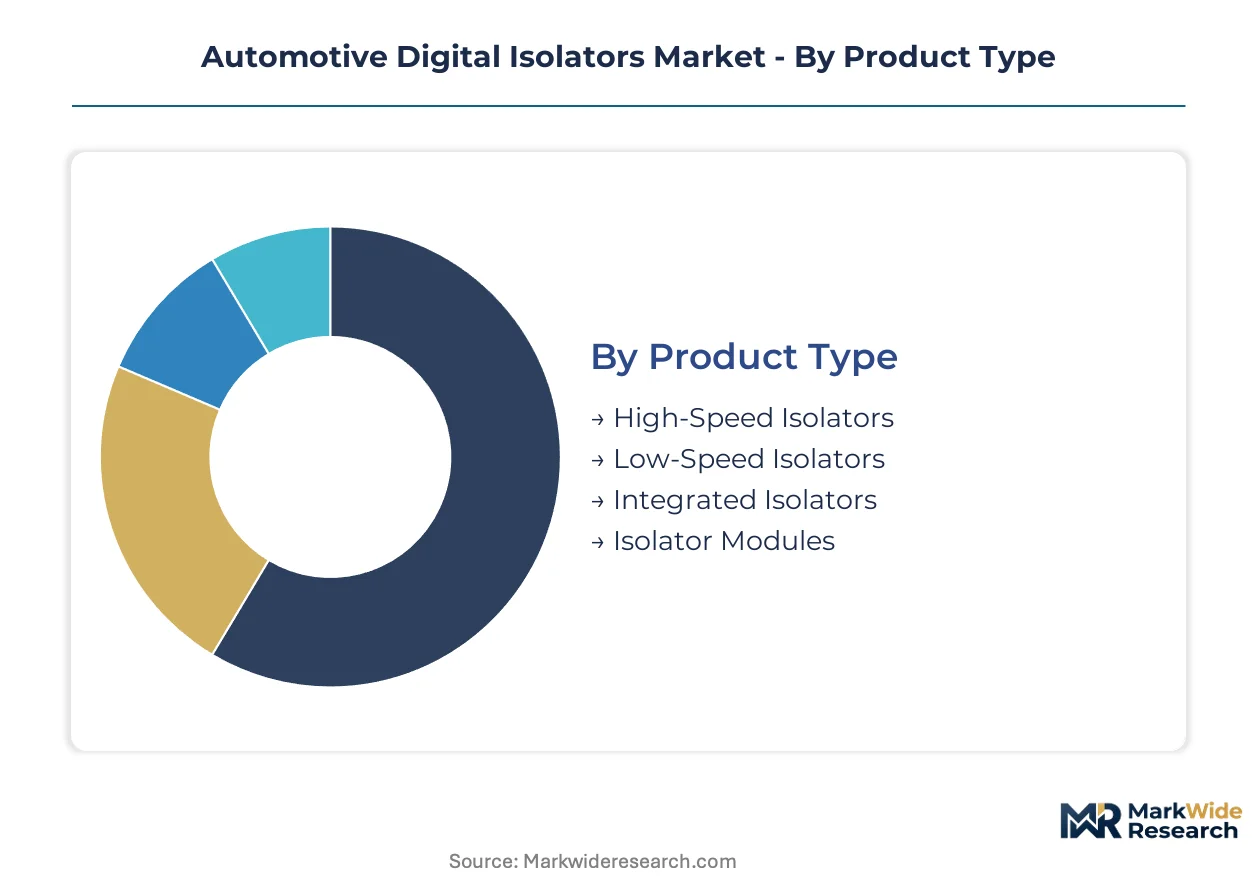
Automotive digital isolators fragment across four distinct dimensions, each reflecting divergent technical requirements and procurement economics. Product type and technology choices determine isolation ratings and propagation speeds, while application and end-user splits reveal where specification pressure concentrates most acutely.
Product Type:
Substitution pressure from integrated alternatives is compressing standalone isolator margins fastest in low-speed and module categories, forcing suppliers to defend position through combined power-and-signal architectures.
- High-Speed Isolators:These devices achieve sub-10 nanosecond propagation delays using capacitive coupling architectures optimized for silicon carbide traction inverter interfaces. Demand concentrates in Germany and United States OEM powertrain programs where ISO 26262 ASIL-D mandates require reinforced isolation for motor control feedback loops.
- Integrated Isolators:Single-package solutions combine signal isolation with isolated DC-DC power conversion, collapsing discrete component counts in battery management systems. BYD and Tesla platforms in China's EV manufacturing corridor are pulling these configurations into high-volume production, rewarding suppliers with captive fab capacity.
- Low-Speed Isolators:Legacy architectures serving body electronics and climate control interfaces face residual optocoupler competition in cost-sensitive vehicle programs.
- Isolator Modules:Multi-channel discrete packages retain footholds in aftermarket retrofit applications where qualification timelines preclude integrated alternatives.
High-speed isolators anchor the volume base while integrated isolators gain share at the steepest rate.
Technology:
Cost tier stratification separates premium magnetic coupling from commodity capacitive alternatives, with optical architectures retreating to non-automotive applications.
- Capacitive Coupling:Silicon dioxide barrier layers enable high-speed data transmission with lower dielectric losses than magnetic alternatives. Infotainment and battery management applications in Shenzhen and Shanghai manufacturing clusters favor these devices for multi-megabit per second signal integrity.
- Magnetic Coupling:Transformer-based architectures using silicon-on-insulator substrates deliver reinforced isolation ratings up to 5 kVrms for traction inverter gate drivers. German OEMs specify these devices for safety-critical powertrain segments where transient immunity requirements exceed capacitive technology limits.
- Optical Coupling:LED-photodiode architectures persist in legacy body electronics where speed requirements remain below 1 Mbps.
- Resistive Coupling:Thin-film resistor barriers serve specialized current-sensing applications in battery monitoring systems with limited isolation voltage requirements.
Capacitive coupling commands the highest shipment volumes while magnetic coupling captures the widest margin expansion.
Application:
Application concentration tracks electrification intensity, with powertrain and safety systems demanding specification upgrades that body electronics rarely require.
- Powertrain:Traction inverters, onboard chargers, and DC-DC converters require isolation barriers rated for 800V+ battery architectures with reinforced creepage distances. China's domestic EV platforms and German premium OEMs are driving qualification cycles for next-generation silicon carbide-compatible isolators.
- Safety Systems:Airbag deployment circuits and brake-by-wire controls mandate ASIL-D rated isolation with fault detection capabilities. United States NHTSA crashworthiness protocols and ECE R10 EMC regulations constrain allowable leakage currents in these signal paths.
- Infotainment:High-speed data links between head units and displays prioritize propagation delay over isolation voltage, favoring cost-optimized capacitive devices.
- Body Control:Door modules, lighting, and climate interfaces tolerate lower isolation ratings, preserving optical isolator residual presence.
Powertrain applications absorb the largest procurement volumes while safety systems impose the most stringent qualification barriers.
End User:
Procurement consolidation among tier-1 suppliers is displacing fragmented OEM direct sourcing, concentrating volume commitments with fewer qualified vendors.
- Tier-1 Suppliers:Battery management system integrators and inverter manufacturers in China's EV corridor are mandating single-source qualification across platform generations. Shenzhen and Shanghai clusters now require domestic semiconductor sourcing compliance, locking in volume commitments with locally qualified isolator vendors.
- OEMs:Vertically integrated manufacturers like Tesla and BYD maintain direct procurement relationships for strategic isolation components, bypassing tier-1 markup structures.
- Aftermarket Providers:Repair and retrofit channels serve legacy vehicle fleets with module-level replacements, prioritizing cost over performance specifications.
- System Integrators:Specialized engineering houses design custom isolation architectures for low-volume commercial and industrial vehicle conversions.
Tier-1 suppliers control the dominant procurement channel while OEM direct sourcing expands most quickly among vertically integrated EV platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing power through scale procurement mandates while German OEMs extract specification premiums for ASIL-D certified components. This asymmetry shapes how suppliers allocate fab capacity across geographies. The analysis tracks five national markets where electrification intensity and regulatory timing diverge sharply.
China
Domestic semiconductor sourcing policies and the world's largest EV production base create captive demand for locally qualified isolator vendors. MIIT's GB standards for automotive electronics mandate domestic qualification pathways for battery management components. Shenzhen and Shanghai manufacturing clusters now require single-source isolator families across platform generations, locking in volume commitments.
Germany
Premium OEM powertrain programs specify reinforced magnetic coupling isolators for 800V silicon carbide traction inverters. KBA enforcement of ECE R10 EMC regulations constrains allowable leakage currents in safety-critical signal paths. Bavaria's automotive electronics corridor anchors qualification cycles for next-generation isolation barriers.
United States
Tesla and vertically integrated EV platforms maintain direct procurement relationships for strategic isolation components. NHTSA crashworthiness protocols and FCC electromagnetic compatibility mandates multiply qualification costs for tier-1 suppliers. Michigan and Texas manufacturing clusters concentrate inverter and battery pack assembly.
Japan
Captive fab operators control critical silicon-on-insulator substrate availability for magnetic coupling architectures. METI's technology roadmaps prioritize domestic qualification of high-voltage isolation components for export markets. Kyushu and Nagoya manufacturing bases supply transformer-grade ferrites to global isolator vendors.
India
PLI scheme incentives for automotive electronics are creating localized isolator qualification pathways ahead of domestic EV production scale-up. BIS standards adoption for high-voltage automotive components accelerates supplier certification timelines. Tamil Nadu and Gujarat manufacturing corridors concentrate battery pack and power electronics assembly.
Automotive Digital Isolators Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated analog fabs competing against fabless designers reliant on SOI substrate access. The vendor base fragments across four to six dominant suppliers controlling captive wafer supply, while tier-2 specialists occupy niche frequency or voltage tiers. Two strategic archetypes predominate: integrated device manufacturers leveraging 300mm analog capacity, and fabless designers anchoring position through magnetic coupling IP. Competitive moves center on gate-driver module integration and single-source qualification mandates from tier-1 battery management integrators.
Among North American integrated device manufacturers, Texas Instruments Incorporated and Analog Devices Inc. exemplify the captive-fab archetype, with the former representing cost-optimized scale production and the latter occupying a position anchored to silicon-on-insulator process IP. Infineon Technologies AG sits within the European gate-driver integration tier, reflecting the German automotive supplier ecosystem's preference for module-level solutions.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Analog Devices Inc. |
| Infineon Technologies AG |
| NXP Semiconductors N.V. |
| Broadcom Inc. |
| STMicroelectronics N.V. |
| Skyworks Solutions Inc. |
| ON Semiconductor |
| Vicor Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between tier-1 battery management suppliers and captive fab operators lock in silicon-on-insulator substrate access while anchoring price visibility across volatile rare earth cycles. These contracts concentrate procurement leverage among vertically integrated analog manufacturers in Japan and the United States, compressing margin pools for fabless designers competing on spot-market wafer availability.
Pricing Analysis
Configured-to-order pricing for ASIL-D certified magnetic coupling isolators commands substantial premiums over standard-grade capacitive alternatives in German OEM powertrain programs. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 26262 certification grade and propagation delay specifications, with cost compression in low-speed body electronics intensifying due to residual optocoupler competition. Tier-1 suppliers in China's EV corridor exhibit highest price sensitivity, while safety system integrators in Germany tolerate premium positioning for reinforced isolation ratings.
Supply Chain Analysis
Inbound logistics costs for transformer-grade ferrites from Kyushu manufacturing bases have tightened margin structures across magnetic coupling isolator production, particularly on transpacific trade lanes constrained by container availability. Supply concentrates in Japan, the United States, and China, with critical dependencies on silicon-on-insulator wafers, rare earth ferrite cores, and halogen-free molding compounds. Single-source vulnerability in 300mm analog substrate supply poses structural risk. Distribution runs through consolidated tier-1 procurement frameworks rather than fragmented OEM direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
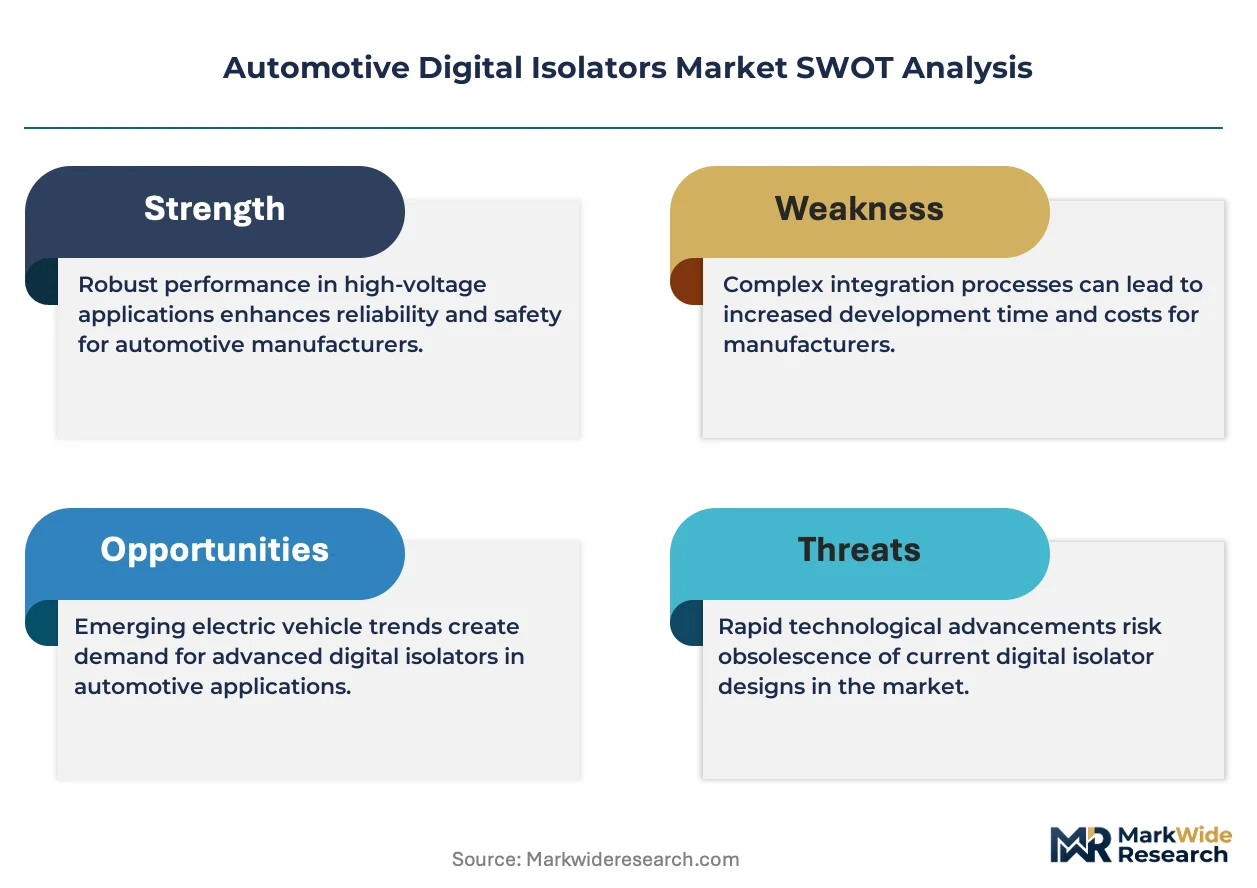
This market requires substitution defense against legacy optocoupler architectures that retain cost advantages in low-speed body electronics, delaying full digital isolator penetration and compressing addressable expansion for capacitive and magnetic alternatives.
For Market Incumbents: Shield market position by deepening captive fab capacity in 300mm analog processes and accelerating ISO 26262 tool chain certification investments to compress new product introduction cycles. Magnetic coupling IP holders must defend against silicon carbide switching frequency demands pulling capacitive architectures into safety-critical powertrain segments previously dominated by transformer-based isolation. For New Entrants and Emerging Players: Custom isolation architecture services for low-volume commercial vehicle conversions represent a service-layer gap where incumbents under-serve, enabling specialized engineering houses to capture margin pools outside tier-1 consolidated procurement frameworks. India's PLI scheme qualification pathways offer the most penetrable geography ahead of domestic EV production scale-up, with BIS standards adoption creating first-mover positioning through localized certification investment. For Investors and Strategic Acquirers: Fabless designers with magnetic coupling IP and established silicon-on-insulator process relationships represent the named acquisition target archetype, offering technology differentiation without captive fab capital intensity. Long-term viability hinges on wireless charging topology emergence and integrated power-and-signal isolator adoption curves across the analysis window. Monitor tier-1 single-source qualification mandates from Shenzhen and Shanghai manufacturing clusters as the inflection indicator for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Gate-Driver Module Integration | Infineon's traction inverter focus reflects German OEM preference for module-level isolation solutions reducing BOM complexity. |
| Silicon-on-Insulator Process Investment | Analog Devices' magnetic coupling IP anchors reinforced isolation ratings required for 800V+ battery architectures. |
| Domestic Semiconductor Sourcing Compliance | MIIT's GB standards in China lock volume commitments with locally qualified isolator vendors in Shenzhen clusters. |
| Wireless Charging Topology Development | Ground pad-to-vehicle coil isolation requirements in Germany and China create new high-frequency barrier specifications. |
| Halogen-Free Encapsulant Qualification | EU Green Deal circularity mandates force material transitions extending validation timelines for European tier-1 suppliers. |
Research Methodology
Operator-level perspectives from tier-1 battery management procurement leads, OEM platform engineers, aftermarket distributors, and semiconductor fab operations managers anchored the qualitative base for this automotive electronics analysis. Primary interview insights combined with secondary validation from SEC 10-K filings, IHS Markit vehicle production databases, MIIT GB standards documentation, and ECE R10 EMC regulatory filings. Bottom-up segment sizing and top-down market triangulation cross-checked isolator content per vehicle assumptions against regional EV production forecasts.
Sensitivity analysis tested propagation delay requirements, silicon carbide adoption curves, and rare earth price volatility as key demand and cost drivers across the projection horizon. The analytical framework modeled segmentation across product type, coupling technology, application intensity, and end-user procurement channel, with CAGRs derived from isolator content expansion in battery electric platforms and functional safety mandate penetration. Industry-specific inputs included ISO 26262 ASIL-D certification timelines and 800V+ architecture migration patterns in premium OEM programs.
Underlying assumptions cover sustained EV production scale-up, stable rare earth supply from Japanese ferrite manufacturing bases, and gradual optocoupler displacement, with deviation risk concentrated in wireless charging standardization timing and China domestic sourcing policy enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Automotive Accelerator Pedal Module Market
Automotive Circuit Systems
Automotive Steering Wheel Switch Market
Automotive Circuit Systems
Global Automotive VVT System Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Automotive Digital Instrument Cluster Market