
 Driver Drowsiness Monitoring System Market | 2026-2036
Driver Drowsiness Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Driver Drowsiness Monitoring System Market Insights
Subscription-based over-the-air software updates for drowsiness detection algorithms is decoupling hardware sales from recurring revenue streams. Continental AG leverages its integrated sensor portfolio to anchor long-term service contracts with European OEMs. Robert Bosch competes through in-house production of infrared camera modules that reduce supplier dependency. Smart Eye AB specializes in computer vision software licensing that extends across multiple Tier-1 hardware platforms.
A driver drowsiness monitoring system detects operator fatigue through real-time physiological and behavioral analysis, typically employing near-infrared cameras sampling at 60 frames per second combined with steering angle variance algorithms to trigger audible or haptic warnings before impairment-related incidents occur. Camera-based technology dominates current installations due to declining CMOS sensor costs and mature image processing pipelines, while steering monitoring retains relevance in commercial vehicle segments where retrofit compatibility matters. Fleet management applications are drawing disproportionate investment from telematics providers seeking to bundle drowsiness alerts with fuel optimization and route planning services.
The European Union's General Safety Regulation and the US NHTSA advanced driver assistance system guidelines are mandating drowsiness detection capabilities in new vehicle certifications, compelling OEMs to pre-integrate these systems rather than offer them as optional packages. Japan's METI has aligned domestic type approval standards with UN ECE R79 provisions for driver state monitoring, creating regulatory convergence across major automotive export markets. Stakeholders must evaluate whether to prioritize camera-based hardware margins or software-defined feature subscriptions as the primary value capture mechanism.
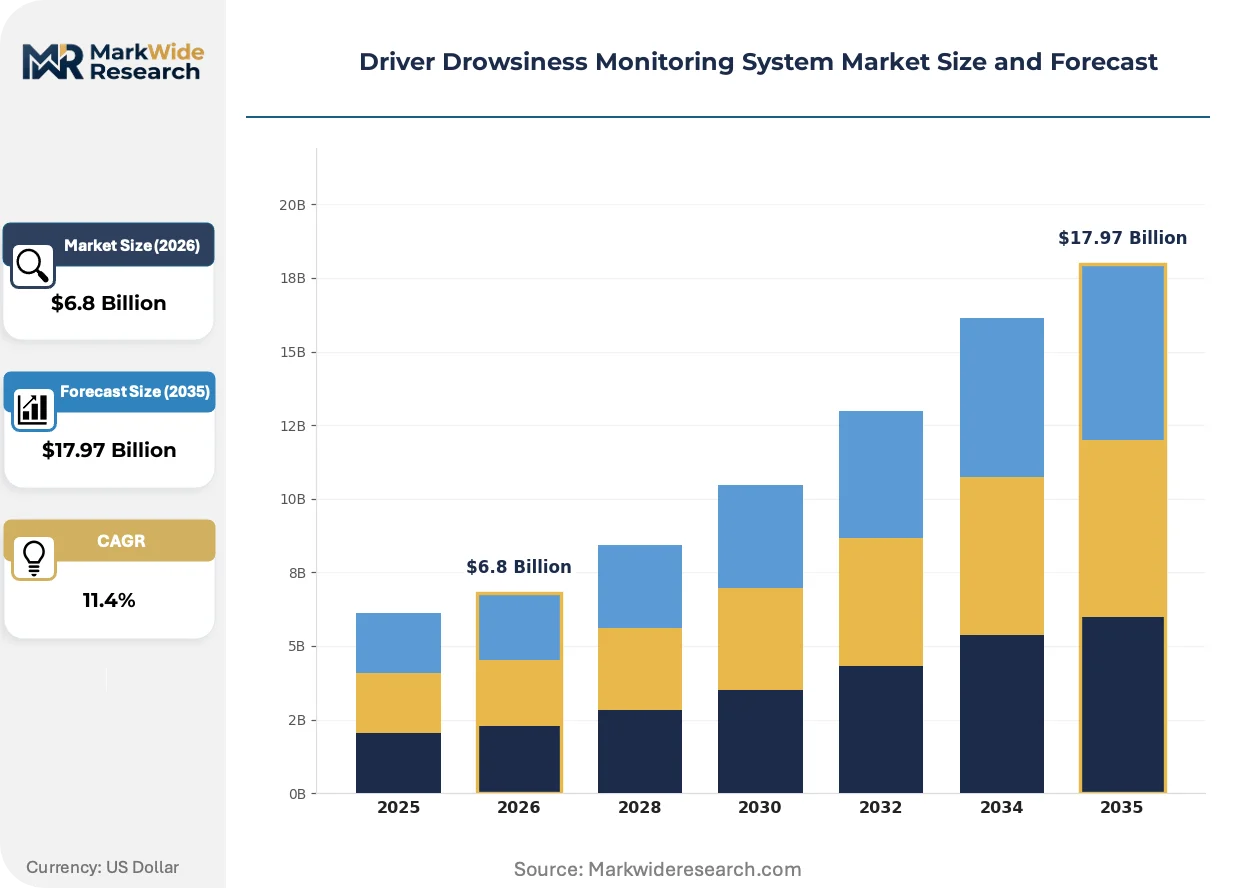
Market Dynamics
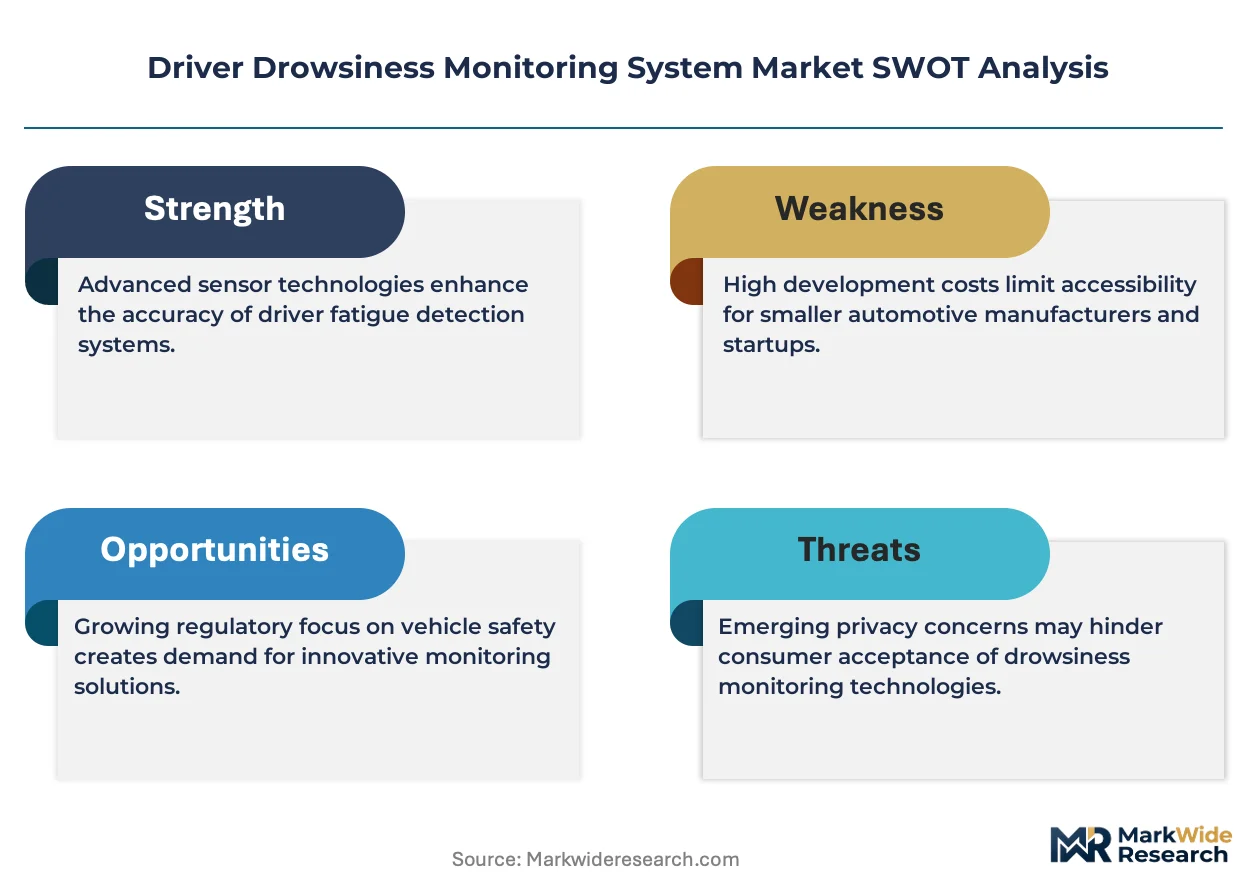
The European Union's General Safety Regulation mandates driver drowsiness detection across new vehicle categories, compelling automotive OEMs to pre-integrate camera-based monitoring systems rather than offer them as optional packages. This regulatory compression is accelerating hardware standardization while decoupling software monetization from initial equipment sales.
Growth Catalysts
- EU General Safety Regulation:Mandates drowsiness detection in new passenger cars and commercial vehicles, eliminating optional adoption pathways and guaranteeing baseline installation volumes.
- Long-haul trucking fleet operators:Demand camera-based monitoring for liability reduction and insurance premium optimization across interstate routes in the United States.
- Near-infrared CMOS sensors:Declining unit costs enable 60 frames-per-second sampling at price points viable for mass-market vehicle platforms.
Market Restraints
- Steering angle sensor dependency:Retrofit compatibility requirements in commercial vehicle segments delay full camera-based system penetration.
- Infrared camera module supply concentration:German and Japanese component suppliers control critical sensor fabrication capacity.
- Algorithm validation timelines:UN ECE R79 provisions require extensive field testing before type approval, extending product development cycles.
Strategic Opportunities
- Subscription-based over-the-air updates:Software-defined feature monetization creates recurring revenue streams independent of hardware replacement cycles.
- Telematics bundling:Fleet management providers integrate drowsiness alerts with fuel optimization and route planning services.
- Japan METI alignment with UN ECE R79:Converged type approval standards reduce regulatory fragmentation for export-oriented OEMs.
Industry Challenges
- Computer vision engineering talent scarcity:Specialized expertise in real-time physiological signal processing commands premium compensation.
- Legacy vehicle integration complexity:CAN bus architecture variations across OEM platforms require customized hardware interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driver Drowsiness Monitoring System Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Camera-Based, Steering Monitoring, Heart Rate Sensors, EEG Application: Commercial Vehicles, Passenger Cars, Fleet Management, Autonomous Driving End User: OEMs, Fleet Operators, Transportation Companies, Insurance Firms Installation Type: Integrated Systems, Retrofit Devices, OEM Installed, Aftermarket Solutions |
| Companies Covered | Robert Bosch, Continental AG, Denso Corporation, Aptiv PLC, Smart Eye AB, Seeing Machines Limited, Valeo SA, Magna International, Cipia Vision Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driver Drowsiness Monitoring System Market Trends and Innovations
Camera-based drowsiness detection is integrating with steering monitoring and vehicle dynamics sensors to create multi-modal fusion architectures. This convergence is compressing single-solution supplier margins while elevating system integrators.
Multi-sensor fusion architectures are integrating near-infrared cameras with steering angle variance algorithms and lane departure warnings into unified driver state monitoring platforms. Tier-1 suppliers in Germany and Japan are adopting these integrated stacks for premium passenger car programs. The technology is integrating discrete hardware categories into consolidated electronic control units, reducing wiring harness complexity and assembly labor content.
The EU AI Act establishes risk classification frameworks for biometric identification systems deployed in vehicles, imposing documentation and human oversight requirements on drowsiness detection algorithms. Automotive OEMs must now maintain algorithmic audit trails and performance benchmarking against standardized fatigue indicators. European type approval bodies are responding with updated testing protocols that verify detection accuracy across diverse demographic and environmental conditions.
Fleet procurement patterns are consolidating around integrated telematics platforms that bundle drowsiness monitoring with driver scorecards and predictive maintenance alerts. Commercial vehicle leasing companies in the United States are displacing standalone safety device purchases with full-stack subscription services. This shift is most visible among interstate trucking operators seeking unified data architectures for regulatory compliance and insurance documentation.
Driver Drowsiness Monitoring System Market Segmentation
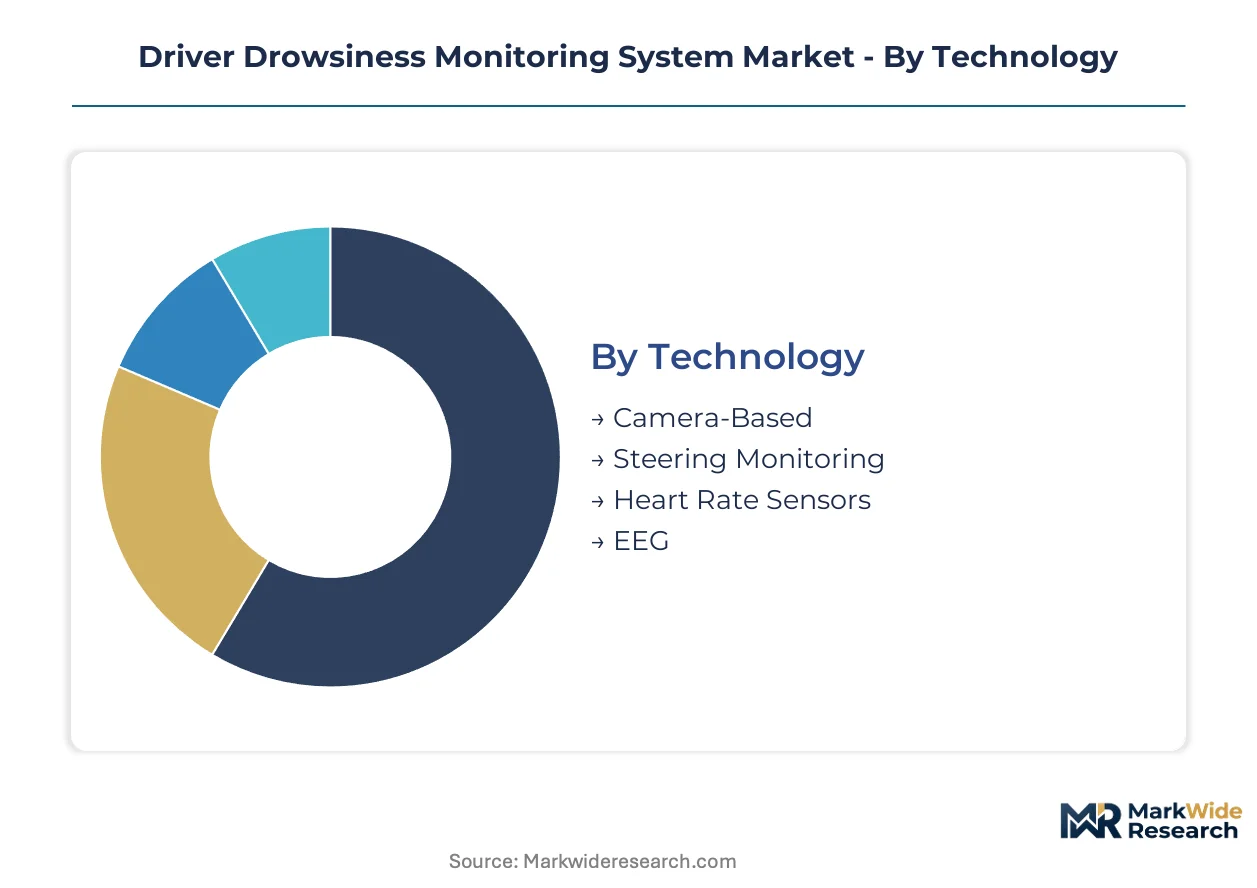
Technology differentiation in drowsiness monitoring creates distinct value capture mechanisms across hardware, software, and service layers. Each segmentation axis reveals where procurement authority concentrates and how regulatory mandates reshape competitive positioning.
Technology:
Near-infrared imaging and physiological signal processing define the core technical frontier, with sensor fusion architectures displacing single-modality solutions.
- Camera-Based:Near-infrared CMOS sensors sampling at 60 frames per second enable real-time eye tracking and head pose estimation. Demand concentrates in Germany where automotive OEMs integrate these systems into premium passenger car platforms under EU General Safety Regulation mandates.
- Steering Monitoring:Algorithms analyze steering angle variance and lane-keeping patterns to infer fatigue states without cabin-facing hardware. Commercial vehicle segments in the United States retain this technology for retrofit compatibility across legacy fleet assets.
- Heart Rate Sensors:Wearable or seat-integrated photoplethysmography provides supplementary physiological validation.
- EEG:Electroencephalography-based detection remains experimental for consumer automotive applications.
Mature deployment sits with Steering Monitoring. Newer deployment is concentrated in Camera-Based systems.
Application:
End-use contexts determine performance requirements, regulatory scrutiny intensity, and integration complexity with adjacent vehicle systems.
- Commercial Vehicles:Long-haul trucking operators deploy multi-sensor fusion to satisfy insurance documentation requirements and reduce liability exposure. Interstate routes in the United States drive disproportionate investment from telematics providers bundling drowsiness alerts with fuel optimization.
- Passenger Cars:EU General Safety Regulation mandates pre-integrated driver state monitoring in new vehicle certifications, eliminating optional adoption pathways. German and Japanese OEMs anchor hardware standardization efforts for mass-market platforms.
- Fleet Management:Unified data architectures consolidate drowsiness monitoring with driver scorecards and predictive maintenance alerts.
- Autonomous Driving:Handover readiness verification requires continuous operator state assessment during conditional automation.
Regulatory compulsion anchors volume in Passenger Cars. Fleet Management applications are climbing the fastest as procurement shifts toward subscription-based full-stack services.
End User:
Procurement authority varies sharply between vehicle manufacturers seeking design integration and operators prioritizing operational data ownership.
- OEMs:Design integration responsibility spans sensor placement, electronic control unit consolidation, and algorithm validation against UN ECE R79 provisions. European type approval bodies impose extensive field testing requirements before certification.
- Fleet Operators:Interstate trucking companies in the United States displace standalone safety device purchases with integrated telematics subscriptions that bundle drowsiness alerts with route planning.
- Transportation Companies:Commercial leasing entities seek unified regulatory compliance documentation across mixed vehicle ages.
- Insurance Firms:Usage-based underwriting models incorporate driver state data for risk segmentation and premium optimization.
System specification authority rests with OEMs. Data ownership claims are concentrating with Fleet Operators.
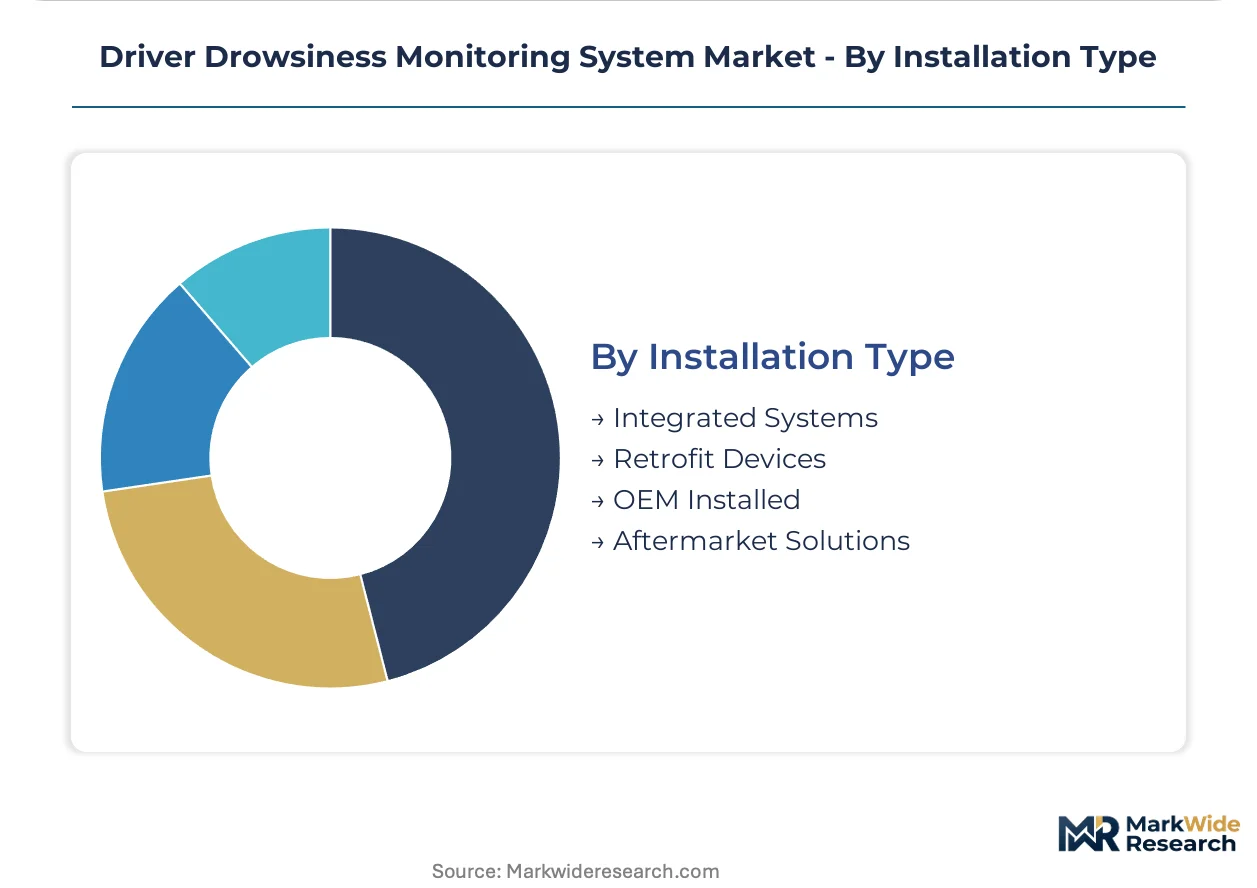
Installation Type:
Supply chain configuration separates factory-integrated electronics from aftermarket retrofit pathways with diverging margin structures.
- Integrated Systems:Consolidated electronic control units reduce wiring harness complexity and assembly labor content. Tier-1 suppliers in Germany and Japan deliver multi-sensor fusion stacks for premium passenger car programs.
- Retrofit Devices:Standalone camera or steering sensor modules serve commercial vehicle segments where legacy fleet assets outnumber new purchases. CAN bus architecture variations across OEM platforms require customized hardware interface development.
- OEM Installed:Factory-fit systems benefit from calibration precision and warranty alignment with vehicle electronics.
- Aftermarket Solutions:Independent installation channels address price-sensitive segments and regulatory compliance deadlines for existing fleet vehicles.
Margin capture favors Integrated Systems. Volume expansion is steepest in Retrofit Devices as fleet operators phase compliance across mixed-age assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates production of near-infrared camera modules and sensor fusion stacks. The United States consumes the largest volume of fleet telematics bundles with integrated drowsiness alerts.
United States
Long-haul trucking operators across interstate routes demand camera-based monitoring for liability reduction and insurance premium optimization. NHTSA advanced driver assistance system guidelines compel OEMs to pre-integrate drowsiness detection capabilities. Fleet management providers in the Midwest and Southeast bundle drowsiness alerts with fuel optimization and route planning services.
Germany
Automotive OEMs anchor hardware standardization efforts for premium passenger car platforms under EU General Safety Regulation mandates. The EU AI Act imposes documentation and human oversight requirements on biometric identification systems deployed in vehicles. Tier-1 suppliers in Stuttgart and Munich deliver multi-sensor fusion stacks that consolidate discrete hardware categories into unified electronic control units.
Japan
Domestic OEMs integrate driver state monitoring into mass-market vehicle certifications aligned with UN ECE R79 provisions. METI convergence with international type approval standards reduces regulatory fragmentation for export-oriented manufacturers. Automotive electronics clusters in Nagoya and Tokyo prefectures specialize in CMOS sensor fabrication and real-time image processing pipelines.
China
Domestic OEMs accelerate camera-based system adoption across new energy vehicle platforms to satisfy advanced driver assistance certification requirements. MIIT standards for intelligent connected vehicles mandate driver monitoring capabilities in conditional automation categories. Manufacturing concentration in the Yangtze River Delta and Pearl River Delta drives cost compression in near-infrared sensor module production.
South Korea
Hyundai Motor Group and Kia Corporation pre-integrate drowsiness detection across premium and mass-market vehicle lineups. MFDS alignment with international medical device standards influences biometric sensor validation protocols. Electronics manufacturing clusters in Gyeonggi Province supply CMOS image sensors to domestic and export automotive programs.
Driver Drowsiness Monitoring System Market Competitive Landscape
Top-tier vendors anchor integrated sensor-fusion platforms, while specialized software licensors occupy adjacent revenue streams. The vendor base stratifies across three tiers: full-stack system integrators with captive hardware production, pure-play algorithm developers licensing across multiple Tier-1 platforms, and retrofit device manufacturers serving commercial fleet segments. Strategic archetypes include sensor-fusion consolidators, computer vision specialists, and telematics bundlers. Competitive moves concentrate on algorithm validation acceleration and long-term service contract anchoring with European OEMs.
Within the integrated hardware tier, Continental AG exemplifies sensor-fusion consolidation through its multi-modal platform approach. Robert Bosch anchors German industrial positioning through in-house infrared camera module production. Smart Eye AB occupies the pure-software licensing archetype, extending computer vision algorithms across disparate Tier-1 hardware platforms without captive manufacturing.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental AG |
| Denso Corporation |
| Aptiv PLC |
| Smart Eye AB |
| Seeing Machines Limited |
| Valeo SA |
| Magna International |
| Cipia Vision Ltd. |
| Others |
Pricing and Supply Chain Analysis
EU AI Act documentation requirements for biometric identification systems gate qualified supply access and anchor premium-tier pricing for algorithm-audited platforms, while OEMs without compliance infrastructure face exclusion from EU General Safety Regulation certification pathways.
Pricing Analysis
Margin tightening in camera-based hardware reflects near-infrared CMOS sensor commoditization and Tier-1 supplier consolidation. Three-tier pricing structure across premium, standard, and economy levels separates UN ECE R79-validated fusion stacks from single-modality retrofit devices, with fleet operators showing highest price sensitivity and German automotive OEMs absorbing premium positioning for integrated electronic control units.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and Japanese automotive platforms, while aftermarket distributors serve retrofit-compatible commercial vehicle segments. Near-infrared sensor fabrication concentrates in Japan and South Korea, with algorithm development anchored in Sweden and Germany. German and Japanese component suppliers control critical CMOS capacity, creating single-source vulnerability for infrared camera modules feeding Tier-1 integration lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camera-based multi-sensor fusion is displacing legacy steering angle variance systems across new vehicle certifications, compressing standalone hardware margins while elevating software-defined service architectures.
For Market Incumbents: Deploy algorithm validation acceleration as the priority lever against computer vision engineering talent scarcity threatening development timelines. Anchor long-term service contracts with European OEMs through integrated sensor-fusion platforms that consolidate discrete hardware categories. Defensive consolidation through in-house infrared camera module production reduces supplier dependency exposure. For New Entrants and Emerging Players: Cloud-native telematics bundling offers the most penetrable entry vector for interstate trucking fleet operators seeking unified data architectures. Target commercial vehicle leasing companies displacing standalone safety device purchases with subscription-based full-stack services. White-space exists in aftermarket retrofit solutions addressing CAN bus architecture variations across legacy OEM platforms. For Investors and Strategic Acquirers: First-mover OEM adoption of over-the-air software update monetization is the leading indicator that recurring revenue models will dominate value capture. Acquisition target archetypes include pure-play computer vision developers with cross-platform licensing capabilities and telematics providers with established fleet data infrastructure. Watch for regulatory convergence signals across UN ECE R79-aligned jurisdictions as inflection triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Platform Development | Consolidates camera, steering, and vehicle dynamics data into unified electronic control units for Tier-1 supply. |
| Over-the-Air Software Monetization | Decouples drowsiness detection algorithm updates from hardware replacement cycles with European OEMs. |
| Telematics Bundling Partnership | Integrates driver alerts with fuel optimization and route planning for US interstate trucking operators. |
| EU AI Act Compliance Infrastructure | Establishes algorithmic audit trails and performance benchmarking for biometric identification systems. |
| Retrofit Device Channel Expansion | Addresses CAN bus compatibility requirements across mixed-age commercial fleet assets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, fleet telematics directors, and aftermarket distribution channel heads. Bottom-up and top-down triangulation validated against UN ECE R79 type approval databases, EU General Safety Regulation implementation timelines, and vehicle production registration data from Germany, Japan, and the United States.
Data-stream reconciliation across technology segmentation, application end-use, and installation type dimensions modeled volume and value outputs throughout the forecast period. CAGRs derived from regression analysis of historical adoption curves against regulatory mandate effective dates, with industry-specific inputs including near-infrared sensor cost trajectories and fleet telematics penetration rates.
The model holds under stable regulatory enforcement timelines; deviation in UN ECE R79 harmonization schedules or EU AI Act implementation rigor would shift baseline projections. Periodic stress-testing of base assumptions is recommended given algorithm validation timeline uncertainty and CMOS sensor supply concentration risks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Safety Restraint Systems Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Automotive Whiplash Protection Equipment Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
In-Cabin Monitoring System (ICMS) Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Highway Crash Cushion Market