
 Automotive Interface Chip Market | 2026-2036
Automotive Interface Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Interface Chip Market Insights
The EU Green Deal is broadening the addressable market for automotive interface chips by mandating stricter vehicle efficiency benchmarks and traceable supply chains across European OEM networks. NXP Semiconductors leverages its dominance in CAN and LIN protocol controllers to anchor production contracts with legacy European automakers. Infineon Technologies sustains technology leadership through silicon carbide integration with interface logic for powertrain modules. Texas Instruments competes aggressively on analog-to-digital interface density for battery management systems in electrified platforms.
An automotive interface chip is a mixed-signal semiconductor that translates, conditions, and routes data between vehicle subsystems, typically operating across voltage ranges from 1.8V to 5V with temperature tolerances exceeding 125°C to ensure reliability under hood-load conditions. Its primary purpose is to enable real-time communication between sensors, actuators, and central compute units without signal degradation. Ethernet technology is capturing the fastest expansion as ADAS and infotainment systems demand bandwidth beyond what CAN or FlexRay can deliver. ASICs command the deepest margin pools where OEMs commission custom interface logic for proprietary domain architectures. Microcontrollers remain the volume backbone in body electronics where cost sensitivity limits migration to more complex silicon.
FCC electromagnetic compatibility rules in the United States, REACH substance restrictions in Europe, and China's GB standards for automotive electronics collectively shape product qualification timelines and material selection for interface chip vendors. EMA and EPA frameworks on vehicle lifecycle emissions are pushing semiconductor makers to certify lower-power standby modes and recyclable packaging. Stakeholders must monitor how regional divergence in software-defined vehicle regulations reshapes interface standardization and procurement consolidation across OEM hierarchies.
Market Dynamics
The automotive interface chip market faces structural pressure from software-defined vehicle architectures, which collapse multiple discrete controllers into centralized compute domains and force suppliers to retool for high-bandwidth mixed-signal integration rather than discrete protocol controllers.
Growth Catalysts
- EU Green Deal vehicle efficiency mandates:The framework tightens CO2 benchmarks for passenger cars and commercial fleets, compelling OEMs to deploy smarter battery interface chips that optimize energy recovery and thermal management across electrified powertrains.
- ADAS sensor fusion bandwidth requirements:Camera, radar, and LiDAR arrays generate multi-gigabit data streams that CAN and FlexRay cannot accommodate, pulling Ethernet-based automotive interface chips into domain controller designs at accelerating rates.
- China's dual carbon policy enforcement:Provincial governments tie automotive manufacturing licenses to verified supply chain carbon intensity, creating procurement pull for interface chips with certified low-power standby modes and recyclable packaging materials.
Market Restraints
- 300mm silicon wafer supply concentration:Taiwan and South Korea foundries control advanced automotive-grade logic capacity, exposing interface chip vendors to allocation rationing during capacity crunches without geographic diversification options.
- Copper and gold bond wire cost volatility:Precious metal price swings directly compress gross margins on wire-bonded packages that remain dominant in body electronics interface chips where cost floors are rigid.
- Legacy CAN protocol entrenchment:Decades of validated vehicle network infrastructure create switching friction that slows Ethernet migration in commercial vehicle and aftermarket segments despite technical superiority.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Production-linked incentives for advanced automotive component manufacturing attract interface chip packaging and testing investments serving both domestic OEMs and export markets.
- Zonal architecture transition in premium EVs:Tesla and Lucid Motors deploy satellite compute nodes that consolidate interface functions, creating demand for multi-protocol bridge chips that unify legacy sensor buses with high-speed backbone networks.
- REACH substance restriction phase-outs:European ECHA timelines for restricted hazardous substances in electronics create replacement demand for lead-free and halogen-free interface chip packages that meet material compliance without performance trade-offs.
Industry Challenges
- ISO 26262 functional safety certification timelines:ASIL-D qualification for safety-critical interface chips in braking and steering systems requires 18-24 month validation cycles that lag vehicle platform development schedules.
- Mixed-signal design talent scarcity:Deep expertise in analog-to-digital conversion, high-speed SerDes, and automotive EMC hardening concentrates among senior engineers at a handful of IDMs and design houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Interface Chip Market |
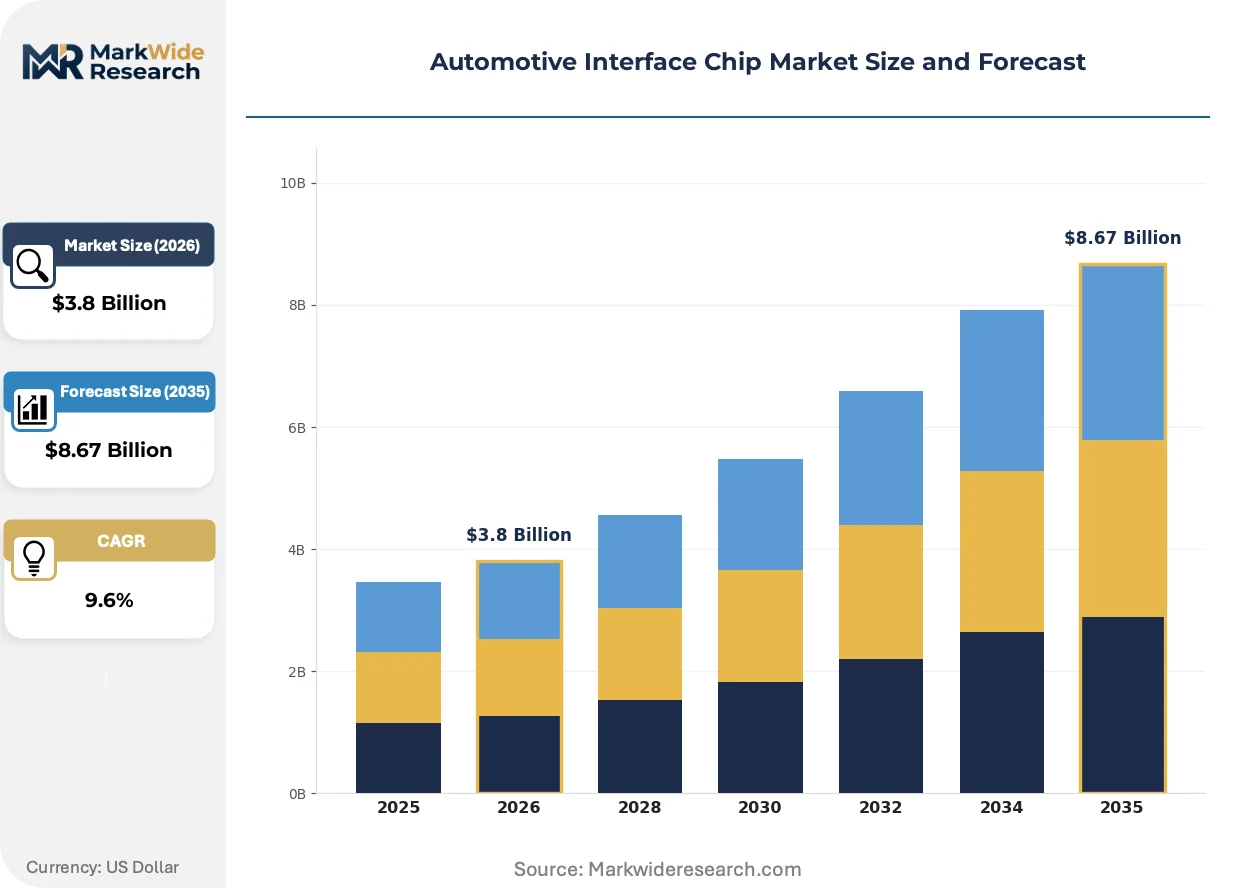
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, FPGAs, ASICs, DSPs Technology: LIN, CAN, FlexRay, Ethernet Application: Infotainment Systems, ADAS, Powertrain, Body Electronics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | NXP Semiconductors, Infineon Technologies, Texas Instruments, Renesas Electronics, STMicroelectronics, Analog Devices, Microchip Technology, Qualcomm Technologies, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Interface Chip Market Trends and Innovations
Automotive interface chip evolution centers on consolidation of disparate communication protocols into unified silicon platforms, driven by zonal E/E architectures that collapse distributed ECUs into fewer, more powerful compute nodes.
Multi-gigabit Ethernet PHY integration is unifying previously separate camera link, display port, and sensor bridge functions into single-die automotive interface chips. Tier 1 suppliers including Bosch and Continental are adopting these consolidated devices for 2026 vehicle platforms. This unification compresses bill-of-materials count and PCB footprint while simplifying software stack maintenance across domain controllers.
REACH substance restrictions from ECHA are accelerating material transitions in automotive semiconductor packaging. The regulatory pressure eliminates legacy lead-frame and mold compound formulations, forcing interface chip vendors to requalify halogen-free alternatives. European OEM procurement teams now require full material disclosure documentation before contract award, privileging suppliers with advanced environmental compliance systems.
Automotive OEMs are consolidating semiconductor procurement under direct supplier relationships rather than Tier 1 mediated sourcing. Volkswagen Group and BMW have established dedicated chip purchasing offices in Dresden and Munich that negotiate directly with NXP, Infineon, and Qualcomm for interface silicon. This disintermediation shifts pricing power toward volume buyers and compresses margin pools available to traditional module suppliers across Germany and Austria.
Automotive Interface Chip Market Segmentation
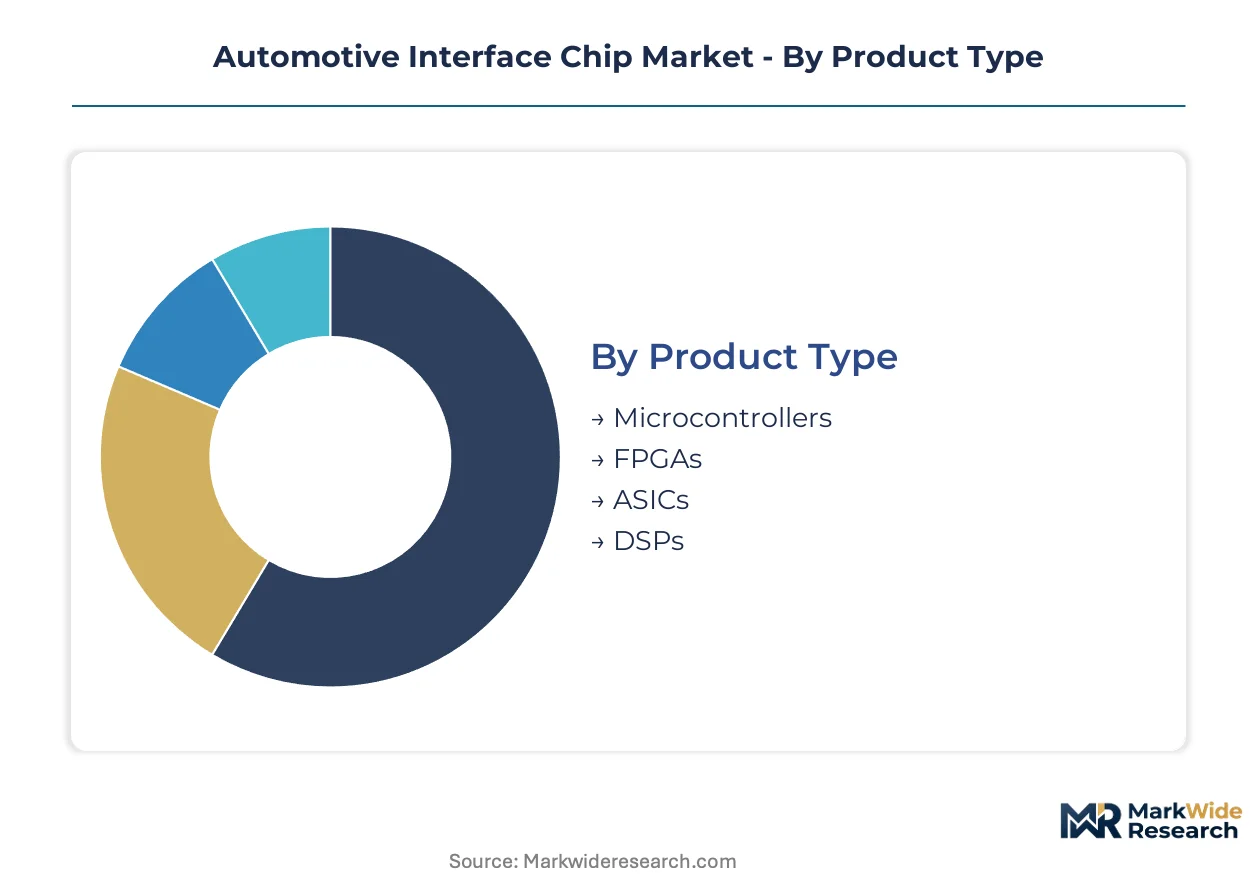
Automotive interface chip procurement decisions hinge on protocol certification requirements, thermal operating envelopes, and integration complexity across vehicle domains. Segmentation reveals how silicon architecture choices cascade into qualification timelines, margin structures, and supplier consolidation patterns.
Product Type:
ISO 26262 ASIL ratings and AEC-Q100 stress-test compliance create divergent certification burdens across product categories, with safety-critical applications demanding ASIL-D validation that extends development cycles.
- Microcontrollers:Mixed-signal ARM Cortex-based cores with integrated CAN/LIN controllers dominate body electronics and door modules where cost floors constrain silicon complexity. Demand concentrates among German OEMs localizing chip procurement for legacy vehicle platforms, constrained by rigid legacy software stacks that resist migration to more flexible architectures.
- ASICs:Custom silicon designs commissioned by OEMs for proprietary domain controllers carry the deepest margin pools but require 24-36 month design cycles with full mask-set respin risks. Tesla and Lucid Motors commission these for zonal compute nodes that consolidate sensor fusion and power distribution functions.
- FPGAs:Reconfigurable logic suits prototyping phases and low-volume premium platforms where protocol flexibility outweighs unit cost penalties.
- DSPs:Specialized digital signal processors handle audio processing and radar signal conditioning in infotainment and ADAS modules.
Leading the category by volume: Microcontrollers. Growing fastest: ASICs.
Technology:
Protocol selection determines electromagnetic compatibility testing scope, with high-speed SerDes interfaces facing FCC Part 15 and CISPR 25 radiated emissions scrutiny that low-speed buses avoid.
- Ethernet:Multi-gigabit automotive Ethernet PHYs operating at 100Mbps to 10Gbps unify camera link, display port, and backbone functions previously served by discrete chips. ADAS sensor fusion bandwidth requirements from LiDAR and camera arrays pull these into domain controller designs at accelerating rates, though EMC hardening for unshielded twisted-pair cabling extends qualification timelines.
- CAN:Controller Area Network controllers remain entrenched in powertrain and chassis modules where decades of validated network infrastructure create switching friction. Infineon and NXP sustain dominance here through silicon carbide integration that addresses EU Green Deal efficiency mandates.
- LIN:Low-cost single-wire buses serve door locks, seat controls, and lighting modules where data rates below 20kbps suffice.
- FlexRay:Deterministic time-triggered protocol clings to brake-by-wire and steering applications requiring sub-millisecond latency guarantees.
Dominant by installed base: CAN. Expanding most quickly: Ethernet.
Application:
Functional safety tiering splits the market, with braking and steering interfaces requiring ASIL-D certification while infotainment operates at ASIL-B or QM levels.
- ADAS:Sensor fusion domains demand highest bandwidth and lowest latency, integrating radar, camera, and LiDAR streams into centralized compute. China's dual carbon policy enforcement creates procurement pull for low-power standby modes in these modules.
- Powertrain:Battery management systems and motor controllers require precision analog-to-digital interfaces with 16-bit resolution and isolation ratings exceeding 2.5kV.
- Infotainment Systems:Display interfaces and audio routing prioritize bandwidth over safety certification, enabling faster product cycles.
- Body Electronics:Door modules, climate controls, and lighting represent highest unit volumes with lowest per-chip value.
Highest revenue concentration: ADAS. Steepest expansion trajectory: Powertrain electrification interfaces.
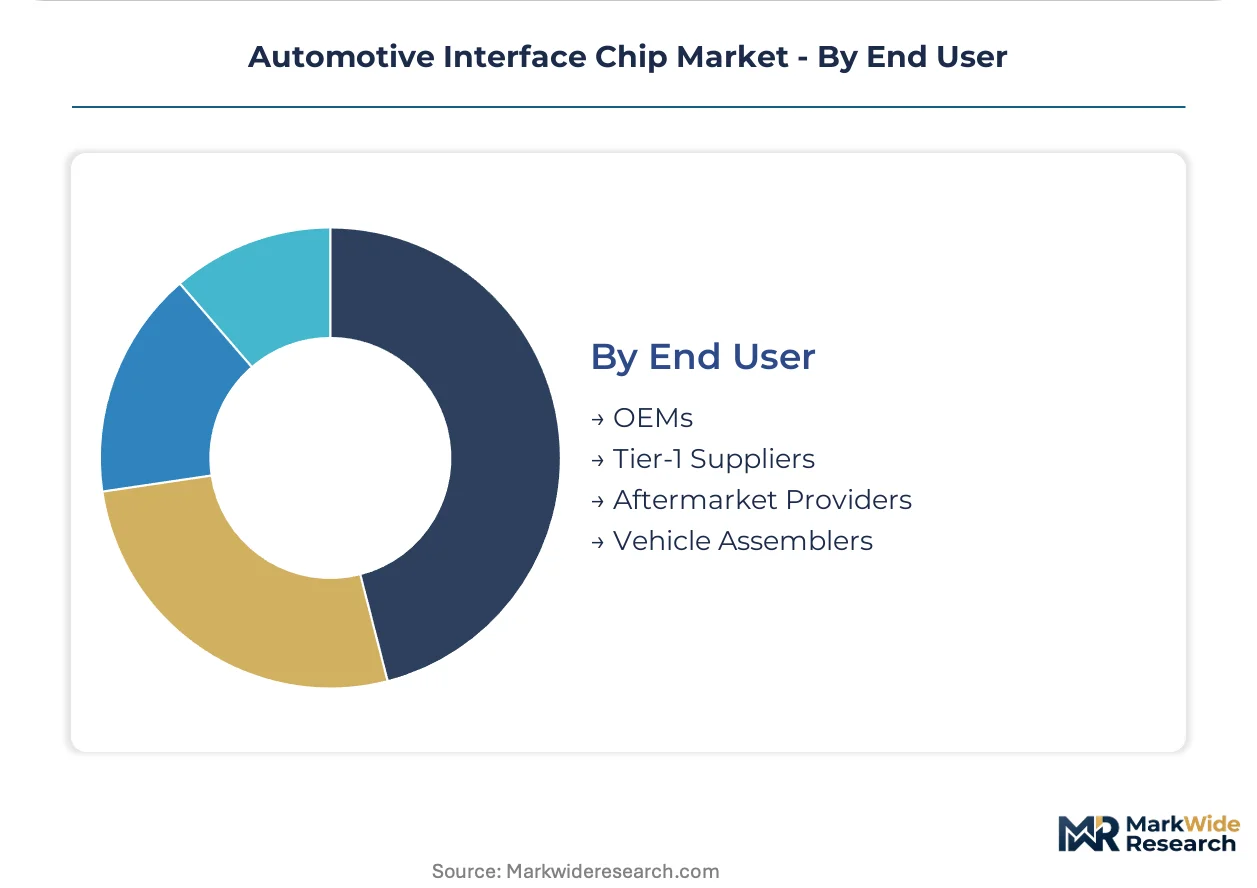
End User:
Procurement authority concentration varies sharply, with direct OEM purchasing offices displacing Tier-1 mediated sourcing for strategic silicon categories.
- OEMs:Volkswagen Group and BMW established dedicated chip purchasing offices in Dresden and Munich that negotiate directly with semiconductor vendors, compressing margin pools available to module suppliers.
- Tier-1 Suppliers:Bosch and Continental retain influence in body electronics and chassis modules where system integration expertise still carries pricing power.
- Vehicle Assemblers:Contract manufacturers serving emerging EV brands aggregate demand for standardized interface modules.
- Aftermarket Providers:Diagnostic tools and retrofit telematics drive replacement demand constrained by legacy protocol entrenchment in commercial vehicle fleets.
Capturing pricing power: OEMs. Facing margin compression: Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian foundry clusters while consumption pulls strongest from German and Chinese OEM assembly lines. Taiwan and South Korea supply advanced automotive-grade logic capacity that feeds interface chip packaging operations across multiple continents. This geographic split exposes vendors to allocation rationing during wafer capacity crunches.
United States
FCC electromagnetic compatibility rules govern automotive Ethernet PHY qualification timelines for ADAS sensor fusion modules. NHTSA safety mandates accelerate demand for ASIL-D certified interface chips in braking and steering domains. Detroit's automotive corridor anchors Tier-1 supplier engineering centers where Bosch and Continental validate next-generation domain controller silicon.
Germany
Volkswagen Group and BMW localize chip procurement through dedicated purchasing offices in Dresden and Munich. EU Green Deal vehicle efficiency mandates force semiconductor suppliers to redesign interface architectures for energy recovery optimization. Baden-Württemberg hosts Infineon production facilities integrating silicon carbide with automotive interface logic for powertrain electrification.
China
Provincial governments tie automotive manufacturing licenses to verified supply chain carbon intensity under dual carbon policy enforcement. GB standards for automotive electronics shape material selection and EMC testing scope for interface chip vendors. BYD and Tesla Shanghai drive demand for high-speed Ethernet interface chips managing battery management systems in electric vehicle platforms.
Japan
METI industrial policy supports domestic semiconductor capacity expansion for automotive mixed-signal integration. JIS standards govern reliability testing protocols for interface chips operating across extreme temperature tolerances. Nagoya's automotive manufacturing belt concentrates Toyota and Honda procurement authority for next-generation vehicle platform silicon.
South Korea
Samsung and SK Hynix foundry operations supply advanced logic capacity for automotive Ethernet PHY designs. MFDS regulatory frameworks influence material disclosure requirements for semiconductor packaging exported to European OEMs. Seoul's design houses concentrate mixed-signal expertise for high-speed SerDes interface development serving global Tier-1 suppliers.
Automotive Interface Chip Market Competitive Landscape
The competitive structure tilts toward integrated device manufacturers with captive fabrication capacity and protocol certification depth. European and American vendors anchor premium segments through ASIL-D safety certification and silicon carbide integration, while Asian suppliers capture volume through foundry scale and cost-optimized packaging. Three archetypes dominate: integrated device manufacturers with automotive-grade fabs, fabless specialists licensing SerDes IP, and diversified analog giants cross-selling power management with interface logic. Competitive moves concentrate on strategic partnerships for zonal architecture silicon and geographic expansion into India's PLI-subsidized packaging corridors.
Among European integrated device manufacturers, NXP Semiconductors and Infineon Technologies exemplify the protocol certification archetype, anchoring production contracts through decades of CAN and LIN controller validation. Texas Instruments represents the diversified analog model, competing on analog-to-digital interface density for battery management systems without captive automotive-grade fab capacity. These three occupy positions across distinct margin pools: NXP and Infineon in safety-critical powertrain and chassis modules, Texas Instruments in cost-sensitive body electronics where analog integration drives bill-of-materials compression.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Infineon Technologies |
| Texas Instruments |
| Renesas Electronics |
| STMicroelectronics |
| Analog Devices |
| Microchip Technology |
| Qualcomm Technologies |
| Broadcom |
| Others |
Pricing and Supply Chain Analysis
Mixed-signal design talent concentration in South Korean design houses and German engineering centers widens pricing-tier spreads, as labor-cost differentials between captive IDM fabrication and fabless outsourcing cascade into three-tier pricing structure across premium, standard, and economy levels for automotive interface silicon.
Pricing Analysis
Margin tightening in economy-tier body electronics traces to rigid cost floors on wire-bonded packages using copper and gold bond wires. Pricing stratifies across premium, standard, and economy tiers based on ASIL-D certification grade and volume scale. Cost-down pressure on standard-tier Ethernet PHYs accelerates because OEMs consolidate procurement through direct purchasing offices. Tier-1 suppliers show highest price sensitivity, while OEMs with captive design teams exhibit least.
Supply Chain Analysis
India's PLI scheme for automotive electronics is reshaping sourcing patterns for packaging and testing operations. Taiwan and South Korea supply advanced automotive-grade logic capacity. Raw material dependencies include 300mm silicon wafers, copper bond wire, and halogen-free mold compounds. Single-source vulnerability concentrates in Taiwan foundry capacity. Distribution runs through direct OEM purchasing offices and Tier-1 module suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive interface chip market sits in a protocol-transition phase, with multi-gigabit automotive Ethernet PHYs displacing decades of entrenched CAN and FlexRay infrastructure across next-generation vehicle platforms.
For Market Incumbents: Deepen silicon carbide integration with interface logic to defend powertrain module positions against fabless competitors. Expand captive automotive-grade fab capacity in Dresden and Munich to offset Taiwan foundry allocation risks. Prioritize ASIL-D certification investment for braking and steering domains where switching costs protect margin pools. For New Entrants and Emerging Players: Multi-protocol bridge chips for zonal architectures offer a technology-first wedge into premium EV platforms from Tesla and Lucid Motors. Target India's PLI-subsidized packaging corridors for cost-optimized body electronics entry. Pursue direct OEM purchasing relationships in Germany to bypass Tier-1 margin compression. For Investors and Strategic Acquirers: The window for entry favors fabless SerDes IP specialists with automotive EMC hardening expertise. Long-term viability hinges on consolidation into platforms serving software-defined vehicle architectures. Watch for inflection when zonal architecture adoption crosses critical mass among European premium OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Integration | Infineon anchors powertrain contracts through SiC-interface logic combination addressing EU Green Deal mandates. |
| Multi-Protocol Bridge Development | Unified CAN-LIN-Ethernet chips capture zonal architecture demand from Tesla and Lucid Motors satellite nodes. |
| Direct OEM Procurement Expansion | Volkswagen Group and BMW purchasing offices in Dresden disintermediate Tier-1 suppliers, compressing margin pools. |
| India PLI Packaging Investment | Production-linked incentives attract testing and packaging operations serving domestic OEMs and export markets. |
| REACH-Compliant Material Transition | ECHA substance restrictions force lead-free and halogen-free package requalification, privileging advanced compliance systems. |
Research Methodology
Document review covered SEC 10-K filings, EU regulatory submissions, and automotive production databases, complemented by interviews with Tier 1 supplier procurement officers, OEM platform engineers, semiconductor design house technical leads, and aftermarket distributors. Secondary validation drew from customs trade data, AEC-Q100 stress-test documentation, and vehicle registration records. Bottom-up and top-down triangulation cross-checked unit volume assumptions against value aggregation.
Segment-level outputs across the analysis window reflect modeled interactions between propulsion architecture, vehicle class, content per vehicle, and regional production cluster. CAGRs derived from regression analysis of historical penetration rates and OEM platform rollout schedules. Industry-specific inputs included ADAS sensor fusion bandwidth requirements and EU Green Deal implementation timelines.
Several conditions sit outside the modeled scope, including unannounced OEM platform cancellations, foundry capacity allocation disruptions, and divergent national implementations of software-defined vehicle regulations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Ethernet Switches Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Global Automotive Intelligent Dashboard System Market
Automotive Circuit Systems
Automotive Oil Pressure Control Valve Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Automotive Body Control Module Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Automotive Cell Contact System Carrier Market
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Automotive Launch Control System Market