
 Global Automotive Composite Liftgate Market | 2026-2036
Global Automotive Composite Liftgate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Composite Liftgate Market Intelligence
The gap between thermoplastic and thermoset processing for large exterior body panels is narrowing as automakers pursue cycle-time reductions and surface-quality parity with steel. Magna International leverages its vertical manufacturing footprint to control resin-to-assembly cost structures across North American and European plants. Plastic Omnium Group anchors its position through proprietary compression-molding lines purpose-built for Class-A composite surfaces. Brose Fahrzeugteile competes on integrated mechatronic liftgate systems that combine composite shells with power-actuation hardware.
An automotive composite liftgate is a tailgate assembly fabricated from fiber-reinforced polymer matrices—typically glass or carbon fiber embedded in epoxy, polypropylene, or polyurethane resins—engineered to achieve stiffness-to-weight ratios superior to stamped aluminum or steel while supporting integration of spoilers, cameras, and lighting modules. Glass Fiber Reinforced Polymer dominates current volume owing to cost scalability, though Carbon Fiber Reinforced Polymer captures the margin pool in luxury and performance vehicle architectures where gram-level mass reduction commands premium pricing. Electric Vehicles represent the fastest-expanding vehicle application segment as range optimization drives OEMs to shed every feasible kilogram from body-in-white and closure assemblies.
The EPA tailpipe-emission standards and Corporate Average Fuel Economy framework in the United States, alongside the EU Green Deal and REACH chemical restrictions in Europe, compel OEMs to adopt lighter closure systems that contribute to fleet-wide efficiency targets. China's MIIT new-energy vehicle mandates and GB standards for lightweight structural components further reinforce composite penetration in domestic EV platforms. Stakeholders must monitor how evolving recyclability requirements under ECHA and emerging carbon-border adjustments reshape material selection and supplier qualification timelines.
Market Dynamics
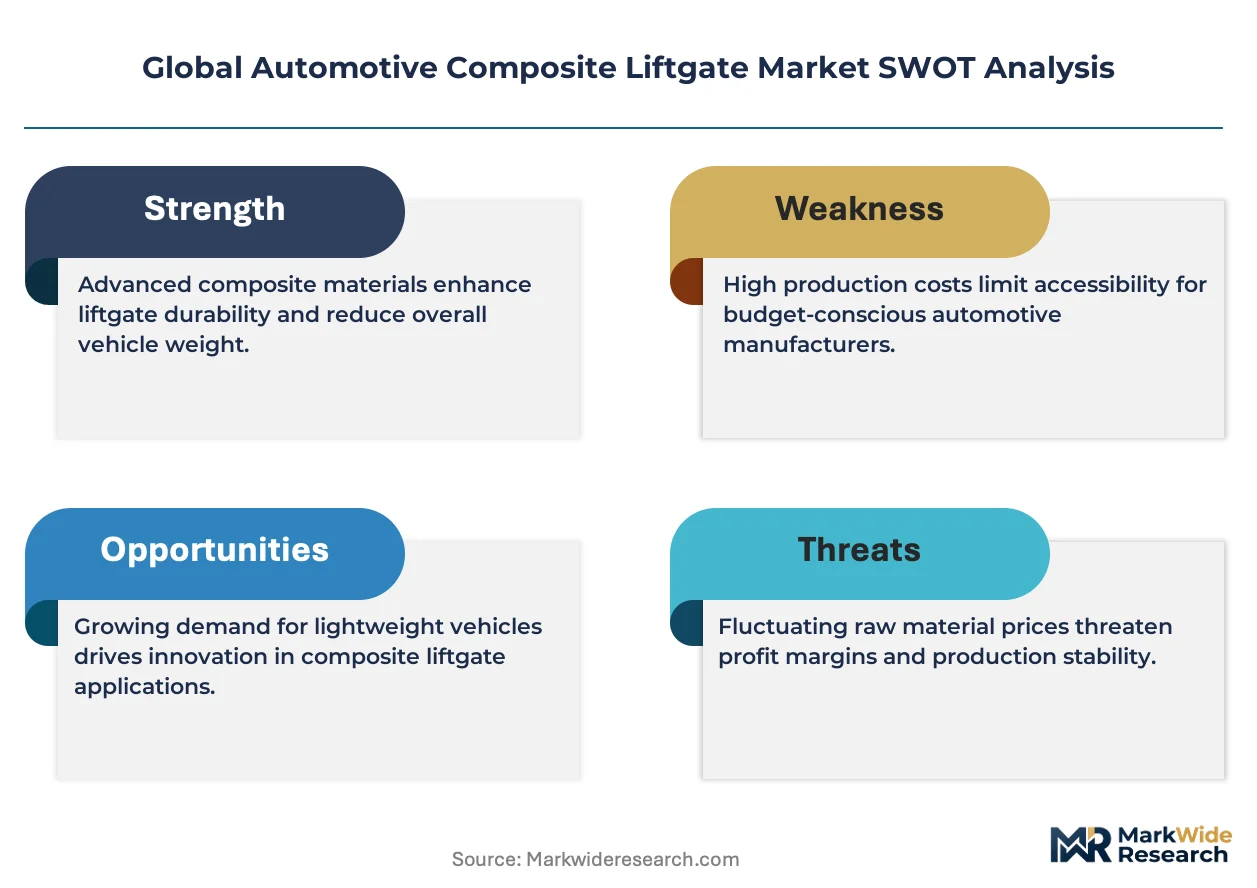
Electric vehicle OEMs are systematically stripping mass from closure assemblies to recover range lost to battery weight, creating structural pull for composite liftgate architectures that stamped metal cannot satisfy.
Growth Catalysts
- EPA CAFE standards:US fleet efficiency mandates compel OEMs to adopt lightweight closures that improve corporate average fuel economy ratings without compromising structural integrity.
- Carbon fiber process innovation:Automated fiber placement and out-of-autoclave curing are compressing CFRP cycle times toward thermoplastic parity, opening mid-volume EV platforms.
- Germany:Premium SUV assembly concentration in Stuttgart and Munich clusters sustains demand for Class-A surface composite liftgates with integrated spoiler and camera modules.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations and energy costs in European polymer production create margin compression for thermoset-dependent suppliers.
- Tooling capex concentration:Compression-molding dies for Class-A surfaces require 12-18 month lead times and single-source dependence on specialized German and Japanese toolmakers.
- Steel recycling infrastructure:Established end-of-life metal recovery systems enjoy 95%+ collection rates versus nascent thermoplastic and thermoset composite recycling pathways.
Strategic Opportunities
- India:Domestic EV production incentives under the PLI scheme and absence of legacy metal-stamping infrastructure create greenfield composite adoption potential.
- Multi-material bonding:Hybrid liftgate designs combining glass fiber skins with aluminum reinforcement beams address stiffness requirements while enabling localized repair.
- Direct-to-OEM digital channels:Configurator platforms allowing real-time specification of surface finish, spoiler integration, and lighting modules bypass traditional tiered supply negotiations.
Industry Challenges
- Surface quality certification:Achieving OEM Class-A paint adhesion and thermal expansion matching requires 18-24 month qualification cycles with no guarantee of platform award.
- Cross-functional engineering talent:Composite material science expertise must integrate with mechatronic hardware engineering for power-actuated liftgate systems, creating hybrid skill scarcity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Composite Liftgate Market |
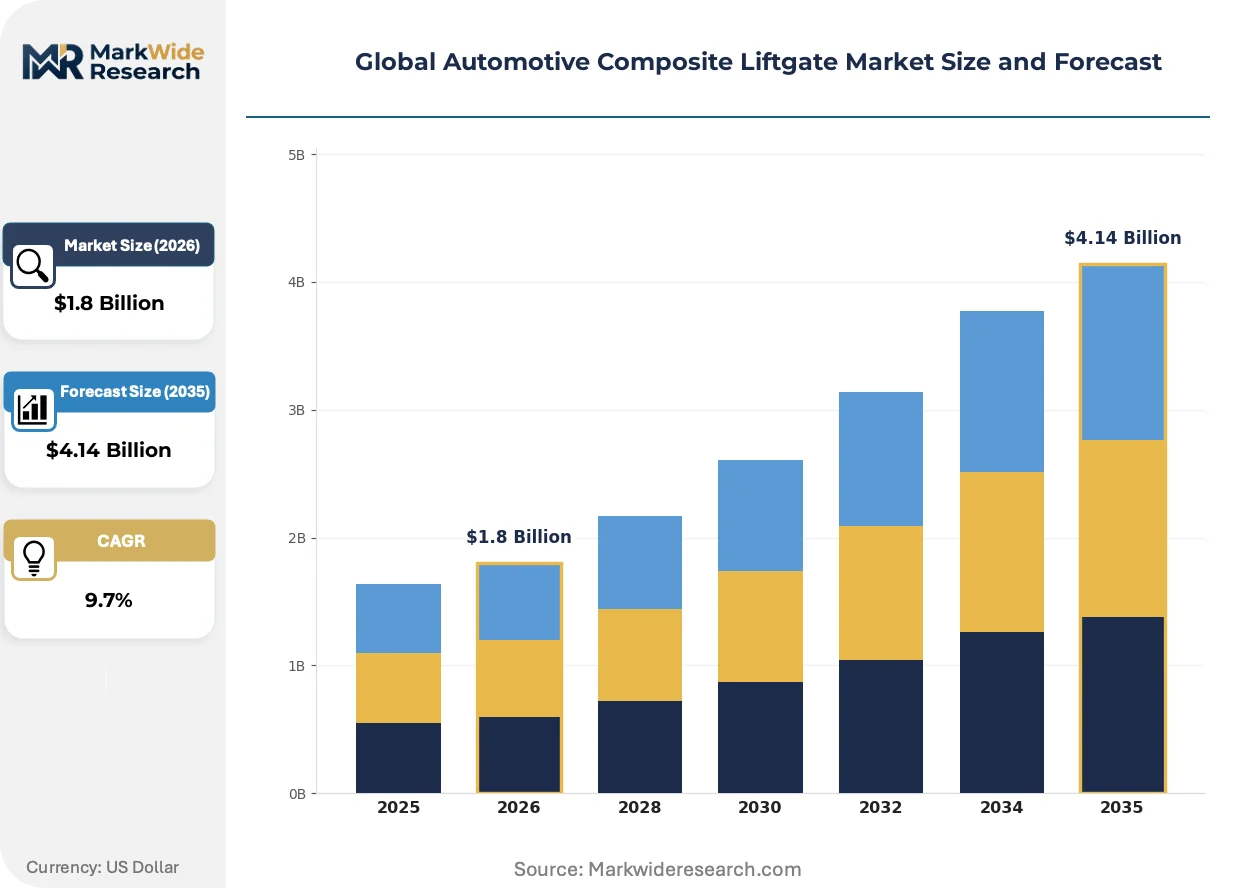
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass Fiber Reinforced Polymer, Carbon Fiber Reinforced Polymer, Aramid Fiber Composite, Natural Fiber Composite, Basalt Fiber Composite Vehicle Application: Passenger Cars, Light Commercial Vehicles, SUVs, Crossovers, Electric Vehicles Manufacturing Technique: Compression Molding, Resin Transfer Molding, Hand Lay-Up, Pultrusion, Vacuum Infusion End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Magna International, Plastic Omnium Group, Brose Fahrzeugteile, Huf Group, Trinseo, Faurecia, IDI Composites International, Auto Body Parts, Stellantis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Composite Liftgate Market Strategic Shifts & Innovations
Digital twin workflows and predictive surface modeling are compressing development cycles for complex curvature composite panels while regulatory pressure on embodied carbon intensifies material scrutiny.
Simulation-driven preforming is virtualizing the traditional tool-and-die development cycle for composite liftgate shells. Tier-1 suppliers deploy finite element draping models to predict fiber wrinkling before physical prototype commitment. BMW and Mercedes-Benz EV platforms now mandate virtual validation gates that eliminate 40% of historical iteration loops, collapsing time-to-production for new closure architectures.
REACH chemical restrictions and ECHA substance-of-very-high-concern listings are forcing systematic substitution of legacy epoxy hardeners and solvent-based surface primers. Formulators accelerate bio-based polyurethane and thermoplastic polyolefin alternatives that maintain Class-A paintability. European OEMs impose full material disclosure requirements extending through tier-3 resin suppliers, reshaping qualification documentation burdens.
Consolidated procurement of complete liftgate modules—composite shell, actuation hardware, wiring harness, and sensor integration—is displacing discrete component sourcing. Volkswagen Group and Hyundai-Kia now issue single-source contracts for functional assemblies rather than material-only supply agreements. Tier-1 suppliers with captive mechatronic capabilities capture margin expansion in Germany and South Korea where integrated system validation is prioritized.
Global Automotive Composite Liftgate Market Segmentation
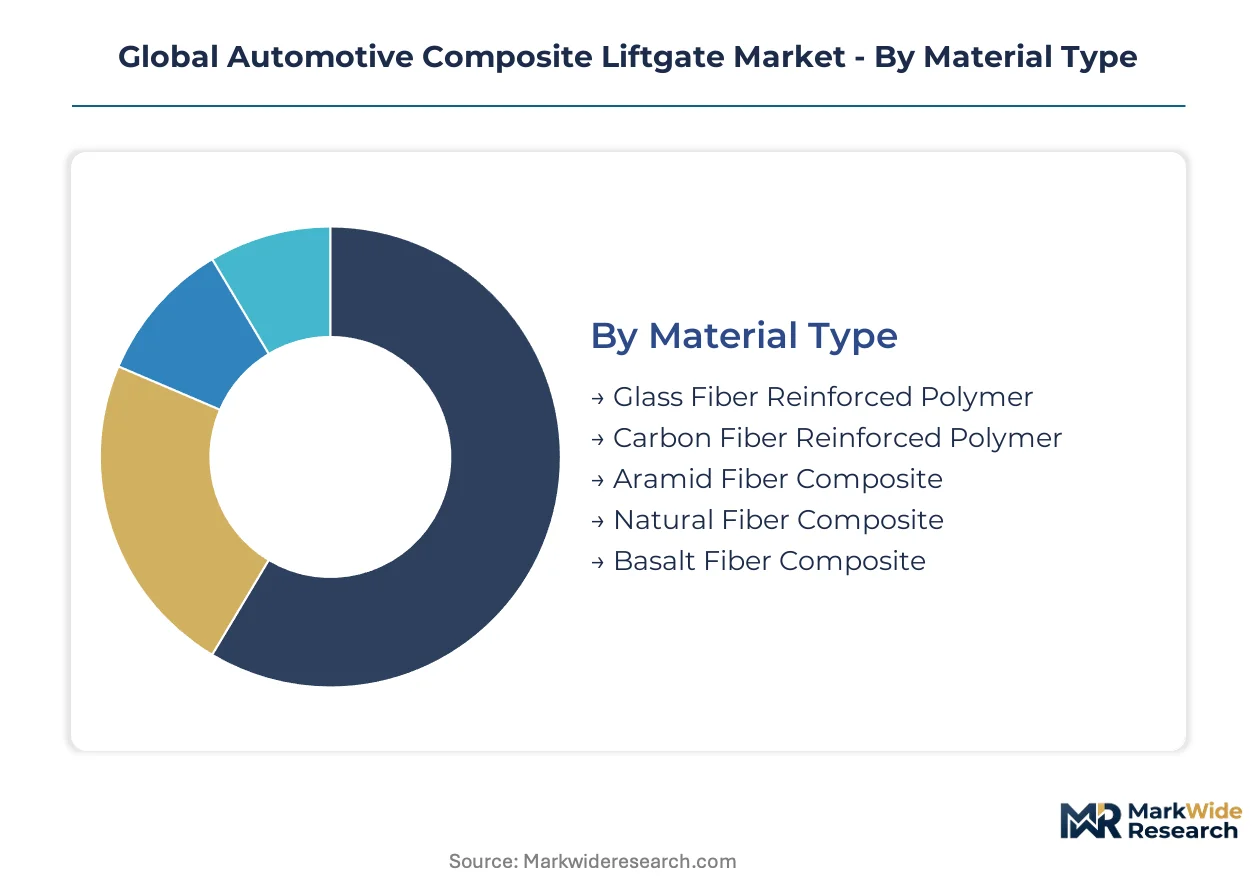
Composite liftgate procurement patterns diverge sharply across material grades and vehicle architectures, with OEMs calibrating fiber selection against cycle-time constraints and surface-quality requirements. Manufacturing technique choice determines supplier qualification timelines and capital intensity, creating distinct competitive moats within each segment cluster.
Material Type:
Cost tier stratification separates mass-market adoptable substrates from performance-grade alternatives commanding premium positioning.
- Glass Fiber Reinforced Polymer:Glass fiber embedded in polypropylene or polyurethane matrices delivers stiffness-to-weight ratios sufficient for mid-volume SUV and crossover platforms. Demand concentrates in Germany and China where premium SUV assembly lines prioritize cost-scalable lightweighting over gram-level optimization.
- Carbon Fiber Reinforced Polymer:Aerospace-derived carbon fiber architectures achieve superior specific strength for luxury EV platforms where range recovery justifies material cost premiums. Stuttgart and Munich OEM clusters sustain procurement volumes for Class-A surface CFRP liftgates with integrated spoiler modules.
- Aramid Fiber Composite:Kevlar-based reinforcement targets impact-critical zones in high-performance vehicle architectures.
- Natural Fiber Composite:Flax and hemp fiber matrices address emerging ECHA recyclability mandates in European EV platforms.
- Basalt Fiber Composite:Volcanic rock-derived fibers occupy a cost-performance midpoint between glass and carbon grades.
Glass Fiber Reinforced Polymer holds installed capacity. Carbon Fiber Reinforced Polymer is rotating up the share rankings.
Vehicle Application:
Application scope tracks platform electrification intensity and closure assembly complexity.
- Electric Vehicles:Battery mass penalties compel systematic closure lightweighting across BEV and PHEV architectures. MIIT compliance mandates in China and EPA CAFE standards in the United States reinforce composite penetration in domestic EV platforms.
- SUVs:Large aperture dimensions and spoiler integration requirements favor composite solutions over stamped metal in premium segments. German OEMs in Stuttgart and Munich clusters specify Class-A composite liftgates with camera and lighting module integration.
- Passenger Cars:Sedan and hatchback platforms balance cost discipline with moderate lightweighting targets.
- Crossovers:Blended car-SUV architectures drive intermediate composite adoption rates.
- Light Commercial Vehicles:Fleet operators prioritize durability and repairability over mass reduction in cargo van applications.
Electric Vehicles command the steepest expansion trajectory. SUVs maintain volume leadership across the analysis window.
Manufacturing Technique:
Process maturity determines cycle-time parity with metal stamping and surface finish qualification feasibility.
- Compression Molding:Heated matched-die forming of thermoplastic prepregs achieves sub-90-second cycle times approaching steel stamping economics. Plastic Omnium Group and Magna International deploy purpose-built compression lines across North American and European plants for Class-A surface production.
- Resin Transfer Molding:Closed-mold infusion of thermoset resins delivers superior fiber volume fractions for structural load-bearing applications. BMW and Mercedes-Benz EV platforms mandate RTM validation gates that compress development cycles through digital twin workflows.
- Vacuum Infusion:Low-pressure resin distribution suits prototype and low-volume production environments.
- Hand Lay-Up:Manual fiber placement persists in aftermarket repair and custom vehicle applications.
- Pultrusion:Continuous profile extrusion targets linear reinforcement beam integration rather than full shell fabrication.
Compression Molding anchors high-volume supply. Resin Transfer Molding is gaining share fastest in premium EV platforms.
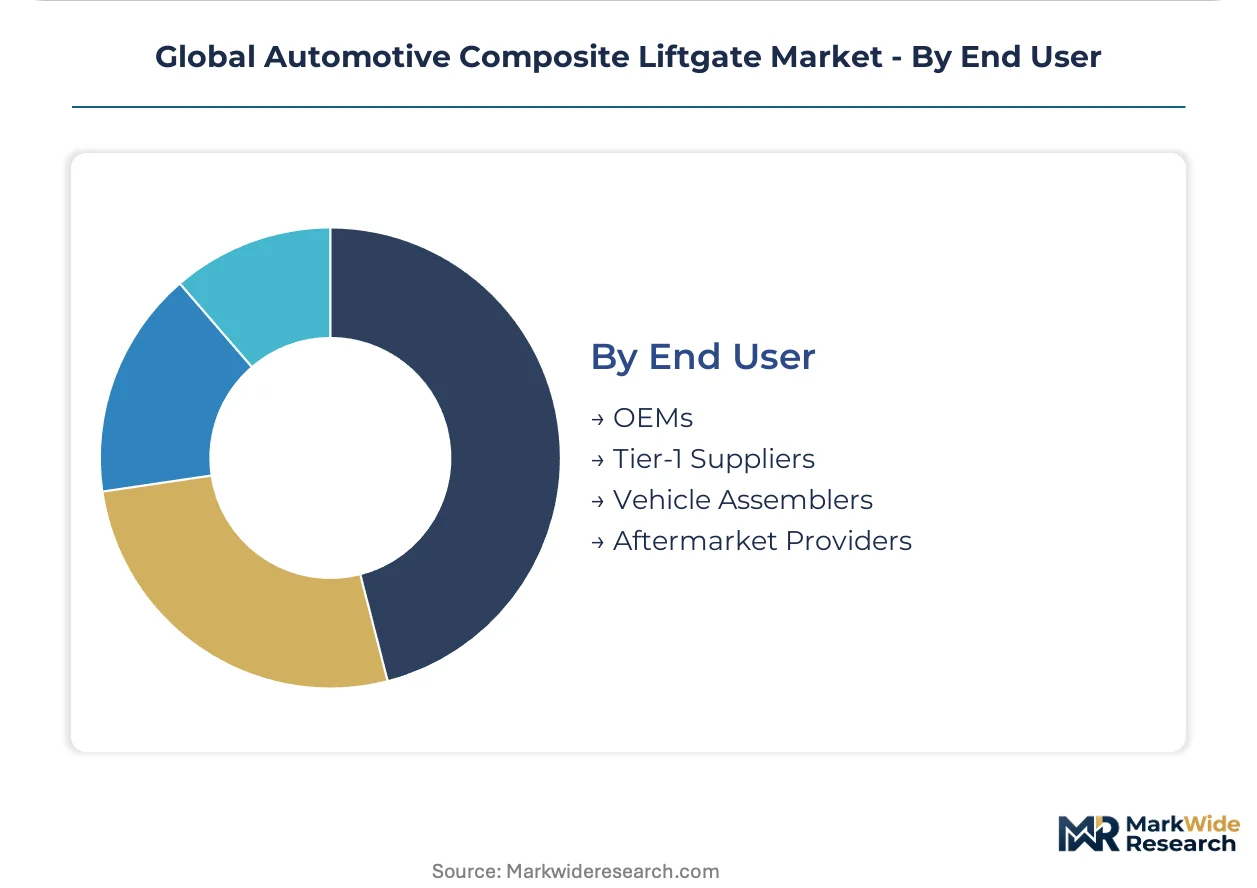
End User:
Customer type dictates specification authority and contract structure complexity.
- OEMs:Volkswagen Group and Hyundai-Kia issue consolidated procurement contracts for complete liftgate modules combining composite shells with mechatronic hardware. Direct OEM relationships require 18-24 month qualification cycles but capture margin expansion through system integration.
- Tier-1 Suppliers:Brose Fahrzeugteile and comparable integrators intermediate between material suppliers and vehicle assemblers, controlling actuation hardware specification.
- Vehicle Assemblers:Contract manufacturers in emerging EV production clusters source pre-qualified module assemblies.
- Aftermarket Providers:Repair and customization channels drive demand for compatible surface finishes and localized bonding solutions.
OEMs concentrate specification authority. Tier-1 Suppliers are consolidating module integration scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German composite liftgate suppliers export Class-A surface modules to Stuttgart and Munich OEM clusters, while Chinese manufacturers serve domestic EV platforms under MIIT mandates. This trade corridor pattern repeats across major automotive production geographies.
United States
EPA CAFE standards compel Detroit Three automakers to adopt lightweight closure systems for truck and SUV platforms. The Inflation Reduction Act's domestic content provisions incentivize localized composite manufacturing. Michigan and Ohio assembly corridors sustain demand for integrated liftgate modules with power-actuation hardware.
Germany
Premium SUV production in Baden-Württemberg and Bavaria drives procurement of carbon fiber-reinforced liftgates with spoiler integration. REACH compliance under ECHA accelerates substitution of solvent-based primers in surface finishing. Stuttgart OEM clusters specify Class-A composite modules for Mercedes-Benz and Porsche EV architectures.
China
MIIT new-energy vehicle mandates enforce lightweight structural component adoption across domestic BEV platforms. GB standards for automotive composites establish qualification protocols for closure assemblies. Yangtze River Delta and Pearl River Delta production bases concentrate EV assembly lines sourcing glass fiber-reinforced liftgates.
South Korea
Hyundai-Kia consolidated procurement contracts favor single-source module suppliers combining composite shells with mechatronic hardware. MFDS chemical safety requirements extend to automotive material disclosure. Gyeonggi-do and Busan-Ulsan manufacturing belts anchor domestic EV platform composite adoption.
India
PLI scheme production-linked incentives for domestic EV manufacturing create greenfield composite adoption potential absent legacy metal-stamping infrastructure. BIS standards for automotive plastics establish quality benchmarks. Maharashtra and Gujarat assembly corridors attract tier-1 suppliers establishing compression-molding capacity.
Global Automotive Composite Liftgate Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered supply positions. Consolidated procurement contracts from Volkswagen Group and Hyundai-Kia favor suppliers with captive mechatronic integration capabilities. Two strategic archetypes dominate: vertically integrated module integrators and material-focused composite processors. Competitive moves center on backward integration into resin compounding and geographic co-location with OEM assembly clusters.
Among North American module integrators, Magna International represents the vertically integrated archetype with in-house control over resin-to-assembly cost structures. European specialists exemplify the Class-A surface tier: Plastic Omnium Group anchors compression-molding expertise, while Brose Fahrzeugteile occupies a position combining composite shells with power-actuation hardware. These three companies illustrate the competitive tension between scale-driven consolidation and specialization in integrated liftgate systems.
| Leading Market Players |
|---|
| Magna International |
| Plastic Omnium Group |
| Brose Fahrzeugteile |
| Huf Group |
| Trinseo |
| Faurecia |
| IDI Composites International |
| Auto Body Parts |
| Stellantis |
| Others |
Cost & Logistics Intelligence
The Shanghai-Rotterdam maritime corridor carries compression-molding dies and carbon fiber prepregs from Chinese resin compounders to European Class-A surface finishers, with freight cost volatility amplifying margin pressure for suppliers serving Stuttgart and Munich OEM clusters while enabling price differentiation between captive in-house production and outsourced module procurement.
Pricing Analysis
The thermoplastic-thermoset pricing gap separates current-gen compression-molded glass fiber liftgates from prior-gen hand lay-up prototypes and next-gen automated fiber placement carbon fiber architectures. Contract-based long-term offtake dominates OEM procurement, with price differentiation driven by surface certification grade and volume scale commitments. Cost compression in mid-volume thermoplastic tiers is intensifying because epoxy resin feedstock volatility and energy costs in European polymer production are squeezing thermoset-dependent suppliers. Fleet procurement teams at commercial vehicle operators exhibit highest price sensitivity, while luxury EV platform engineers prioritize gram-level mass reduction over unit cost.
Supply Chain Analysis
Magna International and Plastic Omnium Group hold captive compression-molding capacity across Michigan, Ontario, and Bavarian manufacturing corridors. Geographic supply concentrates in Germany, China, and the United States, with raw material dependencies spanning Saudi petrochemical feedstocks for epoxy resins, Japanese carbon fiber tow, and German specialty tool steel for Class-A surface dies. Single-source vulnerability in 12-18 month lead-time tooling creates structural risk for OEMs qualifying new liftgate platforms. Distribution runs through consolidated module procurement contracts issued by Volkswagen Group and Hyundai-Kia, displacing discrete component sourcing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive composite liftgate market tracks the capital equipment investment cycle, with OEM platform refresh schedules and EV production ramp timelines serving as the primary cyclical driver governing demand inflection.
For Market Incumbents: Pre-empt margin erosion from emerging thermoplastic compounders by securing backward integration into bio-based polyurethane resin compounding and expanding compression-molding footprint in Yangtze River Delta EV production clusters. Lock in 18-24 month qualification cycles with Stuttgart OEMs before REACH chemical restrictions force reformulation of legacy epoxy hardeners.
For New Entrants and Emerging Players: India's PLI scheme corridors offer white-space opportunity absent legacy metal-stamping infrastructure and established supplier relationships. Target Maharashtra and Gujarat assembly belts with localized glass fiber prepreg supply and rapid tooling partnerships with domestic die makers. Pursue direct-to-OEM digital configurator channels bypassing tiered supply negotiations.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded automotive composite assets outside core portfolio focus. The 5-10 year viability window favors suppliers with captive mechatronic integration capabilities serving consolidated procurement contracts. Monitor ECHA substance-of-very-high-concern listings as inflection signal for material substitution capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen Group's unified EV architecture reduces liftgate variant complexity and compresses supplier qualification timelines. |
| Backward Integration into Resin Compounding | Magna International's in-house polypropylene formulation control insulates margin from petrochemical feedstock volatility. |
| Geographic Manufacturing Footprint | Plastic Omnium Group's Bavarian co-location with Stuttgart OEM clusters minimizes logistics cost for Class-A surface modules. |
| Software-Defined Vehicle Investment | Integrated camera and sensor module calibration requires composite liftgate suppliers to embed firmware validation capabilities. |
| Long-term Supply Agreement | Hyundai-Kia consolidated procurement contracts favor single-source module suppliers with captive mechatronic hardware integration. |
Research Approach
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier production data anchors the qualitative findings. Primary interviews with composite material scientists, automotive procurement directors, and mechatronic hardware engineers combine with secondary validation from EPA CAFE compliance filings, MIIT new-energy vehicle production statistics, and ECHA substance restriction updates. Bottom-up vehicle production forecasts and top-down lightweighting mandate trajectories triangulate market sizing across material type, vehicle application, and manufacturing technique segmentation.
Calibration against historical adoption curves for comparable exterior body panel substitutions informs the analytical framework across the projection horizon. Segmentation dimensions modeled include propulsion architecture, surface finish certification tier, and regional OEM production cluster. CAGRs derive from elasticity estimates linking fleet efficiency mandate stringency to closure system lightweighting intensity, with battery mass penalties and carbon fiber process innovation serving as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese resin compounders or accelerated ECHA chemical restrictions would shift outcomes beyond modeled ranges. Quarterly review of MIIT production license approvals and ECHA SVHC consultation lists is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
US Group 2 Powered Mobility Devices Market
Vehicle Components
Idler Arm Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
Suction Road Sweeper Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Engine Air Filter Market
Vehicle Components
Portable Wheel Jack Market
Vehicle Components
Global Navigation Lighting Market
Vehicle Components
Steering Stabilizers Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Composite Bearings Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
United Kingdom Vacuum Truck Market
Vehicle Components
Mobile Liquid Tanks Market