
 Automotive Liftgate Market | 2026-2036
Automotive Liftgate Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Liftgate Market Analytics
China's Jiangsu and Zhejiang province cluster is rewriting regional supply dynamics for powered closure systems. Magna International Inc. leverages its stamping and assembly footprint across North American SUV platforms. Brose Fahrzeugteile GmbH & Co. KG anchors European premium hatchback programs with mechatronic module specialization. Aisin Corporation competes through integrated motor-and-latch architectures that reduce wiring complexity.
An automotive liftgate is a vertically hinged rear closure panel, typically spanning 1.0 to 1.8 meters in width, that incorporates gas struts, torsion rods, or electromechanical actuators to enable controlled opening and cargo access. Power liftgate variants integrate torque-sensing motors, anti-pinch sensors, and CAN-bus communication protocols to deliver hands-free operation via foot-motion detection or key fob activation. Power liftgate systems command the dominant value share as OEMs standardize hands-free entry across mid-size SUV segments. Smart liftgate variants with programmable height stops and smartphone connectivity represent the fastest-expanding category, though from a smaller installed base. Composite material adoption is accelerating as manufacturers substitute glass-reinforced thermoplastics for steel stampings to achieve mass reduction targets without sacrificing torsional stiffness.
NHTSA Federal Motor Vehicle Safety Standard 401 mandates trunk release mechanisms that directly influence emergency-access latch designs, while EPA Corporate Average Fuel Economy standards pressure suppliers toward lighter closure assemblies. China's MIIT enforces GB standards for electromagnetic compatibility that shape motor controller specifications for powered systems. Stakeholders must monitor evolving UN ECE regulations on pedestrian protection, as rear-impact compliance requirements will dictate next-generation liftgate reinforcement geometries and sensor placement strategies.
Market Dynamics
Hands-free power liftgate standardization across mid-size SUV segments is compressing supplier margins while forcing module consolidation, as OEMs demand integrated motor-latch architectures that eliminate discrete component sourcing.
Growth Catalysts
- Hands-Free Entry Mandates:NHTSA rear-visibility regulations in the United States require integrated camera and sensor packages that power liftgate systems natively accommodate.
- Lightweighting Imperatives:EPA Corporate Average Fuel Economy standards pressure closure assembly mass reduction, accelerating glass-reinforced thermoplastic substitution for steel stampings.
- Electric SUV Proliferation:Germany's accelerating electric SUV adoption creates demand for sophisticated hands-free power liftgate systems with programmable height stops.
Market Restraints
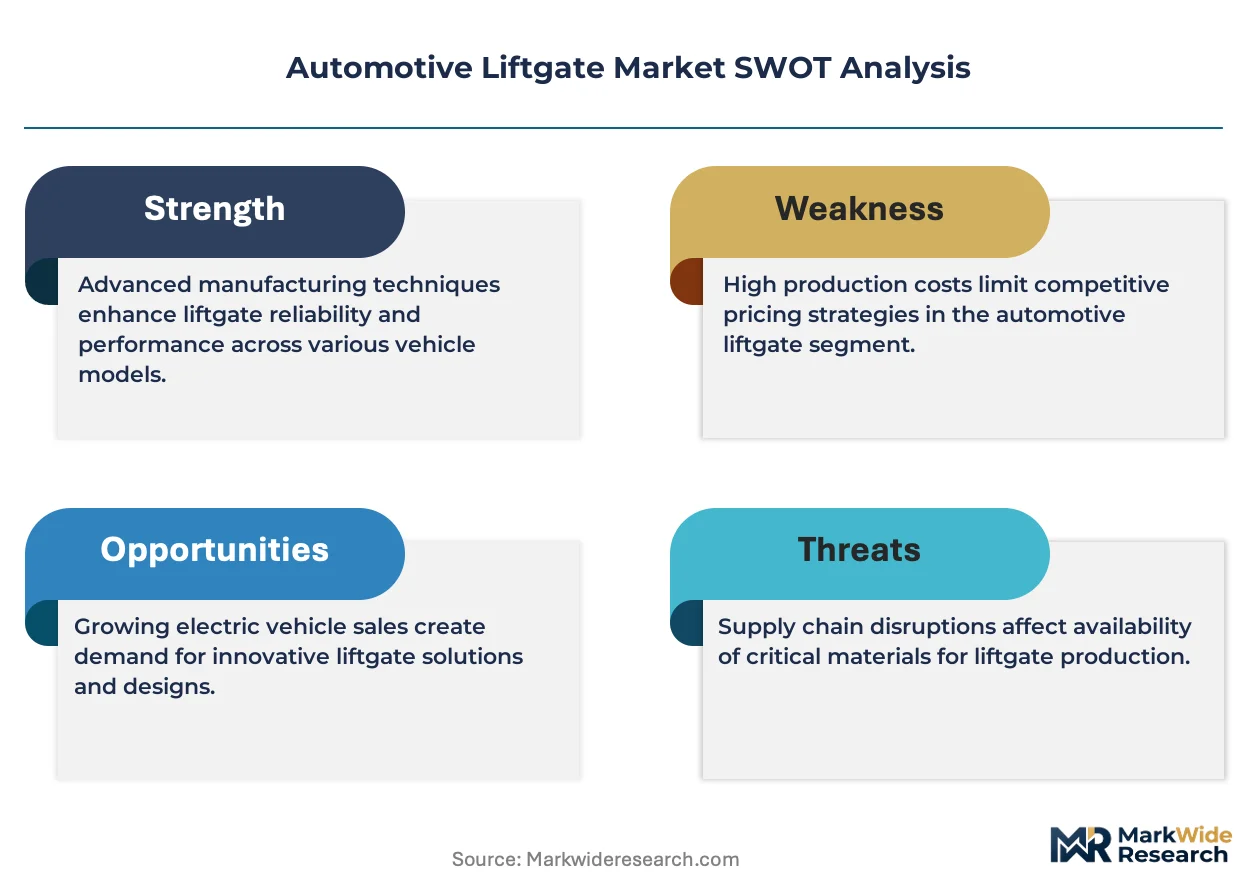
- Raw Material Volatility:Rare earth magnet price swings for torque-sensing motors create unpredictable input cost structures for electromechanical actuator production.
- Supply Concentration Risk:China's Yangtze River Delta automotive manufacturing corridor dominates powered closure system component sourcing, creating geographic vulnerability.
- Electromagnetic Compatibility Friction:China's MIIT GB standards for motor controller specifications impose testing bottlenecks that delay product launches.
Strategic Opportunities
- Smart Liftgate White Space:Smartphone connectivity and programmable height stops represent underpenetrated feature sets across economy SUV segments in India.
- Pedestrian Protection Tailwind:Evolving UN ECE regulations on rear-impact compliance will dictate next-generation sensor placement strategies that first-movers can patent.
- Composite Architecture Convergence:Integration of carbon fiber-reinforced polymers with anti-pinch sensor arrays enables mass reduction without sacrificing torsional stiffness.
Industry Challenges
- Mechatronics Talent Scarcity:Shortage of engineers proficient in CAN-bus communication protocol integration with torque-sensing motor calibration.
- Legacy Platform Integration:Retrofitting power liftgate systems into existing SUV architectures requires expensive wiring harness redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Liftgate Market |
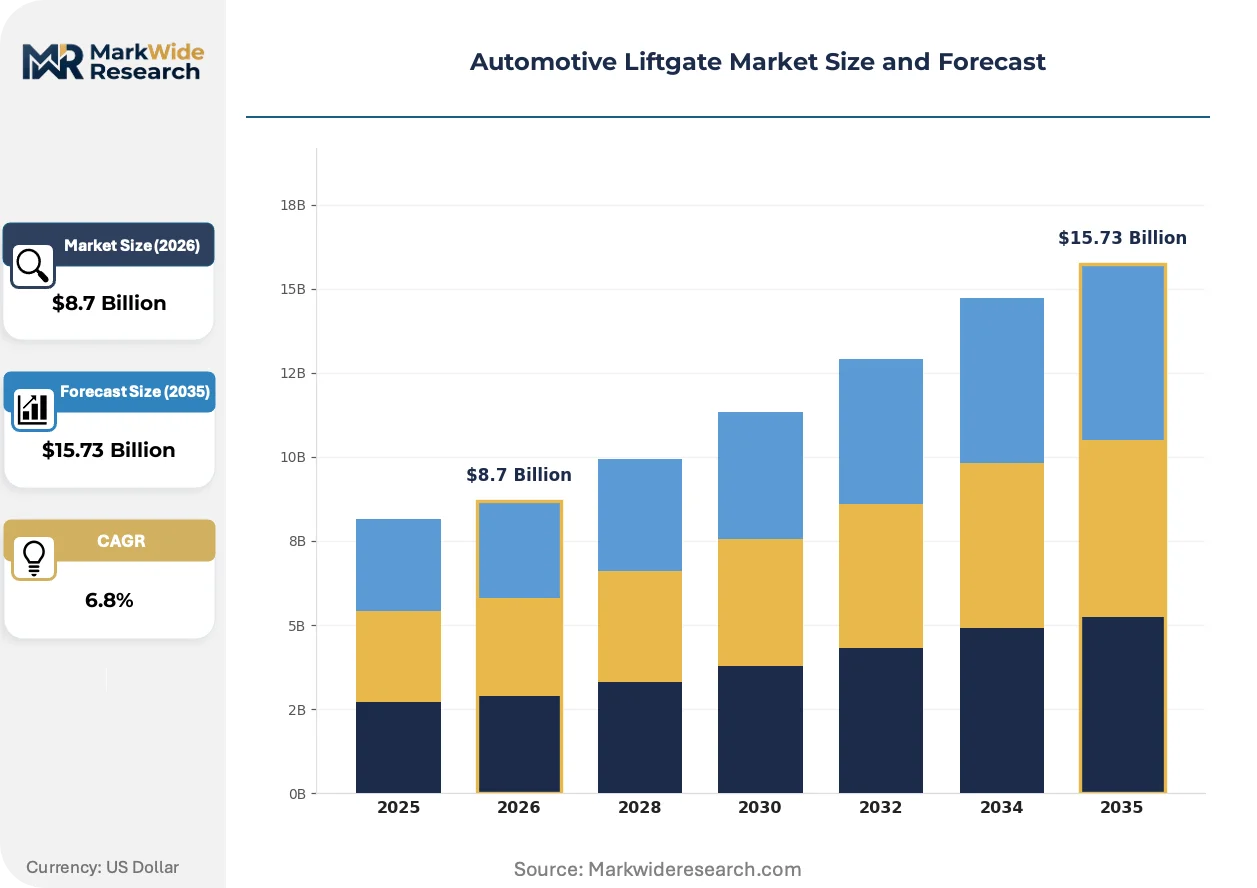
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Liftgate, Power Liftgate, Smart Liftgate, Tailgate Material: Steel, Aluminum, Composite, Plastic Vehicle Type: SUV, Sedan, Pickup Truck, Hatchback End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators |
| Companies Covered | Magna International Inc., Brose Fahrzeugteile GmbH & Co. KG, Aisin Corporation, Continental AG, Faurecia SE, Johnson Electric Holdings Limited, Huf Hulsbeck & Furst GmbH & Co. KG, Denso Corporation, Plastic Omnium Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Liftgate Market Evolving Landscape
Electrification of rear closure systems is converging with connectivity mandates and material science breakthroughs, reshaping how suppliers architect motor-and-latch modules.
Strain-sensing composite materials embedded directly into liftgate structural panels are rendering obsolete discrete anti-pinch sensor arrays that require separate mounting brackets and wiring runs. Premium electric SUV manufacturers in Germany are adopting these integrated architectures for 2026 model year launches. This consolidation is rendering obsolete the multi-supplier model where stampers, sensor vendors, and wiring specialists operated independently.
UN ECE pedestrian protection regulations are mandating deformable rear closure geometries that absorb impact energy without compromising cargo access functionality. European hatchback programs must now validate liftgate reinforcement strategies through standardized head-impact simulations. Suppliers serving Brose Fahrzeugteile GmbH & Co. KG's premium customer base are accelerating development of programmable deformation zones.
Fleet procurement departments are consolidating supplier relationships around full-system integrators capable of delivering motor, latch, and controller as a single validated module. Direct OEM sourcing of discrete components is contracting as manufacturers seek single-source accountability for warranty claims. This concentration is most visible in China's Jiangsu and Zhejiang province cluster, where Magna International Inc. and Aisin Corporation compete for platform-level contracts rather than component orders.
Automotive Liftgate Market Segmentation
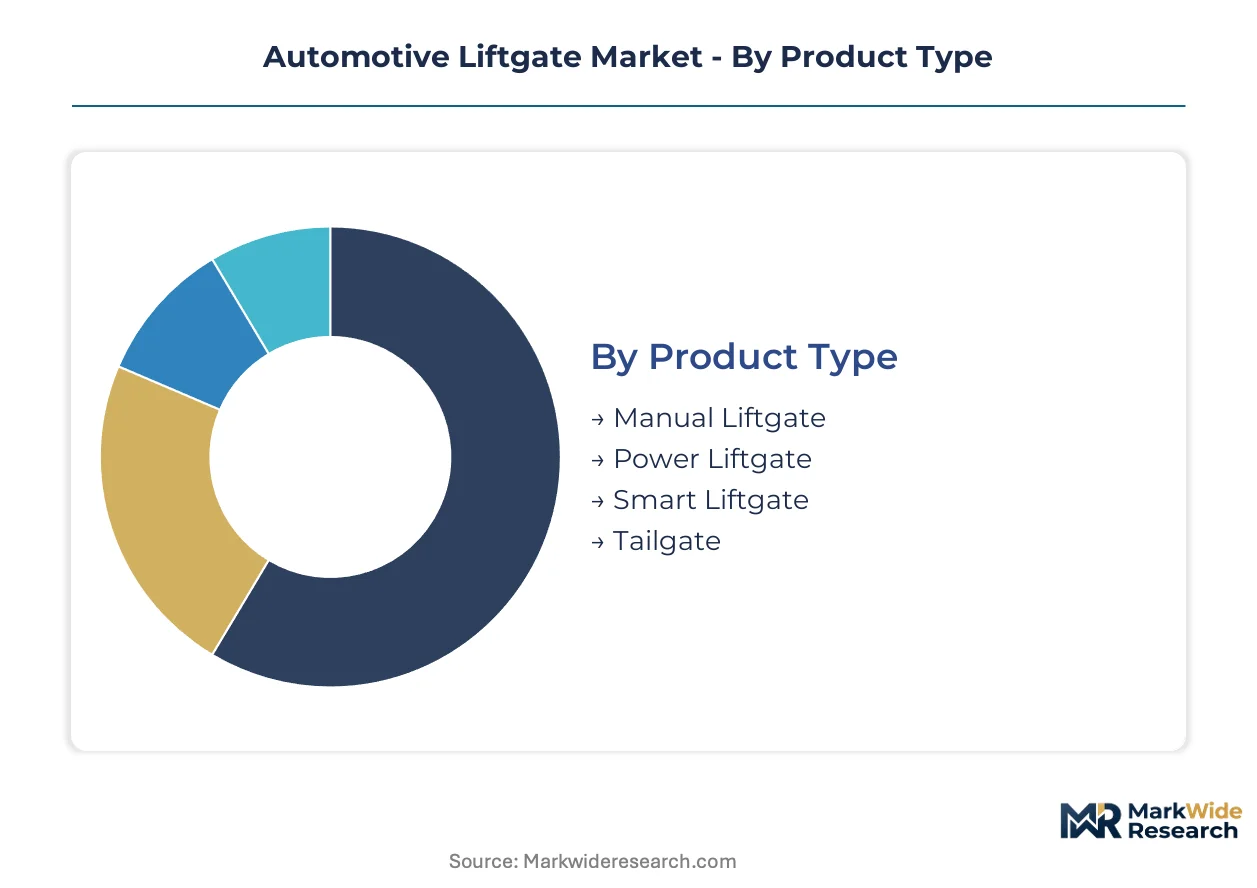
Segmentation in the automotive liftgate market reveals how powertrain electrification, material substitution, and hands-free entry mandates are reshaping supplier priorities across closure system architectures. Understanding these divides enables stakeholders to align R&D spending with where OEM procurement is concentrating.
Product Type:
Mature mechanical variants coexist with emerging electromechanical architectures as electrification penetrates mid-range vehicle segments.
- Manual Liftgate:Gas strut and torsion rod mechanisms dominate entry-level SUV and sedan programs where cost containment outweighs convenience features. Demand persists in India's compact SUV segment and Brazil's fleet vehicle market, though share erosion accelerates as power systems standardize upstream.
- Power Liftgate:Torque-sensing motors with anti-pinch sensors and CAN-bus integration now define mid-size SUV specification sheets across Germany's electric vehicle platforms. NHTSA rear-visibility regulations in the United States mandate integrated camera packages that power liftgate modules natively accommodate, compressing discrete supplier margins.
- Smart Liftgate:Smartphone connectivity and programmable height stops command premium positioning on European electric SUVs. Brose Fahrzeugteile GmbH & Co. KG anchors development of foot-motion detection algorithms for German OEM programs.
- Tailgate:Horizontally hinged variants serve North American pickup truck architectures with integrated step and work surface features. Ford and Ram platform specifications drive aluminum-intensive designs for load-bearing duty cycles.
Power Liftgate retains volume leadership; Smart Liftgate holds the steepest expansion curve.
Material:
Cost tiers separate commodity metals from advanced composites as mass reduction targets intensify across regulatory jurisdictions.
- Steel:High-strength stamped grades maintain dominance in full-size pickup tailgates where impact resistance and repairability outweigh mass penalties. China's Yangtze River Delta stamping corridors supply North American OEMs with hot-formed reinforcement blanks.
- Aluminum:Extruded and sheet alloys enable 40-50% mass reduction in premium SUV liftgates without sacrificing torsional stiffness. Jaguar Land Rover and Mercedes-Benz SUV programs specify aluminum-intensive architectures for electric range optimization.
- Composite:Glass-reinforced thermoplastics substitute for steel in hatchback programs where complex geometries and parts consolidation justify tooling investment. Strain-sensing composites embedded with anti-pinch functionality are displacing discrete sensor arrays in German electric SUV launches.
- Plastic:Injection-molded panels serve interior trim and secondary structural applications where cosmetic finish and corrosion resistance matter more than load-bearing capacity. Southeast Asian compact vehicle programs favor polypropylene-based solutions for cost positioning.
Steel commands the installed base; composite architectures are climbing the fastest as electrification tightens mass budgets.
Vehicle Type:
Application intensity varies dramatically across body styles, with SUV proliferation dictating power liftgate standardization curves.
- SUV:Mid-size and full-size segments drive hands-free power liftgate adoption as a competitive necessity. China's Jiangsu and Zhejiang province cluster concentrates sourcing for powered closure modules serving both domestic brands and export programs.
- Sedan:Trunk lid architectures limit power actuation penetration to premium segments where brand positioning justifies incremental cost. Japanese and Korean OEMs specify simplified motor-latch modules for flagship sedan programs.
- Pickup Truck:Multi-function tailgates with power articulation represent the fastest-growing sub-segment within North American truck platforms. GM and Stellantis compete on bed access innovations that integrate with trailer hitch cameras.
- Hatchback:European C-segment and B-segment programs balance cost with convenience, often specifying semi-powered assist rather than full electromechanical actuation. French and Italian OEMs prioritize compact motor packaging for rear glass integration.
SUV platforms anchor procurement volume; pickup truck tailgate complexity is gaining share fastest.
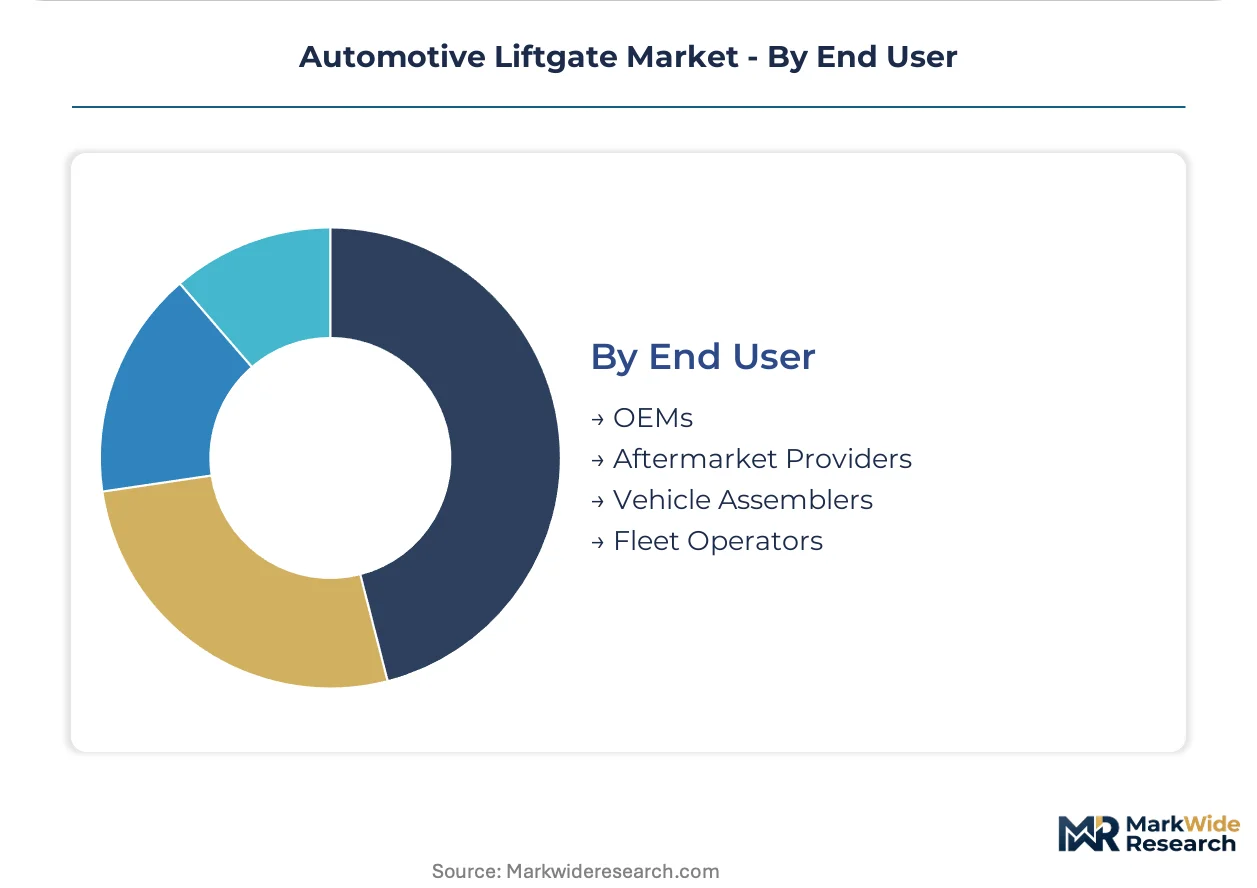
End User:
Customer type determines warranty accountability structures and module integration depth.
- OEMs:Direct platform engineering relationships demand full-system validation from Magna International Inc. and Aisin Corporation for global SUV programs. Single-source accountability for motor, latch, and controller integration is consolidating supplier relationships.
- Aftermarket Providers:Retrofit power liftgate kits serve aging SUV fleets in markets where factory specification lagged feature penetration. Installation complexity and wiring harness compatibility limit addressable volume.
- Vehicle Assemblers:Contract manufacturers in China's Yangtze River Delta corridor source powered closure modules for domestic electric vehicle startups. NIO and XPeng specifications mirror European premium feature sets.
- Fleet Operators:Commercial vehicle procurement prioritizes durability and service interval predictability over convenience features. Last-mile delivery van programs in Germany specify manual systems with reinforced hinge geometries.
OEMs dominate procurement volume; vehicle assemblers for emerging electric brands are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Zhejiang province cluster concentrates powered closure system sourcing for global OEM programs. Germany's electric SUV proliferation drives hands-free power liftgate standardization. NHTSA rear-visibility regulations in the United States mandate integrated camera packages that reshape supplier specifications.
United States
Mid-size SUV procurement dominates power liftgate volume as Detroit Three OEMs standardize hands-free entry across fleet configurations. NHTSA Federal Motor Vehicle Safety Standard 401 mandates trunk release mechanisms that directly influence emergency-access latch designs. Michigan and Ohio-based stamping corridors supply hot-formed reinforcement blanks for North American truck tailgate programs.
Germany
Premium electric SUV adoption accelerates demand for smart liftgate systems with programmable height stops and foot-motion detection. KBA type-approval processes enforce UN ECE pedestrian protection standards that dictate deformable rear closure geometries. Bavaria-based mechatronic specialists anchor development for Mercedes-Benz and BMW platform engineering.
China
Domestic electric vehicle startups NIO and XPeng specify European-equivalent feature sets for powered closure modules. MIIT enforces GB standards for electromagnetic compatibility that shape motor controller specifications and delay product launches. The Yangtze River Delta manufacturing corridor dominates component sourcing for both domestic brands and export programs.
Japan
Flagship sedan programs from Toyota and Honda specify simplified motor-latch modules where brand positioning justifies incremental cost. METI industrial policy supports lightweight material R&D for closure assembly mass reduction targets. Aichi Prefecture suppliers concentrate on compact motor packaging for rear glass integration in hatchback architectures.
India
Compact SUV segments balance cost with convenience, often specifying semi-powered assist rather than full electromechanical actuation. BIS certification requirements for automotive components create compliance barriers for imported powered closure systems. Tamil Nadu and Gujarat vehicle assembly corridors source manual systems with reinforced hinge geometries for fleet durability priorities.
Automotive Liftgate Market Competitive Landscape
Full-system integrators and component specialists split the market between platform-level contracts and discrete supply relationships. Tier-1 suppliers with stamping and mechatronic capabilities capture consolidated OEM procurement as single-source accountability replaces multi-vendor sourcing. Two archetypes dominate: integrated motor-latch-controller module providers and specialized sensor or materials vendors. Competitive intensity manifests through portfolio diversification into smart connectivity features and backward integration into composite material production.
Within the integrated module tier, Magna International Inc. and Aisin Corporation occupy positions defined by their North American and Asian manufacturing footprints respectively. Brose Fahrzeugteile GmbH & Co. KG anchors the European premium specialization archetype through its German engineering base. These three exemplify how geographic proximity to OEM engineering centers shapes competitive positioning in a market where validation timelines and warranty accountability favor regional supply relationships.
| Leading Market Players |
|---|
| Magna International Inc. |
| Brose Fahrzeugteile GmbH & Co. KG |
| Aisin Corporation |
| Continental AG |
| Faurecia SE |
| Johnson Electric Holdings Limited |
| Huf Hulsbeck & Furst GmbH & Co. KG |
| Denso Corporation |
| Plastic Omnium Group |
| Others |
Value Network & Pricing Analysis
Rare earth magnet price volatility for torque-sensing motors compresses both tier spreads and supplier consolidation choices, forcing module integrators to absorb input swings or pass them through to OEM procurement contracts. This cost uncertainty accelerates backward integration into captive magnet sourcing while widening price gaps between steel-intensive manual systems and composite-architecture smart liftgates.
Pricing Analysis
NHTSA Federal Motor Vehicle Safety Standard 401 dictates the pricing tier structure by mandating emergency-access latch mechanisms that add compliance cost floors across all powered variants. Three-tier pricing structure across premium, standard, and economy levels separates smart liftgates with programmable height stops from basic power systems and manual gas-strut alternatives. Cost compression in mid-size SUV power modules is intensifying because OEMs demand integrated motor-latch architectures that eliminate discrete component margins. Fleet operators in commercial van segments exhibit highest price sensitivity, while premium electric SUV buyers absorb connectivity premiums without volume elasticity.
Supply Chain Analysis
Tariff exposure between China and North American assembly plants dominates supply chain risk calculus for powered closure module sourcing. China's Yangtze River Delta corridor, Germany's Bavaria mechatronics cluster, and Mexico's automotive assembly corridors anchor global production gravity for liftgate systems. Rare earth magnet supply draws from Chinese processing facilities, glass-reinforced thermoplastics feed from German compounders, and aluminum extrusions source from Canadian smelters. Single-source vulnerability concentrates in torque-sensing motor controllers subject to MIIT GB standards testing bottlenecks. Distribution runs through Tier 1 full-system integrators rather than discrete component vendors as OEM procurement consolidates around single-source accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams from over-the-air software updates and predictive maintenance subscriptions for smart liftgate systems are expanding faster than hardware replacement cycles, repositioning suppliers as recurring-revenue platforms rather than discrete component vendors.
For Market Incumbents: Build switching-cost moats through CAN-bus protocol lock-in and embedded sensor calibration IP that raises retrofit barriers for challenger module suppliers. Deepen backward integration into strain-sensing composite production to capture margin pools migrating from discrete anti-pinch arrays. Defensive consolidation around full-system validation capabilities addresses emerging electric SUV platform engineering demands from NIO and XPeng specifications.
For New Entrants and Emerging Players: Establish a beachhead in India's compact SUV semi-powered assist segment where European feature sets lag domestic cost positioning. White-space targets include economy SUV smartphone connectivity modules and aftermarket retrofit kits for aging manual liftgate fleets. Go-to-market leverage rests on wiring harness compatibility databases that reduce installation complexity for independent service channels.
For Investors and Strategic Acquirers: The market sits at a module-consolidation phase that favors full-system integrators with captive composite production and OEM platform engineering relationships. Long-term viability over the next decade hinges on software-defined feature roadmaps rather than hardware cost curves. Acquisition target archetype: mechatronics specialists with embedded motor-latch-controller validation histories serving KBA or NHTSA regulatory clusters. Signal to watch: UN ECE pedestrian protection regulation finalization timing that will trigger redesign cycles and patent-positioning races.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation around integrated motor-latch modules reduces multi-vendor complexity for mid-size SUV programs. |
| Backward Integration into Composites | In-house production of glass-reinforced thermoplastics captures margin migration from steel stampings and discrete sensors. |
| Software-Defined Vehicle Investment | Over-the-air programmable height stops and connectivity features create recurring revenue attachment to hardware sales. |
| Geographic Manufacturing Footprint | Proximity to Yangtze River Delta and Bavaria engineering centers accelerates validation timelines for premium electric SUV launches. |
| Charging Infrastructure Partnership | Integration of liftgate sensors with trailer hitch camera packages addresses NHTSA rear-visibility mandate compliance. |
Research Methodology
Desk research of vehicle production databases, regulatory filing repositories, and IHS Markit registration data preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers. Primary fieldwork across China's Jiangsu and Zhejiang province cluster, Germany's Bavaria mechatronics corridor, and Michigan-based stamping operations validated secondary estimates. Bottom-up unit economics modeling triangulated against top-down market size assessments from vehicle segmentation and content-per-vehicle assumptions.
Forecast outputs rest on fixed assumptions regarding NHTSA regulatory enforcement timelines, MIIT GB standards testing throughput, and rare earth magnet price band stability across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from logistic diffusion curves fitted to power liftgate penetration rates by SUV segment and smart feature adoption elasticities in premium electric vehicle platforms.
Stress conditions across rare earth magnet price volatility bands, tariff rate scenarios, and MIIT certification delay distributions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sustained electric SUV proliferation and hands-free entry standardization curves. Material shifts in UN ECE pedestrian protection regulation timing or NHTSA rear-visibility mandate enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Impact-Modified PCR Plastics for Automotive Interiors Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
United States Car Bumper Guard Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Auto Glass Encapsulation Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
LED Fog Lamp Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Automotive Windshield Market