
 Driveline Systems for Electric Vehicle Market | 2026-2036
Driveline Systems for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Driveline Systems for Electric Vehicle Market Analysis
German Tier-1 suppliers is broadening e-axle assembly capacity across the Rhine-Ruhr and Stuttgart corridors. BorgWarner Inc. leverages its power electronics integration to anchor North American OEM supply agreements. ZF Friedrichshafen AG sustains gearbox-dominant positions while extending into full e-drive modules. Schaeffler AG differentiates through torque-vectoring differential technology for premium architectures.
Driveline systems for electric vehicles comprise the integrated electromechanical powertrain that transmits torque from electric motors to driven wheels, typically incorporating permanent magnet synchronous motors with 150-300 kW continuous ratings, multi-speed or single-speed reduction gearboxes, and silicon carbide inverters. Their primary purpose is to optimize efficiency across vehicle speed-load profiles while packaging within constrained axle or chassis volumes. High power motor-inverter combinations command concentrated margin pools as OEMs pursue 800V architectures for premium passenger cars and commercial trucks. Bolt-on installation methods retain share in retrofit and niche conversion segments, though integrated e-axle platforms are displacing modular approaches in clean-sheet EV designs.
EPA tailpipe regulations and NHTSA CAFE standards in the United States mandate fleet-average CO2 reductions that compel OEMs to electrify light-duty and medium-duty lineups. EMA and REACH in Europe impose substance restrictions and end-of-life accountability on motor magnets and gearbox lubricants, reshaping supplier material selection. China's MIIT enforces dual carbon compliance timelines that accelerate domestic driveline certification cycles. Stakeholders must monitor how battery-electric platform consolidation among OEMs alters sourcing leverage between captive driveline production and external Tier-1 supply.
Market Dynamics
Integrated e-axle platforms are consolidating motor, inverter, and gearbox functions into single units, forcing Tier-1 suppliers to retool assembly lines and OEMs to rewrite sourcing specifications around power density rather than component modularity.
Growth Catalysts
- China's MIIT dual carbon goals:Domestic OEMs must localize driveline sourcing to meet fleet-average emissions compliance, accelerating certification cycles for permanent magnet motor suppliers in the Yangtze River Delta cluster.
- 800V architecture migration:Silicon carbide inverters enable faster charging and reduced copper mass, pulling demand from premium passenger car and commercial truck segments toward integrated high-voltage e-drive modules.
- Ride-hailing electrification:Fleet operators across battery-electric passenger car services are standardizing on integrated e-axle platforms to minimize downtime and simplify maintenance protocols.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing capacity clusters in China's Inner Mongolia and Jiangxi provinces, exposing motor manufacturers to export quota volatility and forced localization mandates.
- Copper winding cost exposure:Stator and rotor assemblies consume high-purity copper in quantities that track London Metal Exchange price swings, compressing margins on high-power motor-inverter combinations.
- REACH substance restrictions:ECHA regulations on gearbox lubricant formulations and end-of-life magnet accountability force reformulation cycles that extend supplier qualification timelines.
Strategic Opportunities
- Commercial truck electrification:Medium-duty and heavy-duty battery-electric platforms remain undersupplied with torque-dense e-axles capable of sustained 300 kW continuous output, opening white space for integrated module specialists.
- Retrofit and conversion segments:Bolt-on driveline kits retain demand in niche vehicle electrification projects where clean-sheet platform engineering is economically unviable.
- US EPA tailpipe mandates:Fleet-average CO2 reduction requirements compel light-duty and medium-duty OEMs to accelerate electrification roadmaps, expanding addressable market for North American e-axle assembly capacity.
Industry Challenges
- Power electronics talent scarcity:Silicon carbide inverter design and thermal management engineering functions face acute hiring competition from semiconductor and renewable energy sectors.
- Multi-physics simulation complexity:Electromagnetic, thermal, and mechanical load case integration for e-axle platforms demands CAE capabilities that outstrip legacy gearbox engineering benches.
- ISO 26262 functional safety certification:ASIL-D compliance for motor control software extends development timelines and requires specialized verification partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driveline Systems for Electric Vehicle Market |
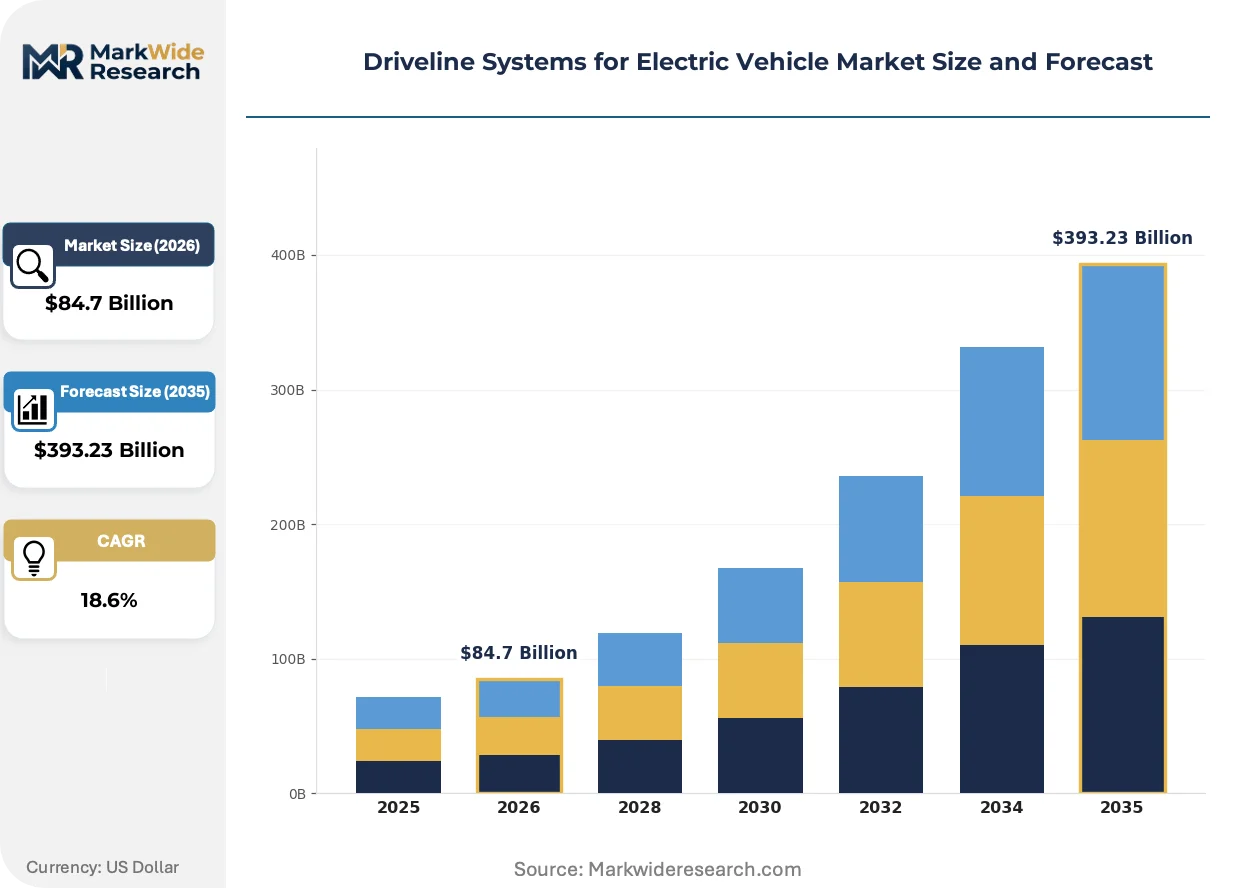
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $393.23 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Electric Motors, Gearboxes, Inverters, Differential Units Installation Method: Integrated, Bolt-on, Modular, Customizable Power Rating: High Power, Medium Power, Low Power, Ultra High Power Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Buses |
| Companies Covered | BorgWarner Inc., GKN Automotive, ZF Friedrichshafen AG, Schaeffler AG, Continental AG, Robert Bosch GmbH, Dana Incorporated, Aisin Corporation, Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driveline Systems for Electric Vehicle Market Emerging Trajectories
Silicon carbide semiconductors and torque-vectoring differentials are rewriting performance benchmarks, while regulatory pressure on rare earth supply chains and end-of-life accountability is reshaping material selection and supplier geography.
Silicon carbide MOSFETs replace silicon IGBTs in traction inverters, cutting switching losses by half and enabling compact thermal packaging for 800V architectures. Premium passenger car OEMs in Germany and South Korea are adopting these inverters at pace for next-generation e-axle platforms. The technology is absorbing margin pools previously captured by discrete power module assemblers as OEMs pursue in-house inverter integration.
REACH substance restrictions and EU Green Deal circular economy mandates are forcing gearbox lubricant reformulation away from perfluorinated compounds and requiring magnet recyclability documentation. European Tier-1 suppliers are requalifying grease specifications and establishing rare earth recovery partnerships to maintain component market access. Commercial truck segments face the steepest compliance cost escalation due to higher fluid volumes and extended service intervals.
Fleet procurement departments are consolidating e-axle sourcing around full-system suppliers capable of warranting motor, inverter, and gearbox as unified units, displacing modular component purchasing. This behavior concentrates contract value with integrated platform specialists and compresses supplier counts in North American and European ride-hailing electrification programs. China's fleet operators are most advanced in this transition, with Yangtze River Delta manufacturing clusters enabling same-day technical response commitments.
Driveline Systems for Electric Vehicle Market Segmentation
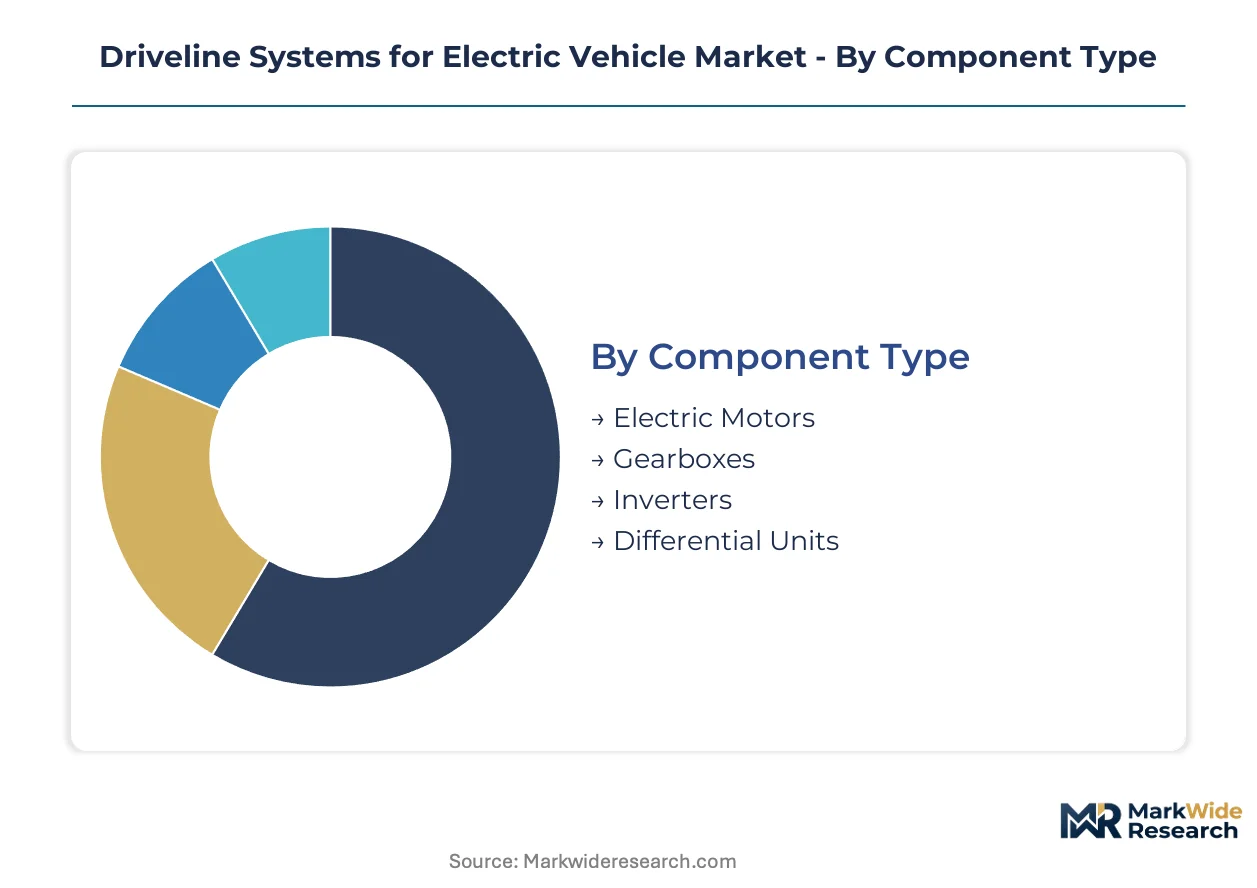
Driveline system configurations diverge sharply across voltage architectures, duty cycles, and OEM platform strategies. Component integration depth and power density requirements create distinct procurement categories with differing margin structures and supplier qualification barriers.
Component Type:
Buyers differentiate by whether they source discrete subsystems or pursue full-system integration partnerships with Tier-1 suppliers.
- Electric Motors:Permanent magnet synchronous designs with 150-300 kW continuous ratings dominate passenger car platforms. China's Yangtze River Delta manufacturing cluster concentrates stator and rotor assembly capacity as MIIT dual carbon compliance accelerates domestic certification cycles.
- Gearboxes:Single-speed reduction units capture volume in battery-electric passenger cars, while multi-speed configurations persist in commercial trucks demanding sustained torque across grade profiles. ZF Friedrichshafen AG and Schaeffler AG anchor European supply through Stuttgart and Rhine-Ruhr production corridors.
- Inverters:Silicon carbide MOSFET designs displace silicon IGBTs in 800V architectures, cutting switching losses and thermal packaging mass.
- Differential Units:Torque-vectoring differentials command premium positioning in performance-oriented architectures.
Volume sits with Electric Motors; growth tilts toward Inverters.
Installation Method:
Procurement patterns track OEM platform maturity, with clean-sheet designs favoring integration and legacy conversions retaining modularity.
- Integrated:Consolidated e-axle platforms merge motor, inverter, and gearbox into sealed units, minimizing assembly complexity and warranty fragmentation. Fleet operators across ride-hailing services standardize on these configurations to compress maintenance intervals and parts inventory.
- Bolt-on:Retrofit kits retain demand in niche vehicle electrification projects where platform engineering economics preclude clean-sheet redesign. Conversion specialists in North America and Europe source these for classic vehicle electrification and industrial equipment upgrades.
- Modular:Discrete component sourcing persists among OEMs with captive motor or inverter capabilities seeking external gearbox partnerships.
- Customizable:Engineering-service contracts address low-volume specialty vehicle manufacturers with unique packaging constraints.
Integrated captures current procurement volume; Bolt-on sustains niche margin pools.
Power Rating:
Continuous output specifications determine thermal management complexity, semiconductor selection, and copper winding mass.
- High Power:200-300 kW continuous ratings serve premium passenger cars and medium-duty commercial platforms. Silicon carbide inverter integration and liquid cooling loops concentrate margin capture among power electronics specialists.
- Ultra High Power:Sustained outputs exceeding 300 kW target heavy-duty battery-electric trucks and performance architectures. These configurations face acute neodymium magnet supply exposure and forced air or immersion cooling requirements.
- Medium Power:100-200 kW ratings dominate mass-market passenger car segments.
- Low Power:Sub-100 kW designs serve urban delivery vehicles and two-wheeler applications.
High Power anchors revenue concentration; Ultra High Power exhibits steepest expansion trajectory.
Vehicle Type:
End-use duty cycles and platform consolidation strategies reshape sourcing specifications across mobility categories.
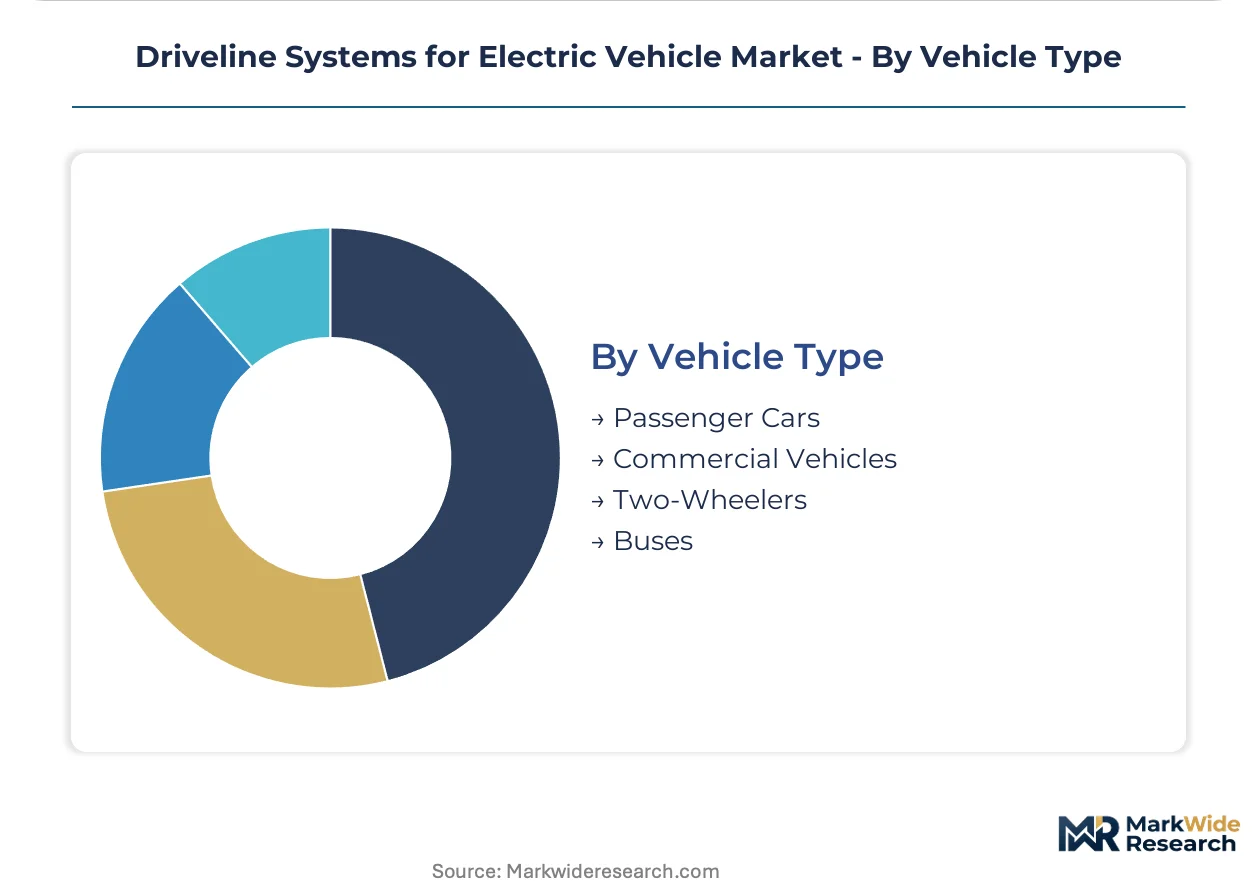
- Passenger Cars:Battery-electric platforms from German, South Korean, and Chinese OEMs drive integrated e-axle standardization. 800V architecture migration and silicon carbide adoption concentrate in this segment before trickling to commercial applications.
- Commercial Vehicles:Medium-duty and heavy-duty trucks demand torque-dense e-axles with sustained thermal performance. EPA tailpipe mandates and NHTSA CAFE standards compel North American fleet electrification, opening white space for integrated module specialists.
- Buses:Transit authority procurement specifications emphasize service interval standardization and overnight depot charging compatibility.
- Two-Wheelers:Cost-optimized hub motor and mid-drive configurations dominate Asian urban mobility markets.
Passenger Cars hold installed base dominance; Commercial Vehicles show fastest adoption velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium magnet processing capacity in China's Inner Mongolia and Jiangxi provinces anchors raw-material supply for permanent magnet motors, while silicon carbide wafer fabrication concentrates in Germany, Japan, and the United States. This geographic split between magnet supply and power semiconductor manufacturing shapes regional competitive positioning across e-axle production corridors.
China
Domestic OEMs accelerate procurement of integrated e-axle platforms under MIIT dual carbon compliance timelines. The Yangtze River Delta manufacturing cluster concentrates stator assembly and rotor winding capacity, with tier-one suppliers co-locating with CATL and BYD cell production. Shanghai and Suzhou anchor e-motor certification cycles for export-qualified suppliers.
Germany
Rhine-Ruhr and Stuttgart corridors host expanded e-axle assembly lines serving premium passenger car OEMs migrating to 800V architectures. KBA type-approval requirements and ECHA REACH substance restrictions force lubricant reformulation and magnet recyclability documentation. Baden-Württemberg suppliers integrate torque-vectoring differentials for performance platforms.
United States
EPA tailpipe regulations and NHTSA CAFE standards compel light-duty and medium-duty fleet electrification, pulling demand toward North American e-axle assembly capacity. Michigan and Ohio anchor motor-inverter integration facilities serving Detroit Three electrification roadmaps. Silicon carbide inverter design talent competes with renewable energy sector hiring.
South Korea
Seoul Capital Area OEMs adopt silicon carbide MOSFET inverters at pace for next-generation e-axle platforms. MFDS industrial standards and METI-aligned technical specifications shape component qualification timelines. Busan-Ulsan corridor concentrates gearbox-dominant suppliers extending into full e-drive modules.
Japan
Chubu/Nagoya and Kanto/Tokyo regions sustain precision gearbox engineering heritage while retooling for integrated e-axle production. JIS standards and METI carbon neutrality roadmaps accelerate domestic driveline certification. Toyota City and Hiroshima anchor captive motor-inverter capabilities among vertically integrated OEMs.
Driveline Systems for Electric Vehicle Market Vendor Landscape
Global majors compete with regional champions across integrated e-axle platform development, with European and North American suppliers holding power electronics integration advantages against Chinese cost-optimized motor producers. The vendor base tiered between full-system integrators, component specialists, and captive OEM operations. Three archetypes dominate: gearbox-dominant incumbents extending into e-drive modules, power electronics specialists capturing inverter margin pools, and magnet-motor integrators leveraging rare earth supply proximity. M&A activity concentrates on silicon carbide talent acquisition and rare earth recovery partnerships.
Within the full-system integrator tier, BorgWarner Inc. and ZF Friedrichshafen AG exemplify gearbox-dominant incumbents retooling for e-axle consolidation. Schaeffler AG occupies a position among torque-vectoring differential specialists targeting premium architectures. These three German-origin entities anchor European supply capacity while extending certification-qualified production into North American and Asian markets.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| GKN Automotive |
| ZF Friedrichshafen AG |
| Schaeffler AG |
| Continental AG |
| Robert Bosch GmbH |
| Dana Incorporated |
| Aisin Corporation |
| Magna International Inc. |
| Others |
Supply Flow & Price Mechanics
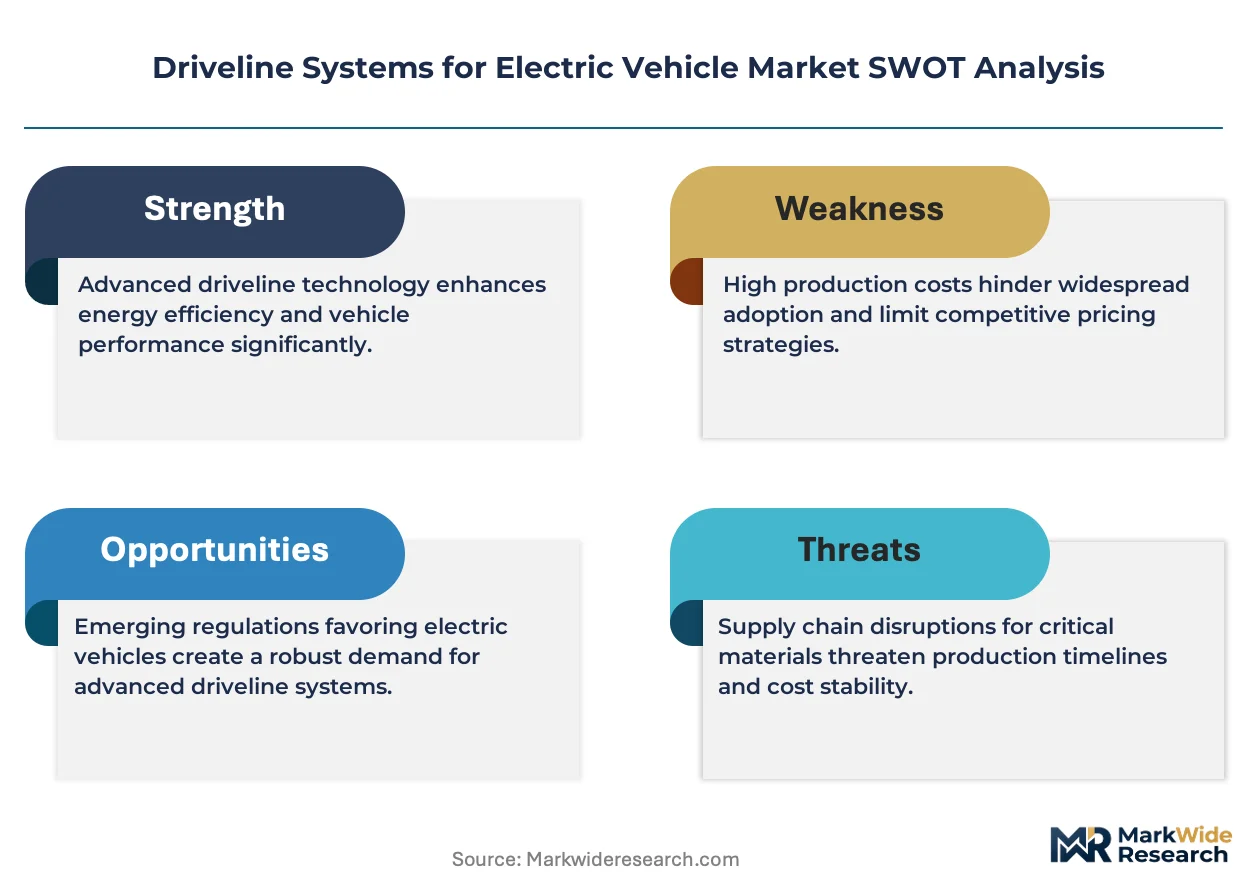
Silicon carbide inverter integration versus silicon IGBT legacy architectures bifurcates the e-axle market into premium high-voltage modules and cost-optimized commodity units, with this performance gap manifesting in warranty bundling structures and supply chain regionalization strategies that concentrate high-margin production in Germany and South Korea while pushing commodity motor assembly toward China's Yangtze River Delta.
Pricing Analysis
Warranty bundling separates integrated e-axle platforms from discrete component sales, with full-system suppliers capturing premium positioning through unified motor-inverter-gearbox coverage while modular vendors face price compression on unbundled subsystems. Price differentiation rests on ISO 26262 ASIL-D certification tier and silicon carbide semiconductor grade, with fleet procurement departments driving hardest bargains on standardized passenger car configurations. Pricing pressure stems from copper winding cost volatility tracking London Metal Exchange movements, eroding margins on high-power motor-inverter combinations. Ride-hailing fleet operators exhibit highest price sensitivity due to volume procurement scale, while premium passenger car OEMs prioritize power density over unit cost.
Supply Chain Analysis
Regional distribution centers in Shanghai, Stuttgart, and Detroit anchor hub-and-spoke fulfillment patterns for e-axle modules, with inventory positioning tied to OEM just-in-sequence assembly requirements. Manufacturing concentrates in China, Germany, and the United States, with neodymium magnet processing anchored in China's Inner Mongolia and Jiangxi provinces and silicon carbide wafer fabrication centered in Germany, Japan, and the United States. Raw material dependencies include rare earth oxides, high-purity copper cathode, and semiconductor-grade silicon carbide substrates. Single-source vulnerability in neodymium supply exposes motor manufacturers to export quota volatility. Distribution runs through Tier-1 supplier direct-to-OEM channels with limited aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restrictions and ECHA end-of-life accountability mandates erect compliance moats that favor incumbent suppliers with established rare earth recovery partnerships and reformulated lubricant qualifications, raising capital barriers for non-compliant entrants.
For Market Incumbents: Lock in rare earth supply through offtake agreements with Jiangxi and Inner Mongolia processors before export quota tightening accelerates. Capture silicon carbide inverter talent pools in Germany and South Korea through targeted hiring away from renewable energy competitors. Defend against Chinese cost-optimized motor producers by deepening ASIL-D certification coverage across full e-axle platforms. For New Entrants and Emerging Players: Launch via bolt-on retrofit kits targeting North American classic vehicle electrification specialists where clean-sheet platform economics fail. Penetrate the medium-duty commercial truck white space underserved by torque-dense 300 kW continuous output modules. Establish technical service partnerships with Yangtze River Delta fleet operators demanding same-day response commitments. For Investors and Strategic Acquirers: Re-rating potential sits with power electronics specialists possessing silicon carbide MOSFET design capabilities given 800V architecture migration across premium passenger car platforms. Long-term viability favors full-system integrators over component specialists as OEM procurement consolidates around unified e-axle sourcing. Watch for EPA tailpipe mandate acceleration as inflection signal for North American capacity expansion decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Supply Agreement | Secures magnet raw material access ahead of MIIT dual carbon localization mandates. |
| Silicon Carbide Talent Acquisition | Captures scarce inverter engineering capacity from renewable energy sector competitors. |
| ASIL-D Certification Investment | Unlocks premium passenger car supply contracts requiring ISO 26262 functional safety compliance. |
| Integrated E-Axle Platform Launch | Consolidates motor, inverter, and gearbox into sealed units displacing modular procurement. |
| Yangtze River Delta Manufacturing Footprint | Positions production adjacent to CATL and BYD cell facilities for logistics optimization. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and rare earth processing specialists. Secondary sources encompassed MIIT certification databases, EPA tailpipe compliance filings, ECHA REACH substance registrations, and vehicle production statistics from IHS Markit. Bottom-up segment sizing triangulated against top-down OEM electrification roadmap aggregation.
Data-stream reconciliation across component shipment volumes, OEM platform launch timelines, and regulatory compliance deadlines informed the analytical framework over the projection horizon. Segmentation dimensions modeled included vehicle class, propulsion architecture, power rating tier, installation method, and regional production cluster. CAGRs derived from fitted growth curves applied to disclosed capacity expansion announcements and fleet procurement contract values.
Neodymium export quota volatility, silicon carbide wafer supply constraints, and REACH lubricant reformulation delays are the dominant revision risks to forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
India Automotive Steering System Market
Vehicle Components
Idler Arm Market
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
RV Battery Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Headlight Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Engine Air Filter Market
Vehicle Components
Marine Wheel Bearings Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Electric Wheelbarrow Market
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Forklift Seats Market
Vehicle Components
Charge Air Coolers Market