
 Rear Spoiler Market | 2026-2036
Rear Spoiler Market Size, Share, and Industry Trends Forecast 2026-2036
Rear Spoiler Market Analysis
Multi-source procurement is restructuring supplier relationships across the rear spoiler supply base. Magna International Inc. leverages its integrated manufacturing footprint to serve multiple OEM platforms simultaneously. Plastic Omnium anchors European supply through its thermoplastic composite capabilities. SMP Automotive specializes in painted surface systems that merge spoiler functions with bumper and fascia integration.
A rear spoiler is an aerodynamic device mounted to the rear decklid or hatch of a vehicle, typically manufactured through injection molding of ABS or polycarbonate blends, compression molding of carbon fiber prepregs, or thermoforming of glass fiber reinforced polymers, designed to reduce lift coefficient and improve high-speed stability. Carbon fiber spoilers command premium positioning due to their stiffness-to-weight ratio and motorsport heritage, while plastic spoilers dominate volume production for mass-market passenger cars and SUVs. OEM installation channels capture the majority of value as automakers integrate spoilers into platform design cycles rather than treating them as accessories.
EPA fuel-economy standards in the United States, EU CO2 fleet emission targets under the Green Deal framework, and China's MIIT vehicle energy consumption regulations all shape spoiler adoption by rewarding aerodynamic drag reduction. NHTSA safety standards and ECE R26 technical prescriptions govern mounting integrity and pedestrian impact performance. Stakeholders must monitor how evolving material certification requirements and platform electrification timelines reshape specification roadmaps for active versus passive aerodynamic systems.
Market Dynamics
Platform electrification timelines are compressing spoiler development cycles as automakers redesign rear-end architectures to accommodate battery packs and thermal management systems, forcing aerodynamic component suppliers to synchronize with shortened vehicle platform refresh rates.
Growth Catalysts
- EPA fuel-economy standards:United States fleet efficiency mandates reward drag coefficient improvements, embedding spoilers into OEM platform engineering rather than accessory catalogs.
- Carbon fiber prepreg advances:Automated fiber placement and out-of-autoclave curing reduce cycle times for high-performance variants, opening motorsport-derived designs to broader vehicle segments.
- China's MIIT energy consumption regulations:Domestic automakers accelerate aerodynamic package adoption to meet NEV credit requirements and corporate average fuel consumption targets.
Market Restraints
- Acrylonitrile-butadiene-styrene resin volatility:Petrochemical feedstock price swings compress margin stability for injection-molded volume spoilers serving mass-market passenger cars.
- Carbon fiber precursor concentration:Polyacrylonitrile supply chains cluster among Japanese and US chemical producers, creating geographic single-source exposure for premium composite spoilers.
- ECE R26 pedestrian impact protocols:Mounting hardware and edge radius requirements add engineering validation burden, extending homologation timelines for European-market introductions.
Strategic Opportunities
- Active aerodynamics convergence:Integration of deployable spoiler actuators with vehicle dynamics controllers creates tiered downforce-on-demand systems for electric performance vehicles.
- India's PLI scheme for auto components:Localization incentives attract spoiler tooling investments to serve domestic SUV demand and export platforms for right-hand-drive markets.
- Direct-to-consumer digital channels:Specialty composite manufacturers bypass traditional tier-1 distribution to serve enthusiast vehicle modification markets through configuration platforms.
Industry Challenges
- Multi-material bonding certification:Dissimilar substrate adhesion between carbon fiber skins and thermoplastic structural cores requires validated process windows that strain quality assurance bandwidth.
- Paint-shop integration sequencing:Spoiler attachment timing relative to body-in-white e-coat and clearcoat operations creates surface finish matching complexity across OEM assembly lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rear Spoiler Market |
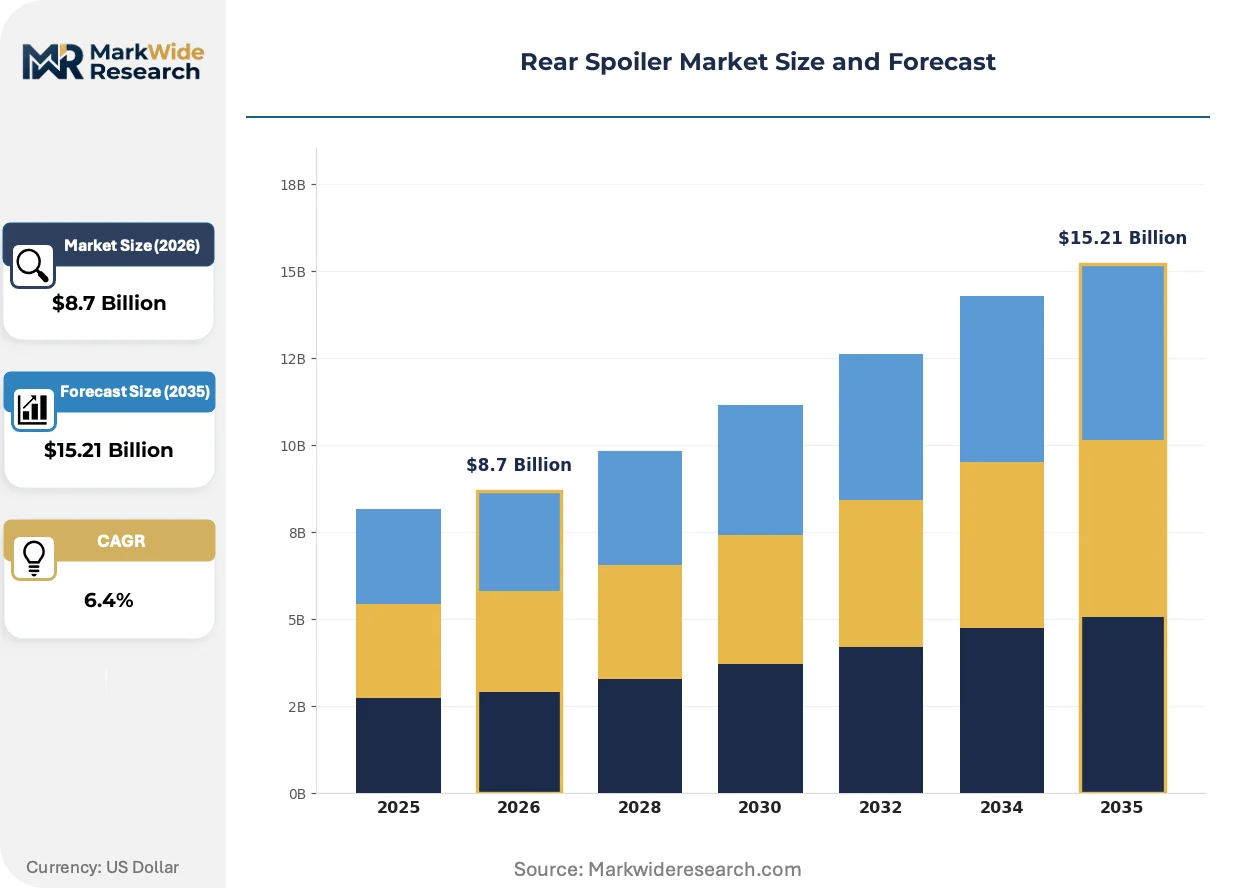
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy Spoilers, Plastic Spoilers, Carbon Fiber Spoilers, Glass Fiber Spoilers Installation Type: OEM Installation, Aftermarket Installation, Drill-Free Installation, Fixed Installation Vehicle Type: Passenger Cars, SUVs, Trucks, Sports Cars End User: Individual Buyers, Automotive Manufacturers, Customization Shops, Racing Teams |
| Companies Covered | Polytec Group, Albar Industries Inc., Magna International Inc., Aisin Corporation, DAR Spoilers, Plastic Omnium, SRG Global, REHAU Automotive, SMP Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rear Spoiler Market Emerging Trajectories
Rear spoiler engineering is bifurcating toward intelligent adaptive systems and ultra-lightweight passive structures, with material science and embedded electronics converging to redefine aerodynamic value capture beyond static form factors.
Active spoiler actuation is electrifying vehicle stability control architectures. Electromechanical deployment mechanisms with integrated wind sensors and CAN bus connectivity enable real-time angle adjustment based on velocity and yaw rate. Premium electric vehicle platforms from German and US automakers are adopting these systems, collapsing the historical separation between chassis dynamics and body exterior engineering functions.
EU Green Deal CO2 fleet targets are tightening embodied carbon accounting for automotive components. Life-cycle assessment requirements now extend to spoiler manufacturing, pressuring suppliers to document recycled content ratios and renewable energy shares in carbon fiber precursor production. European OEMs are responding with supplier scorecards that weight material provenance alongside unit cost in sourcing decisions.
Enthusiast procurement patterns are fragmenting across digital marketplaces and track-day specialist channels. Traditional tier-1 supply agreements no longer capture the full addressable market as composite fabricators sell finished spoilers directly through configuration tools with vehicle-specific fitment databases. This disintermediation is most pronounced in the United States and Germany, where aftermarket penetration rates for performance variants exceed those in regulated markets with stricter modification compliance requirements.
Rear Spoiler Market Segmentation
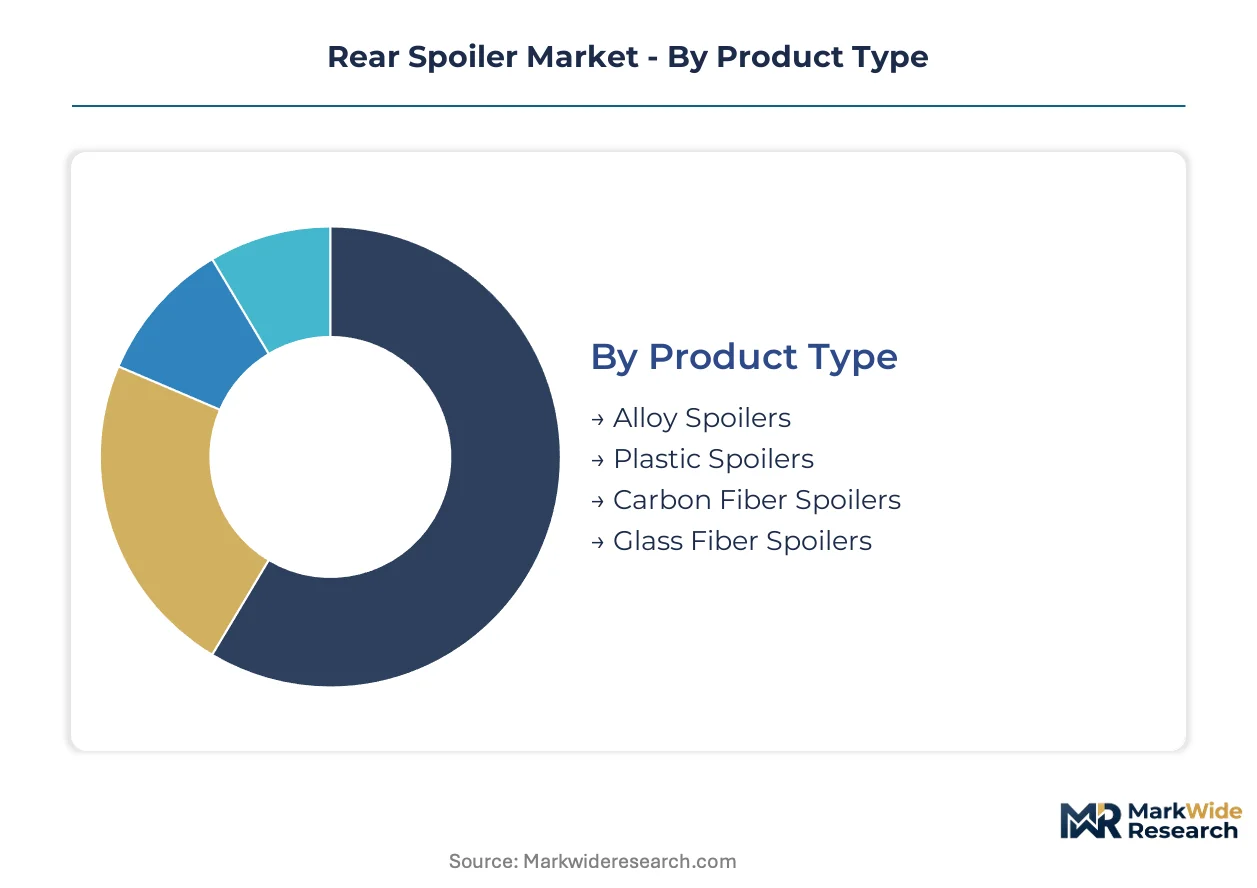
Spoiler procurement splits sharply between engineered-to-spec platform integration and catalog-standard replacement parts. Material selection, mounting protocol, and buyer sophistication create four distinct category hierarchies that suppliers must navigate simultaneously.
Product Type:
Customization intensity runs inverse to production volume across material categories, with hand-laid composites commanding premium positioning against injection-molded commodity alternatives.
- Carbon Fiber Spoilers:Manufactured from polyacrylonitrile precursor through automated fiber placement or prepreg layup, achieving stiffness-to-weight ratios exceeding 150 GPa per kg/m³. Demand concentrates in German and US sports car platforms where EPA fleet efficiency credits reward mass reduction alongside drag coefficient gains.
- Plastic Spoilers:Injection-molded ABS or polycarbonate blends dominate mass-market passenger car and SUV volumes across China's MIIT-regulated domestic OEMs. Acrylonitrile-butadiene-styrene resin price volatility compresses margin stability for tier-1 suppliers serving high-volume platforms.
- Alloy Spoilers:Cast or extruded aluminum architectures persist in commercial truck applications requiring impact resistance beyond polymer capabilities.
- Glass Fiber Spoilers:Thermoformed glass fiber reinforced polymers occupy mid-market positioning with balanced cost-performance profiles for mainstream SUV segments.
Leading the category by volume: Plastic Spoilers. Expanding most quickly: Carbon Fiber Spoilers.
Installation Type:
Channel economics separate captive OEM supply from fragmented aftermarket distribution, with mounting hardware complexity determining warranty exposure and liability allocation.
- OEM Installation:Factory-integrated spoilers synchronize with body-in-white e-coat sequences, requiring validated adhesion protocols between dissimilar substrates. German and Japanese automakers embed these components into platform design cycles rather than accessory catalogs, capturing the majority of segment value.
- Aftermarket Installation:Drill-free adhesive mounting systems bypass body panel modification, serving enthusiast segments in the United States and Germany where digital configuration platforms enable direct-to-consumer procurement. ECE R26 pedestrian impact protocols and NHTSA mounting integrity standards create compliance fragmentation across regulated markets.
- Drill-Free Installation:Pressure-sensitive adhesive and mechanical clip systems reduce installation skill barriers for individual buyers.
- Fixed Installation:Permanent bolt-on architectures dominate racing team procurement where aerodynamic load validation exceeds factory specifications.
OEM Installation captures the dominant revenue share. Aftermarket Installation is gaining share fastest through enthusiast digital channels.
Vehicle Type:
Platform electrification timelines are compressing rear-end architecture redesigns, forcing spoiler specification alignment with battery pack packaging and thermal management routing.
- Passenger Cars:Sedan and hatchback segments across China, Germany, and the United States drive baseline volume, with MIIT energy consumption regulations and EPA fleet standards embedding spoilers into aerodynamic package engineering.
- SUVs:Higher ride heights and larger frontal areas amplify drag coefficient sensitivity, making roofline-integrated spoilers critical for CO2 compliance under EU Green Deal targets.
- Sports Cars:Active electromechanical deployment systems with CAN bus integration are concentrating in German and US premium electric vehicle platforms.
- Trucks:Commercial and heavy-duty applications prioritize durability over drag reduction, with alloy architectures preferred for impact resistance.
Passenger Cars lead absolute unit demand. Sports Cars show the steepest specification value escalation per vehicle.
End User:
Procurement sophistication bifurcates between specification-engineered platform supply and enthusiast-driven aesthetic modification, with racing teams representing the most demanding performance validation segment.
- Automotive Manufacturers:OEM platform engineering teams in Germany, Japan, and the United States drive specification roadmaps, integrating spoiler design into 3-5 year vehicle refresh cycles with life-cycle assessment requirements under EU Green Deal embodied carbon accounting.
- Customization Shops:Specialist installers in the United States and Germany serve modification markets with vehicle-specific fitment databases, bypassing traditional tier-1 distribution through direct composite fabricator relationships.
- Individual Buyers:Digital marketplace procurement concentrates in markets with permissive modification compliance frameworks.
- Racing Teams:Motorsport applications demand validated downforce-to-drag ratios with NACA duct integration and adjustable attack angles.
Automotive Manufacturers dominate procurement value. Customization Shops are climbing fastest through disintermediated digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and the United States where OEM platform engineering integrates spoilers into aerodynamic compliance strategies. Each geography shapes specification roadmaps through distinct regulatory frameworks and supplier clustering patterns.
United States
EPA fuel-economy standards embed spoilers into OEM platform engineering cycles rather than accessory catalogs. NHTSA mounting integrity standards govern pedestrian impact performance and hardware validation requirements. Detroit-area engineering centers coordinate spoiler specification with powertrain thermal management for electric vehicle platforms.
Germany
EU Green Deal CO2 fleet targets accelerate adoption of active electromechanical spoiler systems in premium electric vehicle architectures. KBA homologation protocols enforce ECE R26 technical prescriptions for mounting hardware and edge radius compliance. Stuttgart and Munich engineering clusters synchronize spoiler development with shortened platform refresh cycles for battery-electric architectures.
China
MIIT vehicle energy consumption regulations drive domestic OEM adoption of roofline-integrated spoilers for NEV credit compliance. Dual carbon goals pressure suppliers to document recycled content ratios in composite precursor production. Yangtze River Delta manufacturing bases concentrate thermoplastic injection molding capacity for mass-market passenger car volumes.
Japan
METI energy efficiency standards shape spoiler specification for hybrid and battery-electric platform architectures. JIS quality certification requirements govern material traceability in carbon fiber prepreg supply chains. Nagoya-area automotive suppliers coordinate spoiler integration with lean manufacturing sequences for export platforms.
India
PLI scheme for auto components attracts spoiler tooling investments to serve domestic SUV demand and right-hand-drive export markets. BIS automotive component standards govern material certification and mounting hardware validation. Tamil Nadu and Maharashtra manufacturing corridors concentrate thermoplastic composite capacity for emerging OEM supply agreements.
Rear Spoiler Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers synchronize tooling investments with electrified platform timelines. The vendor base organizes around three tiers: integrated multinational platforms serving multiple OEMs simultaneously, regional specialists anchoring single-market supply relationships, and composite fabricators disintermediating tier-1 distribution through direct digital channels. Strategic archetypes include full-service exterior systems integrators, material-specific composite specialists, and paint-shop process experts. M&A activity and geographic expansion represent the dominant competitive moves as firms position for platform consolidation waves.
Among integrated multinational platforms, Magna International Inc., Plastic Omnium, and SMP Automotive occupy positions spanning multiple OEM relationships and material competencies. Magna exemplifies the full-service archetype through integrated manufacturing footprints synchronized with global platform engineering. Plastic Omnium represents European-focused composite capabilities with thermoplastic specialization. SMP Automotive anchors painted surface system integration, merging spoiler functions with bumper and fascia engineering. These three firms illustrate how scale and process integration create defensive positioning against disintermediation pressures from direct-to-consumer composite channels.
| Leading Market Players |
|---|
| Polytec Group |
| Albar Industries Inc. |
| Magna International Inc. |
| Aisin Corporation |
| DAR Spoilers |
| Plastic Omnium |
| SRG Global |
| REHAU Automotive |
| SMP Automotive |
| Others |
Supply Flow & Price Mechanics
OEM platform engineering teams in Germany, Japan, and the United States are consolidating supplier relationships around integrated exterior systems capabilities, forcing tier-1 spoiler manufacturers to absorb paint-shop integration costs and homologation validation burdens that compress margin structures across commodity plastic segments.
Pricing Analysis
Volume-mass plastic spoilers trade on razor-thin unit economics while carbon fiber variants capture substantial margin premiums. Three-tier pricing structure across motorsport-grade composites, mid-market glass fiber, and injection-molded ABS separates specification-engineered OEM supply from catalog aftermarket parts. Cost compression in thermoplastic segments is intensifying because acrylonitrile-butadiene-styrene resin volatility transfers feedstock risk to tier-1 suppliers. Mass-market passenger car procurement teams exhibit highest price sensitivity; racing teams and premium EV platform engineers demonstrate lowest.
Supply Chain Analysis
ECE R26 pedestrian impact certification and KBA homologation protocols gate European market entry, filtering supplier bases to firms with validated adhesion process windows and paint-shop sequencing expertise. Manufacturing concentrates in Germany, China, and the United States, with Yangtze River Delta injection molding clusters feeding domestic OEM volumes and Stuttgart-area composites specialists serving premium electromechanical systems. Polyacrylonitrile precursor for carbon fiber draws from Japanese and US chemical producers, creating geographic single-source exposure. Tariff exposure on petrochemical feedstocks threatens margin stability. Distribution runs through captive OEM supply agreements with tier-1 integrators, though direct-to-consumer digital channels are fragmenting enthusiast procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform electrification timelines and compressed development cycles are consolidating competitive positions around integrated manufacturing footprints, eliminating standalone spoiler specialists lacking paint-shop process expertise or active aerodynamics actuator capabilities.
For Market Incumbents: Cement defensive positioning through backward integration into carbon fiber precursor supply and captive thermoplastic compounding capacity. Magna International and Plastic Omnium exemplify scale advantages that neutralize disintermediation threats from direct-to-consumer composite channels. Prioritize certification investment in ECE R26 and NHTSA mounting integrity protocols to extend OEM platform lock-in. For New Entrants and Emerging Players: Capture white-space in India's PLI scheme corridors and right-hand-drive export platforms where tooling investments face lower competitive density. Specialty active aerodynamics actuator integration for electric performance vehicles offers the most penetrable segment, with German and US premium OEMs seeking tiered downforce-on-demand systems. Pursue direct digital configuration platforms with vehicle-specific fitment databases to bypass traditional tier-1 distribution. For Investors and Strategic Acquirers: The window for entry favors composite specialists with validated multi-material bonding processes and paint-shop integration capabilities over pure-play spoiler manufacturers. Long-term viability hinges on positioning for active aerodynamics convergence and platform standardization waves. Watch for inflection signals in OEM supplier scorecard weighting toward life-cycle assessment documentation and recycled content ratios under EU Green Deal embodied carbon accounting.| Strategic Initiative | Industry Significance |
|---|---|
| Active Aerodynamics Integration | Electromechanical deployment systems with CAN bus connectivity capture premium EV platform specifications from German and US automakers. |
| Backward Integration into Precursor Supply | In-house polyacrylonitrile sourcing mitigates geographic concentration risk among Japanese and US chemical producers. |
| Paint-Shop Process Certification | E-coat sequencing expertise and validated adhesion protocols create OEM platform lock-in against aftermarket disintermediation. |
| PLI Scheme Localization | Tamil Nadu and Maharashtra tooling investments serve India's domestic SUV demand and right-hand-drive export markets. |
| Life-Cycle Assessment Documentation | Recycled content ratio verification and renewable energy shares in carbon fiber production satisfy EU Green Deal supplier scorecards. |
Methodological Framework
Document review covered vehicle production databases, IHS Markit registration data, SEC filings from tier-1 suppliers, and MIIT energy consumption regulation disclosures, complemented by interviews with OEM platform engineers, tier-1 procurement leads, aftermarket distributors, and composite manufacturing specialists. Secondary validation drew from customs and trade flow records, automotive component customs data, and regulatory filing repositories. Bottom-up unit economics modeling triangulated against top-down market sizing from production volume and content-per-vehicle assumptions.
Cross-referencing historical spoiler adoption patterns against expert panel input on electrification timeline acceleration shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material category, installation channel, vehicle architecture, and regional regulatory cluster. CAGRs were derived from slope analysis of technology diffusion curves and platform refresh cycle compression. Forecast inputs incorporated battery-electric vehicle penetration assumptions and active aerodynamics adoption rates in premium segments.
The model holds under stable petrochemical feedstock pricing and sustained EPA fleet efficiency mandate enforcement; deviation in acrylonitrile-butadiene-styrene resin volatility or suspension of EU CO2 fleet targets would shift specification roadmaps and value capture trajectories. Forecasts reflect documented assumptions on platform electrification timelines and material substitution elasticities. Stakeholders should weight assumptions against their own operating context and supplier qualification bandwidth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Passenger Car Accessories Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Motorcycle Top Box Market
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Japan Ceramic Ball Bearings Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Vehicle Transfer Case Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Brake Friction Materials Market
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market