
 United Kingdom Vacuum Truck Market | 2026-2036
United Kingdom Vacuum Truck Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Vacuum Truck Market Insights
Aluminium is expanding its share in vacuum tank fabrication, displacing traditional steel to reduce vehicle weight and improve fuel efficiency across UK municipal fleets. VAC UK Ltd leverages its domestic manufacturing footprint to anchor supply contracts with Thames Water and regional utilities. KOKS Group B.V. competes through specialized suction excavation configurations tailored to urban utility works. Federal Signal Corporation sustains its position via aftermarket parts availability and service network density across the British Isles.
A vacuum truck integrates a high-capacity vacuum pump, debris storage tank, and hydraulic or pneumatic discharge system mounted on a commercial chassis, engineered to extract liquids, slurries, and dry solids from inaccessible locations. Tank capacities typically range from 1,000 to 15,000 litres with pressure ratings up to 28 inches of mercury for deep suction applications. Truck mounted configurations dominate municipal procurement due to integrated mobility and operator efficiency on congested UK roadways. Combination vacuum units represent the fastest-growing product category as contractors seek dual wet-dry capability to consolidate fleet expenditure. Environmental remediation applications command premium pricing driven by hazardous material certification requirements and operator training mandates.
The Environment Agency enforces waste carriage regulations under the Environmental Permitting Regulations, compelling fleet operators toward sealed tank designs and real-time tracking systems. HSE workplace exposure limits for silica and biological agents shape suction excavation protocols and protective equipment specifications. DVSA vehicle approval standards govern tank integrity testing intervals and brake performance for heavy vacuum configurations. Stakeholders must monitor impending Euro 7 emissions standards and their impact on chassis availability and total cost of ownership calculations.
Market Dynamics
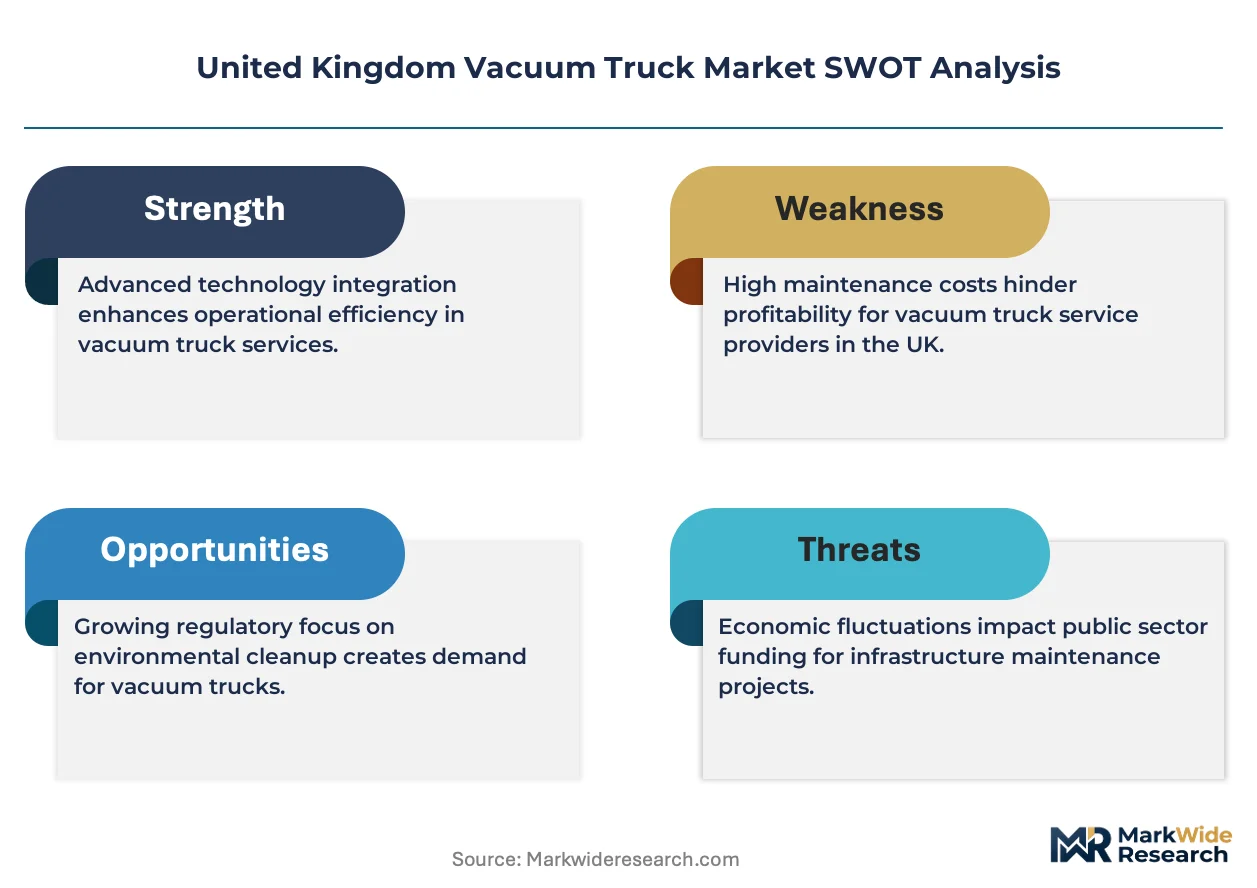
The Environment Agency's tightening sludge disposal regulations under the Environmental Permitting Regulations are forcing fleet operators toward sealed tank designs and real-time tracking systems, compressing replacement cycles across England and Scotland.
Growth Catalysts
- Municipal Sewer Maintenance Contracts:Thames Water and regional utilities in Greater London and the West Midlands are expanding fleet procurement to meet aging infrastructure demands.
- Euro 7 Emissions Standards:Anticipated chassis regulations are accelerating pre-compliance equipment upgrades before supply constraints materialise.
- Aluminium Tank Fabrication:Lightweight material adoption is reducing vehicle weight and improving fuel efficiency across UK municipal fleets.
Market Restraints
- Chassis Supply Concentration:Heavy commercial vehicle manufacturing concentrates in continental Europe, exposing UK operators to Brexit-related customs friction and extended lead times.
- Hydraulic System Component Volatility:Specialist pump and valve imports face sterling-euro exchange rate sensitivity and energy-intensive production cost pressures.
- DVSA Approval Timelines:Vehicle approval standards for tank integrity testing create certification bottlenecks that delay fleet deployment.
Strategic Opportunities
- Scottish Highlands Infrastructure:Remote water and wastewater networks in northern Scotland remain underpenetrated by combination vacuum units with wet-dry capability.
- HSE Silica Exposure Protocols:Tightening workplace exposure limits for suction excavation are mandating upgraded protective equipment specifications and certified operator training programmes.
- Telematics-Conveyance Integration:Real-time sludge tracking systems are converging with route optimisation software to unlock outcome-based municipal contracting models.
Industry Challenges
- Hazardous Material Certification Gaps:Environmental remediation applications require operator training mandates that outpace available accredited programmes.
- Legacy Fleet Integration Complexity:Municipal procurement cycles must reconcile new sealed tank designs with existing maintenance depot configurations and spare parts inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Vacuum Truck Market |
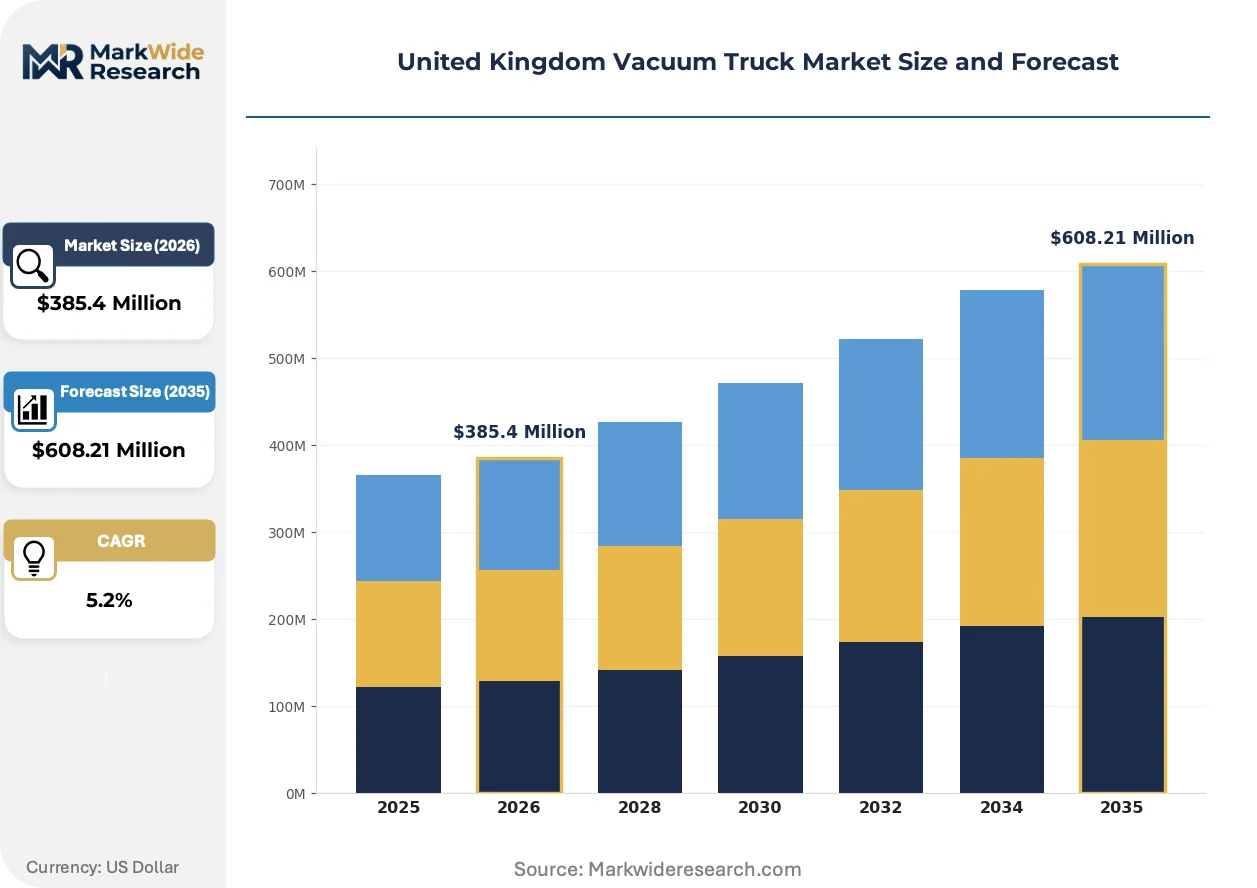
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combination Vacuum, Industrial Vacuum, Portable Vacuum, Trailer Mounted, Truck Mounted Technology: Hydraulic Drive, Pneumatic System, Electric Motor, Diesel Engine, Vacuum Pump Application: Waste Management, Sewer Cleaning, Oil Spill Recovery, Excavation, Environmental Remediation End User: Municipal Corporations, Construction Firms, Oil & Gas Companies, Environmental Agencies |
| Companies Covered | Vac-Con, Inc., VAC UK Ltd, Federal Signal Corporation, Rivard Industries, Suction Excavation UK Ltd, KOKS Group B.V., Keith Huber Corporation, AFI Group, Cappellotto S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Vacuum Truck Market Trends and Innovations
Digitalisation of waste tracking and lightweight material substitution are compressing total cost of ownership calculations while expanding permissible operational envelopes for vacuum truck deployment across constrained UK urban corridors.
Combination vacuum units equipped with dual wet-dry capability are consolidating contractor fleet expenditure by eliminating redundant single-purpose vehicles. Municipal procurement officers in Greater London and the West Midlands are specifying these configurations in new tenders. The technology is consolidating previously separate wet sludge and dry solids extraction contracts into unified service agreements.
The Environment Agency's Environmental Permitting Regulations are mandating sealed tank designs with real-time tracking for all hazardous waste carriage. Fleet operators must retrofit existing vehicles or accelerate replacement timelines. Suction excavation contractors serving urban utility works face the steepest compliance costs and are passing certification requirements upstream to equipment lessors.
Service unbundling is fragmenting traditional full-maintenance lease structures. Large municipal utilities now separate vacuum truck acquisition from aftermarket parts and field service contracts. Channel disintermediation is most advanced in England, where Thames Water and regional utilities negotiate direct with domestic manufacturers for chassis-tank integration while sourcing maintenance through independent service networks.
United Kingdom Vacuum Truck Market Segmentation
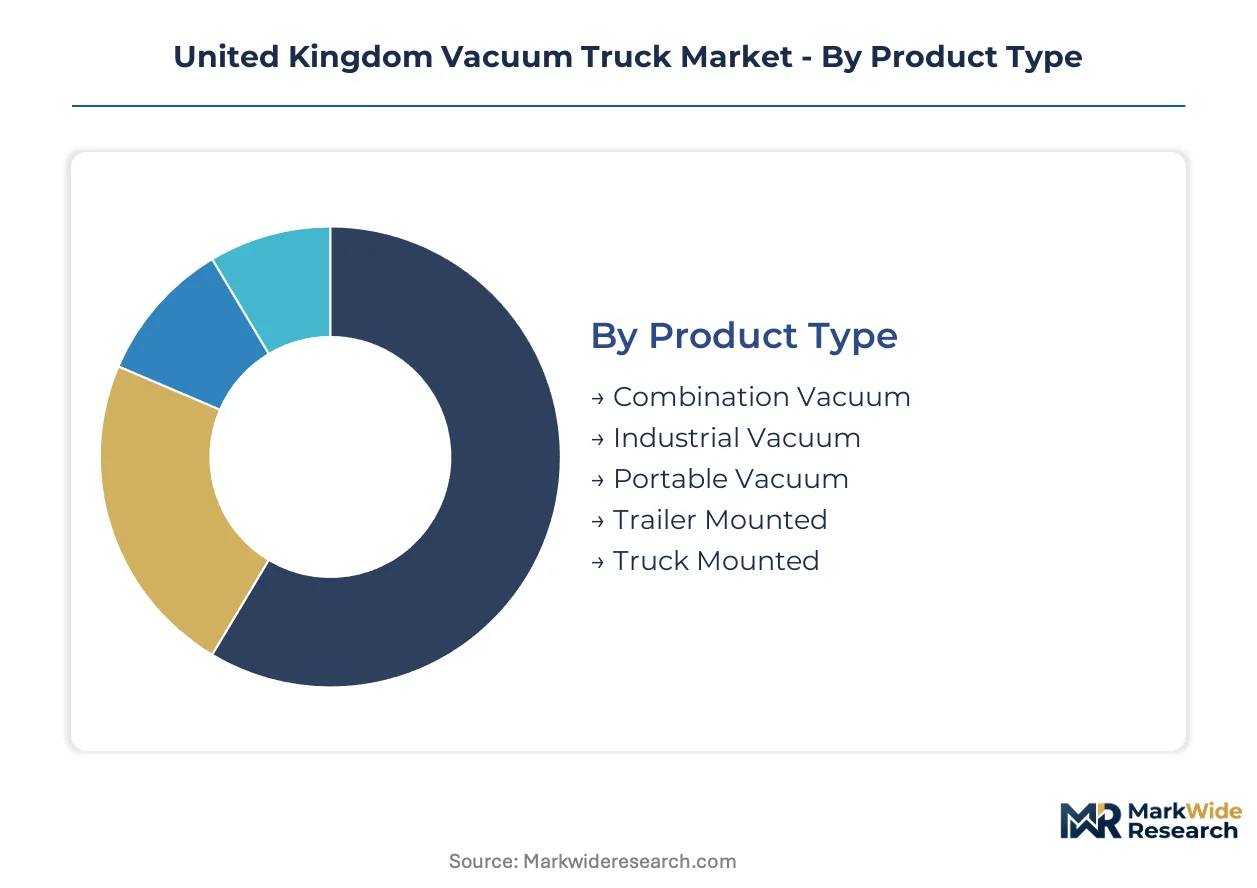
Segmentation in the UK vacuum truck market reveals how procurement priorities diverge between municipal utilities seeking operational consolidation and contractors demanding specialized configurations. Understanding these divides exposes where specification premiums concentrate and where standardization pressures dominate.
Product Type:
Configuration choices pivot on mobility requirements versus tank capacity trade-offs, with chassis integration decisions locking operators into decade-long replacement cycles.
- Combination Vacuum:Dual wet-dry capability eliminates redundant single-purpose vehicles from contractor fleets. Thames Water and West Midlands utilities specify these units in consolidated tenders to merge sludge and solids extraction contracts.
- Truck Mounted:Integrated chassis-tank designs dominate municipal procurement across Greater London due to operator efficiency on congested urban corridors. DVSA brake performance standards and tank integrity testing intervals govern deployment timelines.
- Industrial Vacuum:Stationary high-capacity systems serve manufacturing facilities with continuous process waste streams.
- Portable Vacuum:Compact units access confined spaces in heritage infrastructure across Edinburgh and Glasgow.
- Trailer Mounted:Detachable configurations allow chassis redeployment during seasonal demand peaks in Scottish Highlands water networks.
Mature deployment sits with truck mounted units across England's municipal fleets. Newer deployment is concentrated in combination vacuum configurations as contractors seek fleet consolidation.
Technology:
Powertrain selections determine fuel efficiency compliance trajectories and maintenance depot compatibility, with Euro 7 anticipation accelerating pre-emptive procurement shifts.
- Hydraulic Drive:Proven suction performance for deep extraction applications up to 28 inches of mercury. Sterling-euro exchange rate volatility inflates specialist pump and valve replacement costs for UK operators.
- Diesel Engine:Chassis-integrated power units face impending Euro 7 emissions constraints that threaten continental European supply availability.
- Electric Motor:Zero-emission configurations are gaining traction in Greater London low-emission zones.
- Pneumatic System:Compressed air alternatives reduce hydraulic fluid contamination risks in sensitive environmental remediation sites.
- Vacuum Pump:Positive displacement and liquid ring variants compete on noise regulations and maintenance intervals.
Established fleets rely predominantly on hydraulic drive systems. Steepest expansion trajectory belongs to electric motor configurations as urban emission zones tighten.
Application:
Regulatory stringency varies sharply across use cases, with hazardous material certifications commanding specification premiums that reshape contractor bidding strategies.
- Sewer Cleaning:Aging infrastructure across England and Scotland drives replacement demand. Environment Agency sludge disposal regulations under Environmental Permitting Regulations mandate sealed tank designs and real-time tracking retrofits.
- Environmental Remediation:Hazardous material carriage requires operator training mandates that outpace accredited programme availability. HSE silica and biological agent exposure limits shape protective equipment specifications.
- Waste Management:Municipal collection contracts standardize on combination units for route efficiency.
- Oil Spill Recovery:North Sea proximity supports specialized fleet investment among Aberdeen-based contractors.
- Excavation:Suction excavation for urban utility works faces HSE workplace exposure protocol upgrades.
Volume concentration remains in sewer cleaning across metropolitan utilities. Premium pricing expansion is concentrated in environmental remediation as certification requirements multiply.
End User:
Procurement authority structures determine whether acquisition prioritizes capital efficiency or operational outcome guarantees, fragmenting channel relationships across the value chain.
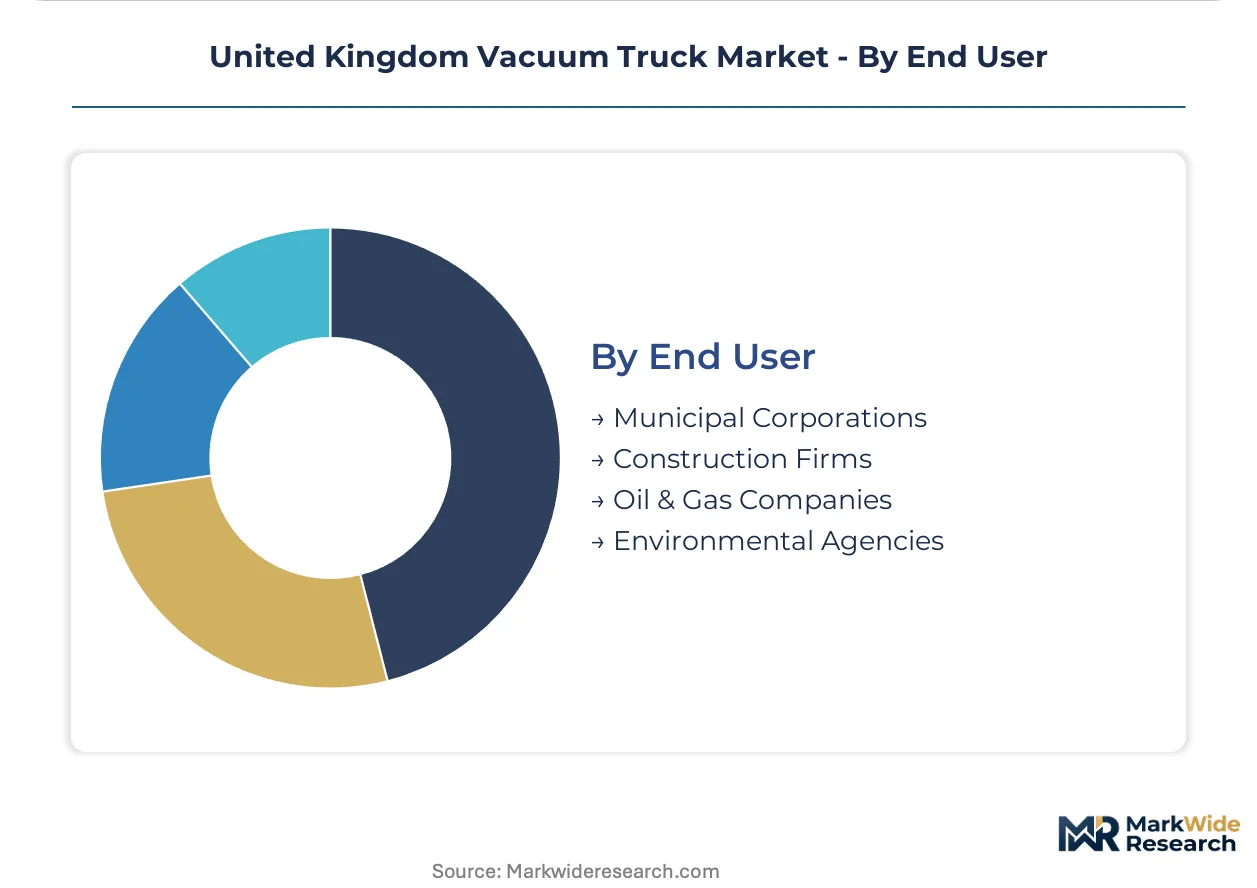
- Municipal Corporations:Thames Water and regional utilities are unbundling full-maintenance leases, separating chassis-tank acquisition from aftermarket service contracts. Direct manufacturer negotiation now dominates England procurement.
- Construction Firms:Project-based hiring preferences favour flexible lease terms over capital deployment, concentrating demand with equipment lessors who absorb certification compliance costs.
- Environmental Agencies:Environment Agency contracting mandates real-time sludge tracking integration with route optimisation software.
- Oil & Gas Companies:Aberdeen cluster operators maintain captive fleets for North Sea logistical requirements.
Contracting maturity sits with municipal corporations executing outcome-based service agreements. Emerging procurement sophistication is concentrated in construction firms demanding telematics-integrated lease structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Greater London and the West Midlands urban corridors, where aging sewer infrastructure and tightening Environment Agency regulations drive fleet procurement. Municipal utilities across England and Scotland dominate equipment deployment. Devolved regulatory frameworks in Scotland and Wales create distinct compliance timelines.
Greater London
Thames Water's capital maintenance programmes anchor fleet procurement for combination vacuum units with wet-dry capability. The Ultra Low Emission Zone expansion accelerates electric motor configuration adoption. Contractors cluster in the Thames Gateway corridor to service Crossrail legacy infrastructure and Tideway tunnel networks.
West Midlands
Severn Trent Water and regional utilities specify sealed tank designs with real-time tracking integration. DVSA vehicle approval bottlenecks delay deployment of heavy vacuum configurations. Birmingham's utility corridor hosts suction excavation specialists serving HS2 phase-one construction sites.
Scotland
Scottish Water's infrastructure investment programme drives demand in the Central Belt. Remote Highlands water networks remain underpenetrated by combination units despite wet-dry operational advantages. HSE silica exposure protocols for suction excavation impose stricter protective equipment mandates than England.
Wales
Natural Resources Wales enforces sludge disposal regulations parallel to Environment Agency standards but with extended compliance deadlines. Dŵr Cymru Welsh Water procurement favours trailer-mounted configurations for seasonal demand peaks in rural networks. Cardiff and Swansea urban corridors concentrate contractor activity.
North England
United Utilities and Yorkshire Water maintenance contracts sustain truck-mounted vacuum deployment across Manchester and Leeds metropolitan areas. Legacy industrial sites in Teesside generate environmental remediation demand with hazardous material certification premiums. DVSA testing facilities in Yorkshire create regional certification advantages.
United Kingdom Vacuum Truck Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with domestic fabricators holding municipal procurement advantages and continental OEMs dominating chassis supply. The vendor base concentrates around three tiers: integrated chassis-tank specialists, component-focused subsystem suppliers, and regional service networks. Strategic moves centre on aluminium tank fabrication adoption and telematics integration for outcome-based contracting.
Among UK-based specialists, VAC UK Ltd anchors domestic manufacturing capacity for municipal supply contracts. Federal Signal Corporation exemplifies aftermarket-driven positioning through service network density. KOKS Group B.V. represents the continental European fabrication archetype with specialized suction excavation configurations.
| Leading Market Players |
|---|
| Vac-Con, Inc. |
| VAC UK Ltd |
| Federal Signal Corporation |
| Rivard Industries |
| Suction Excavation UK Ltd |
| KOKS Group B.V. |
| Keith Huber Corporation |
| AFI Group |
| Cappellotto S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Captive chassis-tank integration by domestic fabricators anchors supply positioning and pricing power across UK municipal procurement. Thames Water and Severn Trent Water negotiate direct with VAC UK Ltd for sealed aluminium tank configurations, compressing margin capture by intermediaries while elevating specification premiums for Environment Agency-compliant real-time tracking systems.
Pricing Analysis
Volume concentration in municipal sewer maintenance contracts splits from margin capture in environmental remediation applications. Three-tier pricing structure across premium hazardous-certified, standard municipal, and economy hire-fleet levels reflects operator training mandates and DVSA tank integrity testing intervals. Pricing pressure stems from sterling-euro exchange rate volatility inflating hydraulic pump and valve replacement costs. Municipal utilities exhibit lowest price sensitivity due to outcome-based contracting, while construction firms hiring on project terms drive hardest bargain negotiation.
Supply Chain Analysis
DVSA vehicle approval and Environment Agency waste carriage certification gate chassis-tank integration before market entry. Germany, Poland, and the Netherlands concentrate heavy commercial vehicle manufacturing, exposing UK operators to Brexit customs friction. The supply chain draws from aluminium sheet mills in Belgium, hydraulic component specialists in Italy, and vacuum pump fabricators in Germany. Single-source vulnerability clusters in continental European chassis supply. Distribution runs through direct manufacturer negotiation for municipal utilities and equipment lessor networks for construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance-capable domestic fabricators as Euro 7 emissions standards and Environment Agency tracking mandates force out undercapitalised regional service networks.
For Market Incumbents: Deploy telematics-conveyance integration to lock in outcome-based municipal contracts before unbundling accelerates. Secure DVSA approval capacity to exploit certification bottlenecks delaying competitor deployment. Absorb hazardous material operator training accreditation costs to capture environmental remediation premium pricing. For New Entrants and Emerging Players: Capture Scottish Highlands water network penetration with trailer-mounted combination units tailored to seasonal demand peaks. Target Dŵr Cymru Welsh Water procurement with extended compliance deadline arbitrage against England operators. Lead with suction excavation specialisation certified to HSE silica exposure protocols stricter than England mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to continental European chassis OEMs seeking UK aftermarket service density. Five-to-ten year viability favours fabricators with captive aluminium tank production and Environment Agency regulatory affairs capability. Watch Euro 7 chassis supply constraints as inflection indicator accelerating replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminium Tank Fabrication Scale-Up | Reduces vehicle weight for Thames Water fuel efficiency mandates across Greater London fleets. |
| Telematics-Tracking Integration | Unlocks Environment Agency-compliant real-time sludge conveyance for outcome-based contracting. |
| HSE Silica Certification Programme | Captures suction excavation premium in West Midlands HS2 construction corridor. |
| Scottish Highlands Distribution Partnership | Addresses underpenetrated remote water networks with seasonal trailer-mounted deployment. |
| Aftermarket Service Network Expansion | Responds to municipal lease unbundling separating acquisition from maintenance contracts. |
Research Methodology
Trade association filings, Environment Agency permit databases, and DVSA vehicle approval records formed the secondary backbone for market sizing validation. Primary interviews with municipal fleet procurement managers, suction excavation contractors, hydraulic component distributors, and aftermarket service heads triangulated against customs data on chassis and pump imports. Bottom-up unit economics for combination vacuum configurations were cross-checked with top-down municipal capital expenditure tracking across Thames Water, Severn Trent Water, and Scottish Water regulatory accounts.
Bottom-up modeling of chassis-tank integration costs and top-down utility fleet procurement disclosure triangulation anchored the analytical framework. Segmentation by product configuration, powertrain technology, application regulatory stringency, and end-user procurement authority shaped volume and value outputs across the projection horizon. CAGRs derived from equipment replacement cycle compression under Environmental Permitting Regulations and Euro 7 pre-compliance procurement acceleration. Forecast inputs incorporated aluminium price volatility and sterling-euro exchange rate sensitivity for hydraulic component sourcing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Euro 7 chassis supply disruption and Environment Agency tracking mandate enforcement timing. Forecasts reflect assumptions on municipal budget continuity and Brexit customs friction persistence. A model refresh is warranted upon material change in Environment Agency sludge disposal regulation implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Locomotive Drive Shaft Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
RV Battery Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Front Forks Market
Vehicle Components
Throttle Cable Market
Vehicle Components
Rolling Stock LED Lights Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Automotive Aftermarket Shock Absorbers Market
Vehicle Components
Passenger Car Sensors Market
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Europe Automotive Connectors Market
Vehicle Components
Electric Forklifts Market