
 Idler Arm Market | 2026-2036
Idler Arm Market Size, Share, and Industry Trends Forecast 2026-2036
Idler Arm Market Foresight
The EU Green Deal is rebalancing procurement criteria across European vehicle assemblers, compelling suppliers to certify lower-carbon forging processes for chassis components. ZF Friedrichshafen AG leverages its integrated foundry network to control melt-to-finish traceability for idler arm castings. MOOG sustains aftermarket dominance through proprietary powdered-metal bushing technology that extends service intervals. ACDelco anchors North American OEM supply through captive distribution into General Motors assembly plants.
An idler arm is a pivotal steering linkage component that translates rotational input from the steering gearbox into lateral pitman arm motion, typically manufactured through forged steel or ductile iron processes with specified hardness ratings between 35 and 45 HRC to withstand cyclic loads exceeding 50,000 duty cycles. Conventional idler arms retain the largest installed base across aging vehicle parc, though heavy-duty variants command premium positioning due to stricter load ratings in commercial applications. Steel material formulations still dominate volume production, while aluminum adoption concentrates in lightweight platforms where OEMs pursue chassis mass reduction targets.
NHTSA Federal Motor Vehicle Safety Standards govern steering system integrity testing in the United States, while REACH compliance in Europe restricts hexavalent chromium coatings historically applied to idler arm hardware. EPA foundry emissions rules are forcing domestic suppliers to convert cupola melting operations to electric induction systems. Stakeholders must monitor how OEM consolidation of steering architectures toward rack-and-pinion designs alters long-term idler arm attach rates in light-vehicle segments.
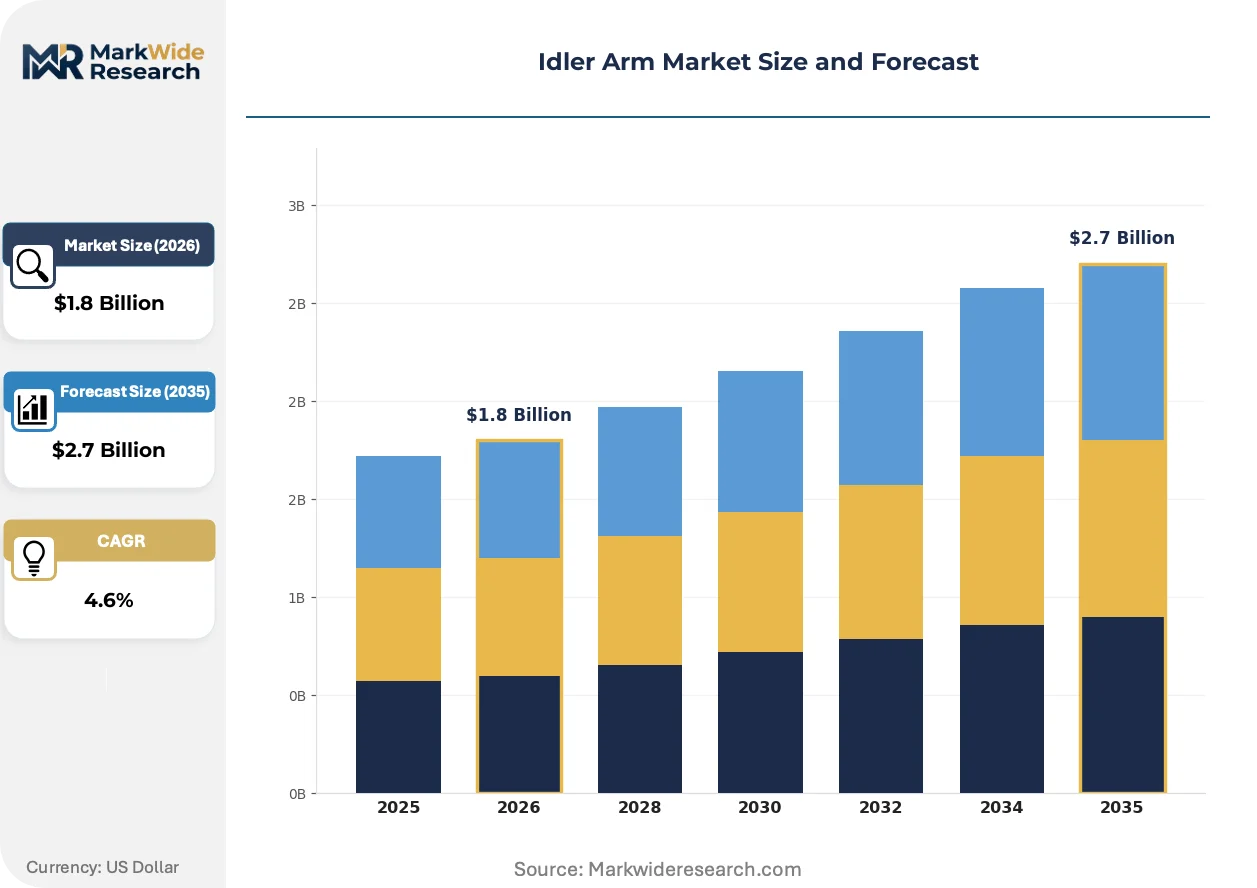
Market Dynamics
The steering linkage market faces structural compression as OEMs consolidate chassis architectures toward rack-and-pinion systems, directly threatening idler arm attach rates in light-vehicle segments while commercial fleet replacement cycles sustain aftermarket demand.
Growth Catalysts
- EPA Foundry Emissions Rules:US regulatory pressure on cupola melting operations is accelerating supplier conversion to electric induction systems, favoring capital-rich domestic producers with compliant infrastructure.
- Heavy-Duty Fleet Replacement Schedules:North American commercial vehicle operators are extending preventive maintenance protocols for steering linkage components under stricter DOT inspection mandates.
- Powdered-Metal Bushing Technology:Advanced sintered bearing surfaces are extending service intervals beyond 75,000 miles, creating upgrade pull in premium aftermarket channels.
Market Restraints
- Scrap Steel Price Volatility:Input cost swings for 4140 and 1045 alloy grades compress forging margins during contract renegotiation windows.
- REACH Hexavalent Chromium Restrictions:European coating compliance is eliminating traditional zinc-chromate hardware finishes, forcing costly process conversions for export-bound suppliers.
- Steer-by-Wire Architecture Threat:Elimination of mechanical steering linkages in autonomous vehicle platforms removes the fundamental application for idler arm assemblies.
Strategic Opportunities
- Mexico Nearshoring Acceleration:OEMs relocating chassis component sourcing from Asia to Mexican border states create demand for localized forging and machining capacity.
- EU Green Deal Procurement Criteria:Lower-carbon forging certification requirements favor suppliers with integrated electric melting and renewable energy contracts.
- E-Commerce Aftermarket Penetration:Direct-to-installer digital platforms are disintermediating traditional warehouse distributors in the North American replacement parts channel.
Industry Challenges
- Heat Treatment Certification Bottlenecks:NADCAP and CQI-9 audit backlogs delay qualified supplier status for aerospace-crossover forging operations.
- Legacy ERP Integration Friction:Tier-1 OEMs mandate EDI and advanced product quality planning interfaces that strain mid-tier supplier IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Idler Arm Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Adjustable, Heavy-Duty, Lightweight Material: Steel, Aluminum, Composite, Cast Iron End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Installation Type: On-Vehicle, Off-Vehicle, Retrofits, Custom Installations |
| Companies Covered | ZF Friedrichshafen AG, MOOG, ACDelco, Sankei Industries Co. Ltd, Mevotech, Dorman Products, TRW Automotive, Sachs, Febi Bilstein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Idler Arm Market Shifts & Advancements
Material science advances and regulatory tightening are bifurcating competitive advantage between lightweight aluminum adoption for mass-sensitive platforms and premium forged steel dominance in load-rated commercial applications.
Aluminum-silicon-magnesium alloy formulations are rewriting chassis component specifications for electric vehicle platforms where unsprung mass reduction extends range. Ford and General Motors have approved A356-T6 idler arm castings for half-ton pickup applications, compressing the traditional steel monopoly in light-duty segments. The structural consequence is a forced technology pivot among forging-dependent suppliers toward hybrid metal capabilities.
REACH authorization requirements for chromium trioxide in corrosion-resistant coatings are mandating trivalent chrome and zinc-nickel alternatives across European-bound production. German Tier-1 suppliers report 12-18 month qualification cycles for new surface treatments, compressing margin recovery timelines. Heavy-duty variants for Scandinavian export markets face the steepest compliance cost escalation due to salt-spray durability specifications.
Fleet maintenance departments are consolidating supplier relationships through integrated procurement platforms that bundle steering linkage with brake and suspension components. National aftermarket distributors in the Great Lakes corridor are losing share to manufacturer-direct programs that guarantee 24-hour availability. This concentration is most visible among US Class 8 truck operators with centralized purchasing authority over multi-state vehicle pools.
Idler Arm Market Segmentation
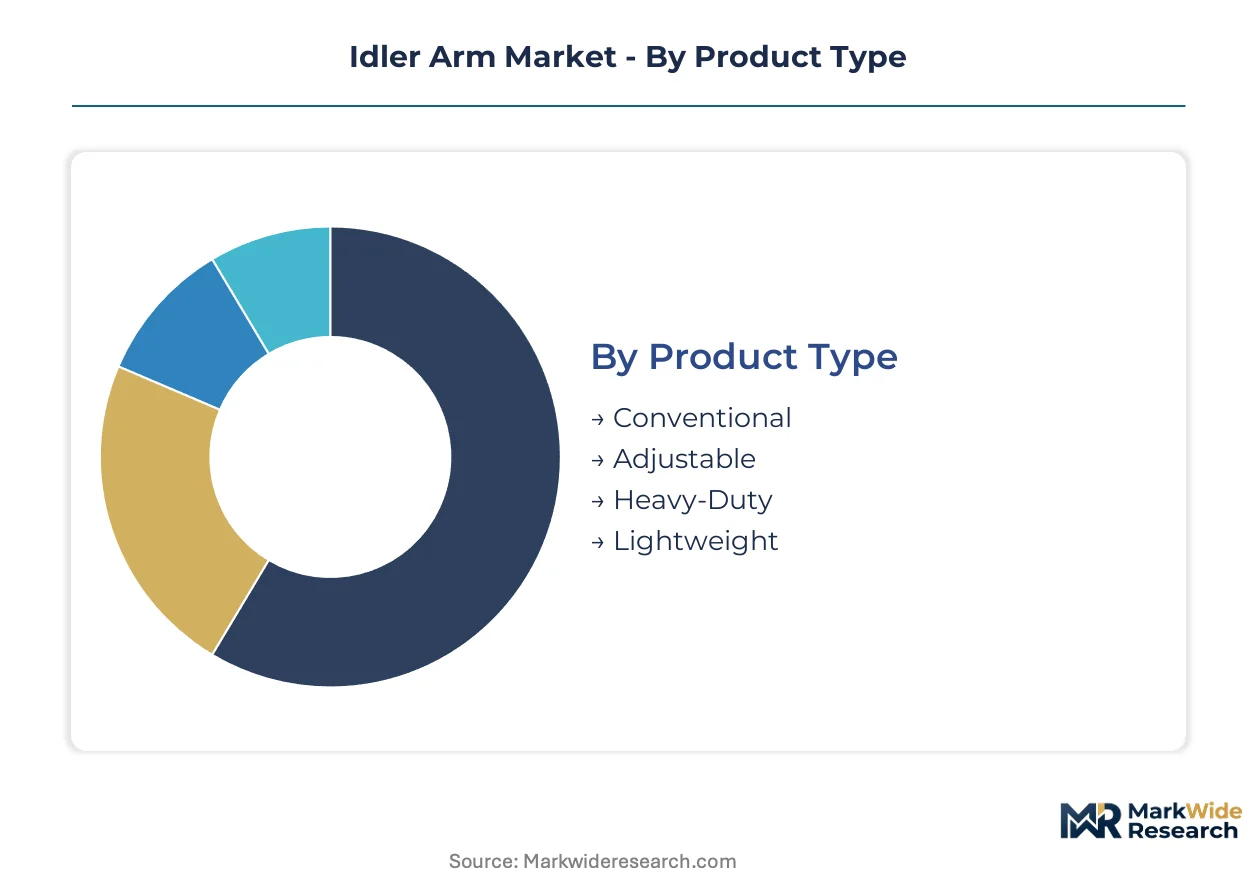
Idler arm procurement patterns diverge sharply between OEM specification cycles and aftermarket replacement velocity. Material selection and duty rating determine margin structures across forging-dependent supply chains.
Product Type:
Volume concentration favors standardized forged configurations, while premium positioning attaches to adjustable and load-rated variants serving commercial duty cycles.
- Conventional:Fixed-geometry forged steel designs dominate aging light-vehicle parc with specified hardness ratings between 35 and 45 HRC. Demand concentrates in United States national aftermarket distributors serving the Great Lakes automotive corridor under extended replacement schedules.
- Heavy-Duty:Reinforced bearing housings and larger-diameter pivot shafts withstand cyclic loads exceeding 50,000 duty cycles. North American Class 8 truck operators with centralized purchasing authority drive specification pull through integrated procurement platforms bundling steering linkage with brake and suspension components.
- Adjustable:Threaded sleeve mechanisms permit toe-angle correction without full component replacement.
- Lightweight:Hollow-section forgings and aluminum pivot assemblies target mass reduction specifications in electric vehicle platforms.
Mature deployment sits with Conventional configurations across the aging vehicle parc. Newer deployment is concentrated in Heavy-Duty variants under stricter DOT inspection mandates.
Material:
Cost tier separation runs between commodity steel formulations and certified low-carbon aluminum alloys commanding Green Deal procurement premiums.
- Steel:4140 and 1045 alloy grades retain volume leadership through established forging infrastructure and NADCAP-qualified heat treatment networks. Scrap steel price volatility compresses margins during contract renegotiation windows for cupola-to-induction conversion projects.
- Aluminum:A356-T6 castings approved by Ford and General Motors for half-ton pickup applications displace traditional steel in mass-sensitive platforms. European assemblers under EU Green Deal procurement criteria certify lower-carbon forging processes favoring electric melting operations.
- Cast Iron:Ductile iron processes specified for hardness-critical commercial applications.
- Composite:Polymer-overmolded bearing surfaces under evaluation for corrosion resistance in salt-spray environments.
Steel formulations anchor current production scale. Aluminum adoption is expanding most quickly in OEM lightweighting programs.
End User:
Customer type dictates specification authority, with captive OEM supply chains enforcing stricter traceability than fragmented aftermarket channels.
- OEMs:Direct supply into General Motors assembly plants through captive distribution networks requires melt-to-finish documentation. ACDelco anchors North American OEM supply with integrated foundry-to-assembly logistics.
- Aftermarket Providers:MOOG sustains channel dominance through proprietary powdered-metal bushing technology extending service intervals beyond 75,000 miles. E-commerce direct-to-installer platforms are disintermediating traditional warehouse distributors.
- Vehicle Assemblers:Tier-1 integration mandates EDI and advanced product quality planning interfaces.
- Repair Shops:Independent service facilities prioritize 24-hour availability guarantees over brand specification.
Aftermarket Providers command replacement volume velocity. Vehicle Assemblers drive specification standardization through consolidated chassis architectures.
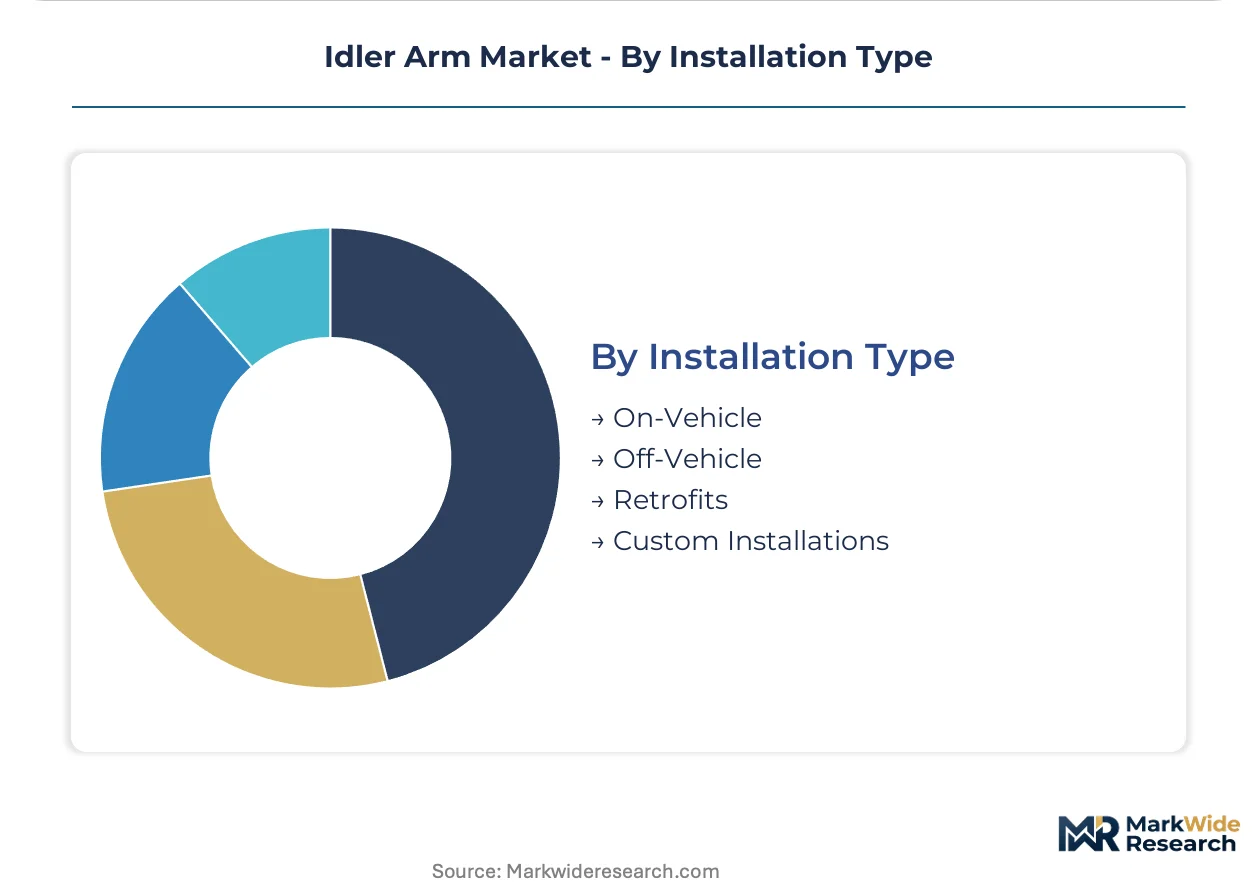
Installation Type:
Service location determines tooling requirements and labor content, with on-vehicle replacement dominating fleet maintenance protocols.
- On-Vehicle:Pitman arm and center link assembly replacement without full steering gear removal. Commercial fleet operators in the United States extend preventive maintenance protocols under tightening NHTSA safety mandates.
- Retrofits:Upgraded bushing materials and reinforced housings for severe-duty applications. Scandinavian export markets face steepest compliance cost escalation due to salt-spray durability specifications under REACH authorization requirements.
- Off-Vehicle:Bench assembly with specialized press fixtures for bearing installation.
- Custom Installations:Modified geometry for lifted suspension or altered steering geometry.
On-Vehicle service retains the largest installed base. Retrofits are gaining share fastest in severe-duty fleet segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes automotive corridor spanning Michigan, Ohio, and Indiana anchors North American idler arm procurement, with heavy-duty fleet operators and national aftermarket distributors concentrating specification authority in this industrial cluster.
United States
Commercial vehicle fleet operators in the Great Lakes corridor are expanding replacement schedules for steering linkage components under tightening NHTSA safety mandates. EPA foundry emissions rules are accelerating supplier conversion from cupola melting to electric induction systems. Detroit-based forging operations are consolidating melt-to-finish traceability capabilities to serve General Motors assembly plants directly.
Germany
Tier-1 suppliers in Baden-Württemberg and Bavaria are certifying lower-carbon forging processes under EU Green Deal procurement criteria. ECHA REACH authorization requirements for chromium trioxide are mandating trivalent chrome and zinc-nickel coating alternatives. Stuttgart-area foundries report extended qualification cycles for new surface treatments serving Scandinavian export markets.
China
Domestic OEMs in the Yangtze River Delta are adopting aluminum-silicon-magnesium alloy formulations for electric vehicle chassis mass reduction targets. MIIT industrial standards are tightening material specifications for steering system components. Shanghai-based forging groups are expanding electric melting capacity to meet dual carbon goals.
Japan
Vehicle assemblers in the Nagoya and Tokyo metropolitan areas are consolidating chassis architectures toward rack-and-pinion systems, compressing idler arm attach rates in light-vehicle segments. METI energy efficiency regulations are incentivizing lightweight material adoption. Aichi Prefecture suppliers are pivoting toward hybrid metal capabilities for remaining commercial applications.
Mexico
OEMs are relocating chassis component sourcing from Asia to Mexican border states, creating demand for localized forging and machining capacity. Nuevo León and Baja California are attracting electric induction foundry investments to serve US assembly plants. Maquiladora operations in Tijuana are integrating powdered-metal bushing technology for aftermarket export channels.
Idler Arm Market Competitive Landscape
The competitive structure tilts toward diversified automotive component conglomerates with captive foundry networks and specialized aftermarket channel specialists with proprietary bushing technology. Three archetypes dominate: integrated Tier-1 systems suppliers controlling melt-to-finish traceability, premium aftermarket brands extending service intervals through material science, and value-tier distributors optimizing logistics velocity. Consolidation is accelerating through OEM captive supply arrangements and digital platform disintermediation of traditional warehouse distributors.
Within the integrated systems tier, ZF Friedrichshafen AG and ACDelco exemplify archetypes of foundry-to-assembly control and captive OEM distribution respectively. MOOG occupies a position among aftermarket specialists leveraging proprietary technology for service interval extension. These three anchors illustrate the bifurcation between specification authority held by OEM-captive suppliers and replacement velocity captured by channel-dominant brands.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| MOOG |
| ACDelco |
| Sankei Industries Co. Ltd |
| Mevotech |
| Dorman Products |
| TRW Automotive |
| Sachs |
| Febi Bilstein |
| Others |
Supply & Pricing Matrix
Centralized procurement authority among US Class 8 truck operators is forcing forging suppliers to absorb scrap steel volatility while maintaining fixed contract pricing, compressing margins and accelerating cupola-to-induction conversion investments.
Pricing Analysis
Service-interval guarantees anchor value-based pricing for powdered-metal bushing upgrades, with MOOG commanding premium positioning through 75,000-mile warranty differentials. Pricing stratifies across heavy-duty forged steel, lightweight aluminum castings, and commodity conventional replacements based on duty-cycle certification and melt-to-finish traceability. Cost compression in standard steel forgings is intensifying because of scrap 4140 and 1045 alloy price swings, with national aftermarket distributors exhibiting highest price sensitivity versus captive OEM supply chains.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta aluminum smelters supplying A356-T6 castings for electric vehicle lightweighting programs. Forging capacity draws from Germany, China, and Mexico, with raw material dependencies on scrap steel alloys, chromium coating chemicals, and silicon-magnesium master alloys. Tariff exposure on European-bound hardware with hexavalent chromium finishes threatens margin recovery timelines. Distribution runs through integrated procurement platforms bundling steering linkage with brake and suspension components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA foundry emissions rules have erected a cost-of-compliance barrier that favors capital-rich domestic producers with electric induction infrastructure, creating a sustainable moat against undercapitalized competitors.
For Market Incumbents: Extend melt-to-finish traceability capabilities to defend against rack-and-pinion architecture displacement in light-vehicle segments. Lock in long-term scrap steel supply agreements before contract renegotiation windows compress forging margins further. Prioritize NADCAP heat treatment certification to maintain qualified supplier status for aerospace-crossover operations. For New Entrants and Emerging Players: E-commerce direct-to-installer platforms represent the most penetrable channel for bypassing traditional Great Lakes warehouse distributors. Target severe-duty retrofit segments in Scandinavian export markets where REACH coating compliance has eliminated incumbent process advantages. Lead with 24-hour availability guarantees to capture fleet maintenance departments consolidating supplier relationships. For Investors and Strategic Acquirers: Re-rating potential sits with electric induction foundry operators given EPA emissions enforcement accelerating cupola obsolescence. The five-to-ten year viability window favors suppliers with renewable energy contracts certifying lower-carbon forging processes under EU Green Deal procurement criteria. Monitor steer-by-wire architecture penetration in autonomous vehicle platforms as the fundamental demand destruction signal.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Induction Foundry Conversion | EPA emissions compliance secures qualified supplier status for NHTSA-governed steering system contracts. |
| Powdered-Metal Bushing Technology Licensing | Service interval extension to 75,000 miles commands premium aftermarket positioning against commodity competitors. |
| Mexico Nearshoring Capacity Buildout | Nuevo León and Baja California locations reduce logistics exposure for US assembly plant supply. |
| EU Green Deal Certification Investment | Lower-carbon forging documentation unlocks procurement criteria for European vehicle assemblers. |
| Integrated Procurement Platform Partnership | Bundled steering linkage with brake and suspension components captures fleet consolidation trends. |
Research Methodology
Multi-period observation of EPA foundry emissions compliance rates, scrap steel price volatility, and NHTSA safety mandate enforcement anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and fleet maintenance directors. Secondary validation drew from EPA enforcement databases, NHTSA FMVSS testing records, SEC 10-K filings of diversified automotive component conglomerates, and vehicle production databases. Bottom-up volume estimates triangulated with top-down market sizing across material grade, duty rating, and end-user channel dimensions.
Input-output matrices modeled attach rates for conventional versus rack-and-pinion steering architectures, alloy substitution elasticities, and replacement cycle velocities across commercial fleet segments over the projection horizon. Segmentation dimensions included product type, material formulation, end-user category, and installation protocol. CAGRs derived from regression analysis of historical procurement patterns against regulatory enforcement timelines and OEM platform standardization roadmaps. Forecast inputs incorporated MIIT industrial standards adoption curves and METI energy efficiency incentive structures.
Caveats apply where accelerated steer-by-wire deployment in autonomous platforms, abrupt scrap steel price dislocations, or REACH authorization scope expansions could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Steering Gear Market
Vehicle Components
EGR Coolers Market
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Forestry Trailers Market
Vehicle Components
Truck Axle Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market
Vehicle Components
Rolling Stock LED Lights Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
EGR Valve Market
Vehicle Components
Global Electric Vehicle Parts and Components Market