
 Portable Wheel Jack Market | 2026-2036
Portable Wheel Jack Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Wheel Jack Market Outlook
Electromechanical actuation with integrated load sensing is reconfiguring how portable wheel jacks deliver precision lifting and safety feedback. Torin Big Red leverages its manufacturing scale to dominate the manual and hydraulic tiers across North American auto parts channels. Snap-on Incorporated differentiates through premium positioning and captive distribution to professional mechanics. Enerpac anchors the heavy machinery segment with high-tonnage hydraulic systems engineered for industrial maintenance environments.
A portable wheel jack is a mobile mechanical, hydraulic, pneumatic, or electromechanical device designed to raise one corner of a vehicle or machine, typically incorporating a rated load capacity, minimum and maximum lift height, and a mechanical safety lock or overload valve to prevent uncontrolled descent during service or tire change operations. The electromechanical product type captures the fastest structural expansion as cordless battery platforms and brushless motor architectures displace manual screw mechanisms in both professional and consumer segments. The automotive repair application occupies the largest margin pool due to recurring demand from independent shops and dealership service bays, while racing applications sustain premium pricing through lightweight alloy construction and rapid-lift specifications.
The U.S. Occupational Safety and Health Administration enforces load-rating verification and stability testing protocols that shape product design and liability exposure for manufacturers selling into American industrial channels. The European Union Machinery Directive mandates CE conformity assessment, risk documentation, and emergency lowering provisions that filter market access for imported equipment. The China GB standards and NMPA-aligned quality supervision systems impose additional certification burdens on electromechanical variants with electronic control modules. Stakeholders must monitor how evolving battery safety standards and regional recycling directives for lithium-ion power packs reshape the electromechanical segment's cost structure and competitive moats.
Market Dynamics
Electromechanical actuation with integrated load sensing is restructuring competitive advantage in portable wheel jacks, compressing the performance gap between professional-grade and consumer equipment while elevating baseline safety requirements across all price tiers.
Growth Catalysts
- Fleet maintenance automation:Logistics operators in Germany are standardizing cordless battery platforms to reduce pneumatic infrastructure dependency in depot environments.
- OSHA load-rating enforcement:The U.S. regulator's expanded stability testing protocols are forcing specification upgrades that favor electromechanical systems with digital verification.
- EU Machinery Directive CE conformity:Emergency lowering provisions and risk documentation mandates are filtering out uncertified imports, concentrating demand with compliant manufacturers.
Market Restraints
- Lithium-ion battery supply concentration:Cell production concentrates in East Asian suppliers, exposing electromechanical jack producers to input cost volatility and logistics bottlenecks.
- Manual mechanism price floor:Screw and hydraulic hand jacks maintain cost advantages below 2-ton capacity ratings, limiting electromechanical penetration in economy consumer segments.
- GB standards certification burden:China's NMPA-aligned quality supervision systems impose extended timelines for electronic control module validation, delaying market entry for new electromechanical variants.
Strategic Opportunities
- Racing and motorsport applications:Lightweight alloy construction and rapid-lift specifications command premium pricing in professional racing pits where seconds determine competitive outcomes.
- Independent automotive repair consolidation:Shop aggregation in the United States is creating volume buyers seeking standardized cordless platforms across multiple bay locations.
- Battery safety standard evolution:UN 38.3 and emerging regional recycling directives for lithium-ion power packs are creating certification moats that favor established electromechanical producers with compliance infrastructure.
Industry Challenges
- Electromechanical technician scarcity:Brushless motor diagnostics and battery management system troubleshooting require skills absent from traditional hydraulic mechanic training pipelines.
- Multi-standard certification overlap:Products targeting both EU Machinery Directive and OSHA channels face conflicting test protocols that extend development cycles and inflate validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Wheel Jack Market |
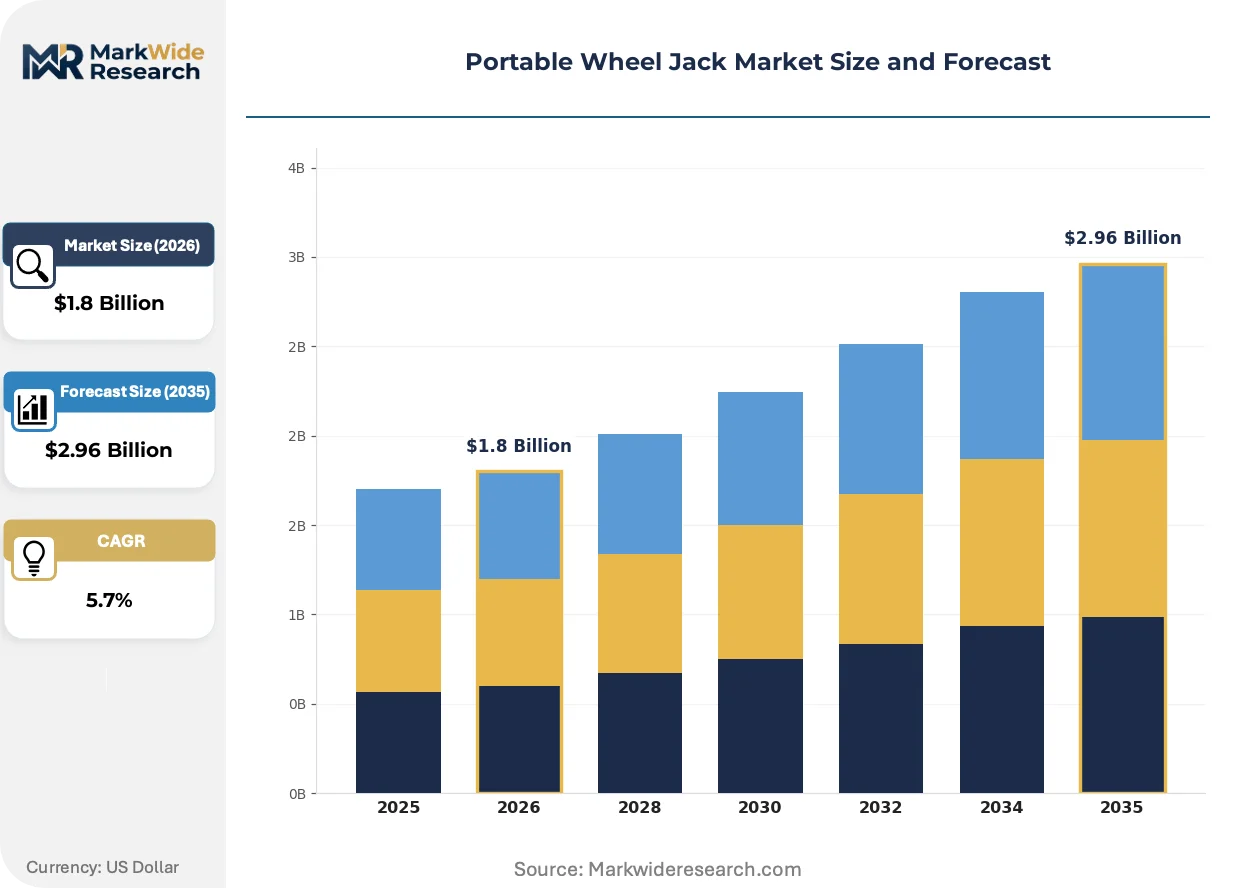
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Pneumatic, Electromechanical, Manual Application: Automotive Repair, Racing, Heavy Machinery, Household Use Size: 2-Ton, 3-Ton, 4-Ton, 5-Ton Distribution Channel: Online Retailers, Auto Parts Stores, Hardware Stores, Wholesalers |
| Companies Covered | Torin Big Red, Blackhawk Automotive, Arcan Tools, ESCO Equipment Supply Company, Powerbuilt Tools, Sunex Tools, Enerpac, Snap-on Incorporated, Jiaxing Datong Machinery Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Wheel Jack Market Strategic Shifts
Portable wheel jack design is converging around cordless electromechanical platforms that integrate sensor feedback, compressing the traditional separation between professional and consumer performance tiers while reshaping how buyers evaluate total cost of ownership.
Brushless DC motor architectures paired with lithium-ion battery packs are rendering obsolete pneumatic and manual screw mechanisms in mid-capacity applications. Independent repair shops in Germany and the United States are adopting these platforms at accelerating rates to eliminate compressed air infrastructure and reduce technician fatigue. The shift is compressing aftermarket parts demand for seal kits and hydraulic fluid while expanding software update and battery replacement revenue streams.
CE marking under the EU Machinery Directive now mandates documented risk assessments and emergency lowering provisions that exceed prior self-certification norms. Manufacturers must maintain technical files and conformity assessment records accessible to market surveillance authorities. Electromechanical variants with electronic control modules face the steepest compliance burden, filtering market access for smaller producers lacking dedicated regulatory affairs capacity.
Buyer evaluation criteria are pivoting from upfront equipment cost toward lifecycle operating expense and technician productivity metrics. Fleet maintenance operators in Germany now specify cordless platforms based on charge-cycle durability and mean time between failures rather than rated lift capacity alone. This behavioral shift is most visible in high-volume depot environments where equipment utilization rates amplify total cost of ownership calculations.
Portable Wheel Jack Market Segmentation
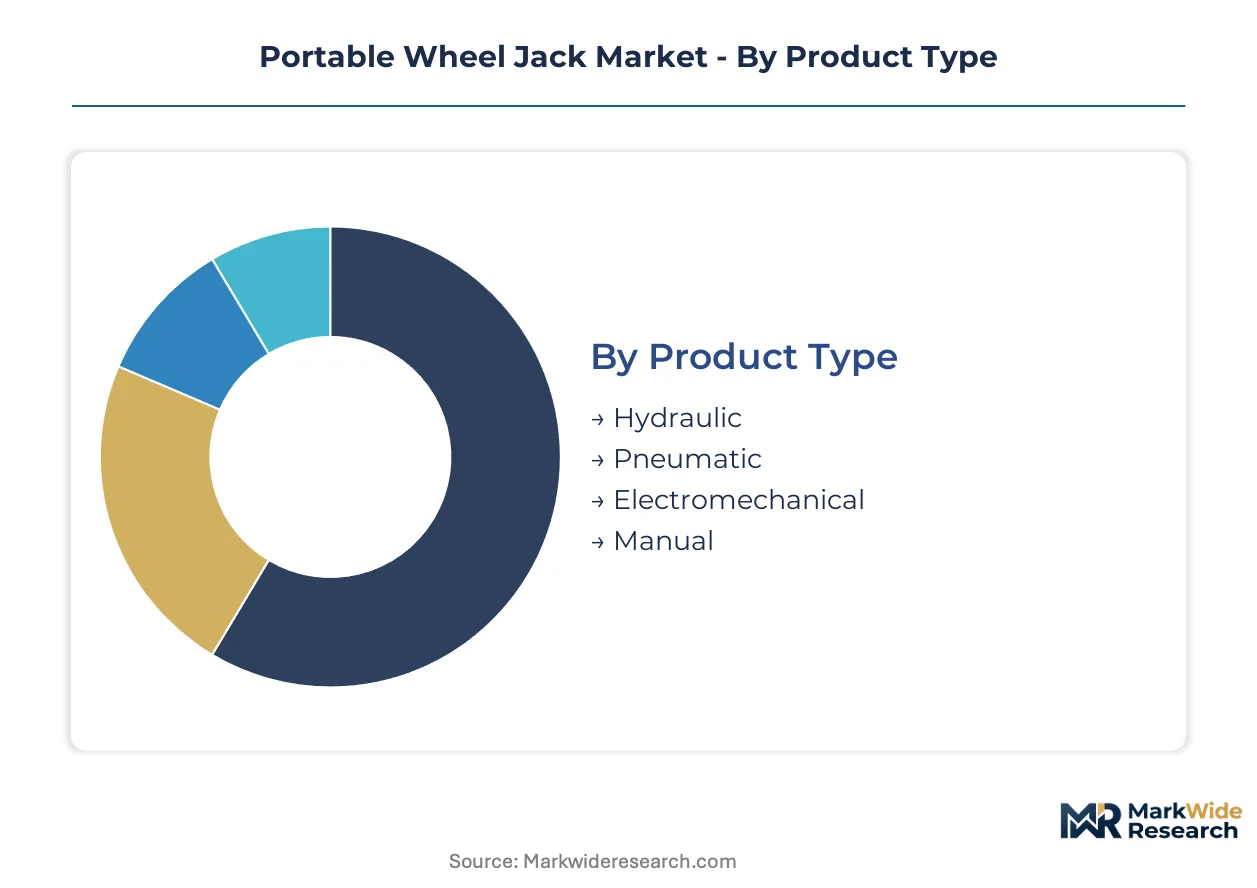
Portable wheel jack purchasing patterns diverge sharply across technical specifications and channel access, with fleet operators prioritizing duty-cycle durability while consumers respond to price-point accessibility and retail availability. Understanding these segment boundaries clarifies where technology investments concentrate versus where cost engineering dominates competitive positioning.
Product Type:
Cycle times vary dramatically across actuation technologies, with electromechanical platforms requiring battery refresh intervals that compress replacement revenue windows versus hydraulic systems with decade-long service lives.
- Hydraulic:Fluid-powered piston mechanisms deliver consistent lift force across temperature extremes and resist contamination in industrial depot environments. Demand concentrates in German fleet maintenance operations where OSHA-aligned stability protocols favor proven load-rating verification systems. The segment anchors replacement parts revenue through seal kit and hydraulic fluid consumption.
- Electromechanical:Brushless DC motor architectures paired with lithium-ion battery packs enable cordless operation and integrated load sensing feedback. German logistics operators are standardizing these platforms to eliminate pneumatic infrastructure dependency while meeting EU Machinery Directive emergency lowering mandates. The technology gains share fastest in professional automotive repair bays seeking technician productivity metrics.
- Pneumatic:Compressed air systems maintain cost advantages in high-volume commercial garages with existing compressor infrastructure.
- Manual:Screw and ratchet mechanisms dominate household emergency kits and economy consumer segments below 2-ton ratings.
Hydraulic systems anchor the volume base while electromechanical platforms gain share at the steepest rate.
Application:
Margin structures invert across use cases, with racing applications commanding alloy-premium pricing while household segments compete on manufacturing scale and retail slotting fees.
- Automotive Repair:Independent shops and dealership service bays generate recurring demand through bay-standardization programs and multi-location procurement contracts. The United States shop consolidation trend is creating volume buyers seeking cordless platform standardization across facilities. Technician fatigue reduction and OSHA compliance documentation drive specification upgrades.
- Racing:Motorsport pits require lightweight titanium or aluminum alloy construction with rapid-lift specifications where seconds determine competitive outcomes. Professional racing teams in Germany sustain premium pricing through FIA-aligned technical partnerships and custom engineering relationships.
- Heavy Machinery:Industrial maintenance environments specify high-tonnage ratings with extended lift heights for construction and agricultural equipment servicing.
- Household Use:Emergency tire change scenarios prioritize compact storage dimensions and intuitive operation for non-technical consumers.
Automotive repair commands the largest revenue pool while racing sustains the highest margin per unit.
Size:
Procurement patterns scale with vehicle fleet composition, with commercial operators standardizing on 3-ton ratings for light truck coverage while passenger car focus drives 2-ton concentration in consumer channels.
- 2-Ton:Compact passenger vehicle coverage dominates household emergency kit purchases and economy retail placements. Manual and basic hydraulic mechanisms maintain price competitiveness in this bracket.
- 3-Ton:Light truck and SUV compatibility makes this the fleet standardization anchor for United States independent repair chains seeking single-SKU bay coverage.
- 4-Ton:Medium-duty commercial vehicle support requires reinforced frame construction and extended lift height specifications.
- 5-Ton:Heavy machinery and commercial truck applications specify industrial-grade hydraulic or electromechanical platforms with documented load-rating certification.
3-ton ratings anchor commercial procurement volume while 5-ton specifications expand fastest in industrial maintenance outsourcing.
Distribution Channel:
Channel economics fragment across technical support requirements, with electromechanical platforms requiring diagnostic service infrastructure that online retailers struggle to provision.
- Online Retailers:Direct-to-consumer logistics enable price transparency and review-aggregation that compresses margin in standardized manual and hydraulic tiers. Battery safety documentation and UN 38.3 shipping compliance create fulfillment complexity for electromechanical variants.
- Auto Parts Stores:Professional mechanic counter relationships and same-day availability sustain premium positioning for Snap-on and comparable brands with captive technical support networks.
- Hardware Stores:Generalist retail placements concentrate in household emergency and light-duty consumer segments with minimal technical consultation.
- Wholesalers:Volume aggregation for fleet operators and repair chain procurement leverages contract pricing and standardized logistics.
Auto parts stores anchor professional-grade volume while online retailers capture the steepest household segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export electromechanical wheel jacks to United States fleet operators, establishing a transatlantic trade corridor shaped by divergent regulatory timelines and automotive aftermarket tooling standards.
United States
Fleet maintenance automation drives cordless platform adoption among logistics operators seeking to eliminate pneumatic infrastructure. OSHA enforces expanded stability testing protocols that favor electromechanical systems with digital load-rating verification. Detroit-area automotive service clusters concentrate demand from independent repair chains standardizing equipment across multi-location procurement contracts.
Germany
Automotive aftermarket tooling investment sustains premium demand for precision lifting equipment with integrated safety feedback. EU Machinery Directive CE conformity mandates emergency lowering provisions and documented risk assessments that filter uncertified imports. Stuttgart's industrial machinery corridor anchors production of high-tonnage hydraulic systems for commercial vehicle servicing applications.
China
Domestic electromechanical platform manufacturing scales to serve regional export markets and internal fleet modernization programs. GB standards and NMPA-aligned quality supervision systems impose extended validation timelines for electronic control modules. Shanghai-Pudong logistics hubs concentrate procurement from state-owned fleet operators upgrading depot maintenance infrastructure.
Japan
Precision manufacturing heritage supports development of compact brushless motor architectures for professional automotive applications. METI industrial standards and JIS certification requirements maintain quality benchmarks for lifting equipment exports. Nagoya's automotive supplier ecosystem integrates wheel jack specification into dealership service bay standardization programs.
United Kingdom
Independent garage consolidation creates volume buyers seeking standardized cordless platforms across acquired locations. Post-Brexit regulatory alignment with EU Machinery Directive provisions maintains CE marking requirements for imported equipment. Midlands automotive repair clusters drive specification upgrades tied to technician productivity and liability reduction metrics.
Portable Wheel Jack Market Competitive Environment
On the supply side, the industry is bifurcated between scale-driven manufacturers serving retail channels and specialized producers targeting professional fleet and industrial segments. Strategic archetypes include manual-hydraulic volume leaders, electromechanical technology specialists, and heavy machinery system integrators. Dominant competitive moves encompass geographic expansion through distributor partnerships and portfolio diversification into cordless battery platforms.
Among North American equipment suppliers, Torin Big Red and Snap-on Incorporated exemplify contrasting positioning archetypes, while Enerpac anchors the heavy machinery tier with industrial-grade system integration capabilities. Jiaxing Datong Machinery Co., Ltd. represents Chinese manufacturing scale in the export-oriented manual and hydraulic equipment segments. These three companies occupy positions that illustrate how channel access and technical specification depth determine competitive boundaries.
| Leading Market Players |
|---|
| Torin Big Red |
| Blackhawk Automotive |
| Arcan Tools |
| ESCO Equipment Supply Company |
| Powerbuilt Tools |
| Sunex Tools |
| Enerpac |
| Snap-on Incorporated |
| Jiaxing Datong Machinery Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure on East Asian lithium-ion cell imports compresses margin structures across electromechanical tiers while simultaneously forcing supply chain reconfiguration toward regional battery assembly partnerships. This dual pressure widens pricing spreads between premium CE-certified platforms and economy manual alternatives, concentrating procurement leverage with fleet operators capable of volume contracting.
Pricing Analysis
The technology-generation pricing gap separates legacy hydraulic systems from first-generation cordless electromechanical platforms and emerging solid-state battery architectures. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in the economy manual tier intensifies because of Chinese manufacturing scale and direct-to-consumer channel expansion. Fleet maintenance operators exhibit the lowest price sensitivity, prioritizing lifecycle operating expense and technician productivity metrics over upfront equipment cost.
Supply Chain Analysis
Extended payment terms from German automotive aftermarket distributors now reach ninety days, straining working capital for smaller electromechanical producers lacking supply-chain finance facilities. Cell production concentrates in China, South Korea, and Japan, while precision machining of aluminum alloy components feeds from German and Japanese supplier networks. Single-source vulnerability around brushless DC motor controllers creates chokepoint risk for European assemblers. Distribution runs through captive auto parts store networks for professional-grade equipment and direct-to-consumer logistics for household emergency segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable wheel jack market sits in early-cycle recovery following pandemic-depressed fleet maintenance capital expenditure, with logistics operator infrastructure renewal now accelerating replacement demand across German and United States depot networks.
For Market Incumbents: Build certification moats through accelerated EU Machinery Directive technical file investment and OSHA-aligned stability testing protocol documentation. Snap-on Incorporated and Torin Big Red should deepen backward integration into brushless motor controller design to offset East Asian semiconductor dependency. Channel control through exclusive auto parts store counter relationships defends margin position against online retail price transparency. For New Entrants and Emerging Players: Pursue white-space capture in the racing and motorsport application tier, where FIA-aligned technical partnerships and lightweight alloy engineering capabilities command premium pricing with limited incumbent specialization. Independent automotive repair consolidation in the United States creates penetrable volume buyer segments seeking standardized cordless platforms across multi-location procurement. A direct-to-fleet sales model bypassing traditional distribution markups offers viable go-to-market positioning. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors electromechanical technology specialists with established CE marking infrastructure and lithium-ion battery safety certification capabilities. Long-term viability over the next decade hinges on regulatory compliance scalability rather than manufacturing scale alone. Acquisition targets should demonstrate documented conformity assessment capacity under evolving UN 38.3 shipping protocols and emerging regional recycling directives. The inflection signal to watch is German logistics operator standardization decisions on cordless platform specifications, which will consolidate demand around compliant producers.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | German fleet operators specify interchangeable lithium-ion packs across depot networks to reduce spare inventory carrying costs. |
| CE Marking Acceleration | EU Machinery Directive emergency lowering provisions filter market access for uncertified imports from Chinese producers. |
| Backward Integration into Motor Controllers | Brushless DC architecture control reduces dependency on East Asian semiconductor suppliers facing tariff exposure. |
| Racing Application Engineering Partnership | FIA-aligned technical relationships sustain premium pricing through custom titanium alloy rapid-lift specifications. |
| Fleet Direct Sales Channel Development | Independent repair chain consolidation in the United States creates volume buyers seeking multi-location equipment standardization. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and automotive aftermarket distribution data. Maintenance directors at German logistics depots, procurement leads at United States independent repair chains, OEM aftermarket service heads, and electromechanical platform engineers provided structured input. Bottom-up demand modeling from fleet operator equipment specifications triangulates against top-down market sizing from trade association production statistics and channel shipment data.
Forecast inputs incorporate actuation technology substitution curves, battery chemistry cost trajectories, and regional regulatory implementation timelines. Segmentation dimensions span product type, application tier, rated load capacity, and distribution channel structure. CAGRs derive from equipment replacement cycle analysis and fleet maintenance automation adoption rates across the projection horizon. Brushless motor platform penetration and lithium-ion cell supply cost evolution constitute primary industry-specific forecast variables.
Sensitivities concentrate around EU Machinery Directive enforcement intensity, OSHA stability testing protocol expansion, and East Asian battery cell supply disruptions. Forecasts reflect documented assumptions on fleet operator capital expenditure recovery and electromechanical technician training pipeline development. Macroeconomic contraction, regulatory timeline acceleration, or solid-state battery commercialization would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Two Wheeler Footrest Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Truck Axle Market
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
Wheel Chocks Market
Vehicle Components
Italy Automotive Composites Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
Front Forks Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Hydrostatic Transmission Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Global Bearings Market