
 US Group 2 Powered Mobility Devices Market | 2026-2036
US Group 2 Powered Mobility Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Group 2 Powered Mobility Devices Market Intelligence
Modular battery architecture and interchangeable drive systems is fragmenting traditional integrated chassis designs into upgradeable component ecosystems. Pride Mobility Products Corporation anchors its market presence through vertical manufacturing control over frame fabrication and upholstery operations. Golden Technologies competes on specialized lift-chair-to-power-mobility cross-selling through durable medical equipment dealer networks. Permobil differentiates via advanced power positioning and standing function technology leadership in complex rehabilitation segments.
Group 2 powered mobility devices comprise electrically powered wheelchairs and scooters meeting CMS coverage criteria for beneficiaries requiring seated mobility assistance in home and community settings, typically featuring minimum six-mile range capability and standard seat widths accommodating bariatric needs through 22-inch or wider configurations. Power wheelchairs represent the established revenue base where CMS competitive bidding and prior authorization requirements have compressed margins, while sensor technologies including obstacle detection and tilt-in-space automation command premium positioning in the fastest-growing technology tier. Mobility scooters sustain volume leadership in senior living community procurement channels where facility-wide fleet standardization drives bulk purchasing agreements.
FDA 510(k) premarket notification requirements govern device safety and electromagnetic compatibility standards, while CMS National Coverage Determinations and Durable Medical Equipment Medicare Administrative Contractor local coverage policies directly control beneficiary access and supplier reimbursement rates. State Medicaid programs layer additional prior authorization complexity that shapes regional market penetration patterns. Stakeholders must monitor evolving FDA software-as-medical-device guidance for autonomous navigation features and CMS competitive bidding program expansion timelines that could restructure supplier economics.
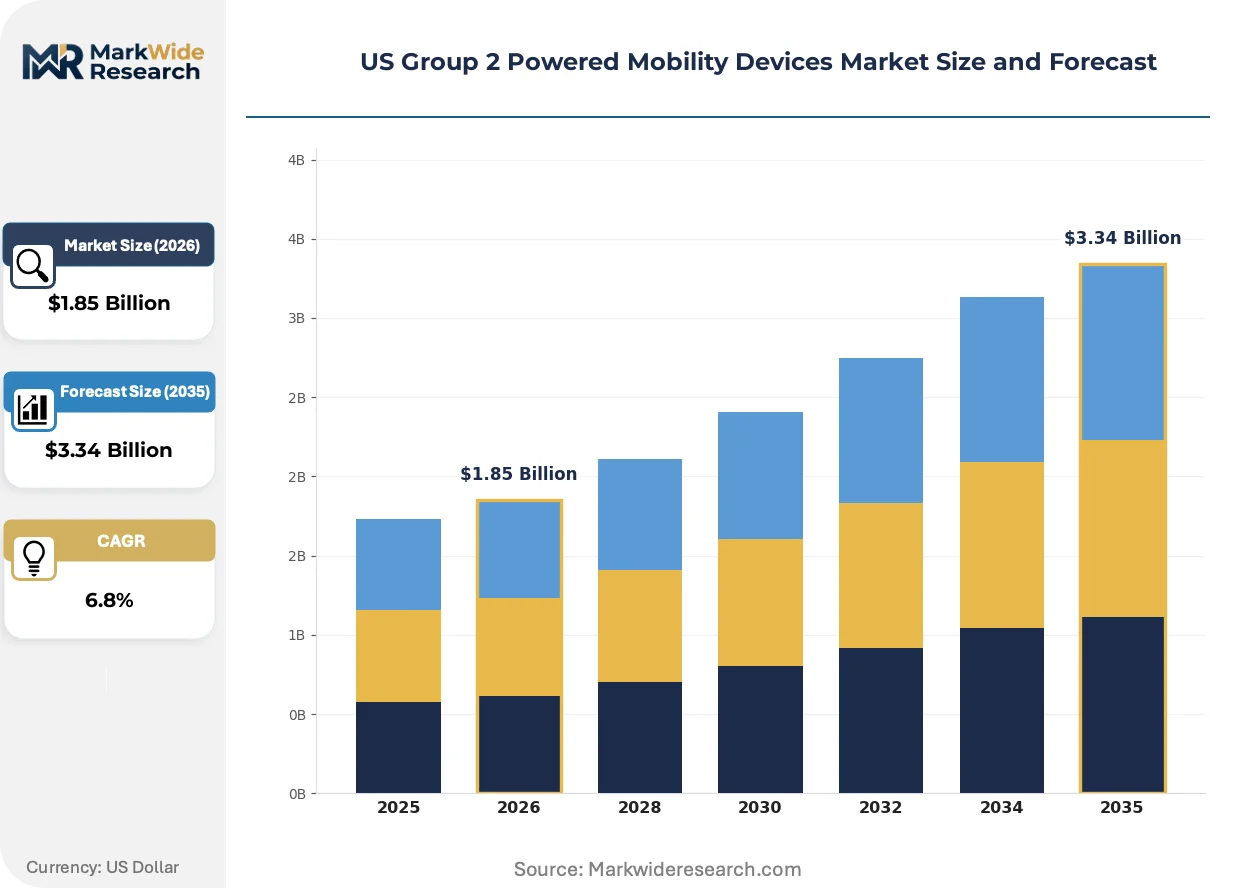
Market Dynamics
CMS prior authorization expansion and competitive bidding program restructuring are compressing supplier margins while accelerating consolidation among durable medical equipment dealers serving Medicare beneficiaries.
Growth Catalysts
- Sun Belt Demographic Migration:Florida, Arizona, and Texas are absorbing disproportionate senior population inflows, expanding addressable beneficiary pools and dealer network density in these corridors.
- IRAs Home Modification Incentives:Federal tax credits for accessible home improvements are reducing out-of-pocket barriers for first-time powered mobility device acquisition among aging-in-place households.
- Modular Battery Swapping:Interchangeable lithium-ion pack architectures are extending product lifecycles and creating recurring revenue streams through component upgrade pathways.
Market Restraints
- CMS Competitive Bidding Compression:Medicare reimbursement rate reductions in competitive bidding areas are squeezing dealer margins below sustainable thresholds for independent suppliers.
- Semiconductor Supply Concentration:Motor controller chip fabrication depends on concentrated Asian foundry capacity, exposing manufacturers to extended lead time volatility.
- Lead-Acid Battery Displacement Lag:Legacy sealed lead-acid power systems retain installed base dominance due to lower upfront costs, slowing premium lithium-ion penetration in price-sensitive segments.
Strategic Opportunities
- Rural Broadband-Enabled Remote Diagnostics:FCC infrastructure subsidies are expanding telehealth connectivity to underserved counties, opening subscription-based predictive maintenance models for fleet operators.
- Standing Function Prior Authorization Liberalization:Evolving CMS coverage determinations for complex rehabilitation technology are widening reimbursement access to power positioning features previously restricted to Group 3 devices.
- Sensor Fusion Convergence:Integration of ultrasonic obstacle detection with gyroscopic tilt compensation is creating autonomous navigation capabilities that command premium positioning in assisted living facility procurement.
Industry Challenges
- FDA Software-as-Medical-Device Classification:Autonomous navigation algorithms face evolving 510(k) pathway uncertainty, extending commercialization timelines for AI-enabled collision avoidance systems.
- Dealer Network Certification Bottlenecks:CMS supplier accreditation requirements and state Medicaid enrollment complexity are constraining qualified distribution capacity in high-growth metropolitan markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Group 2 Powered Mobility Devices Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Wheelchairs, Mobility Scooters, Standers, Accessories End User: Individuals, Healthcare Facilities, Rehabilitation Centers, Senior Living Communities Deployment: Home Care, Hospital Use, Community Access, Outdoor Mobility Technology: Electric Drives, Control Systems, Battery Types, Sensor Technologies |
| Companies Covered | Golden Technologies, Pride Mobility Products Corporation, Invacare Corporation, National Seating & Mobility, Numotion, Drive DeVilbiss Healthcare, Sunrise Medical, Permobil, Shoprider Mobility Products, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Group 2 Powered Mobility Devices Market Strategic Shifts & Innovations
Technology migration from fixed mechanical systems to software-defined control architectures is redefining competitive differentiation beyond hardware specifications toward data-enabled service models.
Brushless DC motor controllers with integrated field-oriented control algorithms are migrating from industrial automation into mid-tier power wheelchair platforms. Complex rehabilitation clinics and veterans affairs procurement channels are adopting these systems for precision torque management. The technology is migrating from premium standing-function chassis into standard tilt-in-space configurations, compressing the performance gap between product tiers.
FDA draft guidance on autonomous navigation features is requiring premarket submission for software updates that modify collision avoidance behavior. Manufacturers must establish quality management systems for over-the-air firmware distribution. Complex rehabilitation segments face the steepest compliance burden as standing-function devices incorporate the most sophisticated environmental sensing arrays.
Facility procurement officers in senior living communities are consolidating vendor relationships through multi-year fleet standardization agreements. Bulk purchasing contracts are displacing individual beneficiary-driven transactions in institutional channels. This concentration is most pronounced across Arizona and Florida metropolitan statistical areas where operator roll-ups have created regional buying coalitions.
US Group 2 Powered Mobility Devices Market Segmentation
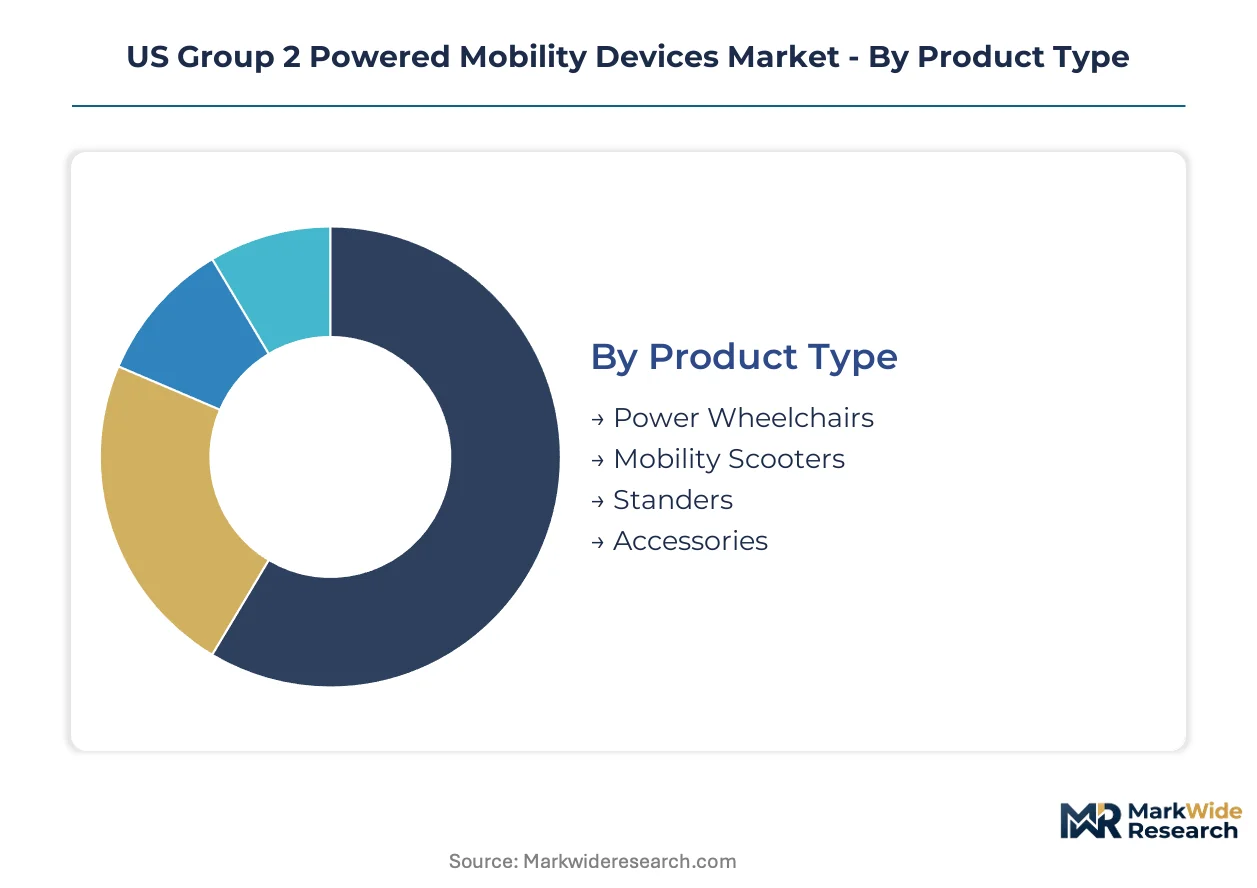
Segmentation in the US Group 2 Powered Mobility Devices Market reveals distinct service intensity patterns across product tiers. After-sales maintenance requirements vary dramatically between complex rehabilitation power wheelchairs and standard mobility scooters, reshaping supplier profitability models and dealer network investment priorities.
Product Type:
After-sales service intensity escalates with mechanical complexity and software dependency, creating divergent margin structures across product categories.
- Power Wheelchairs:These devices integrate brushless DC motors with field-oriented control algorithms and programmable power positioning systems. CMS prior authorization requirements and competitive bidding compression dominate procurement in Florida, Arizona, and Texas corridors where Medicare beneficiary density concentrates dealer network investment.
- Mobility Scooters:Simpler electromechanical architectures with sealed lead-acid or entry lithium-ion power systems serve price-sensitive segments. Senior living communities in Sun Belt metropolitan statistical areas drive fleet standardization agreements that displace individual beneficiary transactions through multi-year bulk purchasing contracts.
- Standers:Complex rehabilitation devices with powered sit-to-stand functionality require specialized clinical assessment and fitting protocols.
- Accessories:Modular battery packs, interchangeable seating systems, and control interface peripherals generate recurring revenue through component upgrade pathways.
Power wheelchairs hold the largest share; momentum sits with accessories as modular architectures extend product lifecycles.
End User:
Procurement authority and reimbursement pathway complexity fragment demand across institutional and individual channels.
- Individuals:Medicare beneficiaries navigate CMS National Coverage Determinations and Durable Medical Equipment Medicare Administrative Contractor local coverage policies to secure device access. IRA home modification tax credits reduce out-of-pocket barriers for first-time acquisition among aging-in-place households.
- Healthcare Facilities:Hospital outpatient departments and skilled nursing facilities operate under distinct reimbursement schedules with consolidated procurement processes.
- Rehabilitation Centers:Complex rehabilitation technology clinics prescribe advanced power positioning features previously restricted to Group 3 devices.
- Senior Living Communities:Facility procurement officers consolidate vendor relationships through multi-year fleet standardization agreements across Arizona and Florida operator roll-ups.
Individuals represent the established volume base; senior living communities are expanding most quickly through institutional procurement concentration.
Deployment:
Environmental exposure conditions determine durability specifications and warranty exposure for suppliers.
- Home Care:Indoor-dominant usage patterns with occasional community access define the core Medicare coverage criteria for Group 2 classification. Aging-in-place households in suburban Sun Belt counties generate replacement demand as sealed lead-acid installed bases reach end-of-life.
- Hospital Use:Short-term rental and patient transport applications require rapid sanitization protocols and bariatric accommodation.
- Community Access:Sidewalk and public transit interface demands six-mile minimum range capability under CMS coverage standards.
- Outdoor Mobility:Uneven terrain navigation and weather exposure accelerate component wear and service event frequency.
Home care dominates beneficiary volume; outdoor mobility commands premium positioning through ruggedized chassis specifications.
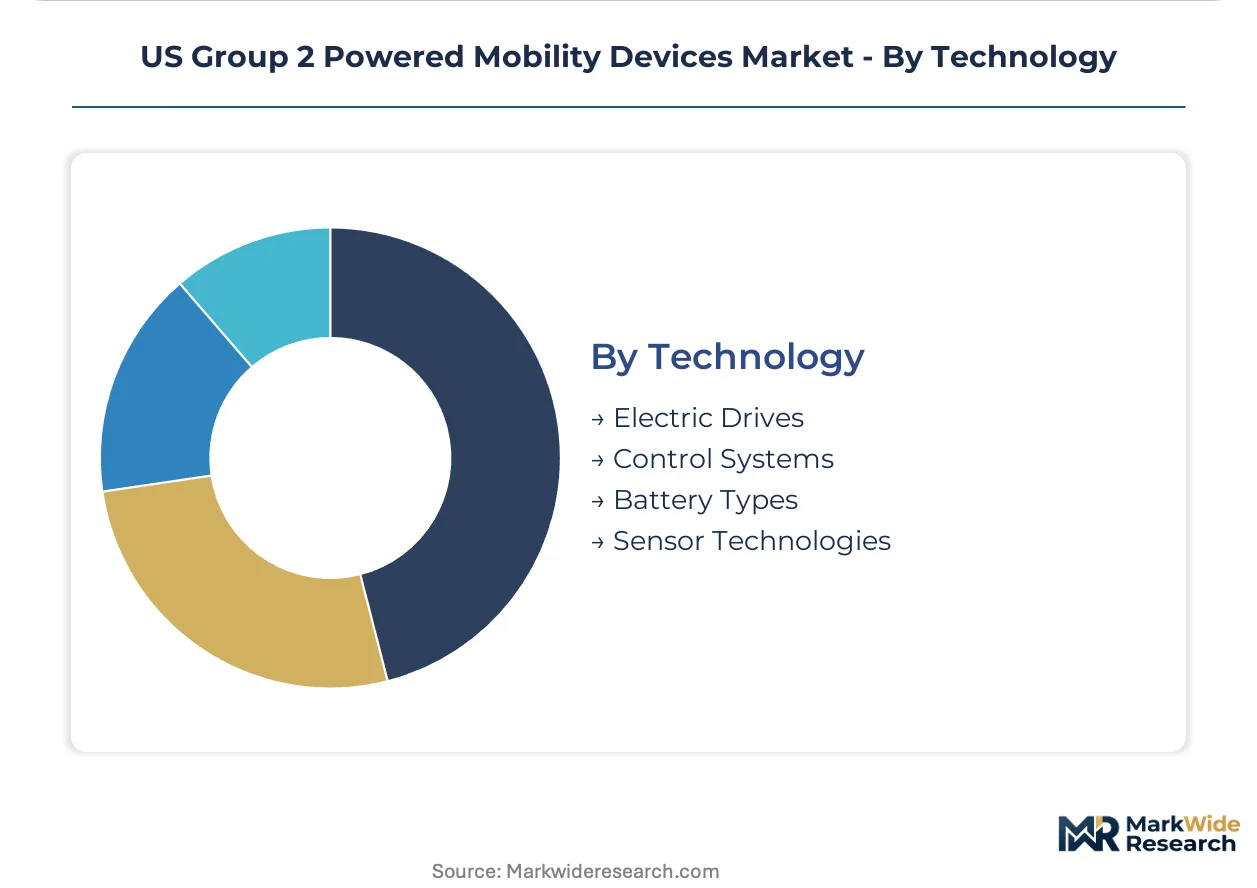
Technology:
Software-defined control architectures are displacing fixed mechanical systems as the primary competitive differentiator.
- Electric Drives:Brushless DC motor controllers with integrated field-oriented control algorithms migrate from industrial automation into mid-tier platforms. Veterans Affairs procurement channels adopt these systems for precision torque management in complex rehabilitation applications.
- Control Systems:Programmable joystick interfaces and alternative access methods accommodate progressive neurological conditions. FDA software-as-medical-device draft guidance requires premarket submission for firmware updates modifying collision avoidance behavior.
- Battery Types:Lithium-ion pack architectures with interchangeable designs create recurring revenue streams through component upgrade pathways. Legacy sealed lead-acid systems retain installed base dominance in price-sensitive segments due to lower upfront acquisition costs.
- Sensor Technologies:Ultrasonic obstacle detection combined with gyroscopic tilt compensation creates autonomous navigation capabilities. Assisted living facility procurement officers command premium positioning for these features in fleet standardization agreements.
Electric drives anchor current revenue; sensor technologies are gaining share fastest as AI-enabled collision avoidance systems advance through FDA clearance pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico exports powered mobility subassemblies to US final assembly plants in the Sun Belt corridor, where Medicare beneficiary density drives dealer network investment and inventory positioning decisions.
Florida
Senior migration from the Northeast and Midwest swells Medicare Advantage enrollment in Tampa and Orlando metropolitan corridors. CMS competitive bidding zones in these counties compress reimbursement rates while concentrating supplier market share. Miami-Dade hosts the densest durable medical equipment dealer network in the Southeast, with facility procurement officers executing multi-year fleet agreements for senior living operator roll-ups.
Texas
Houston and Dallas-Fort Worth absorb retiring military veterans through VA healthcare system referrals for complex rehabilitation technology. State Medicaid prior authorization requirements vary by Health and Human Services Commission region, creating patchwork coverage for power positioning features. Austin's technology sector attracts venture investment in sensor-enabled navigation startups targeting assisted living facility procurement channels.
Arizona
Phoenix and Tucson metropolitan statistical areas lead national growth in adults aged 75-plus, expanding addressable beneficiary pools for first-time device acquisition. IRA home modification tax credits reduce out-of-pocket barriers for aging-in-place households in Maricopa County suburbs. Scottsdale-based dealer networks specialize in premium lithium-ion configurations for snowbird seasonal residents.
California
Los Angeles and San Diego counties operate under distinct Medi-Cal managed care prior authorization protocols that layer complexity atop CMS National Coverage Determinations. FCC rural broadband subsidies expand telehealth connectivity to Imperial and San Joaquin Valleys, enabling remote diagnostics subscription models. Bay Area veterans affairs facilities drive procurement of standing-function power wheelchairs with advanced power positioning systems.
US Group 2 Powered Mobility Devices Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented supplier tiers. The vendor base organizes around three strategic archetypes: vertically integrated manufacturers with captive frame fabrication, specialized complex rehabilitation technology providers with clinical assessment capabilities, and durable medical equipment dealers with Medicare accreditation concentration. Competitive moves center on multi-year fleet standardization agreements with senior living operators and backward integration into lithium-ion battery pack assembly.
Within the integrated manufacturing tier, Pride Mobility Products Corporation and Golden Technologies exemplify channel dominance through vertical control over upholstery and frame operations. Permobil occupies a position in the complex rehabilitation segment where standing-function technology commands premium positioning. These three anchors represent distinct competitive vectors: manufacturing scale, clinical specialization, and product breadth across lift-chair-to-power-mobility cross-selling.
| Leading Market Players |
|---|
| Golden Technologies |
| Pride Mobility Products Corporation |
| Invacare Corporation |
| National Seating & Mobility |
| Numotion |
| Drive DeVilbiss Healthcare |
| Sunrise Medical |
| Permobil |
| Shoprider Mobility Products, Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity in Asian semiconductor foundries is squeezing motor controller availability and forcing US manufacturers toward dual-sourcing premiums that compress margins across all product tiers.
Pricing Analysis
Current-generation lithium-ion configurations command substantial premiums over prior-generation sealed lead-acid systems, while next-generation autonomous navigation features await FDA 510(k) clearance before premium realization. Three-tier pricing structure across premium sensor-enabled, standard programmable positioning, and economy fixed-frame levels dominates the market. Price differentiation rests on CMS competitive bidding zone status and after-sales service bundling intensity. Pricing pressure stems from Medicare reimbursement compression in competitive bidding areas, squeezing dealer margins below sustainable thresholds for independent suppliers. Senior living communities exhibit lowest price sensitivity through fleet standardization agreements, while individual Medicare beneficiaries in non-competitive bidding zones face highest out-of-pocket exposure.
Supply Chain Analysis
Upstream lithium carbonate and cobalt sulfate feedstock draws from concentrated Chilean and Australian mining operations, creating raw material cost volatility that propagates through battery pack assembly. Motor controller chip fabrication rests on Taiwanese and South Korean foundry capacity, exposing manufacturers to extended lead time volatility. Steel tubing and aluminum extrusions for frame fabrication source from Mexican maquiladora operations near US border assembly plants. Single-source vulnerability in brushless DC motor magnet supply creates tariff exposure risk from rare earth element concentration. Distribution runs through CMS-accredited durable medical equipment dealer networks with Medicare Administrative Contractor regional segmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through senior living operator roll-ups across Sun Belt metropolitan areas, consolidating procurement authority into fewer facility procurement officers executing multi-year fleet agreements.
For Market Incumbents: Insulate margin structures by deepening backward integration into lithium-ion battery pack assembly and establishing captive upholstery operations to offset CMS competitive bidding compression. Secure accreditation density in Florida and Arizona corridors where beneficiary migration accelerates dealer network consolidation. Prioritize FDA 510(k) pre-submission pathways for autonomous navigation software to preempt emerging sensor-technology entrants. For New Entrants and Emerging Players: Rural broadband-enabled remote diagnostics subscriptions in FCC-subsidized counties represent the most penetrable entry point, bypassing saturated competitive bidding zones. Standing-function power positioning features migrating from Group 3 to Group 2 CMS coverage determinations create white-space in complex rehabilitation segments. Pursue direct-to-facility sales models targeting Arizona and Florida senior living procurement officers outside established dealer relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor-enabled autonomous navigation sub-segments as FDA software-as-medical-device compliance burdens escalate. Long-term viability favors acquisition targets with established CMS supplier accreditation and vertical control over frame fabrication. Monitor FCC rural broadband subsidy disbursement velocity as inflection indicator for telehealth-enabled predictive maintenance model addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Software-as-medical-device clearance for autonomous navigation features unlocks premium positioning in assisted living procurement. |
| Backward Integration into Battery Assembly | Captive lithium-ion pack production insulates margins from raw material volatility and supplier concentration risk. |
| Senior Living Fleet Standardization Agreement | Multi-year bulk contracts with Florida and Arizona operator roll-ups displace transactional beneficiary-driven volume. |
| Rural Broadband Diagnostics Platform | FCC infrastructure subsidies enable subscription-based predictive maintenance models in underserved counties. |
| CMS Supplier Accreditation Expansion | Accreditation density in competitive bidding zones secures reimbursement access as prior authorization requirements tighten. |
Research Approach
A standing panel of durable medical equipment procurement officers, CMS policy specialists, rehabilitation clinicians, and lithium-ion battery supply managers provided ongoing calibration across primary interview cycles and secondary validation. FDA 510(k) clearance databases, CMS National Coverage Determination records, Medicare Administrative Contractor local coverage policies, and FCC broadband subsidy disbursement reports anchored secondary source triangulation. Bottom-up beneficiary demand modeling and top-down supplier revenue reconciliation converged through iterative refinement.
Scenario-bracketing around CMS competitive bidding program expansion timelines and FDA software-as-medical-device guidance finalization shaped projection boundaries across the analysis window. Segmentation dimensions spanned product type complexity tiers, end-user procurement authority structures, deployment environment durability specifications, and technology generation maturity curves. CAGRs derived from logistic diffusion modeling of lithium-ion displacement rates and beneficiary demographic cohort projections. Forecast inputs incorporated IRA home modification tax credit uptake assumptions and VA complex rehabilitation technology referral patterns.
Stress conditions across semiconductor foundry utilization rates, lithium carbonate price bands, and CMS reimbursement rate adjustment scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway timelines and demographic migration velocity. Cross-checking against CMS Medicare Current Beneficiary Survey utilization benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Bicycle Chain Device Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Two Wheeler Footrest Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
4x4 Vehicle Parts and Accessories Market
Vehicle Components
Transmission Components Market
Vehicle Components
Steering Column Module Market
Vehicle Components
Latin America Two-Wheeler Components Market
Vehicle Components
Railway Brake Pads Market