
 Steering Stabilizers Market | 2026-2036
Steering Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Steering Stabilizers Market Analytics
China is rewriting competitive dynamics through expanded shock absorber foundry capacity in Zhejiang province. Tenneco Inc. leverages its integrated monotube valve manufacturing to sustain cost positions in North American OEM supply. Bilstein competes on motorsport-derived damping architectures that extend into premium aftermarket channels. KYB Corporation anchors Asian production scale, while Öhlins Racing specializes in adjustable stabilizer configurations for performance motorcycle and ATV segments.
A steering stabilizer is a hydraulic or gas-charged damping device mounted inline with a vehicle's steering linkage, typically pressurized to nitrogen gas pressures between nitrogen gas pressures between 150-300 psi and valved to resist rapid angular displacement of the pitman arm or steering rack. Its primary commercial purpose is to attenuate bump steer feedback, tire imbalance oscillation, and drivetrain torque steer in solid-axle and heavy-duty independent front suspension architectures. Adjustable stabilizers command margin premiums over non-adjustable units due to tunable compression-rebound curves demanded by lifted truck and overland vehicle builders. The aftermarket provider channel outpaces OEM attach rates as vehicle aging fleets in commercial and recreational segments drive replacement cycles.
NHTSA enforces FMVSS 126 electronic stability control performance criteria that indirectly constrain steering damper tuning ranges for vehicles above gross vehicle weight ratings. EPA tailpipe and fuel economy standards pressure OEMs to reduce steering system parasitic losses, favoring low-friction stabilizer seals and lighter aluminum bodies over traditional steel constructions. ISO 26262 functional safety protocols now govern steering actuator integration in electric power steering architectures. Stakeholders must monitor how software-defined steering calibration interfaces reshape hardware specification workflows across Tier-1 supplier engineering departments.
Market Dynamics
FMVSS 126 compliance thresholds for electronic stability control are tightening steering damper specification windows, forcing recalibration of nitrogen gas pressure ranges and valve response curves across North American OEM supply chains. This regulatory compression is accelerating hardware-software integration requirements in heavy light truck platforms.
Growth Catalysts
- Off-highway fleet replacement cycles:Aging commercial and recreational vehicle populations in Texas and Arizona off-road clusters sustain elevated aftermarket procurement of dual stabilizer kits.
- NHTSA mandate expansion:Updated FMVSS 126 coverage of heavier light trucks tightens steering system compliance thresholds, mandating upgraded stabilizer performance for gross vehicle weight ratings previously exempt.
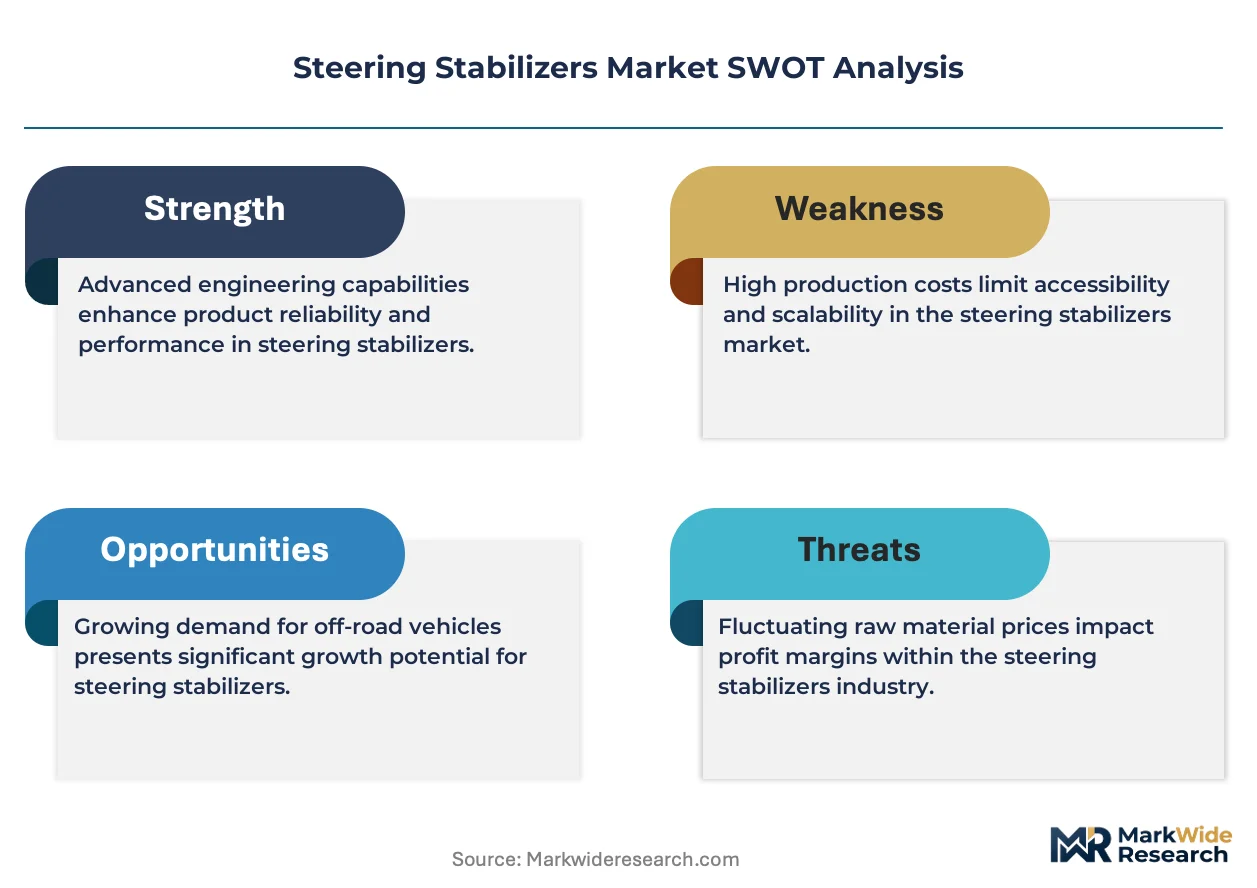
- Adjustable architecture demand:Lifted truck and overland vehicle builders drive tunable compression-rebound curve specifications, commanding margin premiums over fixed-valve units.
Market Restraints
- Steel-to-aluminum material transition costs:EPA fuel economy standards pressure OEMs toward lighter aluminum stabilizer bodies, requiring capital retooling at foundry and machining operations.
- Zhejiang foundry concentration:Shock absorber casting capacity centralization in China's Zhejiang province creates single-source vulnerability for monotube valve housings.
- Parasitic loss reduction mandates:Low-friction seal specifications under EPA tailpipe rules constrain traditional elastomer compound selections, limiting supplier flexibility.
Strategic Opportunities
- Software-defined calibration interfaces:ISO 26262 functional safety protocols governing electric power steering architectures create specification workflow openings for stabilizer-integrated actuator suppliers.
- Performance motorcycle segment:Adjustable stabilizer configurations for ATV and powersports applications remain underpenetrated relative to automotive attach rates.
- Overland vehicle builder channel:Direct-to-builder distribution bypassing traditional tier-1 supply contracts captures margin from premium adjustable kit demand.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 protocol implementation for steering actuator integration requires specialized firmware and systems engineering talent concentrated at tier-1 suppliers.
- Hardware-software specification friction:Tier-1 engineering departments face workflow compression as software-defined steering calibration interfaces reshape traditional damper tuning documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steering Stabilizers Market |
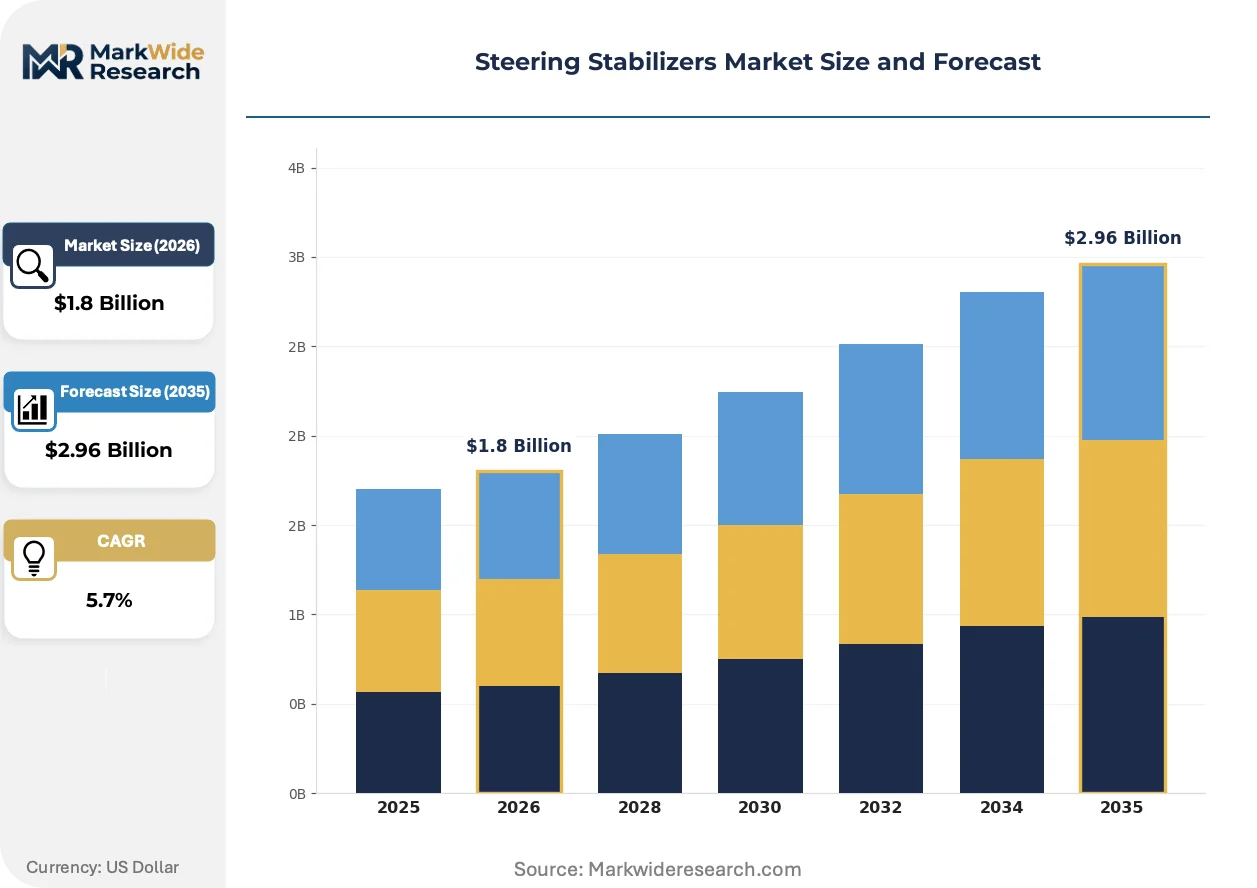
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stabilizers, Dual Stabilizers, Adjustable Stabilizers, Non-Adjustable Stabilizers Automotive Segment: PAS, EPS, Hydraulic Steering, Manual Steering End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Tenneco Inc., Öhlins Racing, Bilstein, Skyjacker, KYB Corporation, DRiV Inc., Pro Comp USA, Hyperpro Sales B.V., Rancho, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steering Stabilizers Market Evolving Landscape
Digital calibration protocols are displacing mechanical adjustment as the primary interface between stabilizer hardware and vehicle dynamics control systems. This shift compresses development cycles while expanding specification complexity for damping architecture suppliers.
Remote tuning interfaces for adjustable stabilizers are virtualizing the traditional shock dyno validation workflow. Overland vehicle builders and fleet operators adopt cloud-connected valve calibration to optimize compression-rebound curves across terrain profiles without physical shop visits. This capability is virtualizing aftermarket service revenue models toward subscription-based damping optimization.
NHTSA's FMVSS 126 electronic stability control mandates are constraining allowable steering damper hysteresis ranges for vehicles above gross vehicle weight ratings. OEMs must now document stabilizer response characteristics within ESC system validation protocols. Heavy light truck platforms face the steepest compliance burden, driving specification standardization across previously fragmented supplier bases.
Fleet procurement of dual stabilizer kits is consolidating around direct aftermarket channels rather than OEM dealer networks. Commercial and recreational vehicle operators in Texas and Arizona off-road clusters now source replacement hardware through specialized off-highway distributors. This channel rotation compresses traditional tier-1 aftermarket margins while expanding addressable volume for specialized stabilizer providers.
Steering Stabilizers Market Segmentation
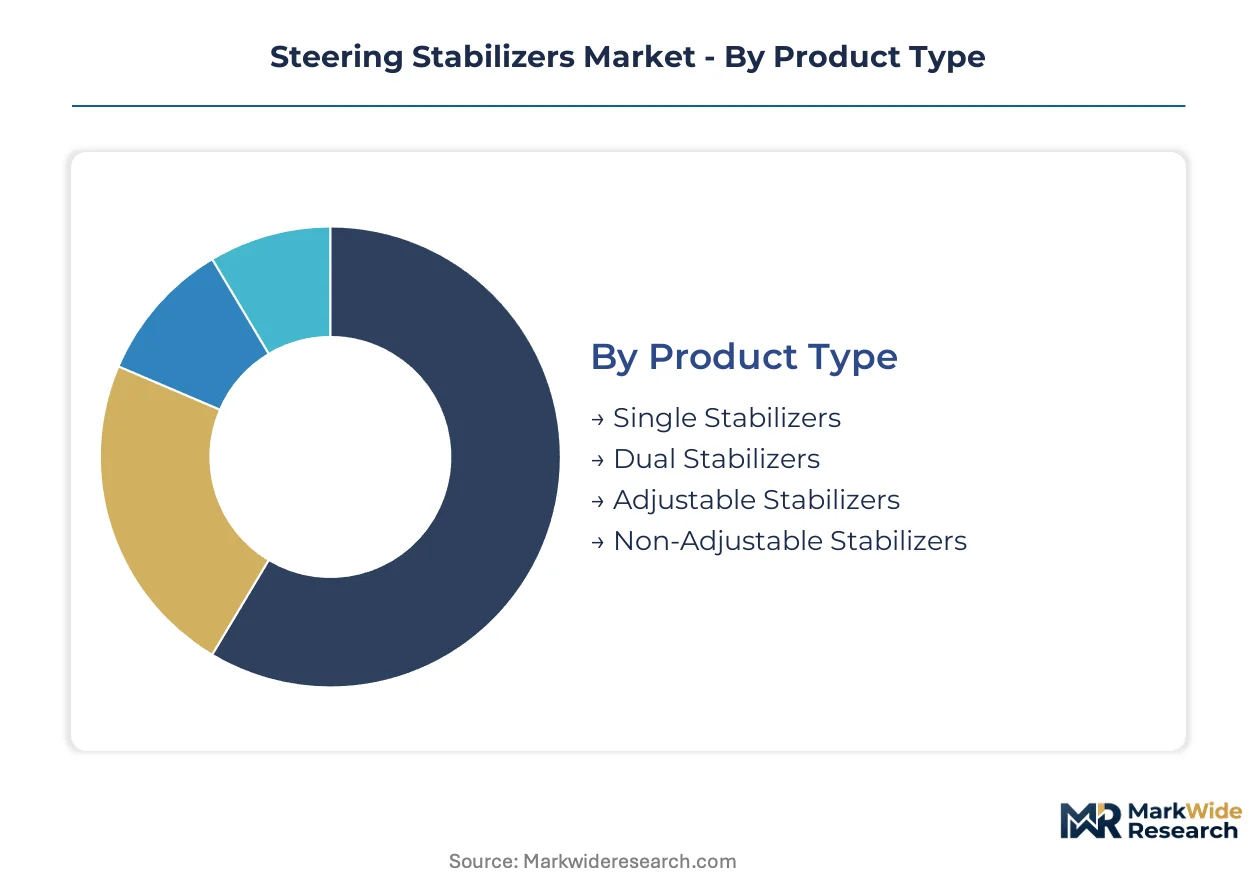
Stabilizer specification varies sharply across steering architectures and procurement channels. Product configuration, automotive integration type, and distribution pathway each dictate margin structures and compliance burdens for suppliers.
Product Type:
Use-case spectrum spans from baseline single units to tunable performance configurations.
- Dual Stabilizers:Paired damping units mounted in parallel configuration deliver amplified angular displacement resistance for solid-axle heavy trucks. Fleet operators in Texas and Arizona off-road clusters sustain replacement demand as these architectures attenuate bump steer in lifted suspension geometries.
- Adjustable Stabilizers:Valving permits compression-rebound curve tuning via external dial or remote interface. Overland vehicle builders command premium positioning for these units, with cloud-connected calibration now virtualizing traditional shock dyno workflows.
- Single Stabilizers:Baseline nitrogen-pressurized units address standard duty cycles in light truck and passenger car applications.
- Non-Adjustable Stabilizers:Fixed-valve configurations dominate high-volume OEM attach rates where specification standardization reduces validation overhead.
Established volume favors Non-Adjustable Stabilizers; emerging adoption favors Adjustable Stabilizers.
Automotive Segment:
Cost tier stratification separates legacy hydraulic architectures from electrified steering systems.
- EPS:Electric power steering architectures integrate stabilizer damping within software-defined calibration protocols. ISO 26262 functional safety requirements govern these integrations, compressing hardware specification workflows at tier-1 engineering departments.
- PAS:Power-assisted steering retains hydraulic pump infrastructure where stabilizer hardware maintains discrete mechanical mounting. Commercial vehicle fleets in aging truck populations sustain aftermarket procurement for these configurations.
- Hydraulic Steering:Full hydraulic architectures persist in off-highway and heavy-duty segments requiring maximum steering torque multiplication.
- Manual Steering:Unassisted linkages in recreational and vintage vehicle segments generate niche stabilizer demand through specialty aftermarket channels.
EPS architectures are climbing the fastest as electrification mandates reshape OEM platform strategies.
End User:
Customer type determines specification authority and validation burden distribution.
- Aftermarket Providers:Specialized distributors and direct-to-builder channels capture margin from premium adjustable kit demand. Fleet procurement of dual stabilizer kits is consolidating around these channels rather than OEM dealer networks.
- OEMs:Original equipment manufacturers impose FMVSS 126 compliance documentation requirements that constrain allowable damper hysteresis ranges. NHTSA mandate expansion to heavier light trucks tightens these thresholds.
- Tier-1 Suppliers:Integrated steering system providers face workflow compression as software-defined interfaces reshape traditional damper tuning documentation.
- Vehicle Assemblers:Contract manufacturers and niche builders source stabilizers through direct supply agreements bypassing traditional tier-1 contracts.
Aftermarket Providers are gaining share fastest as channel rotation compresses traditional tier-1 margins.
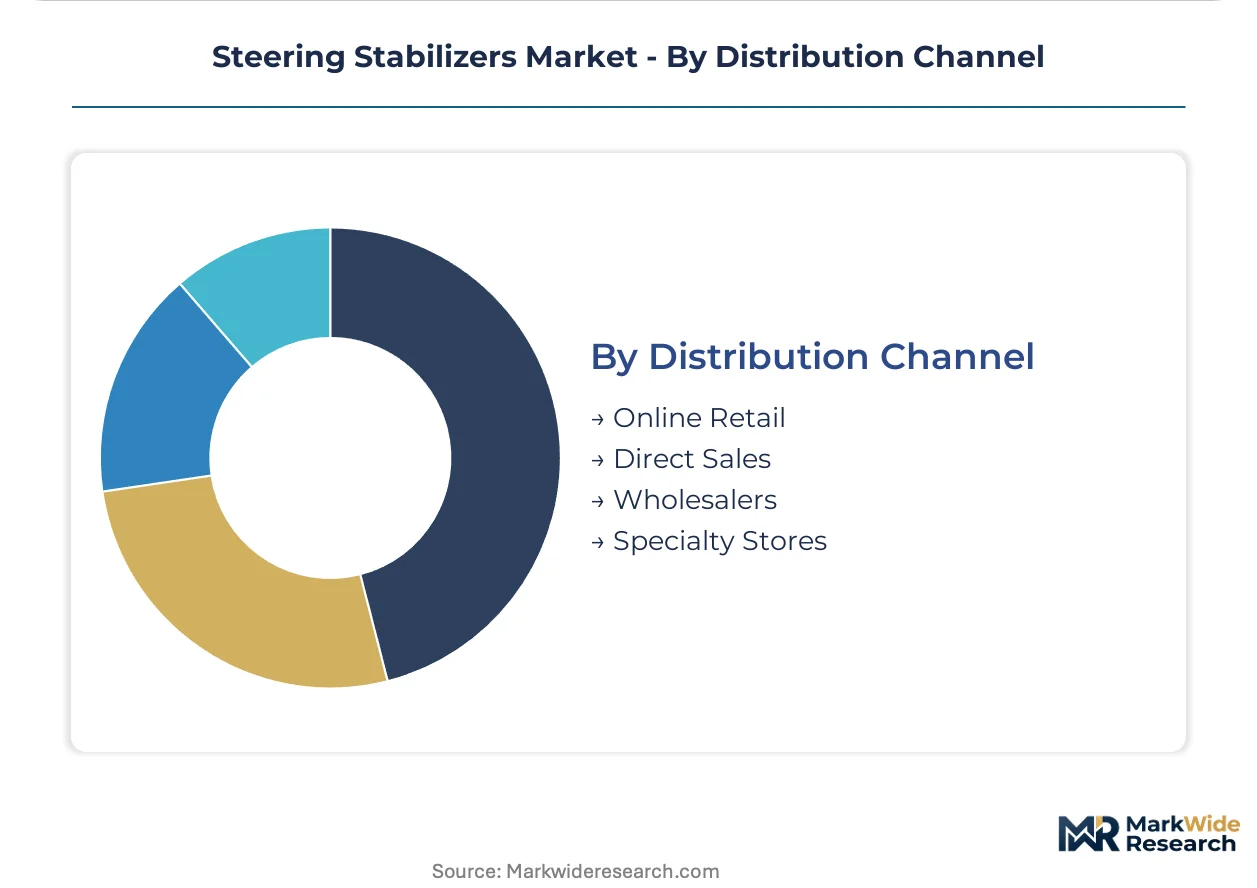
Distribution Channel:
Supply concentration varies from centralized e-commerce platforms to fragmented specialty retail.
- Direct Sales:Manufacturer-to-builder relationships capture premium positioning in overland and performance segments. Remote tuning interfaces enable subscription-based damping optimization revenue models.
- Specialty Stores:Off-highway distributors in Texas and Arizona clusters stock dual stabilizer kits for immediate fleet replacement cycles.
- Online Retail:E-commerce platforms aggregate standard single and non-adjustable unit demand from dispersed recreational vehicle owners.
- Wholesalers:Traditional parts distributors serve dealer network replenishment for OEM-specified replacement intervals.
Direct Sales commands the steepest expansion trajectory as builder-channel disintermediation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA's FMVSS 126 mandate expansion anchors North American demand, while Zhejiang foundry concentration and European electrification protocols reshape supply-side geography across the analysis window.
United States
Texas and Arizona off-road recreation clusters sustain elevated replacement rates for dual stabilizer kits among aging commercial fleets. NHTSA's updated FMVSS 126 coverage of heavier light trucks tightens steering system compliance thresholds for gross vehicle weight ratings previously exempt. The Southwest corridor from Houston to Phoenix anchors aftermarket procurement consolidation around specialized off-highway distributors.
China
Expanded shock absorber foundry capacity in Zhejiang province is rewriting competitive dynamics for monotube valve housing supply. MIIT industrial standards for automotive steering components pressure domestic suppliers toward ISO 26262-aligned functional safety protocols. The Yangtze River Delta manufacturing belt concentrates casting operations serving both domestic OEMs and export markets.
Germany
KBA vehicle type approval requirements for electronic stability control integration constrain steering damper specification windows in heavy commercial platforms. The EU Green Deal's embodied carbon tracking pressures Tier-1 suppliers toward aluminum body constructions over traditional steel. Baden-Württemberg's automotive engineering corridor hosts integrated steering system development for electrified architectures.
Japan
METI carbon neutrality roadmaps accelerate electric power steering platform transitions that reshape stabilizer integration requirements. JIS standards for automotive suspension components govern aftermarket replacement specifications in the domestic market. The Kanto manufacturing region around Tokyo anchors precision machining capacity for low-friction seal technologies.
India
PLI scheme incentives for automotive component manufacturing attract shock absorber assembly investments from multinational Tier-1 suppliers. BIS certification requirements for steering and suspension parts tighten quality thresholds for domestic aftermarket channels. Tamil Nadu's automotive component cluster near Chennai concentrates export-oriented production for Southeast Asian markets.
Steering Stabilizers Market Competitive Landscape
Integrated system suppliers and specialized damping architects split the market along technology-integration fault lines. Tenneco Inc. leverages captive monotube valve manufacturing to sustain cost positions in North American OEM supply chains. The vendor base organizes around three strategic archetypes: vertically integrated Tier-1 steering system providers, motorsport-derived performance specialists, and regional foundry-anchored volume manufacturers. Competitive moves concentrate on hardware-software calibration interface development and direct-to-builder channel disintermediation.
Within the performance-specialist tier, Öhlins Racing and Bilstein exemplify adjustable stabilizer architectures that extend from motorsport validation into premium aftermarket channels. KYB Corporation anchors Asian production scale through Zhejiang-affiliated foundry operations. These three occupy distinct competitive positions: Öhlins represents tunable configuration expertise for powersports applications, Bilstein exemplifies damping technology transfer from racing to consumer markets, and KYB sits within the volume-manufacturing archetype serving multi-regional OEM supply contracts.
| Leading Market Players |
|---|
| Tenneco Inc. |
| Öhlins Racing |
| Bilstein |
| Skyjacker |
| KYB Corporation |
| DRiV Inc. |
| Pro Comp USA |
| Hyperpro Sales B.V. |
| Rancho |
| Others |
Value Network & Pricing Analysis
Zhejiang foundry concentration for monotube valve housings feeds margin capture downstream at integrated Tier-1 suppliers with captive machining capacity. Pricing power pools with manufacturers controlling nitrogen gas seal specifications and remote calibration firmware.
Pricing Analysis
North American adjustable stabilizer kits command 40-60% premiums over Asian-sourced fixed-valve units. Three-tier pricing structure across premium adjustable, standard single-unit, and economy non-adjustable levels tracks certification grade and cloud-connectivity bundling. Cost compression in steel-to-aluminum body transitions is intensifying because EPA fuel economy mandates force retooling amortization. Fleet operators in Texas and Arizona off-road clusters show highest price sensitivity, while overland vehicle builders accept premium positioning for tunable compression-rebound architectures.
Supply Chain Analysis
Tariff exposure between China and North America dominates supply chain risk calculations for monotube valve housing procurement. Manufacturing gravity centers on Zhejiang province casting operations, German precision machining corridors, and Mexican assembly plants serving US OEMs. Raw material dependencies span nitrogen gas charging systems, low-friction elastomer compounds, and aluminum billet stock. Single-source vulnerability concentrates in Zhejiang shock absorber foundries serving KYB Corporation and export markets. Distribution runs through direct-to-builder channels, specialized off-highway distributors, and traditional tier-1 aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined steering calibration interfaces are transforming stabilizer hardware into platform-dependent ecosystem components, with ISO 26262 functional safety protocols governing interoperability specifications across electric power steering architectures.
For Market Incumbents: Build firmware integration moats around cloud-connected valve calibration protocols that virtualize traditional shock dyno workflows. Tenneco Inc. and Bilstein should deepen backward integration into nitrogen gas seal compound formulation to defend against Zhejiang foundry cost pressure. Capture direct-to-builder distribution relationships before channel disintermediation consolidates aftermarket procurement away from dealer networks. For New Entrants and Emerging Players: Pursue underpenetrated performance motorcycle and ATV adjustable stabilizer segments where motorsport-derived damping architectures command premium positioning. Target powersports OEM supply contracts in Baden-Württemberg and Kanto manufacturing regions where JIS and KBA validation requirements create specification barriers for volume manufacturers. Lead with remote tuning interface capabilities that enable subscription-based damping optimization revenue models. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive monotube valve manufacturing and ISO 26262-aligned functional safety engineering capacity. Long-term viability hinges on software-hardware calibration interface ownership as electric power steering platforms displace hydraulic architectures. Watch NHTSA FMVSS 126 mandate expansion timelines as the inflection signal for heavy light truck compliance-driven specification upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Calibration Interface Development | Cloud-connected valve tuning virtualizes shock dyno validation workflows for overland builders. |
| Direct-to-Builder Channel Establishment | Bypassing tier-1 contracts captures margin from premium adjustable kit procurement in Texas and Arizona. |
| ISO 26262 Functional Safety Certification | Electric power steering integration requirements compress specification workflows at engineering departments. |
| Aluminum Body Manufacturing Transition | EPA fuel economy mandates pressure OEMs toward lighter constructions requiring foundry retooling. |
| Dual Stabilizer Kit Portfolio Expansion | Fleet replacement cycles in off-highway segments sustain elevated aftermarket procurement volumes. |
Research Methodology
The analysis maps adjustable and non-adjustable stabilizer configurations, each validated through steering system engineers, aftermarket distributor procurement heads, and fleet maintenance directors. Primary interviews with OEM platform engineers, tier-1 supplier R&D leads, and off-highway vehicle builders combined with secondary validation against NHTSA FMVSS 126 documentation, EPA fuel economy rulemakings, and ISO 26262 protocol specifications. Bottom-up triangulation across product-type attach rates and top-down reconciliation against vehicle production databases anchored volume estimates.
Assumptions held fixed include NHTSA mandate expansion timelines and Zhejiang foundry capacity trajectories, while electric power steering penetration rates and cloud-connected calibration adoption curves were varied across sensitivity scenarios. Segmentation dimensions modeled span product type, automotive integration architecture, end-user procurement channel, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to technology transition patterns, with nitrogen gas pressure specification windows and valve response curve compliance burdens as industry-specific forecast inputs.
Sensitivities concentrate around NHTSA FMVSS 126 enforcement timing, Zhejiang supply disruption events, and electric power steering platform transition velocity. Forecasts reflect documented assumptions about regulatory trajectory and technology substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
Latin America Automotive Connectors Market
Vehicle Components
Sideloaders Market
Vehicle Components
Car Seat and Accessories Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
Injector Deposit-Resistant Fuel Injection Component Platforms Market
Vehicle Components
Automotive Sensors Market
Vehicle Components
Wheel Loaders Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Trailer Spindles Market
Vehicle Components
Canada Automotive Carbon Fiber Composites Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Global Bicycle Wheels Market