
 5th Wheel Hitches Market | 2026-2036
5th Wheel Hitches Market Size, Share, and Industry Trends Forecast 2026-2036
5th Wheel Hitches Market Insights
Maintenance subscription packages for electronic coupling monitoring is decoupling hardware sales from pure unit economics in the 5th wheel hitches space. SAF-HOLLAND leverages integrated telematics to anchor fleet service contracts across European and North American channels. B&W Trailer Hitches specializes in precision-machined steel assemblies that dominate premium consumer segments. JOST Werke extends its foundry-to-finished-product pipeline to control OEM pricing and delivery schedules for commercial vehicle manufacturers.
A 5th wheel hitch is a heavy-duty coupling device mounted in the bed of a pickup truck or tractor unit, featuring a kingpin receptacle plate typically rated from 15,000 to 30,000 pounds gross trailer weight, designed to distribute load directly over the rear axle for stable towing of semi-trailers, RVs, and equipment flatbeds. Fixed configurations remain the volume baseline for standard-wheelbase fleet trucks, while sliding variants capture the fastest growth as short-bed pickups proliferate among independent owner-operators needing cab clearance during tight maneuvering. Steel dominates material share due to fatigue resistance under cyclical loading, though aluminum gains traction in recreational applications where payload reduction justifies premium sourcing.
NHTSA Federal Motor Vehicle Safety Standards and FMCSA brake system regulations govern kingpin dimensions, locking mechanism integrity, and visibility requirements for interstate commerce in the United States. ISO 3842 and SAE J2638 provide dimensional and testing protocols that shape export compatibility and cross-border component acceptance. Stakeholders must monitor pending amendments to rear-underride guard rules and autonomous truck platooning standards, as both will redefine hitch load profiles and connectivity specifications.
Market Dynamics
Fleet telematics integration is redefining how 5th wheel hitches generate recurring revenue, shifting commercial buyers from capital expenditure cycles toward subscription-based coupling monitoring services.
Growth Catalysts
- NHTSA Trailer Safety Standards:Tightening kingpin dimension and locking mechanism requirements in the United States mandate hardware replacement cycles among interstate carriers.
- Short-bed pickup proliferation:Independent owner-operators purchasing compact trucks drive sliding hitch configurations for cab clearance during maneuvering.
- Steel fatigue resistance:Cyclical loading durability under heavy freight conditions sustains material preference in commercial fleet procurement specifications.
Market Restraints
- Aluminum substitution ceiling:Premium pricing for lightweight recreational hitches limits penetration in price-sensitive commercial segments.
- Foundry capacity concentration:OEM supply chains depend on concentrated North American and European casting facilities for precision-machined components.
- ISO 3842 dimensional rigidity:Export compatibility protocols constrain rapid design iteration for region-specific kingpin geometries.
Strategic Opportunities
- Autonomous truck platooning:Connectivity specifications for linked heavy-duty vehicles create demand for intelligent hitch load sensors and real-time coupling data.
- Rear-underride guard amendments:Pending NHTSA rule changes redefine load profile requirements, opening retrofit and redesign contracts.
- RV recreation aftermarket:Seasonal replacement cycles among recreational vehicle owners support dedicated distribution channels for premium consumer configurations.
Industry Challenges
- Telematics integration complexity:Fleet service contracts require seamless data handoff between hitch-mounted sensors and existing vehicle management platforms.
- SAE J2638 testing timeline:Validation protocols for new coupling designs extend product development cycles and compress launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5th Wheel Hitches Market |
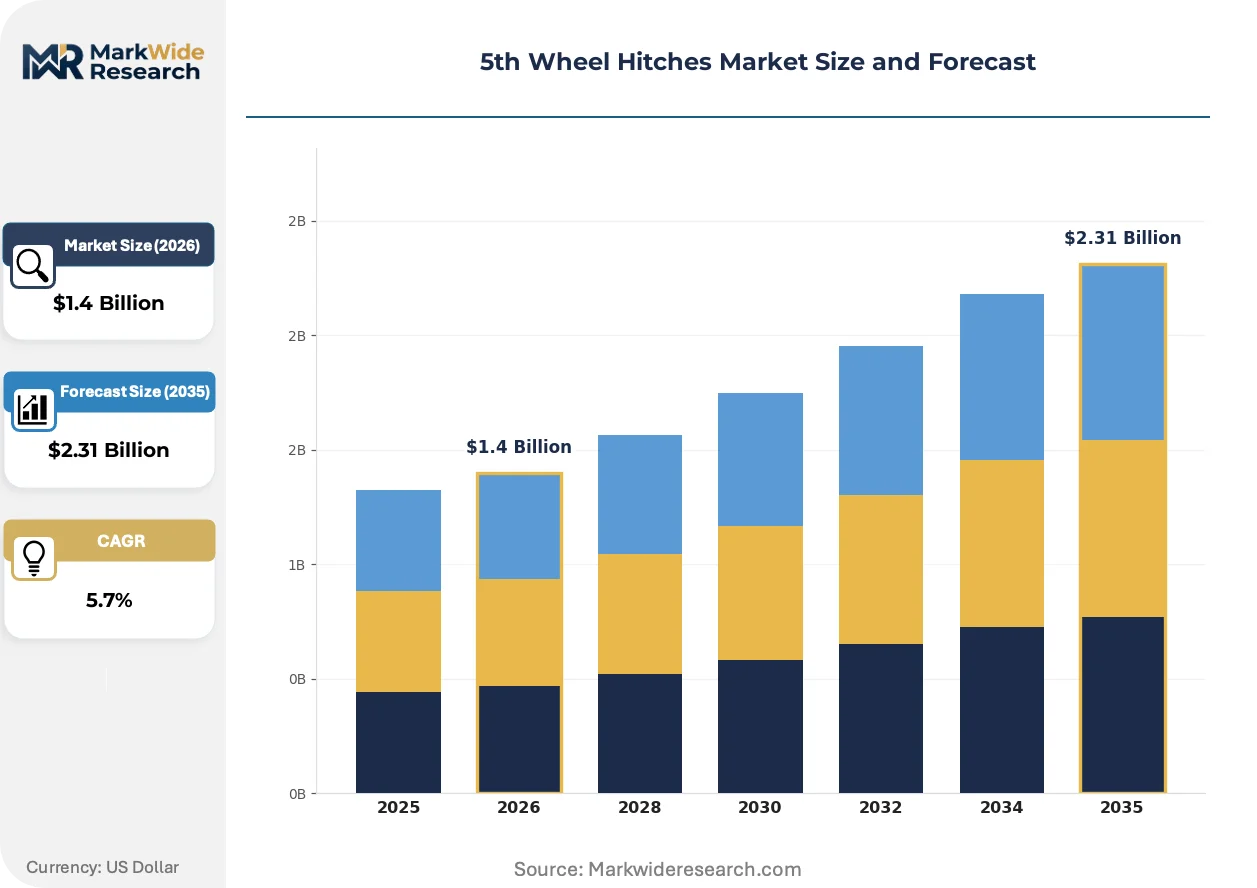
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Sliding, Release Lever, Sidewinder Material: Steel, Aluminum, Composite, Alloy Application: Recreational Vehicles, Commercial Transport, Agricultural Equipment, Construction Trailers End User: Fleet Operators, Independent Truckers, Rental Companies, Dealerships |
| Companies Covered | JOST Werke, SAF-HOLLAND, Fontaine Fifth Wheel, Lippert Components, B&W Trailer Hitches, CURT Manufacturing, Reese, Demco Products, Andersen Hitches, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5th Wheel Hitches Market Trends and Innovations
Electronic monitoring systems are penetrating 5th wheel hitches at accelerating rates, converting mechanical hardware into data-generating assets that anchor long-term service relationships.
Sensor-embedded coupling plates are converging with cloud-based fleet management platforms. Heavy-duty carriers in the United States adopt these configurations to track kingpin wear, locking integrity, and load distribution in real time. This convergence is compressing the traditional replacement cycle toward predictive maintenance triggers.
FMCSA brake system regulations now mandate enhanced visibility and locking mechanism documentation for interstate commerce. Commercial vehicle inspectors enforce these provisions through roadside verification protocols. Fleet operators respond by standardizing on hitches with integrated compliance logging capabilities.
After-sales service unbundling separates hardware procurement from monitoring subscriptions. Independent owner-operators purchase base mechanical units through retail channels while activating telematics features through separate fleet software providers. This bifurcation is most visible in the United States, where long-haul freight density justifies distributed service networks.
5th Wheel Hitches Market Segmentation
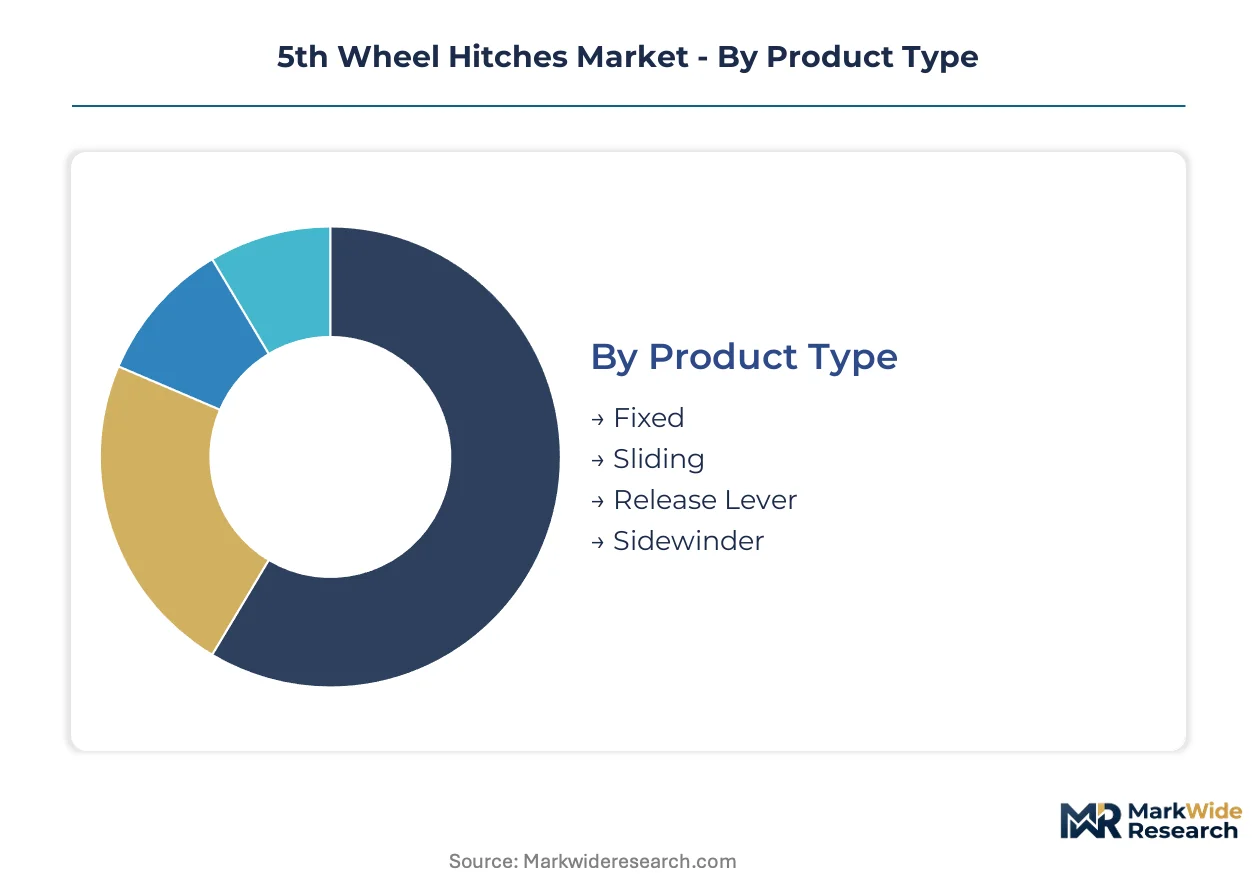
Segmentation in the 5th wheel hitches market reflects divergent engineering priorities between commercial freight operators seeking durability cycles and recreational users optimizing for payload flexibility. Product configuration, material selection, and end-use application each create distinct procurement channels with separate pricing architectures and replacement cadences.
Product Type:
Customization intensity varies sharply across this category, from standardized fixed mounts for fleet standardization to highly configurable sliding mechanisms addressing individual cab-clearance requirements.
- Fixed:Stationary kingpin receptacle plates welded or bolted to truck bed frames, rated typically from 15,000 to 30,000 pounds gross trailer weight. Fleet operators in the United States specify these for long-haul freight tractors where wheelbase consistency eliminates clearance concerns, with NHTSA brake regulations reinforcing replacement cycles through mandatory locking mechanism inspections.
- Sliding:Rail-mounted hitch assemblies allowing 10-24 inches of fore-aft travel to prevent trailer-to-cab contact during tight maneuvering. Independent owner-operators purchasing short-bed pickups from Detroit manufacturers drive concentration here, as compact truck proliferation in the consumer channel creates structural demand for cab-clearance solutions.
- Release Lever:Manual or assisted uncoupling mechanisms reducing operator physical strain during trailer detachment. Rental companies prioritize these for driver safety liability reduction.
- Sidewinder:Pin box replacement systems shifting pivot point rearward of truck axle, eliminating sliding rail weight. RV owners towing with short-bed configurations favor this for bed space preservation.
Leading the category by volume: Fixed configurations anchor fleet procurement. Growing fastest: Sliding variants gain share as compact truck penetration climbs.
Material:
Cost tier stratification separates commodity steel procurement at scale from premium lightweight alternatives commanding margin premiums in recreational channels.
- Steel:High-tensile alloy formulations delivering fatigue resistance under cyclical loading across millions of duty cycles. Commercial transport operators in the United States specify steel assemblies exclusively, with FMCSA roadside enforcement protocols validating material traceability through SAE J2638 documentation requirements.
- Aluminum:Extruded and cast alloys reducing hitch weight by 40-50 percent versus steel equivalents. Recreational vehicle owners in coastal states favor these for corrosion resistance and payload capacity recovery.
- Composite:Fiber-reinforced polymer structures with metal load-bearing inserts. Specialty agricultural equipment trailers test these for chemical exposure resistance.
- Alloy:Hybrid material combinations blending steel strength with aluminum weight reduction. Premium consumer segments experiment here for performance differentiation.
Dominant by procurement volume: Steel formulations. Expanding most quickly: Aluminum configurations in recreational applications.
Application:
Customer type fragmentation separates seasonal retail replacement from continuous-duty commercial specifications with divergent warranty and service attachment rates.
- Recreational Vehicles:Fifth-wheel travel trailers and toy haulers requiring 15,000-25,000 pound rated hitches with aesthetic finish requirements. Dealerships in the United States cluster demand geographically around retirement migration corridors, with aftermarket replacement cycling tied to seasonal usage patterns rather than mileage accumulation.
- Commercial Transport:Semi-trailer tractors in interstate freight service demanding 30,000+ pound ratings with integrated telematics compatibility. Fleet operators standardize on SAE J2638-validated configurations to satisfy FMCSA brake system documentation mandates.
- Agricultural Equipment:Grain and livestock trailers operating in corrosive environments with seasonal intensity. Equipment dealers specify enhanced coating systems.
- Construction Trailers:Equipment flatbeds and dump trailers requiring rapid coupling cycles. Rental yards prioritize release lever integration for operator efficiency.
Highest shipment volume: Commercial transport specifications. Steepest expansion trajectory: Recreational vehicle configurations.
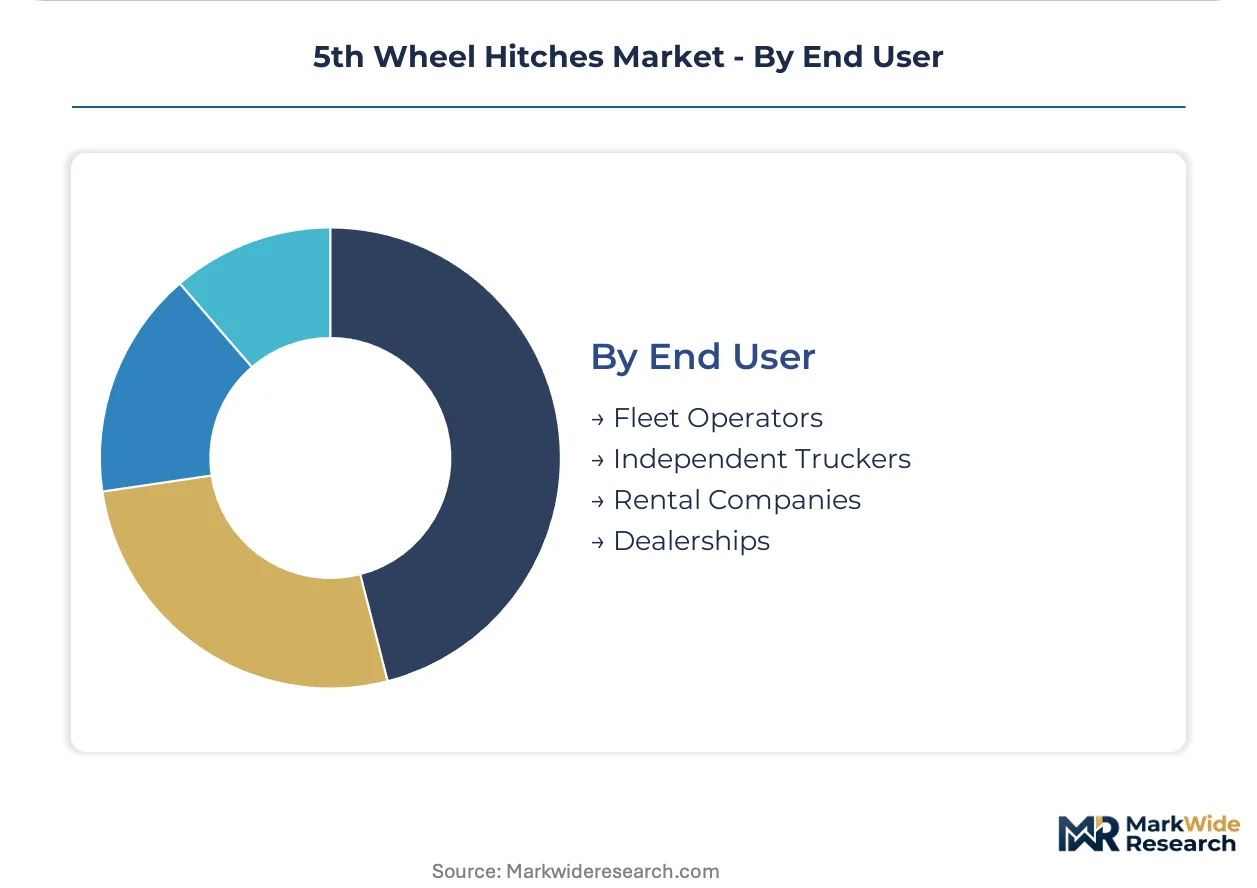
End User:
Procurement authority concentration distinguishes centralized fleet technical specifications from fragmented individual purchasing decisions with divergent price sensitivity profiles.
- Fleet Operators:National and regional trucking companies with centralized procurement departments negotiating multi-year supply agreements. These buyers in the United States integrate hitch specifications with telematics platform requirements, converting hardware procurement into subscription-anchored service relationships.
- Independent Truckers:Owner-operators purchasing through retail channels with individual credit financing. Short-bed pickup proliferation drives sliding hitch preference among this segment for residential maneuvering flexibility.
- Rental Companies:National equipment rental chains standardizing across mixed fleets for maintenance simplification. These buyers prioritize release lever configurations for driver accessibility compliance.
- Dealerships:RV and truck retailers bundling hitches with new vehicle sales. Seasonal sales patterns concentrate demand in spring preparation months.
Controlling largest procurement volume: Fleet operators with centralized technical specifications. Gaining share fastest: Independent truckers as compact truck sales accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and the United States, while consumption pulls strongest from American long-haul corridors and European freight networks. Foundry operations in industrial clusters supply precision-machined components to assembly plants near Detroit and Stuttgart. Emerging demand surfaces in Australian mining regions and Canadian resource extraction zones.
United States
Long-haul freight density and RV recreation sustain replacement cycles across interstate corridors. NHTSA trailer safety standards and FMCSA brake regulations tighten coupling requirements and mandate hardware documentation. The Detroit-Warren automotive cluster anchors OEM supply relationships with precision machining facilities supplying kingpin assemblies.
Germany
Commercial vehicle manufacturers in Baden-Württemberg and Lower Saxony drive OEM procurement for heavy-duty tractor configurations. KBA type-approval processes enforce ISO 3842 dimensional compliance for export-bound components. The Stuttgart industrial region hosts foundry-to-finished-product pipelines controlling delivery schedules for European fleet operators.
Canada
Resource extraction and agricultural equipment trailers generate seasonal demand spikes across prairie provinces. Transport Canada CMVSS regulations align with SAE J2638 testing protocols for cross-border component acceptance. Alberta's oil sands logistics corridors concentrate heavy-haul specifications requiring 30,000+ pound rated assemblies.
Australia
Mining equipment trailers and remote infrastructure projects drive demand for fatigue-resistant steel configurations in Western Australia and Queensland. The country's national transport regulator enforces ADR 62 coupling standards for heavy vehicle combinations. Perth-based equipment dealers specify enhanced coating systems for corrosive operating environments.
Mexico
Cross-border freight growth and nearshoring manufacturing expansion pull sliding hitch configurations for short-bed pickup fleets. NOM-012-SCT standards govern dimensional requirements for commercial vehicle combinations. The Nuevo León automotive corridor integrates with Texas-based distribution networks for aftermarket volume.
5th Wheel Hitches Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing models. The vendor base clusters around three strategic tiers: integrated foundry operators controlling upstream casting capacity, precision-machining specialists serving premium consumer channels, and assembly-focused fabricators sourcing components from distributed supplier networks. Consolidation pressures favor backward integration into captive supply of kingpin assemblies and locking mechanisms. Geographic expansion into Australian mining corridors and Canadian resource zones represents the dominant competitive move alongside telematics platform partnerships.
Among German-based industrial groups, JOST Werke and SAF-HOLLAND occupy positions anchoring OEM supply relationships through foundry-to-finished-product control. These entities exemplify the integrated production archetype. B&W Trailer Hitches represents the precision-machining specialist tier, sitting within premium consumer distribution channels that emphasize steel assembly quality. The competitive structure rewards entities that can bridge commercial fleet telematics requirements with recreational aftermarket accessibility.
| Leading Market Players |
|---|
| JOST Werke |
| SAF-HOLLAND |
| Fontaine Fifth Wheel |
| Lippert Components |
| B&W Trailer Hitches |
| CURT Manufacturing |
| Reese |
| Demco Products |
| Andersen Hitches |
| Others |
Pricing and Supply Chain Analysis
Precision-machining labor pools in the Detroit-Warren corridor and Stuttgart industrial region create cost-tier spreads that separate premium consumer configurations from commodity fleet specifications. Wage differentials between these specialized foundry clusters and assembly-focused fabricators in Mexico and Eastern Europe directly shape three-tier pricing stratification across the 5th wheel hitches market.
Pricing Analysis
Margin tightening in economy-tier fixed configurations reflects steel alloy spot volatility and foundry capacity bottlenecks. Three-tier pricing structure across premium, standard, and economy levels separates SAE J2638-validated commercial assemblies from recreational aluminum variants and unbranded import alternatives. Cost-down pressure on standard-tier products accelerates because fleet operators consolidate procurement volumes through multi-year supply agreements. Independent owner-operators exhibit highest price sensitivity, while national fleet operators prioritize certification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from FMCSA-regulated fleet operators mandate qualified supplier redundancy across North American and European foundry networks. Kingpin assembly production draws from concentrated casting capacity in Germany, the United States, and Mexico. High-tensile steel alloys, precision-machined locking mechanisms, and corrosion-resistant coating systems constitute critical input dependencies. Single-source vulnerability around German foundry-to-finished-product pipelines threatens OEM delivery schedules. Distribution runs through direct fleet supply agreements, RV dealership networks, and aftermarket retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market hinges on backward integration into captive kingpin foundry capacity and telematics platform anchoring, with first-mover advantage accruing to players controlling both hardware production and recurring service revenue streams.
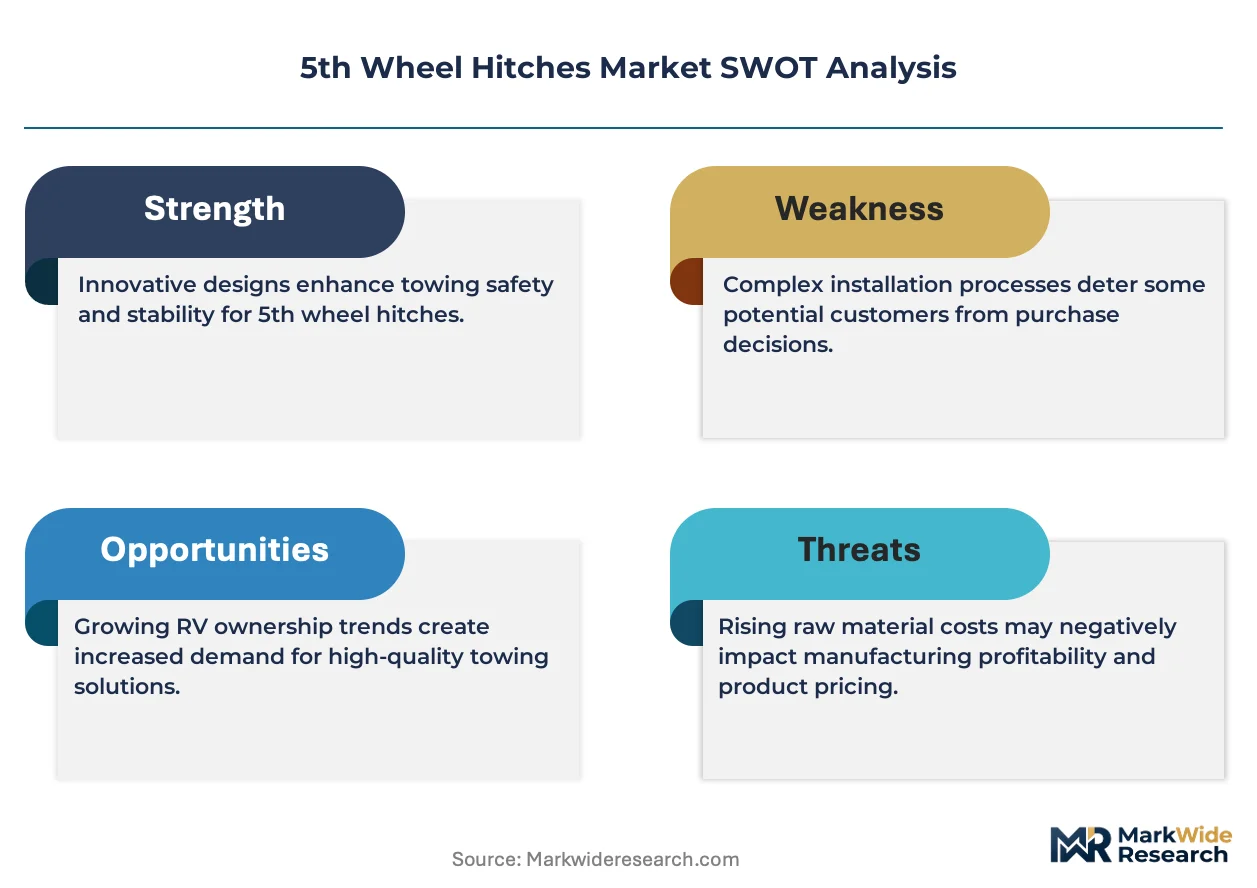
For Market Incumbents: Deepen foundry-to-finished-product control over precision-machined components to defend against aluminum substitution threats in recreational segments. Anchor fleet service contracts through integrated electronic coupling monitoring that locks in multi-year subscription revenue. Prioritize SAE J2638 certification investments to maintain technical barriers against low-cost import competition. For New Entrants and Emerging Players: Begin with sliding hitch configurations for short-bed pickup proliferation among independent owner-operators, the most penetrable segment lacking entrenched supplier relationships. Target aftermarket retail channels in Australian mining corridors and Canadian resource extraction zones where geographic incumbency remains weak. Pursue telematics-agnostic hardware positioning that integrates with existing fleet management platforms rather than competing for platform dominance. For Investors and Strategic Acquirers: Re-rating potential sits with precision-machining specialists possessing SAE J2638 validation and established RV dealership distribution, given subscription revenue attachment rates expanding across commercial transport. Long-term viability over the projection horizon favors targets with demonstrated foundry capacity and telematics partnership pipelines. Watch FMCSA autonomous truck platooning rulemaking as the inflection signal for intelligent hitch sensor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Foundry Capacity | Controls kingpin assembly pricing and delivery schedules for OEM supply agreements. |
| Telematics Platform Partnership | Converts hardware sales into recurring fleet service contracts with multi-year visibility. |
| SAE J2638 Certification Investment | Maintains technical compliance barriers against unvalidated import competition. |
| Geographic Expansion into Mining Corridors | Captures Australian and Canadian demand for fatigue-resistant steel configurations. |
| Sliding Hitch Configuration Development | Addresses short-bed pickup proliferation among price-sensitive independent operators. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fleet procurement directors, RV dealership operators, foundry production managers, and aftermarket distribution specialists. NHTSA safety standard amendments, FMCSA brake system documentation requirements, and ISO 3842 dimensional protocols provided regulatory validation anchors. Bottom-up shipment data from precision-machining facilities combined with top-down freight equipment production estimates to establish market sizing boundaries.
Granularity-level modeling addressed product type, material formulation, application segment, and end-user procurement authority across the projection horizon. Fixed, sliding, release lever, and sidewinder configurations were modeled separately with distinct replacement cycle assumptions. Steel, aluminum, composite, and alloy material tiers carried differentiated pricing architectures. CAGRs derived from historical fleet expansion patterns, RV shipment correlations, and regulatory replacement cycle mandates. Telematics penetration curves and autonomous truck platooning readiness served as industry-specific demand modifiers.
Underlying measurement precision varies by segment; commercial transport specifications carry tighter precision than recreational vehicle configurations due to consolidated procurement visibility. Forecasts reflect assumptions around NHTSA rulemaking timelines, foundry capacity expansion, and steel alloy cost trajectories. Deviation in FMCSA autonomous vehicle regulations or rear-underride guard amendments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Engine Components Market
Vehicle Components
Gas Station Equipment Market
Vehicle Components
Electric Wheelbarrow Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Engine Valve Market
Vehicle Components
Trailer Terminal Tractor Market
Vehicle Components
Rear Axle Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Latin America Two-Wheeler Components Market
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Electric Forklifts Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Transmission Components Market