
 Global Navigation Lighting Market | 2026-2036
Global Navigation Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Navigation Lighting Market Outlook
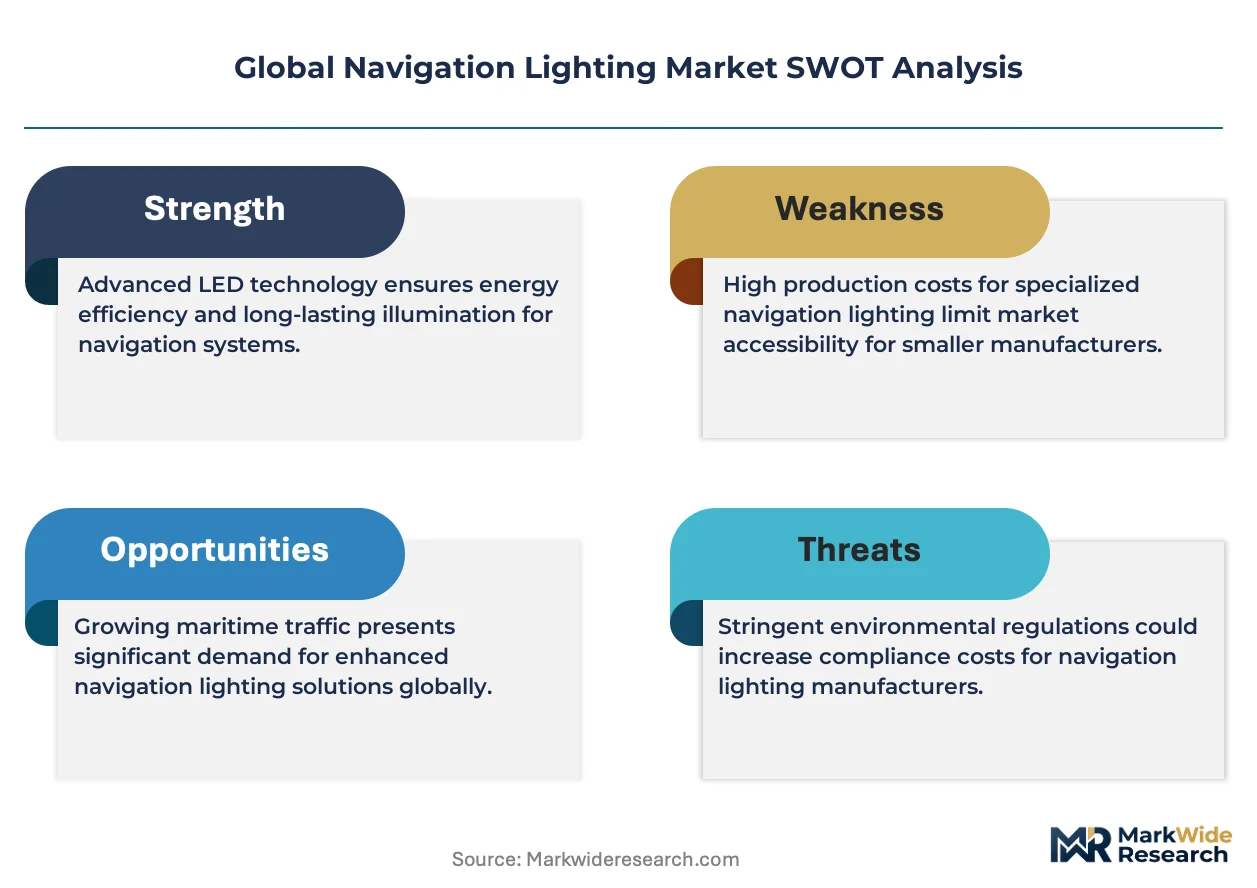
Marine-grade IP67 certification is redrawing procurement benchmarks across the Global Navigation Lighting Market. Glamox AS leverages its Nordic manufacturing heritage to dominate Arctic vessel retrofit programs. Hella Marine sustains technology leadership through specialized optical engineering for superyacht segments. Aveo Engineering Group differentiates via FAA-certified aviation obstruction lighting systems for wind energy towers.
Global Navigation Lighting encompasses luminous signaling devices engineered to emit specified candela intensities, color temperatures, and flash characteristics compliant with International Maritime Organization and ICAO photometric standards; these systems employ precision optics, corrosion-resistant housings, and regulated power drivers to ensure continuous visibility under adverse weather and electromagnetic conditions. LED product types now command the dominant margin pool as port authorities and airport operators phase out xenon and incandescent sources under energy mandates. Smart lighting technology is expanding fastest as remote monitoring and automated fault detection reduce maintenance sorties for offshore platforms and remote airfields.
The US FAA mandates specific intensity classes for airport approach and runway edge systems, while the EU's Ecodesign Directive phases out inefficient fluorescent marine lanterns; China's CAAC enforces domestic certification parallel to ICAO Annex 14 for all imported airfield lighting. Stakeholders must monitor divergence between national certification timelines and component sourcing constraints as dual-compliance inventories strain working capital.
Market Dynamics
ICAO's Annex 14 aerodrome standard revisions are forcing synchronized LED retrofits across commercial aviation and offshore energy infrastructure, compressing replacement cycles and redrawing supplier qualification criteria.
Growth Catalysts
- China CAAC Certification Mandates:Domestic airport construction under the 14th Five-Year Transport Plan requires ICAO-compliant LED approach lighting, pulling procurement volumes toward certified suppliers.
- EU Ecodesign Directive Phase-Out:Inefficient fluorescent marine lanterns face mandatory retirement, accelerating harbor authority capital programs for LED vessel navigation systems.
- Offshore Platform Electrification:North Sea and Gulf of Mexico wind farm installations require aviation obstruction lighting for turbine arrays, creating parallel demand streams from energy infrastructure.
Market Restraints
- Aluminum Alloy Input Volatility:Marine-grade IP67 housings depend on corrosion-resistant aluminum castings, exposing manufacturers to London Metal Exchange price swings and foundry capacity constraints in Norway and Germany.
- Dual-Compliance Inventory Strain:Suppliers must stock separate FAA-certified and CAAC-certified driver assemblies, doubling working capital requirements for China-bound shipments.
- Optical Component Concentration:Precision Fresnel lenses and collimator assemblies concentrate among Japanese and German specialty glassworks, creating single-source vulnerabilities.
Strategic Opportunities
- India Regional Airport Buildout:The UDAN scheme targets 100 underserved airfields with upgraded lighting infrastructure, opening procurement channels outside saturated Chinese and North American markets.
- Remote Monitoring Convergence:Integration of IoT sensors with LED drivers enables predictive maintenance for Arctic shipping lanes and Pacific island airfields, unbundling hardware from service contracts.
- South Korean Offshore Wind Incentives:METI-aligned renewable energy subsidies for Yellow Sea wind farms include aviation lighting as eligible capex, redirecting supplier attention toward East Asian energy developers.
Industry Challenges
- Photometric Calibration Talent Scarcity:ICAO and IMO compliance requires certified photometric laboratories, with qualified technicians concentrated in France, Germany, and the United States.
- Legacy Incandescent Integration:Airfield operators maintaining mixed LED-xenon fleets face interoperability failures in series circuit configurations, demanding custom isolation transformers.
- FAA TSO Certification Timelines:Technical Standard Order approval for new LED intensity classes averages 18-24 months, delaying product launches behind competitor windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Navigation Lighting Market |
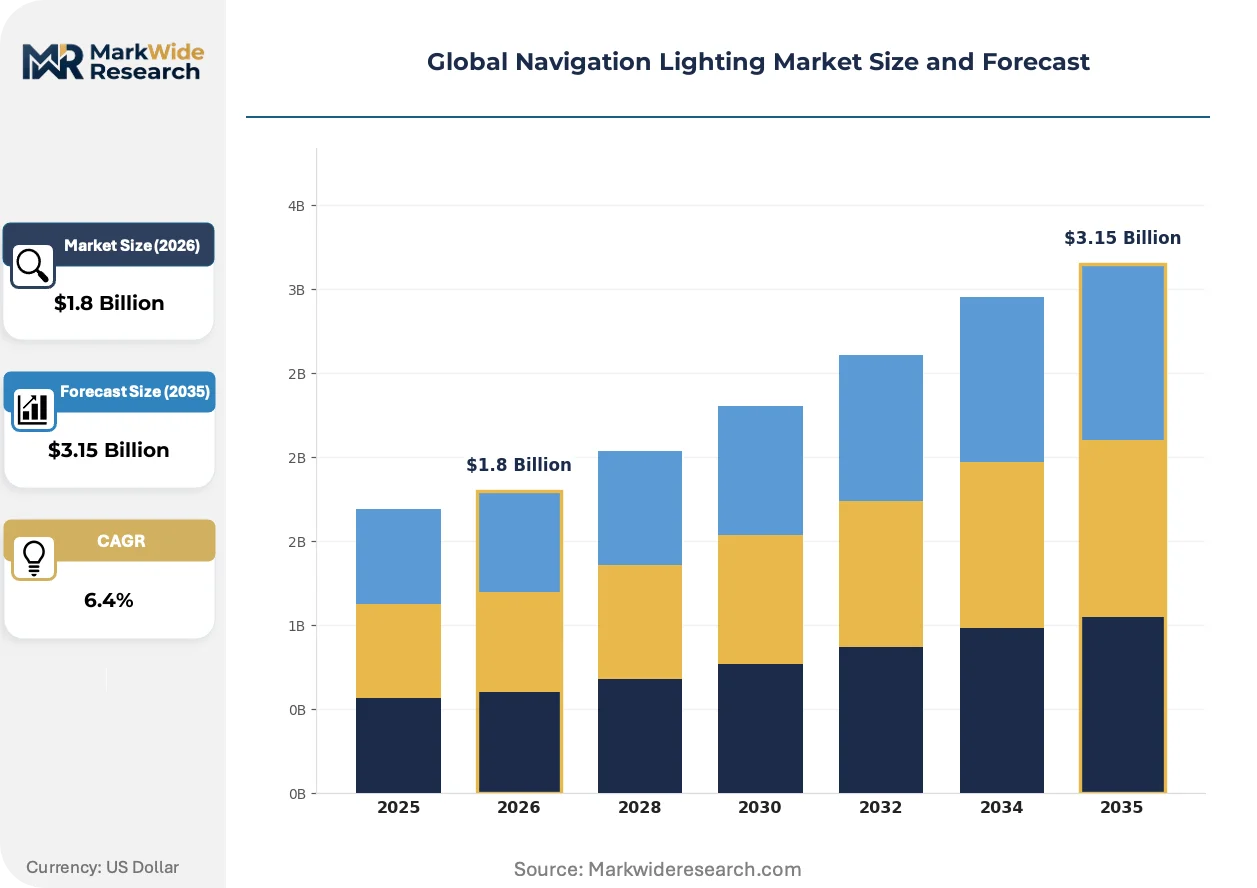
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Xenon, Incandescent, Fluorescent End User: Aviation, Marine, Roadway, Industrial Technology: Solar-Powered, Smart Lighting, Conventional, Hybrid Installation Type: Surface-Mounted, Pole-Mounted, Embedded, Portable |
| Companies Covered | Glamox AS, Hella Marine, Aveo Engineering Group, Perko Inc., Den Haan Rotterdam, FAMOR S.A., TRANBERG, Canepa & Campi, Lutron Electronics Co., Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Navigation Lighting Market Strategic Shifts
Solid-state lighting architectures are compressing maintenance intervals while digital control protocols enable centralized airfield management, shifting value capture from hardware sales toward system integration and remote diagnostics.
Multi-die LED arrays with independent thermal management are supplanting single-source xenon flash tubes in high-intensity obstruction applications. Offshore wind developers in the North Sea and Taiwan Strait have standardized on these solid-state systems for turbine marking. The technology is supplanting legacy gas-discharge inventory across European and Asia-Pacific renewable energy portfolios, collapsing relamping schedules from annual to decadal cycles.
REACH Annex XVII restrictions on mercury-containing lamps entered full enforcement for marine navigation equipment in 2024. Shipowners operating EU-flagged vessels must now document LED conversion timelines or face port state control detention. German and Dutch maritime insurers have begun premium adjustments based on compliance certification status, transferring regulatory burden directly to fleet operating economics.
Harbor masters and airport operations directors now specify outcome-based availability contracts rather than unit purchase orders. Danish and Singaporean port authorities lead this shift, penalizing suppliers for luminous failure events rather than rewarding equipment delivery. The model compresses supplier margins while extending contract tenures, most visible in long-term concession agreements for Baltic and Malacca Strait vessel traffic services.
Global Navigation Lighting Market Segmentation
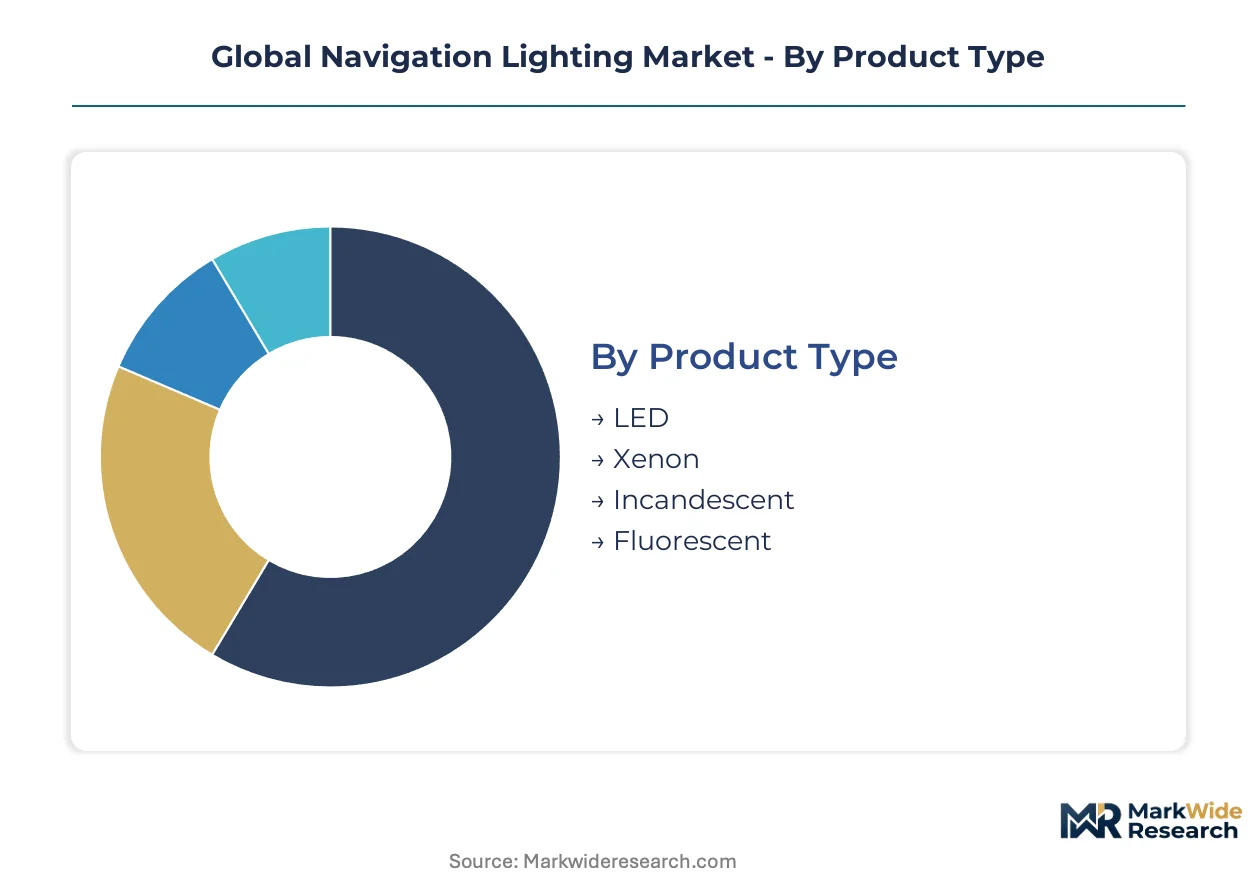
Navigation lighting procurement splits across four structural dimensions, each carrying distinct regulatory burdens and lifecycle economics. Product type determines energy compliance exposure, while installation geometry constrains retrofit feasibility for legacy infrastructure.
Product Type:
LED substitution pressure is most acute against xenon and incandescent inventory, driven by ICAO intensity mandates and EU Ecodesign Directive phase-outs that collapse total cost of ownership calculations.
- LED:Multi-die arrays with independent thermal management deliver specified candela outputs across -40°C to +55°C operating envelopes. Chinese airport construction under CAAC certification requirements and North Sea wind farm aviation marking specifications concentrate procurement volumes here.
- Xenon:Gas-discharge flash tubes retain installed base in high-intensity obstruction applications requiring extreme peak outputs. Mixed-fleet interoperability demands and 18-24 month FAA TSO certification timelines for LED replacements sustain residual demand in US airfield approach systems.
- Incandescent:Tungsten-halogen sources persist in cost-constrained regional airfields with minimal flight movements.
- Fluorescent:Marine lantern applications face REACH Annex XVII mercury restrictions, forcing accelerated retirement across EU-flagged vessel fleets.
LED anchors the volume base while xenon gains share at the steepest rate among legacy categories as operators defer capital conversion.
End User:
Application-specific photometric standards create divergent procurement cycles, with aviation and marine segments operating under distinct international regulatory frameworks.
- Aviation:Runway edge, approach, and taxiway systems must comply with ICAO Annex 14 candela specifications and FAA TSO intensity classes. Chinese regional airport buildout and Indian UDAN scheme infrastructure commitments concentrate near-term demand.
- Marine:Vessel navigation lanterns and harbor entry lighting operate under IMO Colregs photometric requirements. Arctic vessel retrofit programs and Malacca Strait traffic services drive specification intensity for IP67-rated housings.
- Roadway:Bridge marking and highway obstruction lighting follows national transport authority standards with lower specification stringency.
- Industrial:Chimney, cooling tower, and stack marking for petrochemical and power generation facilities.
Aviation commands the revenue concentration while marine expands most quickly as fleet renewal cycles compress.
Technology:
Power architecture selection determines maintenance economics and remote operability, with solar and smart configurations displacing conventional grid-dependent systems in inaccessible locations.
- Solar-Powered:Photovoltaic panels with battery storage eliminate grid connection requirements for Pacific island airfields and offshore platform applications. South Korean Yellow Sea wind farm subsidies include solar-integrated aviation lighting as eligible capex.
- Smart Lighting:IoT-enabled drivers with automated fault detection and predictive maintenance algorithms. Danish and Singaporean port authorities specify outcome-based availability contracts penalizing luminous failure events.
- Conventional:Hardwired AC systems with manual monitoring protocols.
- Hybrid:Grid-primary with solar backup for critical redundancy in severe weather corridors.
Conventional retains the installed base dominance while smart lighting climbs the fastest as remote monitoring converges with LED driver architectures.
Installation Type:
Physical mounting geometry constrains retrofit feasibility and determines labor intensity for infrastructure upgrade programs.
- Surface-Mounted:Flush-deck fixtures for helipad touchdown zones and vessel bridge wings. Arctic shipping lane icebreaker retrofits and superyacht newbuild specifications concentrate demand for marine-grade aluminum castings.
- Pole-Mounted:Elevated assemblies for runway approach masts and wind turbine nacelle marking. Taiwan Strait and North Sea offshore wind standardization drives volume for adjustable-intensity LED arrays.
- Embedded:In-pavement fixtures for runway centerline and taxiway edge applications requiring load-bearing housings.
- Portable:Battery-operated temporary systems for construction zones and emergency airfield activation.
Pole-mounted fixtures anchor the volume base while embedded systems gain share fastest as concrete pavement reconstruction cycles align with LED conversion timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in navigation lighting equipment tilt toward deficit positions in countries with aggressive airport modernization timelines, while surplus capacity concentrates in Nordic and German manufacturing clusters serving Arctic marine retrofit programs.
United States
FAA Technical Standard Order certification requirements drive domestic procurement toward established suppliers with approved LED intensity classes. The Infrastructure Investment and Jobs Act directs federal aviation funds toward runway edge system replacements at regional airfields. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate MRO demand for approach lighting upgrades as passenger volumes recover.
China
CAAC domestic certification mandates parallel to ICAO Annex 14 standards redirect import flows toward dual-compliant inventory stocking. The 14th Five-Year Transport Plan commits capital to regional airport networks in western provinces. Chengdu and Xi'an manufacturing zones host assembly operations for pole-mounted LED arrays serving domestic wind farm aviation marking specifications.
Germany
EU Ecodesign Directive enforcement phases out fluorescent marine lanterns across Hamburg and Bremen port authorities. REACH Annex XVII mercury restrictions entered full effect for vessel navigation equipment in 2024. The country's national maritime regulator coordinates with Dutch and Danish harbor masters on standardized LED conversion timelines for Baltic Sea traffic corridors.
Norway
Arctic vessel retrofit programs concentrate demand for IP67-rated marine housings resistant to icebreaker operational conditions. Glamox AS leverages domestic manufacturing heritage to capture polar shipping lane specifications. Bergen and Stavanger industrial zones supply corrosion-resistant aluminum castings for offshore platform aviation obstruction systems in the North Sea.
India
The UDAN regional connectivity scheme targets 100 underserved airfields with upgraded lighting infrastructure under Ministry of Civil Aviation directives. State governments in Maharashtra and Karnataka compete for maintenance hub status. Mumbai and Delhi procurement offices evaluate LED approach systems against total cost of ownership metrics incorporating grid reliability constraints.
Global Navigation Lighting Market Competitive Environment
Listed leaders compete with private specialists across certification-intensive segments, creating a tiered structure where public company scale advantages confront family-owned technical agility. The vendor base fragments across photometric calibration capabilities and national regulatory approvals. Three archetypes dominate: Nordic marine heritage houses, German precision optics fabricators, and diversified aviation electronics conglomerates. Consolidation pressure concentrates among component suppliers facing aluminum alloy input volatility, while technology licensing agreements accelerate LED driver standardization.
Within the marine heritage tier, Glamox AS and Hella Marine exemplify concentrated technical positioning. Aveo Engineering Group occupies a position bridging aviation and renewable energy applications. These three anchors represent distinct competitive vectors: Arctic vessel retrofit specialization, superyacht optical engineering, and wind turbine obstruction marking systems.
| Leading Market Players |
|---|
| Glamox AS |
| Hella Marine |
| Aveo Engineering Group |
| Perko Inc. |
| Den Haan Rotterdam |
| FAMOR S.A. |
| TRANBERG |
| Canepa & Campi |
| Lutron Electronics Co., Inc |
| Others |
Value Chain & Pricing Dynamics
Foundry utilization rates above 85% at German and Norwegian aluminum casting facilities compress margin buffers for marine-grade IP67 housing suppliers, forcing tiered pricing stratification across certification levels and locking smaller assemblers out of Arctic vessel retrofit programs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FAA TSO-certified LED driver assemblies commanding substantial premiums over CAAC-only variants. Price differentiation hinges on photometric calibration grade and dual-compliance inventory status, while cost compression in standard-tier marine lanterns is intensifying due to REACH Annex XVII mercury restriction enforcement. Airport authorities exhibit lowest price sensitivity given regulatory non-negotiability, whereas regional airfield operators under Indian UDAN scheme budgets face acute cost constraints.
Supply Chain Analysis
Strait of Malacca transit underwrites logistics costs for precision Fresnel lens shipments from Japanese specialty glassworks to Southeast Asian assembly operations. Manufacturing gravity centers on Germany, Norway, and China, with production drawing from corrosion-resistant aluminum alloys, regulated LED driver components, and photometric calibration equipment. Single-source vulnerability concentrates in German and Japanese optical component suppliers, while distribution runs through harbor master procurement offices and airport authority tender boards with extended qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between ICAO Annex 14, FAA TSO, and CAAC certification timelines fragments vendor qualification pools, creating defendable niches for specialists with multi-jurisdictional approval capabilities.
For Market Incumbents: Secure dual-compliance certification portfolios before CAAC mandates harden import requirements, and deepen backward integration into aluminum casting capacity to buffer London Metal Exchange volatility. LED driver standardization threatens component-level margins, making captive photometric calibration laboratories in France or Germany essential for differentiation. For New Entrants and Emerging Players: Lead with smart lighting IoT integration for Pacific island airfields and Arctic shipping lanes where remote monitoring commands outcome-based contract premiums. Indian UDAN regional airfields present the most penetrable geography given infrastructure buildout timelines and lower incumbent saturation compared to Chinese markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists with FAA-ICAO-CAAC triple certification and established harbor master relationships over undifferentiated LED assemblers. Acquisition targets should demonstrate installed base visibility in North Sea wind farm aviation marking or Malacca Strait vessel traffic services. The signal to monitor is METI-aligned subsidy expansion for Yellow Sea offshore wind lighting specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Compliance Certification Investment | CAAC parallel approval unlocks procurement access to China's 14th Five-Year Transport Plan airport construction. |
| Backward Integration into Aluminum Casting | Captive foundry capacity insulates margin structures from London Metal Exchange price volatility. |
| Smart Lighting IoT Platform Development | Automated fault detection capabilities enable outcome-based availability contracts with Danish and Singaporean port authorities. |
| Photometric Calibration Laboratory Acquisition | Certified facilities in Germany or France address talent scarcity constraining ICAO and IMO compliance. |
| Arctic Marine Retrofit Program Concentration | IP67-rated housing specialization captures polar shipping lane specifications from Glamox AS-dominated segments. |
Study Parameters
The analysis maps LED aviation approach systems, marine navigation lanterns, solar-powered offshore platform lighting, and smart IoT-enabled architectures, each validated through airport procurement directors, harbor masters, offshore wind farm EPC contractors, and marine vessel fleet managers. Primary interview intelligence triangulates against ICAO regulatory filings, FAA Technical Standard Order databases, EU Ecodesign Directive implementation reports, and customs trade flow records. Bottom-up installation counts and top-down energy infrastructure capex allocations converge to establish volume baselines.
Consistency checks against external benchmarks validate projection outputs across the modeling period. Segmentation dimensions include product type, end-use application, power architecture, and installation geometry, with regional regulatory cluster overlays for certification timeline divergence. CAGRs derive from replacement cycle compression analysis and infrastructure commitment tracking, incorporating aluminum alloy input cost trajectories and photometric standard revision schedules as industry-specific modifiers.
Forecasts assume regulatory continuity in FAA, ECHA REACH, and CAAC regimes; material policy shifts would require re-modeling. Supply chain disruptions from single-source optical component concentration or foundry capacity constraints present specific revision triggers. Practitioners should keep alternative scenarios live as offshore wind subsidy alignment and Arctic shipping lane icebreaker fleet expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Precision Bearing Market
Vehicle Components
India Automotive Steering System Market
Vehicle Components
Towing Ropes Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Industrial Brake Caliper Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
Wheel Seals Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
Car Modification Market