
 Automotive Composite Suspension Components Market | 2026-2036
Automotive Composite Suspension Components Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Composite Suspension Components Market Analysis
Market Overview
China is fragmenting as local resin compounders and state-backed automakers build dedicated composite suspension capacity in Jiangsu and Zhejiang provinces. Continental AG leverages its vertically integrated carbon-fiber prepreg operations to anchor supply contracts with European OEMs. ZF Friedrichshafen AG competes through its modular composite chassis platform, while SGL Carbon specializes in high-volume carbon-fiber leaf spring production for commercial vehicle programs.
Technical Definition and Segment Structure
Automotive composite suspension components are fiber-reinforced polymer structures—typically carbon fiber or glass fiber embedded in thermoset epoxy or thermoplastic matrices—engineered to manage wheel kinematics, dampen road inputs, and reduce unsprung mass by 40-60% versus forged aluminum equivalents. Their primary commercial purpose is enabling OEMs to meet stringent fleet emissions targets without sacrificing ride quality or durability. Control arms and leaf springs represent the most mature product categories with established qualification protocols, while 3D-printed suspension nodes occupy emerging niche applications where topology optimization justifies premium unit economics. Compression molding dominates high-volume output for glass-fiber stabilizer bars, whereas injection molding of thermoplastic composites is gaining share in passenger vehicle shock absorber housings.
Regulatory Environment and Outlook
NHTSA crashworthiness standards and EPA corporate average fuel economy rules shape material selection timelines for US-bound platforms, while ECHA REACH compliance and EU End-of-Life Vehicle directives mandate recyclability pathways that favor thermoplastic resins over thermosets. China's MIIT new-energy vehicle subsidies and GB standards for lightweighting intensity create parallel compliance obligations for suppliers serving domestic OEMs. Stakeholders must monitor evolving recyclability mandates and resin qualification cycles, as regulatory divergence between jurisdictions threatens to fragment platform standardization strategies.
Market Dynamics
Electric vehicle platform architectures are forcing a material substitution cycle in suspension engineering, as battery mass penalties drive OEMs to recover efficiency through unsprung weight reduction in wheel-end components.
Growth Catalysts
- EPA Corporate Average Fuel Economy mandates:US-bound vehicle programs face escalating fines for fleet inefficiency, accelerating qualification of carbon-fiber control arms in light-truck platforms.
- Thermoplastic resin advancement:Polyamide and PPA matrix systems enable sub-60-second cycle times in injection molding, collapsing cost gaps with forged aluminum for passenger vehicle stabilizer bars.
- Jiangsu and Zhejiang manufacturing clusters:Chinese state-backed automakers are building captive composite suspension capacity, creating localized supply security for domestic EV platforms.
Market Restraints
- Carbon fiber feedstock concentration:Precursor acrylonitrile supply concentrates among three Asian petrochemical conglomerates, exposing tier-1 suppliers to input volatility.
- ECHA REACH compliance timelines:Thermoset epoxy systems face extended substance authorization cycles, delaying platform approvals for European OEMs.
- Aluminum forging substitution:High-strength 7xxx series aluminum retains cost advantage in sub-50,000 unit annual volumes, capping composite penetration in niche performance vehicles.
Strategic Opportunities
- Commercial vehicle leaf spring electrification:Battery-electric trucks require 15-20% payload recovery through chassis lightweighting, opening volume applications for glass-fiber reinforced polymer springs.
- MIIT new-energy vehicle subsidies:China's lightweighting intensity credits create direct procurement incentives for composite suspension in domestic EV platforms.
- Topology-optimized additive nodes:Convergence of generative design algorithms and carbon-fiber 3D printing enables load-path-optimized suspension knuckles for low-volume performance architectures.
Industry Challenges
- Crash simulation validation:Composite damage modeling requires 18-24 month correlation cycles against physical barrier tests, compressing development timelines for fast-cycle vehicle programs.
- End-of-Life Vehicle directive compliance:EU recyclability mandates for thermoset components lack scaled industrial processing pathways, creating liability exposure for OEMs.
- Multi-material joining expertise:Dissimilar material interfaces between composite links and aluminum knuckles demand specialized adhesive and mechanical fastening protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Composite Suspension Components Market |
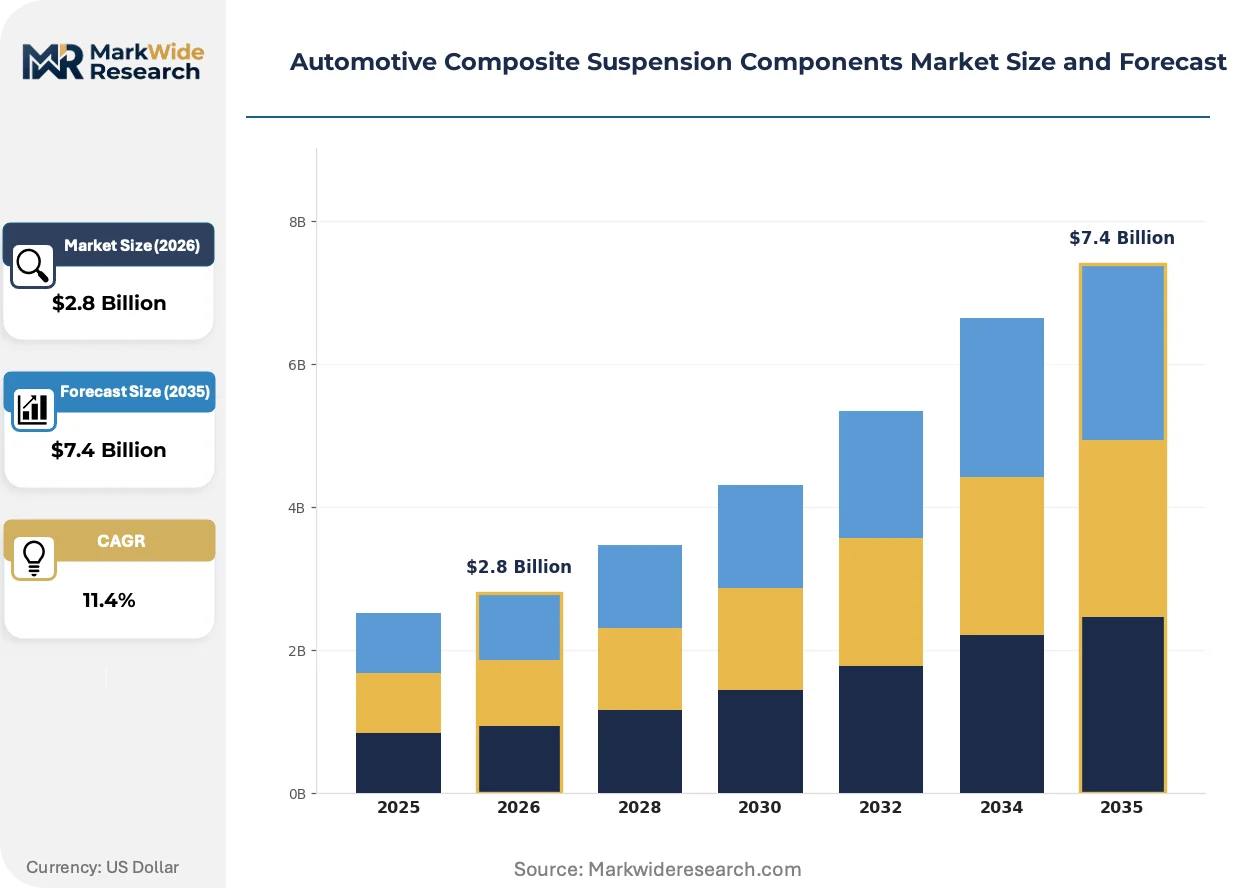
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Arms, Stabilizer Bars, Leaf Springs, Shock Absorbers Technology: Injection Molding, Compression Molding, Reinforced Fiber, 3D Printing End User: OEMs, Aftermarket Suppliers, Commercial Vehicles, Passenger Vehicles Material: Carbon Fiber, Glass Fiber, Thermoset Resin, Thermoplastic Resin |
| Companies Covered | Continental AG, Benteler International AG, ZF Friedrichshafen AG, SGL Carbon, Hendrickson International, Tenneco Inc., KYB Corporation, Mubea, ThyssenKrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Composite Suspension Components Market Emerging Trajectories
Digital engineering workflows are collapsing traditional prototype-test-validate cycles, enabling concurrent development of composite suspension architectures alongside vehicle platform definition.
Generative design software paired with automated fiber placement is virtualizing the suspension component development process. Tier-1 suppliers deploy topology optimization to identify minimum-material load paths before physical tooling commitment. BMW and Mercedes-Benz R&D centers compress design iterations from 18 months to 8 weeks. This capability is virtualizing the traditional sequential engineering timeline, allowing composite architectures to enter vehicle programs earlier in platform development.
ECHA REACH substance restrictions on bisphenol-A epoxies are redirecting formulation chemistry toward bio-based thermoset alternatives. Industrial consequence includes 12-18 month requalification cycles for existing automotive approvals. European OEMs respond by accelerating thermoplastic composite adoption in shock absorber housings, where polyamide matrices bypass epoxy regulatory exposure entirely.
Fleet procurement departments now specify total-cost-of-ownership metrics incorporating fuel savings from unsprung mass reduction, displacing unit-price-only sourcing for composite suspension. Large commercial vehicle operators in Germany and California embed lifecycle efficiency clauses in tier-1 supply agreements. This behavioral shift concentrates demand among vertically integrated suppliers capable of warranty-backed performance guarantees.
Automotive Composite Suspension Components Market Segmentation
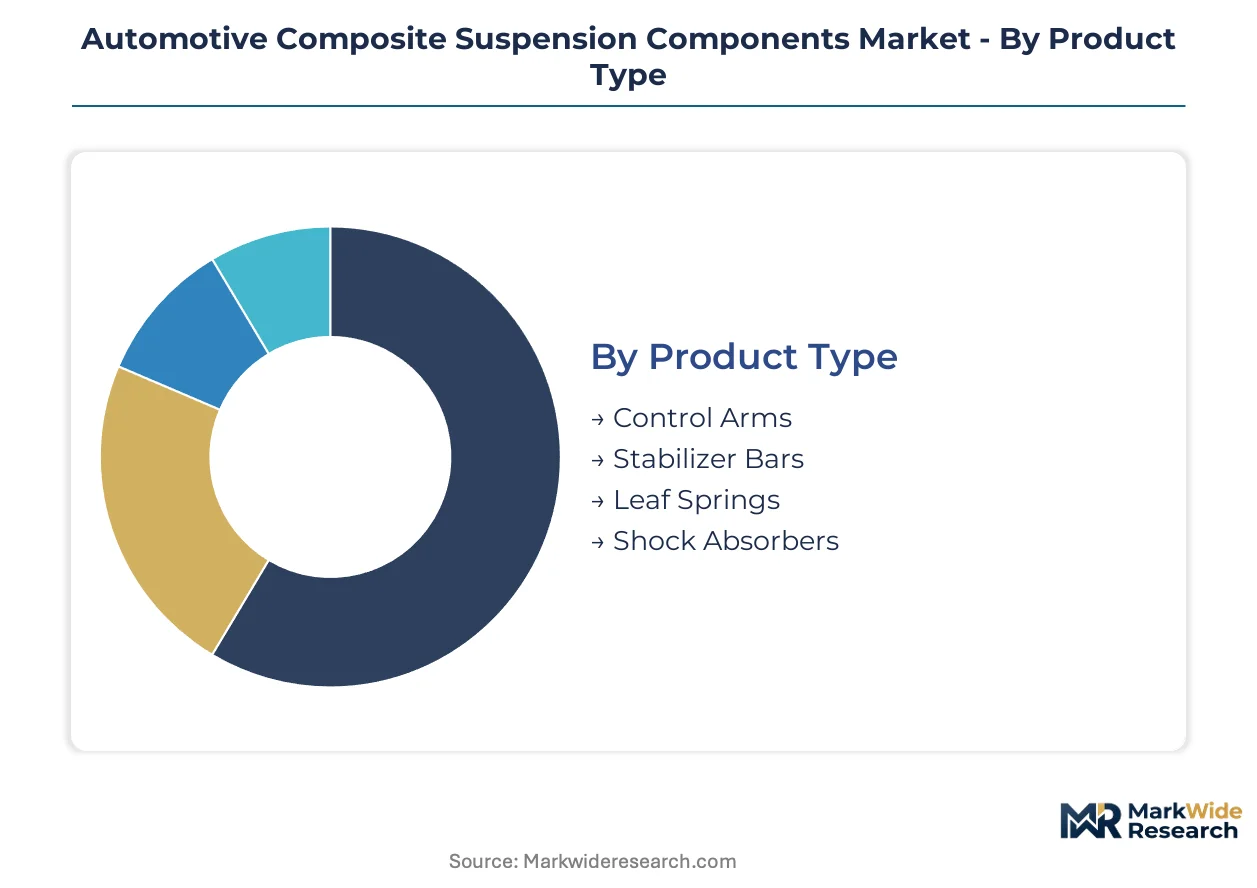
Segmentation in automotive composite suspension components reveals how material science, manufacturing economics, and regulatory pressure intersect across distinct product categories. Understanding these divisions exposes where substitution cycles accelerate and where incumbent technologies defend position.
Product Type:
Mature stamped-aluminum architectures coexist with emerging composite alternatives, creating a bifurcated competitive landscape where qualification protocols separate volume leaders from niche specialists.
- Control Arms:Carbon-fiber-reinforced wishbones and A-arms achieve 40-50% unsprung mass reduction versus forged aluminum. BMW and Mercedes-Benz programs in Germany anchor demand as EPA fuel-economy fines intensify lightweighting mandates for US-bound luxury platforms.
- Leaf Springs:Glass-fiber-reinforced polymer parabolic springs dominate commercial vehicle electrification, delivering 15-20% chassis mass reduction critical for battery-electric truck payload recovery. SGL Carbon's high-volume production lines serve European and North American OEM fleet procurement contracts.
- Stabilizer Bars:Compression-molded glass-fiber bars balance torsional stiffness with corrosion immunity in sub-50,000 unit annual volumes.
- Shock Absorbers:Thermoplastic composite housings bypass thermoset regulatory exposure under ECHA REACH substance restrictions.
Control Arms retain volume leadership; Leaf Springs hold the steepest expansion curve.
Technology:
Cost-per-part economics and cycle-time compression determine manufacturing method selection, with thermoplastic processing gaining ground as resin chemistry advances.
- Injection Molding:Polyamide and PPA matrix systems enable sub-60-second cycle times, collapsing cost gaps with forged aluminum for passenger vehicle stabilizer bars and shock absorber housings. MIIT new-energy vehicle subsidies in China accelerate adoption for domestic EV platforms.
- Compression Molding:Thermoset epoxy prepregs deliver fiber volume fractions exceeding 60% for high-load control arms and leaf springs. Continental AG's vertically integrated carbon-fiber operations anchor European supply security.
- Reinforced Fiber:Automated fiber placement optimizes load-path orientation in structural suspension links.
- 3D Printing:Topology-optimized additive nodes occupy emerging niche applications where generative design justifies premium unit economics in low-volume performance architectures.
Compression Molding dominates current output; Injection Molding is climbing the fastest as thermoplastic adoption accelerates.
End User:
Procurement authority and warranty liability structures fragment demand across captive OEM integration and independent aftermarket channels.
- OEMs:Integrated R&D centers at BMW, Mercedes-Benz, and Volkswagen in Germany co-develop composite architectures with tier-1 suppliers, compressing design iterations through digital engineering workflows. Fleet procurement departments now embed total-cost-of-ownership fuel savings clauses in supply agreements.
- Commercial Vehicles:Battery-electric truck programs require chassis lightweighting intensity that glass-fiber leaf springs uniquely satisfy. California and German fleet operators specify lifecycle efficiency metrics in tier-1 contracts.
- Passenger Vehicles:EV platform architectures prioritize unsprung mass reduction to offset battery mass penalties.
- Aftermarket Suppliers:Performance upgrade segments serve niche motorsport and tuning applications with limited volume scale.
OEMs command revenue concentration; Commercial Vehicles generate the most rapid demand acceleration.
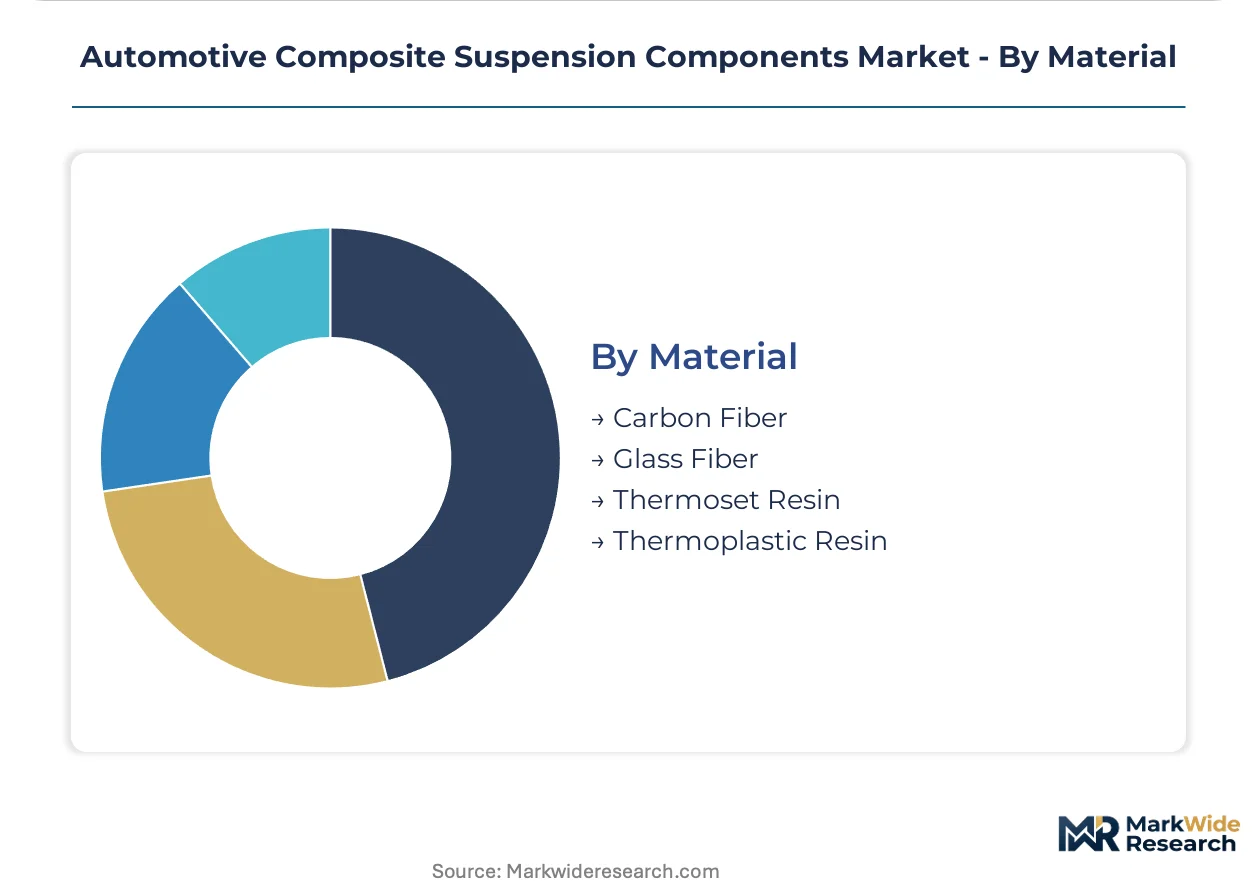
Material:
Recyclability mandates and feedstock concentration risks create divergent strategic postures across fiber and matrix categories.
- Carbon Fiber:PAN-based precursors deliver exceptional stiffness-to-weight ratios for control arms and structural nodes. Acrylonitrile supply concentrates among three Asian petrochemical conglomerates, exposing tier-1 suppliers to input volatility and price spikes.
- Thermoplastic Resin:Polyamide matrices bypass ECHA REACH authorization cycles affecting bisphenol-A epoxy systems, enabling faster platform approvals for European OEMs. Injection molding compatibility supports high-volume passenger vehicle applications.
- Glass Fiber:E-glass and S-glass variants dominate cost-sensitive commercial vehicle leaf spring applications.
- Thermoset Resin:Epoxy systems retain performance advantages in high-temperature underhood environments but face EU End-of-Life Vehicle directive compliance gaps.
Carbon Fiber holds technology leadership; Thermoplastic Resin is gaining share fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA crashworthiness standards anchor US regulatory pressure, while ECHA REACH compliance and MIIT subsidies create parallel compliance obligations across Germany and China. Each geography shapes material selection timelines through distinct regulatory instruments.
United States
EPA Corporate Average Fuel Economy mandates accelerate carbon-fiber control arm qualification for light-truck platforms facing fleet inefficiency penalties. NHTSA barriers govern physical validation protocols. Detroit-area engineering centers co-develop composite architectures with tier-1 suppliers serving domestic OEM electrification programs.
Germany
BMW, Mercedes-Benz, and Volkswagen operate integrated composite R&D centers that compress design iterations through digital engineering workflows. ECHA REACH substance restrictions on bisphenol-A epoxies redirect formulation chemistry toward bio-based alternatives. Stuttgart and Munich anchor European supply security for high-load structural components.
China
MIIT new-energy vehicle subsidies create direct procurement incentives for composite suspension in domestic EV platforms. GB standards for lightweighting intensity mandate material substitution thresholds. Jiangsu and Zhejiang provinces concentrate state-backed automaker capacity building for captive composite suspension production.
Japan
METI carbon-neutrality roadmaps pressure OEMs to recover battery mass penalties through unsprung weight reduction. JIS standards govern fiber-reinforced polymer qualification protocols. Nagoya-area manufacturing clusters specialize in high-volume glass-fiber stabilizer bar production for hybrid vehicle programs.
South Korea
Domestic battery-electric vehicle platforms prioritize chassis lightweighting intensity to offset cell mass penalties. MFDS and KSA standards shape material approval timelines for suspension components. Seoul Capital Area engineering centers partner with European tier-1 suppliers for technology transfer in thermoplastic composite processing.
Automotive Composite Suspension Components Market Vendor Landscape
Capability concentration sits with vertically integrated resin compounders and fiber specialists; scale advantage sits with diversified chassis system suppliers. The market structures around three archetypes: carbon-fiber precursor producers controlling upstream material supply, modular platform integrators bundling composite architectures with electronic systems, and process-technology licensors enabling regional manufacturing scale. Dominant competitive moves include backward integration into prepreg operations and strategic partnerships binding OEM R&D centers to exclusive supply agreements.
Within the diversified chassis tier, Continental AG and ZF Friedrichshafen AG exemplify platform integrators bundling composite architectures with broader vehicle systems. SGL Carbon represents the fiber-specialist archetype with captive precursor-to-component capabilities. These three German-origin entities anchor European supply security while competing through distinct vectors: Continental through vertically integrated carbon-fiber operations, ZF through modular chassis platforms, and SGL Carbon through high-volume production specialization.
| Leading Market Players |
|---|
| Continental AG |
| Benteler International AG |
| ZF Friedrichshafen AG |
| SGL Carbon |
| Hendrickson International |
| Tenneco Inc. |
| KYB Corporation |
| Mubea |
| ThyssenKrupp AG |
| Others |
Supply Flow & Price Mechanics
Acrylonitrile feedstock concentration among three Asian petrochemical conglomerates exposes tier-1 suppliers to simultaneous input volatility and tariff exposure, compressing both pricing tier spreads between carbon-fiber and glass-fiber architectures and forcing supply chain regionalization around Jiangsu and Zhejiang manufacturing clusters.
Pricing Analysis
Price spreads between German-engineered carbon-fiber control arms and Chinese-manufactured glass-fiber leaf springs reflect a three-tier pricing structure across premium, standard, and economy levels. Certification grade under ECHA REACH substance authorization and volume scale under fleet procurement contracts drive differentiation. Cost compression in thermoplastic injection-molded stabilizer bars is intensifying because polyamide matrix cycle times collapsed below aluminum forging economics. Commercial vehicle fleet operators exhibit highest price sensitivity, while luxury OEM platform engineers prioritize total-cost-of-ownership fuel savings clauses.
Supply Chain Analysis
Export-control regimes on carbon-fiber precursor technology limit flows from Japanese and US specialty chemical producers to Chinese compounders, fragmenting global prepreg availability. Manufacturing gravity centers on Germany for high-load structural components, China for state-backed EV platform capacity, and Japan for glass-fiber stabilizer bar specialization. The supply chain draws from PAN-based precursor feedstocks, thermoplastic resin formulations, and automated fiber placement equipment. Single-source vulnerability concentrates in acrylonitrile supply. Distribution runs through vertically integrated tier-1 suppliers with captive OEM R&D partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among fleet procurement departments embedding lifecycle efficiency clauses, consolidating demand around warranty-backed performance guarantees from vertically integrated suppliers.
For Market Incumbents: Insulate carbon-fiber prepreg operations through backward integration into precursor supply or captive resin formulation capacity. Aluminum forging substitution in sub-50,000 unit volumes threatens margin compression in niche performance segments. Prioritize thermoplastic composite R&D to bypass ECHA REACH authorization delays affecting epoxy systems. For New Entrants and Emerging Players: Pursue commercial vehicle leaf spring electrification as the most penetrable white-space target, where battery-electric truck payload recovery mandates create volume pull. Target Jiangsu and Zhejiang manufacturing clusters for state-backed automaker partnerships. Lead with topology-optimized additive manufacturing capabilities for low-volume performance architectures. For Investors and Strategic Acquirers: The market sits at a material-substitution acceleration phase that favors fiber-specialist archetypes with captive precursor-to-component capabilities. Long-term viability rests on regulatory tailwinds for thermoplastic recyclability and EV platform standardization. Watch for MIIT subsidy recalibration as the inflection signal for Chinese demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Secures acrylonitrile feedstock against Asian petrochemical conglomerate concentration risk. |
| Thermoplastic Resin Platform Shift | Bypasses ECHA REACH authorization cycles delaying European OEM platform approvals. |
| Commercial Vehicle Fleet Partnership | Locks in lifecycle efficiency clauses with California and German battery-electric truck operators. |
| Topology-Optimized Additive Manufacturing | Enables load-path-optimized suspension nodes for low-volume performance architectures. |
| Jiangsu-Zhejiang Manufacturing Footprint | Captures MIIT new-energy vehicle subsidy flows for domestic EV platform supply security. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, commercial vehicle fleet managers, and composite materials R&D directors anchored the qualitative base. Primary interview data combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive suppliers, and customs/trade flow records. Bottom-up segment sizing triangulated against top-down macro automotive production forecasts.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, manufacturing technology, end-user category, and material composition, crossed with vehicle class and propulsion architecture. CAGRs derived from regression analysis of historical substitution patterns and forward-looking platform deployment schedules. Forecast inputs incorporated EPA fuel-economy fine schedules, ECHA REACH substance authorization timelines, and MIIT subsidy intensity thresholds.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, battery-electric vehicle penetration rates, or carbon-fiber feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement consistency and OEM platform standardization strategies. Material shifts in EU End-of-Life Vehicle directive recyclability mandates or thermoplastic resin qualification breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Tail Lifts Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
Car Seat and Accessories Market
Vehicle Components
Heavy Vehicles Suspension Anti-Vibration Components Market
Vehicle Components
Bicycle Components Aftermarket Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Rail Components Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
4x4 Vehicle Parts and Accessories Market
Vehicle Components
Truck Suspension System Market
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Spark Plug Accessories Market