
 Suction Road Sweeper Market | 2026-2036
Suction Road Sweeper Market Size, Share, and Industry Trends Forecast 2026-2036
Suction Road Sweeper Market Analytics
Aluminum alloy chassis construction is broadening design flexibility for compact sweepers while reducing curb weight. Bucher Industries leverages in-house hydraulics expertise to sustain premium positioning in European municipal fleets. Zoomlion Heavy Industry anchors volume production through integrated manufacturing bases serving Asia-Pacific markets. Fayat Group competes across multiple brands with differentiated regional footprints.
A suction road sweeper is a motorized vehicle equipped with vacuum suction systems, rotating brushes, and debris hoppers designed to remove particulate matter, litter, and sediment from paved surfaces. Operating suction typically ranges from 2,500 to 6,000 cubic meters per hour depending on vehicle class, with filtration systems capturing particles down to PM2.5 for regulatory compliance. Heavy-duty models dominate municipal highway contracts where durability requirements and payload capacity command premium pricing, while electric technology represents the fastest-expanding segment as battery energy density improves and total cost of ownership calculations shift favorably. Compact sweepers occupy specialized margin pools in historic European city centers and narrow Asian alleyways where maneuverability constraints exclude larger equipment.
EPA emission standards and OSHA workplace exposure limits in the United States tighten particulate thresholds and operator cabin air quality requirements, directly influencing filtration specification upgrades. The EU Green Deal and associated F-Gas Regulation accelerate diesel-to-electric transition timelines for municipal procurement tenders across Germany, France, and Italy. India's BIS certification and CEA electrical safety mandates shape import compliance pathways for foreign manufacturers. Stakeholders must monitor battery supply chain localization requirements and charging infrastructure deployment schedules as procurement criteria evolve beyond equipment specifications toward total ecosystem readiness.
Market Dynamics
Electric drivetrain conversion is compressing procurement cycles as municipal fleet operators accelerate replacement timelines ahead of regulatory phase-outs. Battery-swappable architectures and fast-charging protocols are redefining operational uptime benchmarks across dense urban service routes.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based cooling systems in vacuum filtration units is forcing equipment upgrades across German, French, and Italian municipal fleets, creating replacement demand for compliant electric models.
- India Smart Cities Mission:Central government disbursements for urban cleanliness infrastructure are channeling sustained orders into compact sweeper categories serving narrow historic districts and informal settlement access roads.
- PM2.5 Filtration Systems:Advanced baghouse and cartridge configurations capturing sub-micron particulate matter are becoming mandatory specification items in air quality non-attainment zones, elevating equipment technical thresholds.
Market Restraints
- Lithium-Ion Cell Supply Concentration:Battery pack production clusters in East Asian manufacturing corridors create input vulnerability for European and North American sweeper assemblers without captive cell supply agreements.
- Copper and Rare Earth Magnet Costs:Permanent-magnet motor architectures depend on neodymium and dysprosium pricing volatility that compresses margin predictability for electric drivetrain variants.
- Technical Limitation of Cold-Weather Range:Battery energy density degradation below minus ten degrees Celsius restricts electric sweeper deployment viability in Nordic and Canadian municipal contracts without thermal management upgrades.
Strategic Opportunities
- Indonesian Urban Expansion:Jakarta and Surabaya metropolitan sanitation authorities are initiating fleet modernization programs with limited incumbent supplier relationships, creating first-mover positioning potential.
- Autonomous Route Navigation:Lidar and computer vision integration with existing suction and brush systems is converging toward driver-optional operation in controlled campus and industrial environments.
- US Inflation Reduction Act:Commercial clean vehicle tax credits are expanding total-cost-of-ownership advantages for electric sweepers in municipal and private fleet procurement evaluations.
Industry Challenges
- High-Voltage Technician Certification:Electric drivetrain maintenance requires specialized training pipelines that municipal garages and third-party service networks are struggling to populate at sufficient scale.
- Legacy Fleet Integration Complexity:Mixed-fleet operations combining diesel, hybrid, and battery-electric sweepers are forcing depot reconfiguration for charging infrastructure, parts inventory, and fueling logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suction Road Sweeper Market |
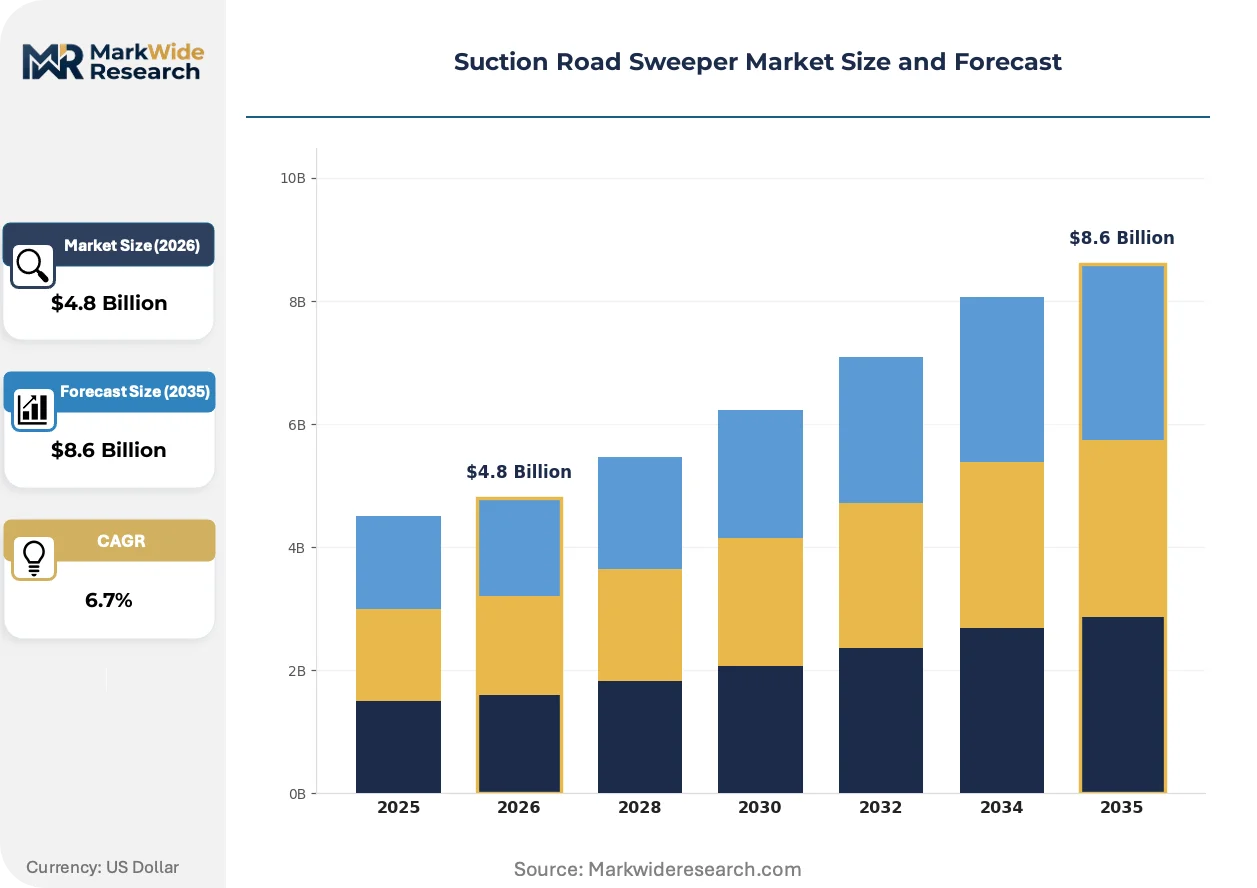
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty, Compact, Mechanical, Combination Technology: Vacuum, Airflow, Hydraulic, Electric End User: Municipalities, Contractors, Facility Managers, Industrial Deployment: On-Road, Off-Road, Urban, Rural |
| Companies Covered | Aebi Schmidt Group, Bucher Industries, Nilfisk Group, Dulevo International, Elgin Sweeper Company, Fayat Group, Hako GmbH, Zoomlion Heavy Industry, FAUN Umwelttechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suction Road Sweeper Market Evolving Landscape
Active filtration and energy recovery systems are displacing passive mechanical designs as regulatory thresholds tighten and operating cost scrutiny intensifies. Equipment differentiation is migrating from chassis specifications to software-defined service optimization.
Modular battery pack architectures with standardized form factors are decentralizing fleet energy management away from centralized depot charging toward opportunity-based swapping and distributed fast-charging nodes. Municipal operators in Rotterdam and Singapore are piloting hot-swap protocols that reduce vehicle downtime from hours to minutes. This topology is compressing the capital intensity barrier for full-electric fleet conversion.
The EU Green Deal's F-Gas Regulation and associated national implementation decrees are accelerating diesel equipment phase-out timelines across German and French procurement tenders. Manufacturers are responding with integrated electric platforms rather than retrofit conversions. Italian municipal associations are demanding ten-year total-cost guarantees that favor battery-electric lifecycle economics.
Lifecycle service contracting is displacing discrete equipment sales in Scandinavian and Benelux municipal procurement frameworks. Copenhagen and Amsterdam sanitation departments now specify availability-based performance metrics rather than capital expenditure line items. This model shift is compressing supplier margins on initial delivery while extending revenue recognition across fifteen-year service horizons.
Suction Road Sweeper Market Segmentation
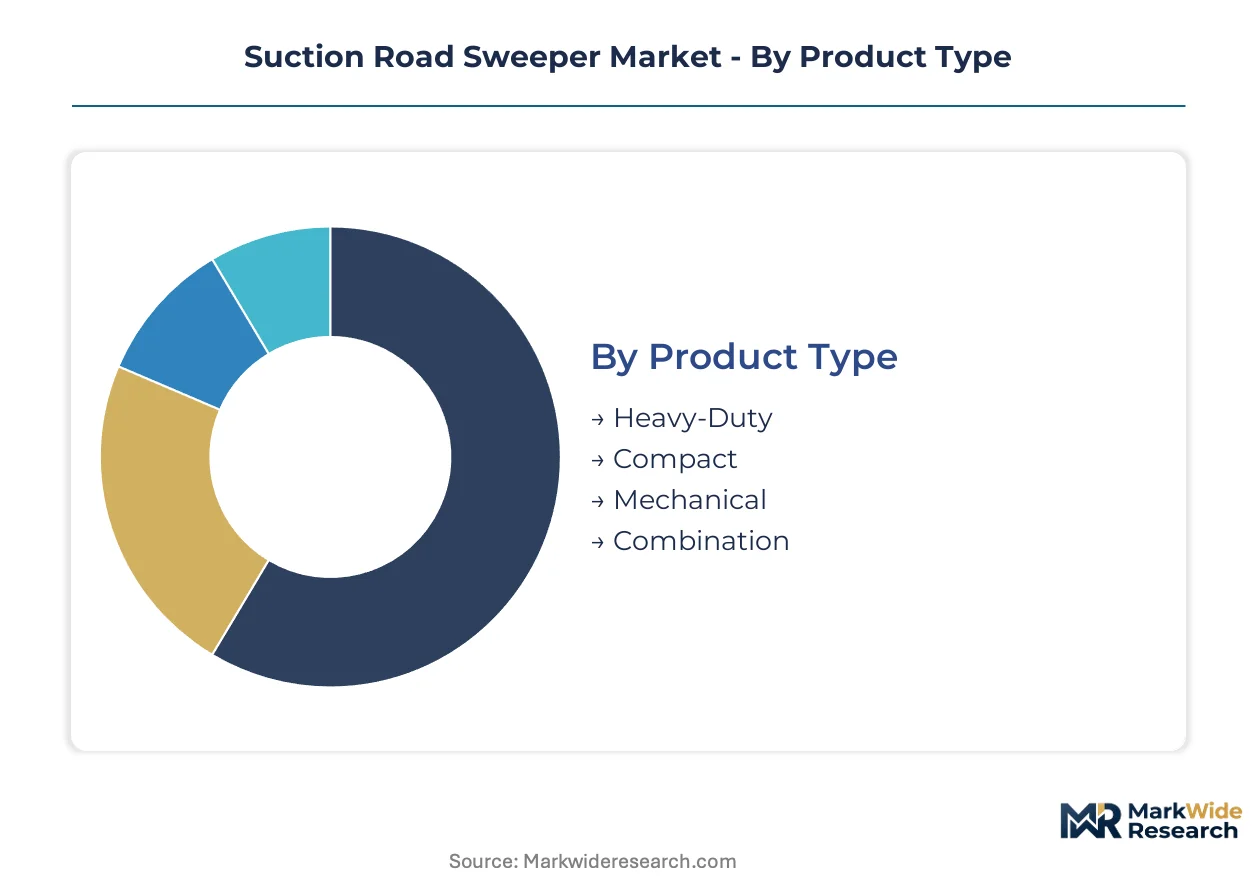
Suction road sweeper procurement decisions hinge on duty-cycle intensity, regulatory jurisdiction, and total-cost-of-ownership horizons. Fleet operators segment requirements across vehicle scale, powertrain architecture, and operational environment to align capital deployment with service-level agreements.
Product Type:
Capital intensity escalates sharply with chassis mass and auxiliary system complexity, placing heavy-duty configurations at the apex of upfront investment requirements.
- Heavy-Duty:Full-size truck platforms with 8,000+ liter hopper capacity and dual-engine vacuum systems dominate German Autobahn maintenance contracts and Indian national highway tenders. Municipal procurement in Maharashtra and Karnataka channels sustained orders toward this segment where durability specifications justify premium pricing.
- Compact:Narrow-track designs under 2.2 meters width access UNESCO-protected historic cores in Prague, Bruges, and Varanasi where maneuverability constraints exclude larger equipment. Battery-electric variants are gaining specification share in Amsterdam and Copenhagen zero-emission zones.
- Mechanical:Brush-and-conveyor architectures without vacuum filtration serve dust-suppression roles in mining haul roads and quarry access routes where particulate capture is secondary to debris removal.
- Combination:Modular sweeper-vacuum units with interchangeable heads address seasonal demand fluctuations in Canadian and Nordic municipalities facing snow-removal integration requirements.
Most installed capacity flows through Heavy-Duty configurations. Expansion is steepest in Compact variants.
Technology:
Powertrain selection determines operational economics across depreciation, energy, and maintenance cost pools, with electric architectures resetting lifecycle calculation frameworks.
- Vacuum:Negative-pressure suction systems operating at 2,500–6,000 cubic meters per hour remain the baseline specification for fine particulate capture in EPA non-attainment zones and EU PM2.5-exceedance areas.
- Airflow:Regenerative air recirculation designs reduce filter loading in high-debris environments such as autumn leaf-collection routes in New England and Central European forestry corridors.
- Hydraulic:Auxiliary power take-off systems from diesel chassis engines dominate legacy fleet compositions across Italian and Spanish municipal garages where electrification retrofit capital is constrained.
- Electric:Battery-dominant platforms with 150–300 kWh pack configurations are capturing specification share in Rotterdam, Singapore, and Shenzhen procurement tenders where depot charging infrastructure is operational.
Electric drivetrains are climbing the fastest as total-cost guarantees extend beyond ten-year horizons.
End User:
Procurement sophistication varies across public-sector tender complexity and private-sector fleet standardization pressures.
- Municipalities:City sanitation departments in India's Smart City clusters and EU Green Deal jurisdictions specify availability-based performance contracts rather than capital-acquisition line items, compressing supplier margins on initial delivery.
- Contractors:Third-party service providers across Indonesian and Vietnamese urban expansion corridors face working-capital constraints that favor lease-to-own financing structures and standardized maintenance protocols.
- Facility Managers:Campus and logistics park operators in the United States leverage IRA commercial clean vehicle tax credits to accelerate electric sweeper deployment in controlled private-road environments.
- Industrial:Steel mills, cement plants, and port authorities specify explosion-proof configurations and heavy-duty filtration for combustible dust environments under OSHA and ATEX directives.
Contractor channels are gaining share fastest in emerging-market urbanization corridors.
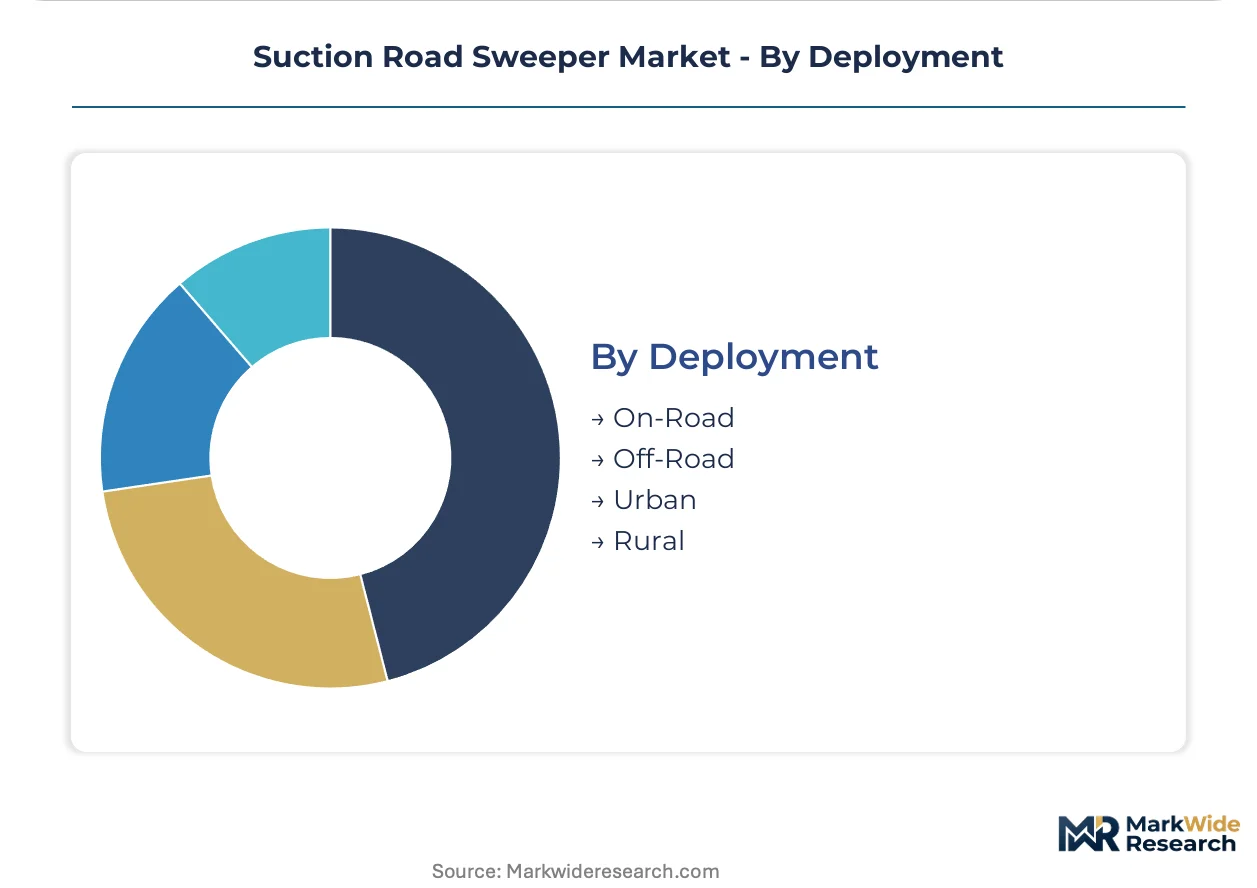
Deployment:
Surface classification and population density dictate vehicle specification, with on-road certification requirements adding compliance cost layers absent from confined-site applications.
- On-Road:Highway-legal chassis with full lighting and crashworthiness certification serve arterial road networks in Germany, France, and Italy where Euro 7 emission standards are accelerating diesel phase-out timelines.
- Off-Road:Non-homologated sweepers operate in mining concessions, airport aprons, and port terminals where surface debris includes metal fragments and chemical spill residues requiring specialized hopper construction.
- Urban:Dense-route optimization with frequent stop-start cycles favors regenerative braking and battery-electric architectures in Jakarta, Surabaya, and Metro Manila fleet modernization programs.
- Rural:Extended-range diesel and hybrid configurations address charging infrastructure gaps in Canadian prairie provinces and Australian outback road maintenance contracts.
Urban deployment specifications are expanding most quickly as metropolitan sanitation authorities consolidate fleet procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal procurement frameworks anchor European demand for heavy-duty suction sweepers, with Autobahn maintenance contracts and urban zero-emission zones driving specification intensity across the continent.
Germany
KBA homologation requirements and Euro 7 pre-compliance tenders are accelerating diesel-to-electric fleet transitions in Bavaria and North Rhine-Westphalia. The EU F-Gas Regulation mandates vacuum filtration system upgrades, forcing equipment replacement cycles in Frankfurt-Rhine-Main and Stuttgart metropolitan sanitation departments.
France
Paris-region air quality non-attainment status is elevating PM2.5 capture specifications in municipal tenders. ANSM-aligned technical standards for operator cabin exposure limits are reshaping filtration procurement criteria. Lyon and Marseille port authorities are specifying explosion-proof configurations for combustible dust environments.
India
Smart Cities Mission disbursements are channeling compact sweeper orders into Maharashtra and Karnataka urban clusters. BIS certification and CEA electrical safety mandates shape import compliance for foreign manufacturers. Delhi-NCR municipal corporations are consolidating fleet procurement under availability-based performance contracts.
United States
EPA non-attainment zone designations in California and Texas are tightening particulate thresholds for highway maintenance equipment. OSHA workplace exposure limits are influencing operator cabin air quality specifications. IRA commercial clean vehicle tax credits are expanding electric sweeper total-cost advantages in municipal fleet evaluations.
Indonesia
Jakarta and Surabaya metropolitan sanitation authorities are initiating fleet modernization programs with limited incumbent supplier relationships. The country's national infrastructure regulator is drafting urban cleanliness procurement guidelines. Java-based contractors are adopting lease-to-own financing structures for compact sweeper deployment.
Suction Road Sweeper Market Competitive Landscape
Global majors compete with regional champions across municipal procurement sophistication and fleet standardization requirements. Market structure tilts toward consolidated premium positioning in European tenders while fragmenting across price-sensitive emerging-market corridors. Three archetypes dominate: integrated hydraulics specialists, volume-scale Asian fabricators, and multi-brand European holding companies. Competitive moves center on electric platform development partnerships and lifecycle service contracting transitions.
Among European-based holding companies, Fayat Group and Bucher Industries occupy positions spanning multiple regional brands with differentiated geographic footprints. Zoomlion Heavy Industry anchors volume production through integrated manufacturing bases. These three exemplify the strategic divergence between premium-tier municipal specification capture and scale-driven emerging-market penetration.
| Leading Market Players |
|---|
| Aebi Schmidt Group |
| Bucher Industries |
| Nilfisk Group |
| Dulevo International |
| Elgin Sweeper Company |
| Fayat Group |
| Hako GmbH |
| Zoomlion Heavy Industry |
| FAUN Umwelttechnik |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation mandates on municipal sanitation departments across Germany, France, and Italy are compressing equipment replacement timelines and forcing supply chains to absorb compliance-cost pass-throughs while maintaining bid competitiveness in tender-heavy procurement frameworks.
Pricing Analysis
Input-cost pass-through from lithium-ion cell procurement and rare-earth magnet sourcing is reshaping margin structures across electric drivetrain variants. Three-tier pricing structure across premium, standard, and economy levels separates Bucher Industries and Fayat Group specifications from Zoomlion volume offerings and regional Asian fabricators. Cost compression in the economy tier is intensifying because municipal budget constraints in Southeast Asian markets favor lease-to-own financing over capital acquisition. Contractor channels in Indonesia and Vietnam exhibit highest price sensitivity; German Autobahn maintenance contracts show lowest sensitivity due to availability-based performance contracting.
Supply Chain Analysis
Container freight rate volatility from East Asian manufacturing corridors to European port hubs is elevating landed cost unpredictability for battery pack and chassis component imports. Production gravity centers on China for lithium-ion cells, South Korea for permanent-magnet motor assemblies, and Germany for hydraulic system integration. Raw material dependencies span copper busbar stock, neodymium-dysprosium magnet alloys, and aluminum alloy extrusions. Single-source vulnerability concentrates in East Asian cell supply agreements. Distribution runs through municipal procurement consortia in Europe and contractor lease networks in emerging Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
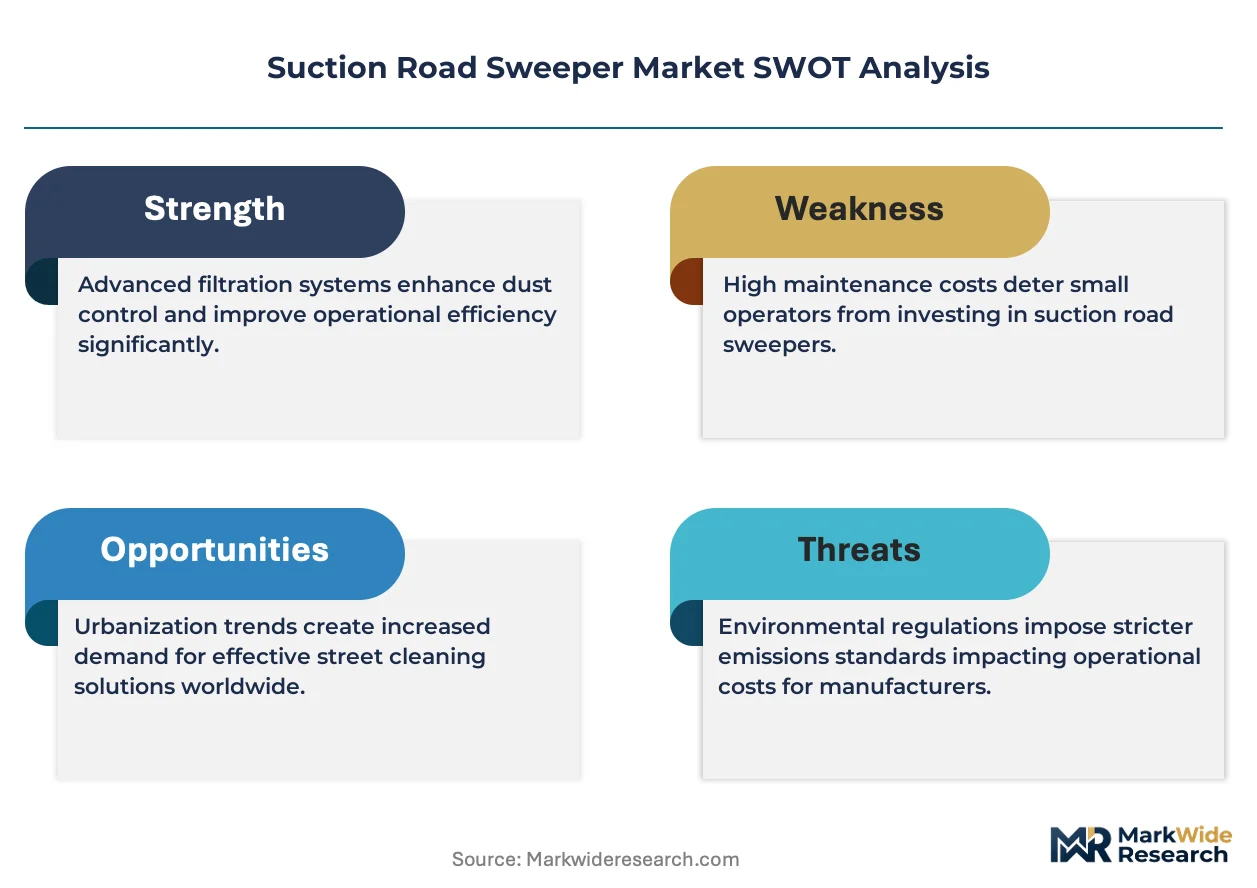
The suction road sweeper market functions as a regulatory compounder where EU F-Gas Regulation phase-out timelines and Euro 7 pre-compliance mandates are generating replacement demand that outpaces organic fleet expansion.
For Market Incumbents: Extend service-contracting capabilities to capture fifteen-year revenue recognition windows as Copenhagen and Amsterdam sanitation departments shift from capital expenditure to availability-based metrics. Deepen backward integration into battery pack assembly to mitigate East Asian cell supply concentration. Certification investment in CEA electrical safety compliance secures positioning in India's Smart Cities Mission procurement clusters against emerging Asian competitors. For New Entrants and Emerging Players: Autonomous route navigation systems present a technology-first wedge for campus and industrial environment deployment where lidar-computer vision integration can bypass entrenched municipal supplier relationships. Indonesian urban expansion corridors offer most penetrable geography given limited incumbent supplier relationships in Jakarta and Surabaya metropolitan authorities. Go-to-market through lease-to-own financing structures aligns with contractor working-capital constraints across Vietnamese and Indonesian sanitation markets. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated hydraulics specialists possessing captive electric platform development partnerships and lifecycle service contracting infrastructure. Five-to-ten year viability favors suppliers with demonstrated municipal performance-contract execution in Benelux and Scandinavian frameworks. Signal to monitor: battery supply chain localization mandates in Indian and European procurement criteria as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive cell sourcing from East Asian manufacturers insulates margin predictability against commodity volatility. |
| Lifecycle Service Contracting | Fifteen-year availability-based metrics in Amsterdam and Copenhagen compress upfront margins while extending revenue recognition. |
| Autonomous Navigation Integration | Lidar and computer vision convergence enables driver-optional operation in controlled industrial campus environments. |
| Backward Integration into Hydraulics | In-house auxiliary power system production sustains premium positioning in European municipal fleet specifications. |
| Geographic Manufacturing Footprint | Integrated production bases in Asia-Pacific anchor volume scale for price-sensitive emerging market procurement. |
Research Methodology
Direct dialogue with municipal fleet procurement officers, aftermarket service directors, OEM platform engineers, and battery supply chain managers grounded qualitative assessment in operational constraints across European and Asia-Pacific deployment contexts. Secondary validation drew from KBA homologation filings, EU F-Gas Regulation implementation decrees, Indian Smart Cities Mission disbursement records, and SEC disclosures from listed equipment manufacturers. Bottom-up unit economics triangulated against top-down market sizing from municipal fleet registries and tender announcement databases.
Segment-level outputs across the projection horizon reflect modeled interactions between powertrain architecture, vehicle class, and regional regulatory cluster. The analytical framework incorporated duty-cycle intensity variations, charging infrastructure deployment schedules, and total-cost-of-ownership calculation shifts favoring electric drivetrains. CAGRs derived from regression against historical procurement velocity and regulatory mandate phase-in timelines. Industry-specific inputs included battery energy density improvement curves and thermal management upgrade penetration rates for cold-climate deployments.
The model holds under stable regulatory enforcement and battery cost decline trajectories; deviation in lithium-ion supply disruptions or Euro 7 implementation delays would shift replacement cycle assumptions. Forecasts reflect documented assumptions about municipal budget continuity and charging infrastructure buildout schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Car Accessories Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Electric Vehicle High Voltage Connector System Market
Vehicle Components
Truck Suspension System Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Passenger Car Sensors Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
Steel and Rubber Tracks Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
Steering Knuckle Market