
 Low Speed Vehicle (LSV) Market | 2026-2036
Low Speed Vehicle (LSV) Market Size, Share, and Industry Trends Forecast 2026-2036
Low Speed Vehicle (LSV) Market Foresight
Mexico is reconfiguring North American LSV supply chains through expanding maquiladora capacity for electric drivetrain assembly. Textron leverages its vertical integration across composite body manufacturing to sustain cost leadership in utility vehicle platforms. Yamaha Motor anchors its position through specialized powertrain engineering for personal carrier segments in Japanese and North American markets.
A low speed vehicle is a four-wheeled motor vehicle capable of achieving speeds between 20 and 25 miles per hour, powered by electric or internal combustion engines with gross vehicle weight ratings below 3,000 pounds, designed primarily for short-distance transportation in controlled environments. Golf cart applications retain the largest installed base though utility vehicles command superior margins through commercial customization and heavier payload specifications. Neighborhood electric vehicles are gaining traction in master-planned communities where municipalities restrict conventional automobile access to internal road networks.
NHTSA FMVSS 500, EPA emission standards for small spark-ignition engines, and ISO 6469 electric vehicle safety specifications collectively determine product compliance pathways and market access conditions across jurisdictions. The EU AI Act and CE marking requirements under the EU Machinery Directive increasingly influence autonomous LSV development programs targeting European campus and logistics deployments. Stakeholders must monitor evolving battery certification standards and local ordinances permitting street-legal LSV operation as these regulatory layers determine addressable market expansion.
Market Dynamics
The electrification of campus and community mobility infrastructure is compressing replacement cycles as institutional buyers consolidate procurement around zero-emission fleet mandates. This structural pull is reordering supplier priorities across powertrain engineering, battery certification, and vehicle-to-grid integration capabilities.
Growth Catalysts
- EPA emission standards for small spark-ignition engines:Tightening exhaust regulations are accelerating phase-out of gasoline-powered utility vehicles in municipal and university fleets.
- Master-planned communities:Restricted automobile access policies in age-restricted and resort developments are expanding street-legal neighborhood electric vehicle deployment.
- Lithium iron phosphate battery chemistries:Thermal stability improvements and declining cell costs are enabling longer-range electric utility configurations without active cooling systems.
Market Restraints
- Raw material concentration:Cathode active material processing concentrates in China, exposing non-Chinese assemblers to supply disruption and export licensing friction.
- FMVSS 500 speed ceiling:The 25 mph federal maximum constrains product applicability on roads with higher posted limits, fragmenting addressable use cases.
- Lead-acid battery substitution:Flooded lead-acid packs retain installed base in price-sensitive golf fleet applications, delaying lithium conversion economics.
Strategic Opportunities
- Autonomous campus logistics:The EU AI Act and Machinery Directive are creating compliance frameworks for driverless LSV deployments in European university and industrial settings.
- Vehicle-to-grid integration:Bidirectional charging hardware is opening revenue streams from grid services and peak-shaving contracts for fleet operators.
- Indian industrial campuses:Factory automation and export-zone logistics hubs present underpenetrated demand for electric utility carriers outside traditional golf and leisure applications.
Industry Challenges
- Functional safety engineering:ISO 6469 high-voltage system certification requires specialized electrical engineering talent scarce among legacy golf cart manufacturers.
- Multi-jurisdiction homologation:Divergent state-level street-legal equipment mandates create SKU proliferation and inventory management complexity for national distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Speed Vehicle (LSV) Market |
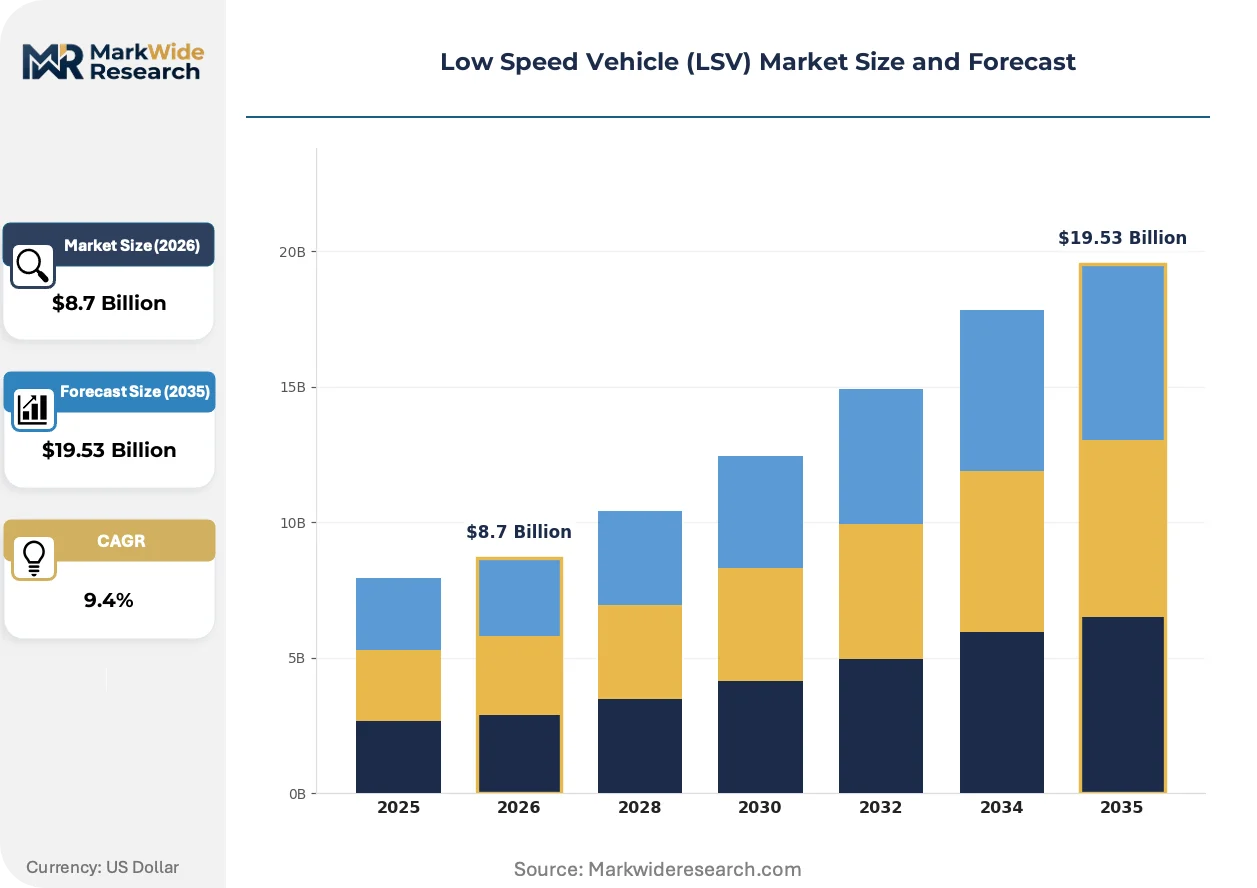
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neighborhood Electric Vehicle, Golf Cart, Utility Vehicle, Personal Carrier Application: Residential Use, Golf Courses, Campus Transportation, Commercial Delivery End User: Municipalities, Universities, Golf Clubs, Hospitality Industry Distribution Channel: Online Sales, Dealerships, Direct Sales, Rental Services |
| Companies Covered | Textron, KUBOTA, Yamaha Motor, Deere & Company, The Toro Company, Club Car, Polaris, Columbia Vehicle, EVolution Electric Vehicles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Speed Vehicle (LSV) Market Shifts & Advancements
Powertrain architecture and energy management systems are converging with automotive-grade standards, blurring historical segmentation between recreational and commercial vehicle platforms. This technical elevation is raising baseline performance expectations while compressing development cycles.
Solid-state battery prototyping is hybridizing energy density and safety profiles previously treated as trade-offs. Tier-1 cell suppliers are sampling sulfide-electrolyte cells to LSV OEMs for 2026 platform integration. Campus fleet operators are piloting these configurations to extend duty cycles without expanding charging infrastructure footprints.
The EU AI Act's risk-classification framework is reshaping autonomous vehicle development roadmaps. European manufacturers are prioritizing CE marking pathways for limited-speed autonomous shuttles ahead of full self-driving certification. University procurement offices are inserting algorithmic transparency requirements into RFP language, favoring suppliers with documented conformity assessment procedures.
Fleet-as-a-service contracting is displacing traditional unit sales in municipal and institutional segments. Subscription models bundle vehicles, charging infrastructure, and predictive maintenance into per-mile or per-month arrangements. This shift concentrates buyer relationships with national service networks rather than regional dealers, visible most acutely in California and Florida municipal procurement patterns.
Low Speed Vehicle (LSV) Market Segmentation
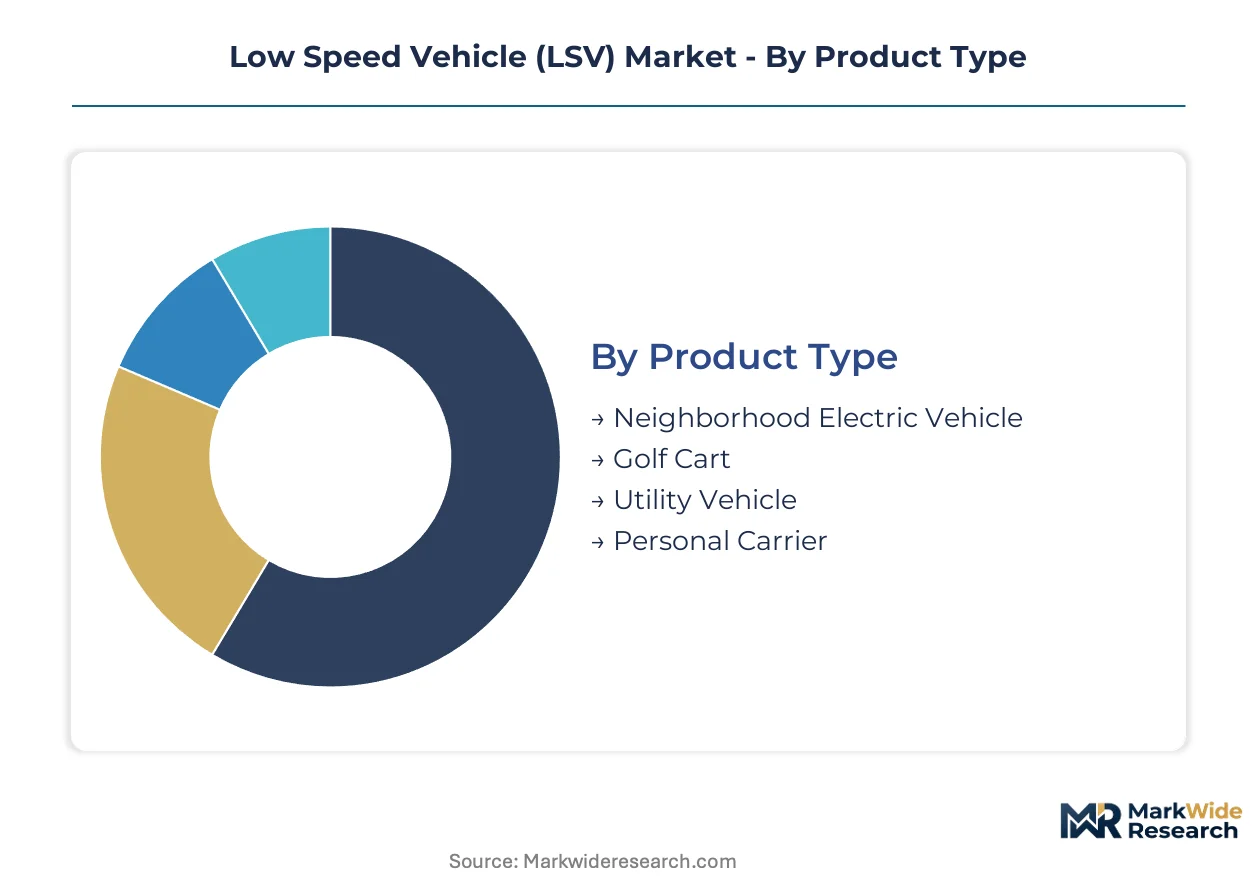
LSV procurement patterns diverge sharply across use cases, with fleet operators prioritizing total cost of ownership while individual buyers emphasize acquisition price. After-sales service intensity varies dramatically by segment, reshaping distributor economics and manufacturer channel strategy.
Product Type:
After-sales service intensity tracks directly with duty cycle severity and powertrain complexity across LSV categories.
- Utility Vehicle:Heavy-duty steel frames and modular cargo configurations support commercial payload ratings up to 1,200 pounds. Campus maintenance departments and municipal fleets in Texas and Florida are standardizing procurement around electric utility platforms to meet internal carbon targets.
- Golf Cart:Lightweight aluminum or composite bodies optimized for frequent stop-start operation on manicured turf. Replacement demand concentrates in the southeastern United States where course renovations and master-planned community expansions compress fleet turnover cycles.
- Neighborhood Electric Vehicle:Street-legal lighting and safety equipment packages compliant with NHTSA FMVSS 500.
- Personal Carrier:Compact two-to-four passenger configurations for resort and hospitality shuttles.
By volume, Golf Cart leads. By growth pace, Utility Vehicle is ahead.
Application:
Application-specific duty cycles determine battery chemistry selection and charging infrastructure requirements.
- Campus Transportation:High-utilization shuttle routes exceeding 40 miles daily drive lithium iron phosphate adoption. Universities in California and Massachusetts are bundling vehicle procurement with solar canopy charging installations.
- Commercial Delivery:Last-mile logistics configurations with refrigerated compartments or secure cargo boxes. Industrial parks in Georgia and Arizona are deploying electric utility fleets for intra-facility material movement.
- Golf Courses:Low-speed turf transport with specialized tire compounds minimizing ground compaction.
- Residential Use:Private ownership for gated community mobility and recreational property access.
Campus Transportation commands the highest service attachment rates. Commercial Delivery is expanding most quickly.
End User:
End-user sophistication determines specification complexity and contract structure preferences.
- Universities:Centralized fleet management offices negotiate multi-year procurement agreements with performance guarantees. Sustainability mandates at public institutions in Colorado and North Carolina are accelerating gasoline fleet phase-outs.
- Municipalities:Street-legal permitting authority and park maintenance operations create dual-use procurement requirements. Cities in Florida and California are consolidating parks and recreation vehicle purchases under climate action plans.
- Golf Clubs:Seasonal utilization patterns and member experience priorities influence replacement timing.
- Hospitality Industry:Brand-aligned vehicle aesthetics and guest shuttle reliability standards.
Municipalities represent the largest contract value per transaction. Universities are gaining share fastest.
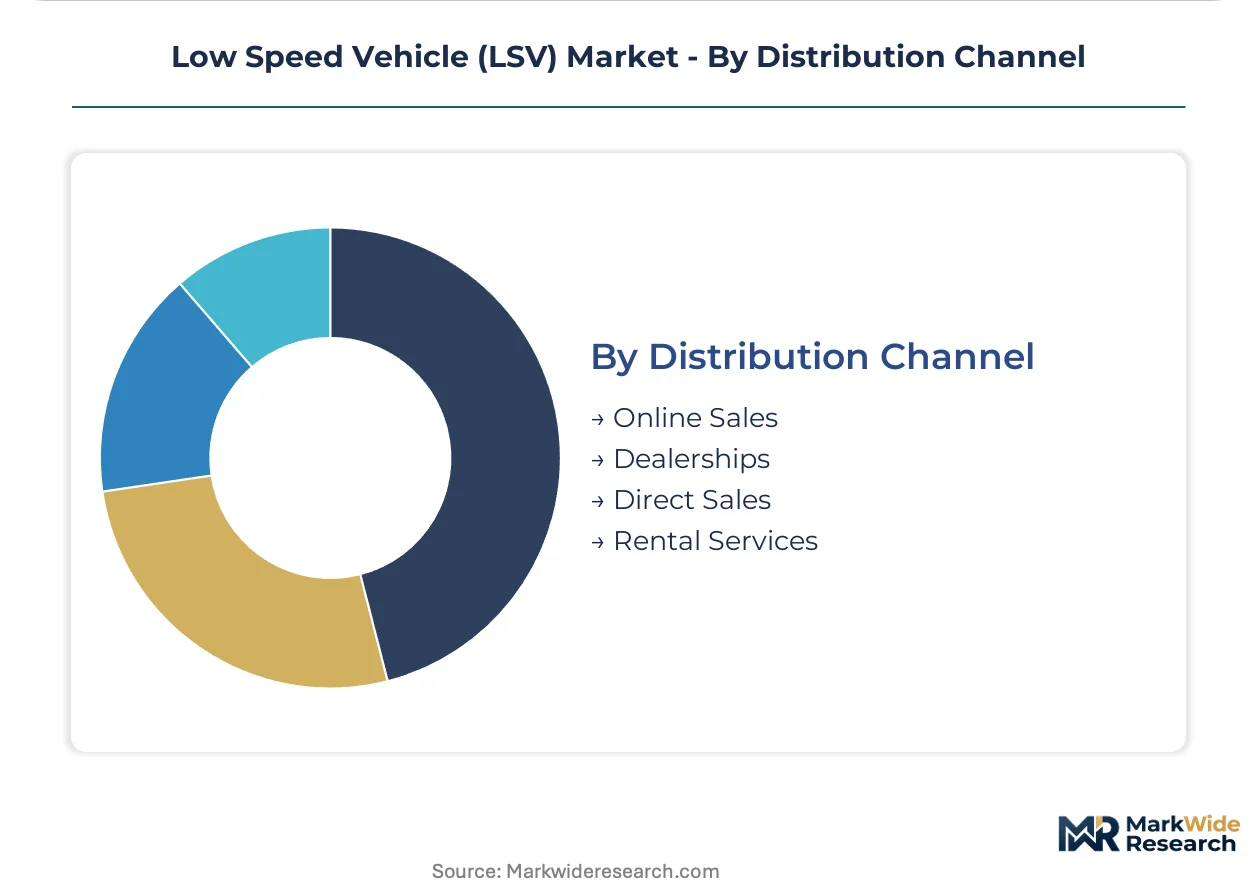
Distribution Channel:
Channel selection reflects buyer scale, technical sophistication, and service dependency.
- Direct Sales:National fleet operators negotiate factory-direct pricing with embedded maintenance contracts. Large university systems and municipal cooperatives in Texas bypass dealer networks to standardize specifications across multiple locations.
- Dealerships:Regional inventory stocking and field service capabilities support smaller fleet operators. Independent dealers in Florida and Arizona maintain golf cart rental fleets that feed replacement sales.
- Rental Services:Short-term access models for seasonal demand spikes and event-based requirements.
- Online Sales:Direct-to-consumer configurations with limited customization for residential buyers.
Dealerships handle the highest transaction volume. Direct Sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Campus fleets in the United States favor heavy-duty utility configurations, while European buyers prioritize compact autonomous-ready platforms for historic city centers. Japanese demand concentrates on precision-engineered personal carriers for resort hospitality. Indian procurement is industrial-first, with factory logistics outpacing leisure applications.
United States
Southeastern golf course renovations and master-planned community expansions drive replacement cycles in Florida and Georgia. NHTSA FMVSS 500 governs street-legal lighting and braking requirements, constraining speed ceilings to 25 mph. Austin and Raleigh campus clusters are consolidating electric utility procurement under carbon neutrality mandates.
Germany
Industrial park logistics and university medical center shuttles create dual-use demand for street-legal electric carriers. The EU AI Act and CE marking under the Machinery Directive shape autonomous development roadmaps. Stuttgart engineering clusters are prototyping solid-state battery integration for extended-range campus configurations.
Japan
Resort hospitality and senior care facility mobility anchor personal carrier demand with premium reliability specifications. METI safety standards and JIS certification requirements govern powertrain engineering protocols. Nagoya manufacturing corridors supply specialized drivetrain components to domestic and North American OEMs.
India
Export-zone factory automation and textile park logistics generate industrial utility vehicle demand outside traditional leisure segments. BIS certification and state-level electric vehicle incentives under the PLI scheme influence procurement timing. Tamil Nadu automotive corridors are assembling lithium iron phosphate packs for captive fleet deployments.
Mexico
Maquiladora capacity expansion for electric drivetrain assembly is reconfiguring North American supply chains. DGFT export licensing frameworks and local content requirements under USMCA shape component sourcing decisions. Nuevo León industrial parks are scaling battery module production for cross-border OEM integration.
Low Speed Vehicle (LSV) Market Competitive Landscape
Capability concentration sits with specialized powertrain engineers; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: recreational specialists with dealer networks, diversified machinery manufacturers with captive fleet relationships, and emerging electric-native entrants with subscription service models. Consolidation pressure is accelerating through strategic partnerships for battery certification and geographic expansion into underpenetrated industrial segments.
Among diversified industrial manufacturers, Textron, Yamaha Motor, and KUBOTA occupy positions spanning recreational and commercial archetypes. Textron exemplifies backward integration through composite body manufacturing. Yamaha Motor anchors the precision-engineered personal carrier segment. KUBOTA represents agricultural-industrial crossover capability into utility vehicle platforms.
| Leading Market Players |
|---|
| Textron |
| KUBOTA |
| Yamaha Motor |
| Deere & Company |
| The Toro Company |
| Club Car |
| Polaris |
| Columbia Vehicle |
| EVolution Electric Vehicles |
| Others |
Supply & Pricing Matrix
The Laredo-Colombia freight corridor's diesel surcharge volatility feeds directly into landed cost spreads between Chinese battery modules and Mexican-assembled packs, compressing margin buffers for distributors serving price-sensitive golf fleet operators while amplifying differentiation power for integrated manufacturers with captive Nuevo León production.
Pricing Analysis
Long-term offtake contracts dominate procurement between large university systems and Tier-1 OEMs, locking in volume commitments against lithium iron phosphate cell price indices. Three-tier pricing structure across premium, standard, and economy levels separates autonomous-ready campus shuttles with ISO 6469 certification from basic utility configurations and refurbished lead-acid golf carts. Cost compression in the economy tier is intensifying because flooded lead-acid substitution delays lithium conversion at municipal fleets with constrained capital budgets. Golf clubs exhibit the highest price sensitivity due to seasonal cash flow patterns, while research hospitals prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Extended payment terms from cathode active material processors in China are forcing non-Chinese assemblers to carry 90-day inventory exposure on lithium iron phosphate precursors. Supply concentrates in China for cathode processing, South Korea for electrolyte formulation, and Mexico for cross-border module assembly. The chain rests on refined cobalt sulfate, lithium carbonate, and copper foil inputs. Single-source vulnerability in Chinese export licensing creates disruption risk for North American OEMs without alternative qualification pathways. Distribution runs through regional dealer networks for golf and residential segments, shifting to factory-direct fulfillment for municipal and university fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution pressure from electric-native entrants bundling vehicle-as-a-service contracts with embedded charging infrastructure, eroding the traditional unit-sale economics that dealer networks depend upon.
For Market Incumbents: Entrench fleet relationships by embedding predictive maintenance algorithms into long-term service agreements, countering subscription-based entrants. Backward integration into battery module assembly in Nuevo León reduces exposure to Chinese export licensing friction. Prioritize ISO 6469 certification investment to disqualify lower-tier competitors from university RFPs requiring documented high-voltage safety conformity.
For New Entrants and Emerging Players: Build out vehicle-to-grid integration capabilities as a differentiated service layer for Texas municipal fleets seeking grid-services revenue. Indian industrial campuses present the most penetrable geography, with factory automation demand outpacing established supplier presence. Lead with fleet-as-a-service contracting rather than unit sales to bypass entrenched dealer relationships in saturated North American golf markets.
For Investors and Strategic Acquirers: Specialized powertrain engineering boutiques with JIS certification and METI relationships represent the most defensible acquisition archetype for Japanese and North American market access. Long-term viability hinges on battery chemistry flexibility and regulatory compliance bandwidth across multi-jurisdiction homologation requirements. Monitor BIS certification timelines for Indian market entry as an inflection signal for industrial segment penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term lithium iron phosphate offtake secures cell cost stability for Texas and California fleet deployments. |
| Backward Integration | In-house cathode processing in Nuevo León reduces Chinese export licensing exposure for cross-border OEMs. |
| Geographic Manufacturing Footprint | Tamil Nadu assembly capacity captures Indian industrial campus demand under PLI scheme incentives. |
| Platform Standardization | Unified chassis architecture across utility and personal carrier variants compresses development cycle timelines. |
| Charging Infrastructure Partnership | Solar canopy bundling with California university procurement meets carbon neutrality mandates. |
Research Methodology
Operator-level perspectives from fleet managers at Texas municipal cooperatives, California university sustainability officers, and Arizona golf course superintendents anchored the qualitative base. Primary interviews with OEM platform engineers, regional dealer principals, and battery certification specialists combined with secondary validation through NHTSA FMVSS 500 filings, EPA small spark-ignition engine compliance databases, and USMCA customs records. Bottom-up unit shipment estimates triangulated against top-down fleet procurement budget analysis across the projection horizon.
Scenario-bracketing framed the analytical approach, with base, upside, and downside cases reflecting lithium carbonate price trajectory assumptions and state-level street-legal ordinance adoption rates. Segmentation dimensions modeled include product type, application duty cycle, end-user sophistication tier, and distribution channel structure. CAGRs derived from logistic curve fitting to historical replacement cycle data, with campus carbon neutrality mandate intensity and master-planned community expansion permitting velocity as industry-specific forecast inputs.
Practitioners should monitor Chinese cathode export licensing decisions, EU AI Act implementation guidance for autonomous vehicle risk classification, and Indian PLI scheme capacity utilization thresholds for early signals of forecast deviation. The analysis reflects documented assumptions on battery chemistry substitution economics and regulatory harmonization timelines; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Low-Speed Electric Vehicle Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
United States RV Rental Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
Camping Trailer Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
Towable Tubes Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market