
 Mobile Liquid Tanks Market | 2026-2036
Mobile Liquid Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Liquid Tanks Market Analytics
ASME-certified pressure vessel specifications are redrawing competitive thresholds in mobile liquid containment. Chart Industries leverages in-house cryogenic engineering to sustain technology leadership in LNG transport segments. Taylor-Wharton anchors North American manufacturing scale through dedicated stainless steel fabrication facilities. INOXCVA dominates South Asian project logistics with customized cryogenic tank trailers for industrial gas distributors.
Mobile liquid tanks are pressure-rated or atmospheric vessels mounted on trailers, skids, or chassis for transporting and temporary storing liquids including fuels, chemicals, potable water, and cryogenic fluids; construction typically employs stainless steel or aluminum with multi-layer insulation and relief valve systems to maintain product integrity during transit. Fuel tanks lead type segmentation due to persistent demand from remote power generation and mining operations, while food-grade stainless steel variants command premium positioning in dairy and beverage logistics. Composite material adoption is accelerating in chemical transport applications where corrosion resistance and weight reduction intersect with stringent UN portable tank protocols.
US DOT hazardous materials regulations, UN Model Regulations on portable tanks, and EU ADR agreements collectively determine design codes, inspection intervals, and cross-border operating permissions for mobile liquid tank operators. EPA spill prevention requirements and OSHA workplace safety standards further constrain fleet deployment decisions in chemical and fuel handling environments. Stakeholders must monitor evolving carbon-border adjustment mechanisms and low-carbon fuel standards that will reshape material selection and refurbishment economics across tank manufacturing value chains.
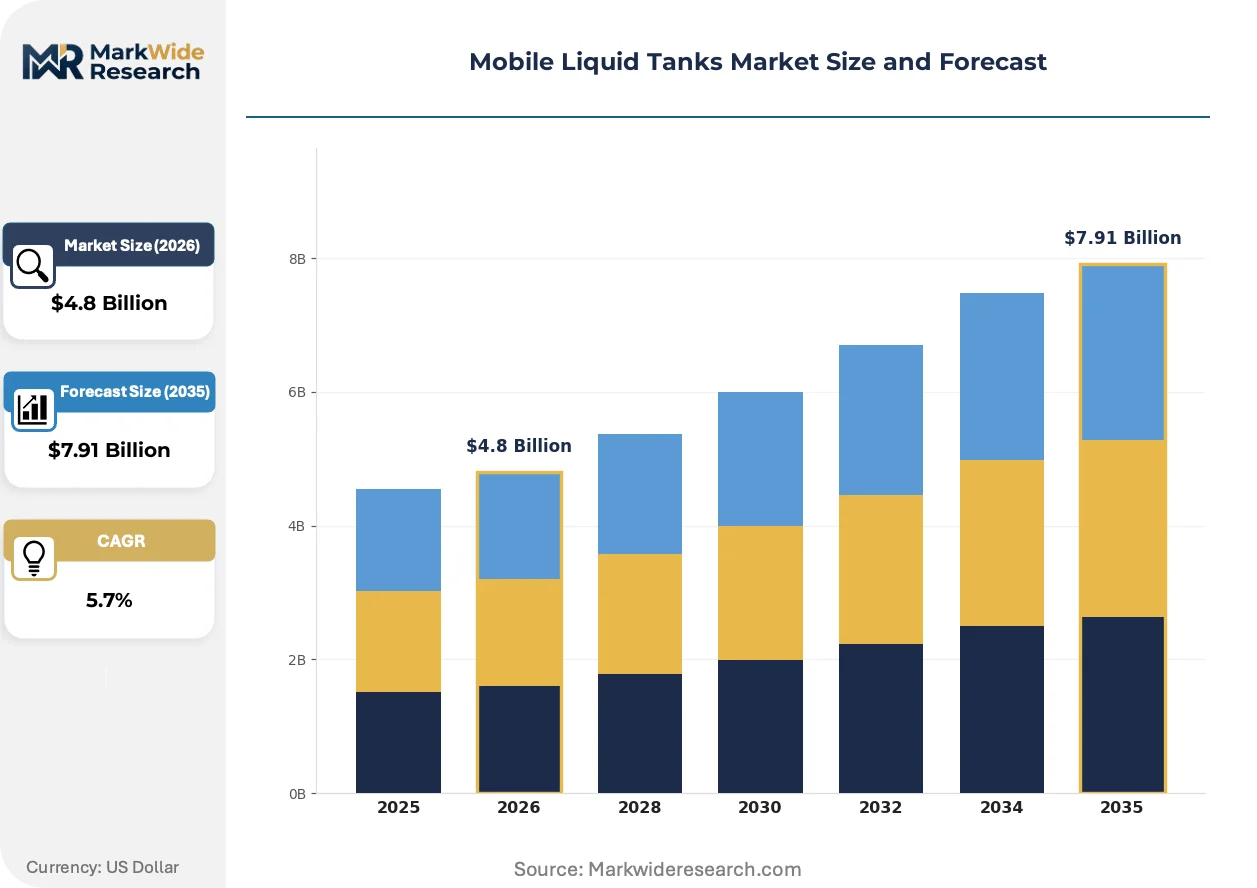
Market Dynamics
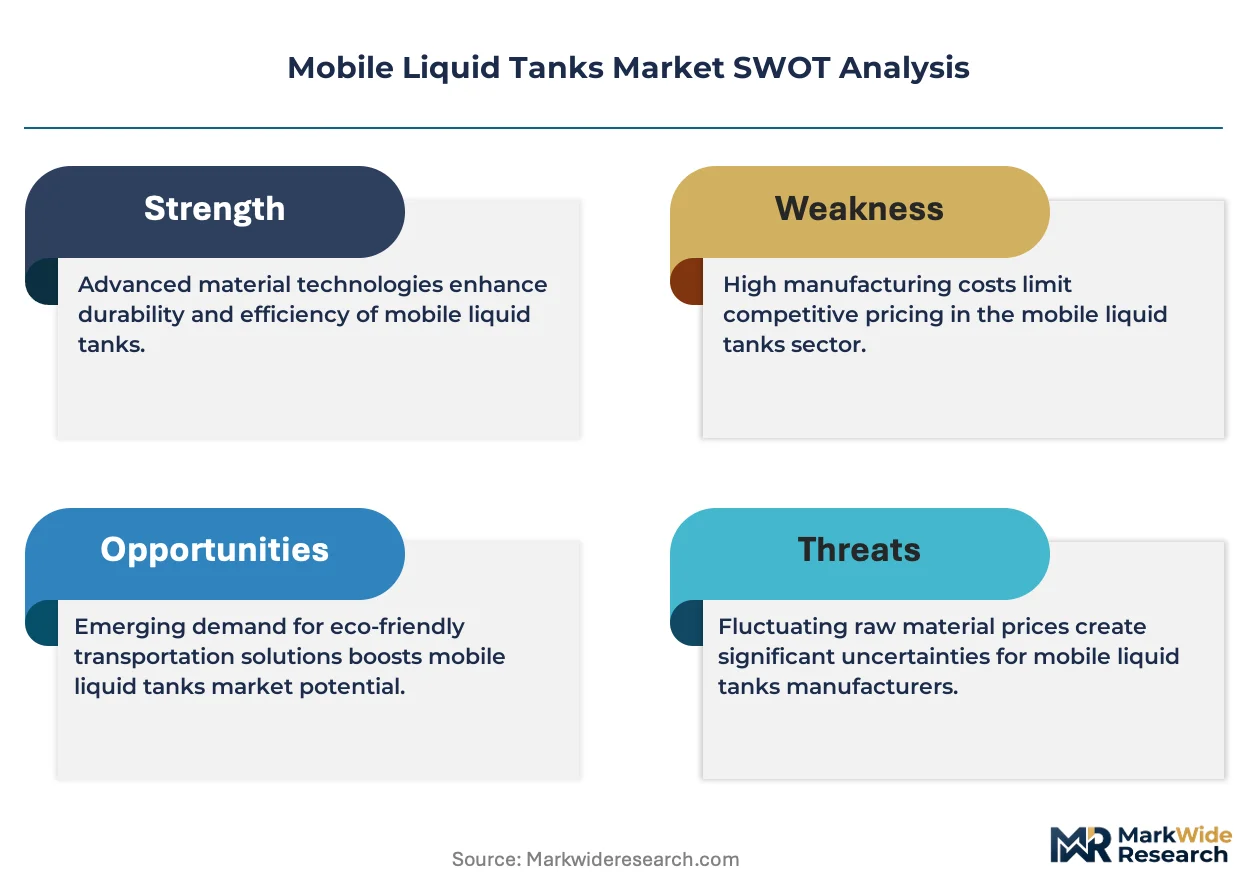
ASME certification requirements are compressing vendor margins while elevating technical barriers, forcing mid-scale fabricators to consolidate or exit as Tier-1 suppliers capture premium contract flows in cryogenic and chemical transport segments.
Growth Catalysts
- Permian Basin Frac Operations:Texas shale operators deploy rapid-deployment liquid storage to replace fixed infrastructure, generating pull-through demand for high-capacity mobile tanks with DOT-407 certification.
- EU Green Deal Methane Rules:Stricter leak detection mandates for LNG transport chains accelerate replacement of aging atmospheric vessels with sealed cryogenic systems across European industrial gas distribution.
- Composite Material Maturation:Carbon-fiber reinforced polymer tanks achieve UN portable tank approval for corrosive chemicals, opening weight-sensitive chemical logistics to mobile alternatives previously restricted to steel.
Market Restraints
- Stainless Steel Input Volatility:Nickel and molybdenum price swings compress fabrication margins, particularly for ASME-certified pressure vessels requiring 316L grade specifications.
- Certification Timeline Friction:US DOT and UN portable tank recertification cycles create fleet downtime that operators cannot monetize, extending payback periods on specialized chemical transport assets.
- Stationary Tank Substitution:Modular bolted tank farms at wellpad sites capture mid-duration storage demand that mobile units previously served in oilfield logistics.
Strategic Opportunities
- India Industrial Gas Expansion:Cryogenic tank trailer demand from steel and healthcare sectors outpaces domestic fabrication capacity, creating import substitution openings for certified foreign suppliers.
- Carbon Border Adjustment Mechanisms:EU CBAM compliance requirements favor low-carbon stainless steel sourcing, rewarding tank manufacturers with verified supply chain emissions documentation.
- Hydrogen Transport Protocol Convergence:ISO 19881 and SAE J2601 standard alignment for gaseous hydrogen trailers enables cross-certification economies for manufacturers serving multiple regional codes.
Industry Challenges
- ASME Code Welder Scarcity:Qualified pressure vessel welders command 40% wage premiums, constraining expansion timelines for fabrication facilities serving oil and gas logistics.
- Multi-Jurisdiction Compliance Burden:Simultaneous DOT, ADR, and UN certification requirements fragment engineering resources and delay product launches for cross-border chemical transport operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Liquid Tanks Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fuel Tanks, Chemical Tanks, Water Tanks, Food-Grade Tanks Material: Stainless Steel, Aluminum, Plastic, Composite End User: Agriculture, Oil & Gas, Construction, Government Application: Transportation, Storage, Distribution, Fire Suppression |
| Companies Covered | Cryofab, Inc., TransTech Energy, Chart Industries, Taylor-Wharton, Cryolor, Linde Engineering, Wessington Cryogenics, Manchester Tank & Equipment Co., INOXCVA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Liquid Tanks Market Evolving Landscape
Digital monitoring integration and material science advances are restructuring competitive advantage around real-time asset visibility and extended service intervals rather than pure manufacturing scale.
Multi-layer vacuum insulation systems are decomposing the traditional tradeoff between hold time and payload capacity in cryogenic transport. LNG distributors in the US Gulf Coast now specify 45-day hold durations for intermodal tank containers, compressing the addressable market for conventional foam-insulated trailers. This performance tier is consolidating procurement decisions around engineering-intensive suppliers with in-house vacuum expertise.
REACH chemical registration requirements are forcing reformulation of tank interior coatings and seal materials for European chemical logistics operators. Manufacturers must now document full material composition down to 0.1% concentration thresholds, extending qualification timelines for new tank designs. The coatings segment is responding with fluoropolymer alternatives that preempt SVHC listing risks.
Leasing structures are displacing outright purchase for frac water and flowback containment assets in North American shale plays. Mid-size operators now prefer per-day tank rental with maintenance inclusion, transferring residual value risk to fleet owners. This preference shift concentrates demand with national rental platforms possessing balance sheet capacity for 10-year asset depreciation cycles.
Mobile Liquid Tanks Market Segmentation
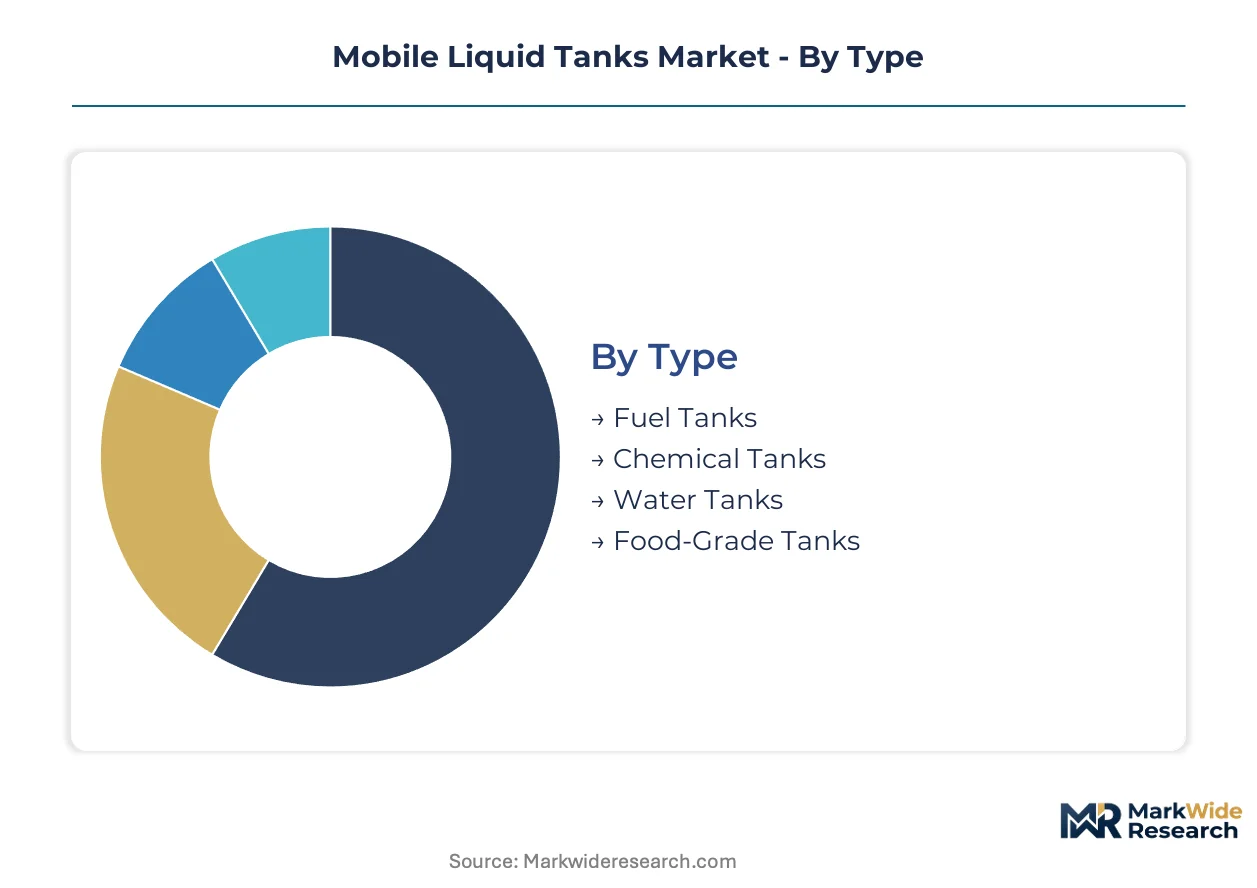
Mobile liquid tank procurement decisions fragment across four independent axes, each carrying distinct certification burdens and margin profiles. Fabricators must align production capacity with the intersection of material specifications and end-use regulatory intensity rather than pursuing horizontal coverage.
Type:
Fuel tanks face the most acute substitution pressure from modular bolted tank farms and stationary containment systems at wellpad sites, forcing mobile suppliers to differentiate through rapid-deployment certification and intermodal compatibility.
- Fuel Tanks:DOT-407 and UN portable tank certification for diesel, gasoline, and aviation fuel transport. Demand concentrates in Texas Permian Basin frac operations where operators replace fixed infrastructure with rapid-deployment mobile storage. EPA spill prevention requirements constrain fleet deployment decisions for remote power generation and mining logistics.
- Chemical Tanks:ASME pressure vessel specifications with corrosion-resistant interior coatings for acids, caustics, and industrial solvents. REACH chemical registration mandates in Europe force reformulation of seal materials and coating compositions down to 0.1% concentration thresholds.
- Water Tanks:Atmospheric vessels for potable and non-potable liquid transport in municipal and emergency response applications. OSHA workplace safety standards govern handling protocols for construction and disaster relief deployments.
- Food-Grade Tanks:316L stainless steel construction with sanitary fittings for dairy, beverage, and edible oil logistics. FDA food contact surface regulations and USDA dairy equipment standards determine inspection intervals and cleaning validation requirements.
Fuel tanks anchor the volume base while food-grade tanks gain share at the steepest rate.
Material:
Cost tier stratification separates premium alloy specifications from commodity-grade alternatives, with certification-grade stainless steel commanding 40% fabrication cost premiums over aluminum in pressure vessel applications.
- Stainless Steel:304 and 316L grades dominate ASME-certified pressure vessels for chemical and food-grade transport. Nickel and molybdenum price volatility compresses margins for fabricators serving oil and gas logistics with corrosion-resistant specifications.
- Aluminum:Lightweight alloys for fuel and water transport where payload optimization outweighs corrosion resistance requirements. UN portable tank protocols limit aluminum deployment in certain chemical classifications due to reactivity concerns.
- Plastic:Polyethylene and cross-linked polymer tanks for agricultural and non-hazardous chemical applications. Lower capital cost positions plastic for seasonal demand patterns in irrigation and fertilizer distribution.
- Composite:Carbon-fiber reinforced polymer construction achieving UN portable tank approval for corrosive chemicals. Weight reduction opens chemical logistics segments previously restricted to steel tankage.
Stainless steel retains the dominant revenue share while composite materials expand most quickly in weight-sensitive chemical transport.
End User:
Application maturity varies sharply across customer types, with oil and gas operators driving specification innovation while government procurement remains tethered to legacy DOT-406 designs.
- Oil & Gas:Rapid-deployment liquid storage for frac water, flowback containment, and drilling fluid logistics. Leasing structures displace outright purchase for mid-size operators seeking per-day tank rental with maintenance inclusion.
- Agriculture:Seasonal demand for fertilizer, pesticide, and irrigation water transport. Plastic tank configurations dominate due to cost sensitivity and lower utilization rates compared to commercial fleet operations.
- Construction:Fuel and water logistics for remote site operations. OSHA workplace safety standards constrain fleet deployment in chemical handling environments.
- Government:Emergency response, military, and municipal procurement with extended specification cycles. FEMA and defense logistics requirements prioritize interoperability over performance optimization.
Oil and gas anchors procurement volume while agriculture shows the steepest expansion trajectory in developing markets.
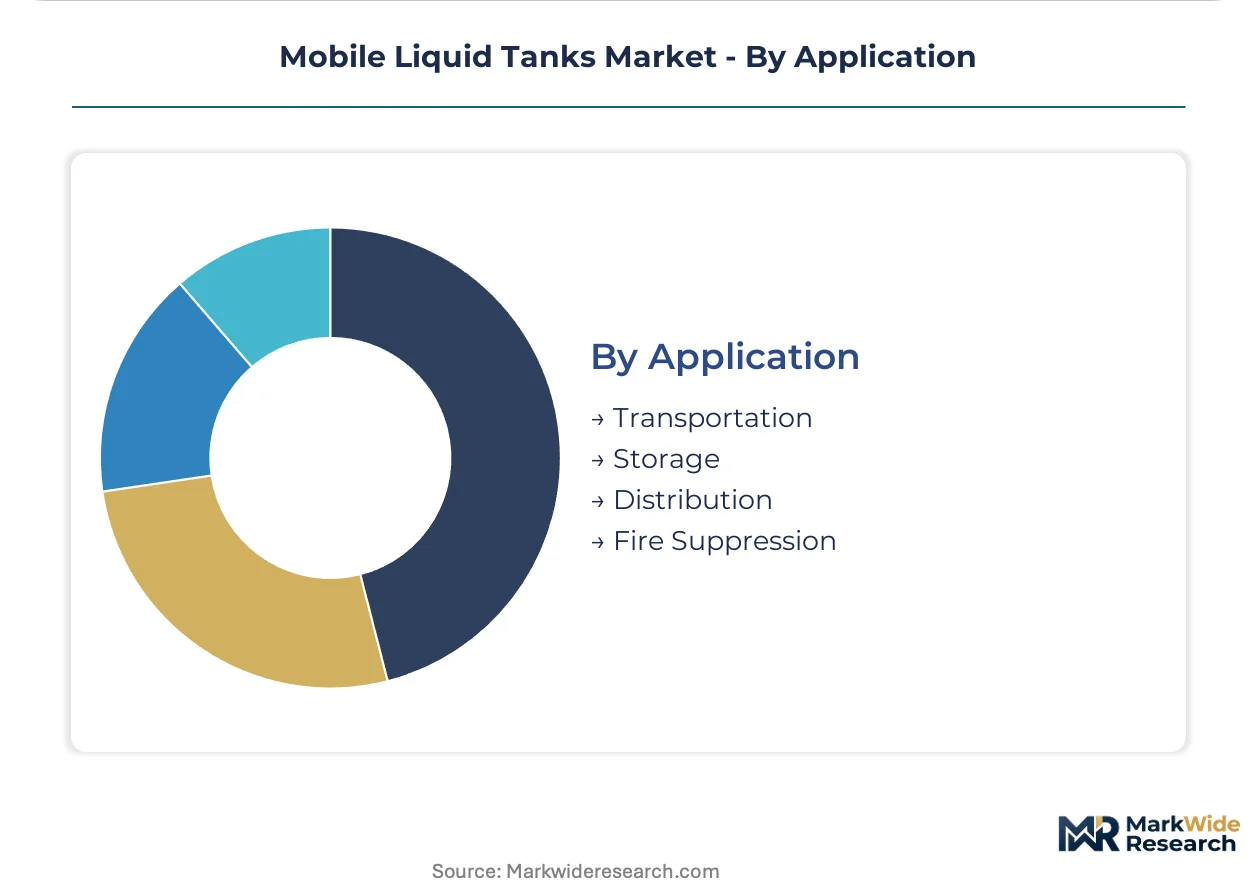
Application:
Customer type concentration shapes margin structure, with transportation applications consolidating around national fleet operators while storage demand fragments across regional rental platforms.
- Transportation:Highway and intermodal liquid movement requiring DOT, ADR, and UN certification alignment. Multi-jurisdiction compliance burdens fragment engineering resources for cross-border chemical operators.
- Storage:Temporary containment at wellpad sites, industrial facilities, and emergency response locations. Modular bolted tank farms capture mid-duration demand previously served by mobile units.
- Distribution:Last-mile liquid delivery for industrial gas, fuel, and chemical supply chains. Cryogenic tank trailers for LNG and industrial gases require vacuum insulation expertise.
- Fire Suppression:Specialized water and foam concentrate transport for municipal and wildfire response. NFPA standards govern tank configuration and pumping system integration.
Transportation commands the dominant revenue share while storage applications face the most severe substitution pressure from stationary alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in cryogenic equipment are redirecting fabrication capacity toward demand centers with certified welder availability. The United States runs a structural deficit in specialized tank trailers, while India and Germany maintain surplus positions in ASME-certified pressure vessels.
United States
Permian Basin frac water logistics and Gulf Coast LNG export terminals drive procurement of DOT-407 and cryogenic-certified mobile tanks. EPA spill prevention requirements constrain fleet deployment timelines for chemical transport operators. Houston anchors domestic fabrication capacity, though ASME code welder scarcity extends delivery schedules for pressure vessel orders.
Germany
Industrial gas distribution networks and chemical export corridors sustain demand for ADR-certified tank trailers with extended hold times. EU Green Deal methane regulations accelerate replacement of atmospheric vessels with sealed cryogenic systems. The Rhine-Ruhr industrial cluster concentrates engineering expertise for multi-jurisdiction certification alignment.
India
Steel sector expansion and healthcare oxygen logistics outpace domestic cryogenic tank trailer fabrication capacity. BIS certification requirements and PLI scheme incentives favor import substitution by foreign suppliers with verified ASME documentation. Gujarat's industrial corridor hosts project logistics hubs serving petrochemical and pharmaceutical distribution chains.
China
Dual carbon goals and hydrogen transport infrastructure investments reshape material specifications for mobile pressure vessels. GB standards alignment with ISO protocols enables cross-certification economies for export-oriented fabricators. The Yangtze River Delta concentrates stainless steel processing capacity for chemical-grade tank construction.
United Arab Emirates
Port-centric liquid logistics and regional fuel distribution hubs generate demand for rapid-deployment storage solutions. MOHAP and civil defense regulations govern tank configuration for emergency response applications. Dubai's Jebel Ali free zone facilitates re-export of certified equipment to African and South Asian markets.
Mobile Liquid Tanks Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage dimensions. The vendor base stratifies into three tiers: integrated cryogenic engineering houses, regional stainless steel fabricators, and rental platform operators with captive fleet assets. Consolidation pressure concentrates in mid-scale ASME shops facing nickel price volatility and welder wage premiums. Dominant competitive moves include backward integration into stainless steel supply chains and technology licensing for vacuum insulation systems.
Within the cryogenic engineering tier, Chart Industries and Taylor-Wharton exemplify integrated fabrication models with in-house vacuum expertise. INOXCVA occupies a position representing South Asian project logistics specialization. These three anchors illustrate divergent strategic postures: North American scale, European certification breadth, and emerging market customization capability.
| Leading Market Players |
|---|
| Cryofab, Inc. |
| TransTech Energy |
| Chart Industries |
| Taylor-Wharton |
| Cryolor |
| Linde Engineering |
| Wessington Cryogenics |
| Manchester Tank & Equipment Co. |
| INOXCVA |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Permian Basin operators and mobile tank fleet owners lock in both stainless steel supply access and price visibility across volatile nickel cycles. These arrangements transfer commodity price risk to fabricators while securing dedicated capacity for DOT-407 certified assets.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. ASME-certified pressure vessels command substantial premiums over atmospheric tankage due to qualified welder scarcity and extended certification timelines. Cost compression in standard-grade fuel tanks is intensifying because modular bolted tank farms capture mid-duration storage demand. National rental platforms show least price sensitivity due to captive fleet depreciation cycles, while mid-size shale operators exhibit highest sensitivity driving per-day rental preferences.
Supply Chain Analysis
Inventory cycles for 316L stainless steel coil extend delivery timelines for ASME-certified orders beyond atmospheric tank fabrication. Supply concentrates in China, India, and Germany for cryogenic-grade stainless steel processing. Fabrication draws from nickel, molybdenum, and specialized vacuum insulation panel inputs. Single-source vulnerability runs through qualified ASME code welder pools constraining expansion. Distribution runs through project logistics hubs serving oilfield and industrial gas corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated national rental platforms with multi-year fleet deployment commitments, fragmenting procurement influence among independent operators.
For Market Incumbents:Fortify ASME certification depth against emerging composite tank entrants achieving UN portable tank approval for corrosive chemicals. Deepen backward integration into stainless steel supply chains to offset nickel price volatility. Prioritize vacuum insulation R&D to extend cryogenic hold times beyond 45-day thresholds specified by Gulf Coast LNG distributors.
For New Entrants and Emerging Players:UN portable tank fast-track certification for carbon-fiber reinforced polymer construction opens weight-sensitive chemical logistics previously restricted to steel tankage. Target India's industrial gas expansion where domestic cryogenic fabrication capacity lags steel and healthcare demand. Pursue white-label manufacturing partnerships with established South Asian project logistics specialists lacking in-house composite expertise.
For Investors and Strategic Acquirers:Regional stainless steel fabricators with captive ASME welder pools and verified low-carbon supply chain documentation represent prime acquisition targets for EU CBAM compliance positioning. Long-term viability hinges on certification moat sustainability against composite material maturation. Monitor ISO 19881 and SAE J2601 convergence for hydrogen transport as inflection signal for cross-certification economies.
| Strategic Initiative | Industry Significance |
|---|---|
| ASME Certification Expansion | Deepens regulatory moats against composite entrants in pressure vessel segments. |
| Backward Integration into Stainless Supply | Captures margin from nickel volatility while securing 316L grade access. |
| Vacuum Insulation Technology Licensing | Monetizes engineering expertise for 45-day hold duration specifications. |
| Composite Material Qualification | Opens UN portable tank approval pathways for weight-sensitive chemical transport. |
| India Manufacturing Footprint | Addresses cryogenic tank trailer deficit serving steel and healthcare oxygen demand. |
Research Methodology
Desk research of customs trade databases, ASME certification registries, and EPA spill prevention filings preceded structured interviews with mobile tank fleet operators, pressure vessel procurement managers at oilfield service companies, cryogenic engineering directors, and stainless steel distribution channel heads. Secondary validation drew from DOT hazardous materials enforcement data, UN Model Regulation revision notices, and SEC 10-K disclosures from listed fabrication groups. Bottom-up unit economics triangulated against top-down regional demand aggregation.
Variance decomposition across type, material, end user, and application dimensions structured the analytical framework over the projection horizon. Modeled segmentation captured fuel, chemical, water, and food-grade tank categories intersecting with stainless steel, aluminum, plastic, and composite material specifications. CAGRs derived from installation base growth, replacement cycle acceleration, and specification upgrade premiums. Forecast inputs incorporated Permian Basin frac water logistics intensity and EU methane regulation compliance timelines.
Decision-makers should treat outputs as directional under sustained nickel price volatility and qualified welder availability assumptions; material deviation would warrant model refresh. Specific risk factors include REACH chemical registration reformulation costs and carbon border adjustment mechanism documentation requirements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Composite Bearings Market
Vehicle Components
Wheel Seals Market
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market
Vehicle Components
Charge Air Coolers Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
India Automotive Steering System Market
Vehicle Components
Trailer Spindles Market
Vehicle Components
Hydrostatic Transmission Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Precision Bearing Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Truck Suspension System Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Front Forks Market
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market