
 Global Boat Trailers Market | 2026-2036
Global Boat Trailers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Boat Trailers Market Intelligence
The generational shift in skilled welders and aluminum fabricators is unwinding traditional manufacturing workflows for trailer chassis. EZ Loader leverages its extensive dealer network across North America to maintain market presence. Karavan Trailers differentiates through its focus on galvanized and aluminum options for specific hull types. TRACKER anchors its sales by packaging trailers directly with its own line of fishing boats, creating a closed-loop supply for its customers.
A boat trailer is a specialized unpowered vehicle designed to transport watercraft over land. Key designs incorporate adjustable bunks or rollers to support the boat's hull, with axle capacities and braking systems rated for specific gross vehicle weight ratings. In terms of application, recreational boating constitutes the largest segment, driving sales for private owners. Material selection is critical, with galvanized steel offering a cost-effective solution and aluminum alloy commanding a premium for its superior corrosion resistance in saltwater environments.
Trailer safety and construction standards are governed by national bodies like the US National Highway Traffic Safety Administration (NHTSA) and Germany's Kraftfahrt-Bundesamt (KBA). These regulations, along with China's GB standards for road vehicles, mandate specific lighting, braking, and load-bearing requirements. Manufacturers must now decide whether to invest in advanced composite materials or further optimize aluminum designs to meet future weight and durability expectations.
Market Dynamics
The primary structural force is the tension between advancements in lightweight materials, like aluminum alloys and composites, and the persistent shortage of skilled labor required for high-quality fabrication. This dynamic, particularly in welding and chassis assembly, shapes production capacity and influences material choices across the industry.
Growth Catalysts
- Lightweight Materials:Aluminum alloy adoption improves tow vehicle fuel efficiency and offers superior corrosion resistance, extending trailer life in saltwater environments.
- Recreational Boating:High participation in recreational boating, especially in coastal hubs, creates a continuous stream of first-time and replacement trailer buyers.
- Infrastructure Projects:Public investment in new boat ramps and marinas expands waterway access, stimulating demand for personal boat transport solutions.
Market Restraints
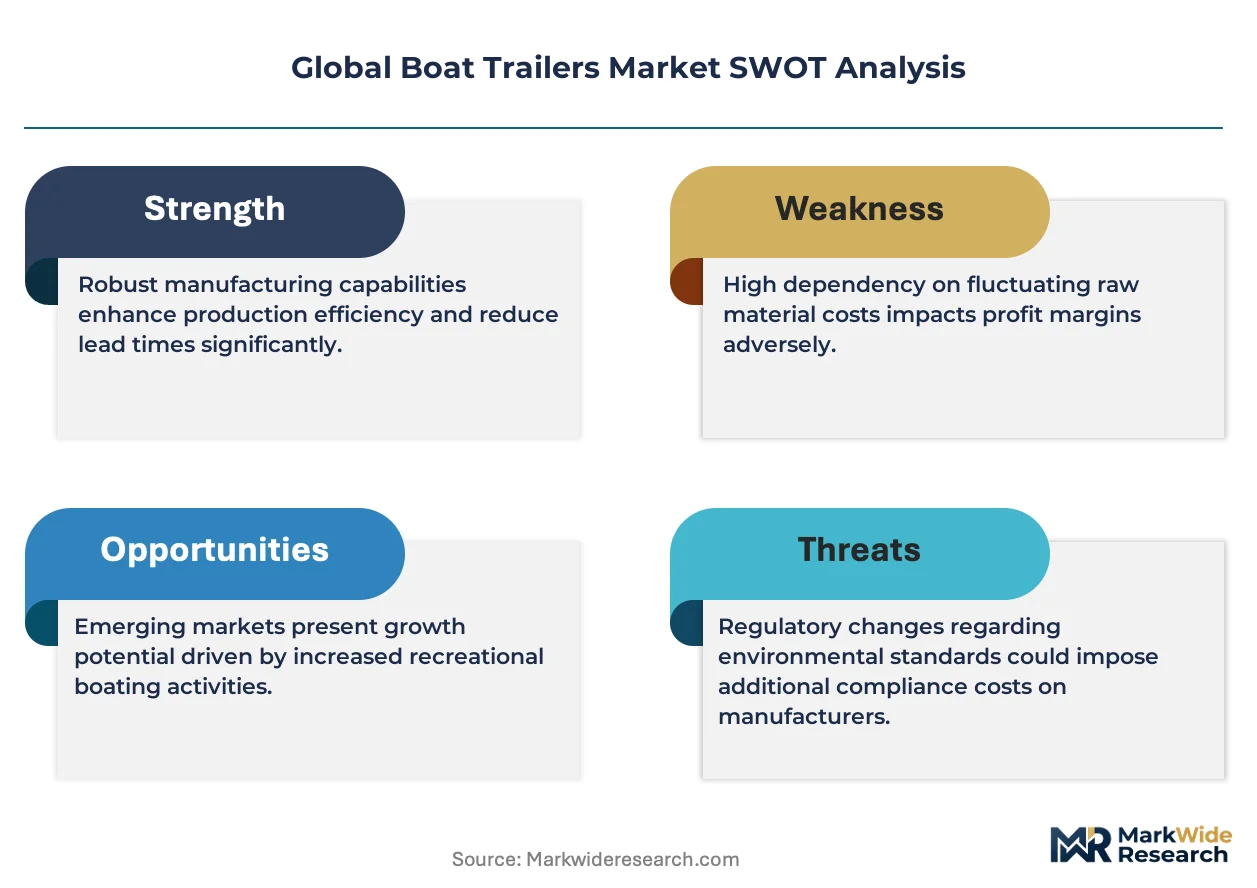
- Input Cost Volatility:Price fluctuations for raw materials, specifically galvanized steel and aluminum, directly impact manufacturer margins and final product pricing.
- Skilled Labor Scarcity:A shortage of certified welders and aluminum fabricators constrains production capacity and increases labor costs for trailer manufacturers.
- Regulatory Fragmentation:Navigating disparate safety standards from bodies like the US NHTSA, Germany's KBA, and China's GB standards adds complexity and cost.
Strategic Opportunities
- Emerging Markets:Untapped demand for recreational boating in Southeast Asia and Latin America presents significant growth potential for trailer manufacturers.
- Smart Trailer Integration:Incorporating IoT sensors for tire pressure monitoring, lighting diagnostics, and bearing temperature alerts creates a new premium feature set.
- Niche Watercraft:Designing specialized trailers for the growing personal watercraft (PWC) and kayak segments opens new markets beyond traditional boats.
Industry Challenges
- Fabrication Skill Gap:The widening gap in skilled aluminum welders and fabricators creates production bottlenecks and challenges quality control for complex chassis designs.
- Compliance Burden:Adhering to evolving international road safety regulations, including specific braking and lighting mandates from bodies like NHTSA and KBA, requires continuous R&D investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Boat Trailers Market |
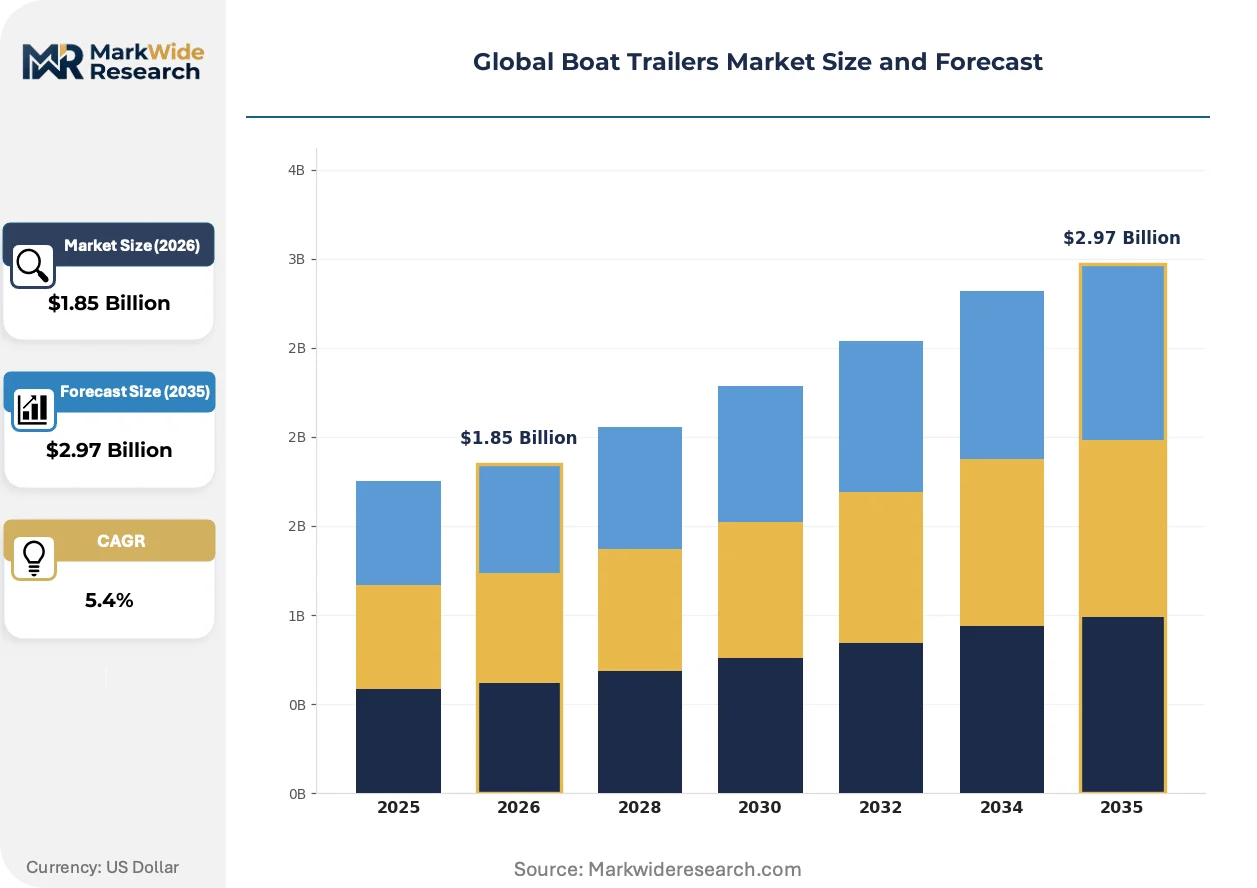
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bunk Trailers, Roll-On Trailers, Pontoon Trailers, Tandem Axle Trailers, Single Axle Trailers Material: Galvanized Steel, Aluminum Alloy, Stainless Steel, Composite Materials, Wooden Frame Application: Recreational Boating, Fishing Expeditions, Water Sports, Marine Transportation, Rental Services End User: Boat Rental Companies, Marina Operators, Water Sports Centers, Fishing Charter Businesses, Private Owners |
| Companies Covered | EZ Loader, Load Rite, Kropf Industrial Inc., Triton Trailers, Karavan Trailers, HOSTAR Marine Transport Systems, TRACKER, Midwest Industries Inc., TRIGANO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Boat Trailers Market Strategic Shifts & Innovations
Material science innovations and tightening safety regulations are the principal forces reshaping product development in the boat trailer industry. These pressures compel manufacturers to balance performance enhancements with new compliance mandates, influencing design and cost structures.
Advanced composite materials are emerging for non-structural components like fenders, offering weight savings and design flexibility. High-performance boat owners are the primary early adopters, seeking aesthetic and performance advantages. This adoption is bifurcating the market, creating a premium tier focused on advanced materials while the mainstream sector optimizes aluminum and steel.
The US National Highway Traffic Safety Administration (NHTSA) is enforcing stricter rules for trailer braking systems, particularly for higher gross vehicle weight ratings. This forces manufacturers to integrate more reliable electric-over-hydraulic brake actuators over older surge brake designs. Trailers for boats over 20 feet are most affected, requiring significant engineering updates to meet compliance.
Online direct-to-consumer (DTC) sales channels are disrupting traditional distribution, with buyers using web-based configurators to order custom trailers. This model bypasses the limited inventory of local marine dealerships for specialized hull or axle configurations. The trend is most visible in North America, where a mature market supports consumer demand for tailored solutions.
Global Boat Trailers Market Segmentation
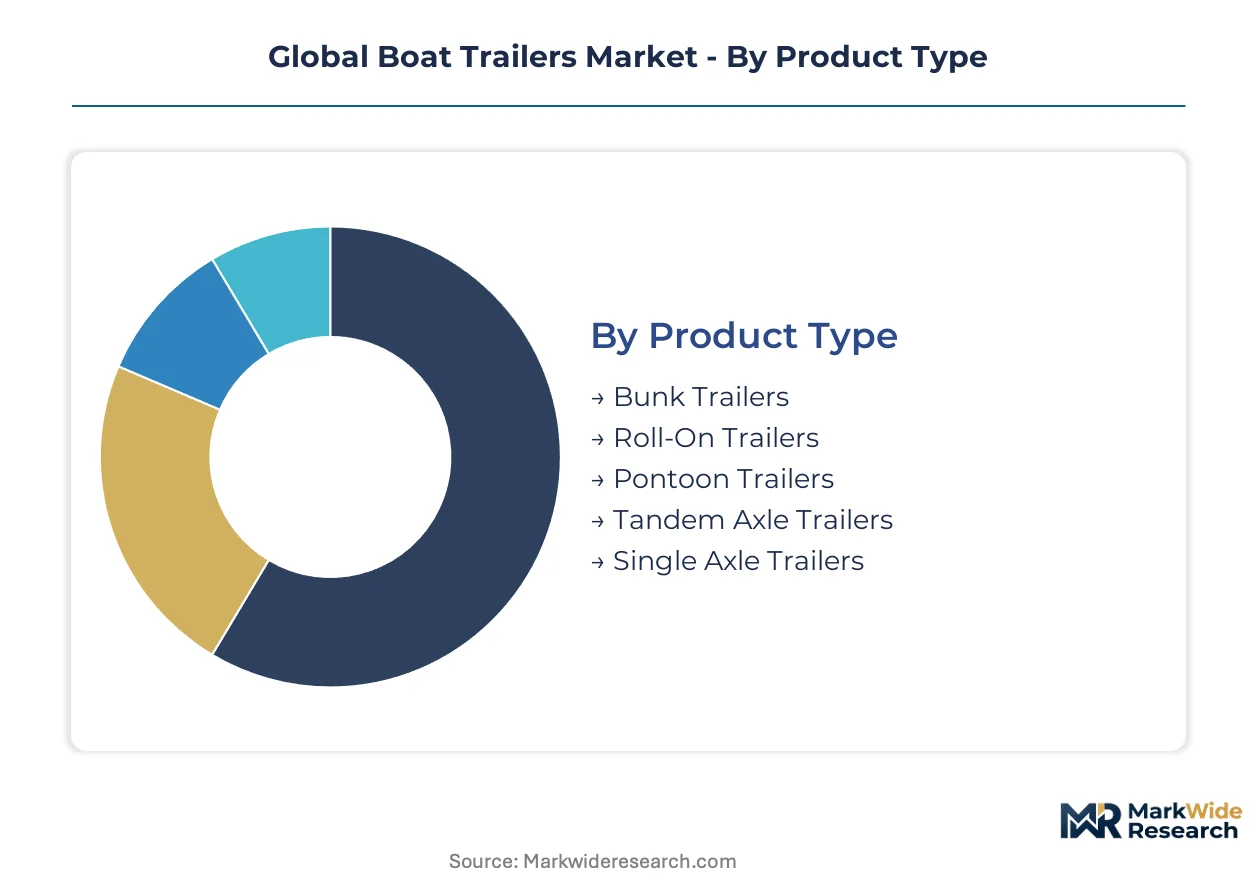
The Global Boat Trailers Market segmentation provides a structured view of product diversity, material innovations, and end-user demands shaping the industry. Understanding these distinct categories helps manufacturers align production with specific market needs and regulatory compliance.
Product Type:
Regulatory frameworks often differentiate boat trailer product types based on their load-bearing capacity and required braking systems.
- Tandem Axle Trailers:These trailers offer enhanced stability and higher load capacity, often required for transporting larger and heavier boats exceeding specific weight thresholds. US National Highway Traffic Safety Administration (NHTSA) regulations frequently mandate braking systems on all axles for trailers over 3,000 lbs Gross Vehicle Weight Rating.
- Single Axle Trailers:Characterized by their simpler design and lighter weight, these units are ideal for transporting smaller boats over shorter distances. Many single-axle configurations fall below the thresholds for mandatory braking systems in various jurisdictions, which can reduce the initial purchase cost.
- Bunk Trailers:These trailers provide continuous support along the boat's hull, making them suitable for long-term storage and accommodating a wide range of hull designs.
- Roll-On Trailers:Equipped with a series of rollers, these trailers facilitate easier loading and unloading of boats, particularly advantageous for heavier vessels and frequent use.
- Pontoon Trailers:Specifically engineered with central bunks or cradles, these trailers are designed to securely transport the unique multi-hull structure of pontoon boats.
Single Axle Trailers handle the majority of throughput; Tandem Axle Trailers are the fastest mover on share.
Material:
Material selection for boat trailers is primarily driven by a balance of initial cost, longevity, and environmental exposure.
- Aluminum Alloy:This material offers superior corrosion resistance, making it ideal for saltwater environments and significantly reducing the overall trailer weight. Demand from high-performance boat owners in coastal regions like Florida strongly influences sales.
- Galvanized Steel:Providing a cost-effective and robust solution, galvanized steel offers good corrosion resistance through its zinc coating. This material remains a popular choice for freshwater applications and for buyers seeking a durable, budget-conscious option.
- Composite Materials:Lightweight and offering design flexibility, these materials are increasingly utilized for non-structural components such as fenders.
- Stainless Steel:Valued for its premium corrosion resistance, stainless steel is frequently employed for hardware, fasteners, and specific structural components rather than entire chassis.
- Wooden Frame:A traditional material, wooden frames are now largely superseded by advanced metal alloys due to concerns regarding durability and maintenance requirements.
Galvanized steel production remains concentrated in established industrial regions; aluminum alloy fabrication is expanding with specialized welding capabilities.
Application:
The volume of boat trailer sales directly correlates with the activity levels across various maritime applications.
- Recreational Boating:This segment represents the largest application, encompassing personal leisure activities such as cruising, fishing, and weekend excursions. High participation rates in coastal tourism hubs, including the Australian Gold Coast, significantly stimulate this demand.
- Fishing Expeditions:This application demands robust and reliable trailers capable of transporting fishing boats to diverse and often remote launch sites. The segment prioritizes extreme durability and ease of launch in varied environmental conditions.
- Water Sports:This category supports trailers specifically designed for transporting watercraft associated with activities like wakeboarding, waterskiing, and personal watercraft (PWCs).
- Marine Transportation:Involves the use of larger, specialized trailers for the commercial movement of vessels or oversized recreational boats between locations.
- Rental Services:Utilizes a diverse fleet of versatile trailers to support boat rental operations, catering to a wide array of customer needs and boat types.
Private owners dominate the recreational boating segment; commercial operators drive demand in marine transportation.
End User:
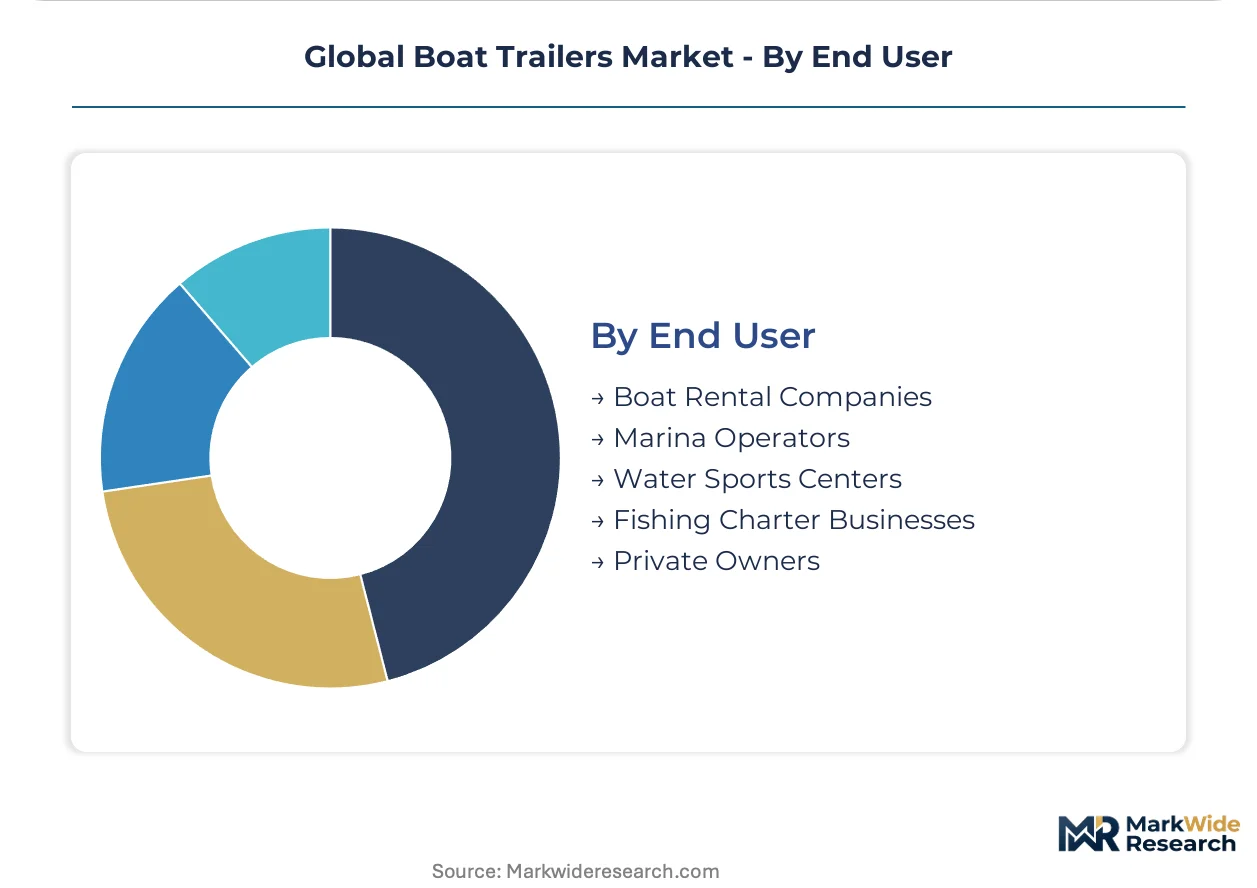
End-user segments exhibit varying purchasing behaviors, influencing trailer specifications and manufacturer margins.
- Private Owners:This group constitutes the largest customer base, acquiring trailers for their personal recreational vessels. Demand from private owners is particularly robust in regions characterized by high disposable income and extensive access to waterways.
- Boat Rental Companies:These businesses purchase fleets of durable, easily maintainable trailers to support their diverse rental inventories. Their procurement decisions heavily prioritize longevity, operational efficiency, and low maintenance costs.
- Marina Operators:Marina operators frequently acquire trailers for moving boats within their facilities, offering storage solutions, or facilitating various service and maintenance operations.
- Water Sports Centers:These centers require specialized trailers for efficiently transporting smaller craft such as personal watercraft and wake boats to launch points.
- Fishing Charter Businesses:These enterprises invest in heavy-duty trailers capable of reliably transporting larger fishing vessels to various launch and retrieval locations.
The private owner segment is mature and established; boat rental companies represent an expanding commercial opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for boat trailers exhibits varied patterns across global regions, driven by distinct recreational boating cultures and regulatory landscapes. In North America, private ownership of diverse watercraft fuels a robust market for specialized trailers. European markets emphasize compliance with stringent safety standards for both leisure and commercial applications.
United States
Recreational boating drives significant trailer demand across the United States, particularly in coastal states. The US National Highway Traffic Safety Administration (NHTSA) enforces stricter rules for trailer braking systems, impacting higher gross vehicle weight ratings. Florida's extensive coastline and numerous marinas support a dense network of marine dealerships and specialized trailer fabricators.
Germany
Leisure boating on numerous lakes and rivers generates consistent demand for boat trailers in Germany. The Kraftfahrt-Bundesamt (KBA) mandates rigorous safety and construction standards for all road-legal trailers. Northern Germany's port cities and manufacturing hubs concentrate on producing durable, compliant trailer chassis for both domestic and export markets.
Australia
Coastal tourism and a high concentration of private boat owners fuel strong trailer sales across Australia. State-level road transport regulations govern trailer specifications, including lighting and load-bearing requirements. The Gold Coast region in Queensland, a major recreational boating hub, sees significant activity among trailer manufacturers and retailers.
China
Emerging recreational boating markets and a growing commercial marine transport sector create new opportunities in China. The country's GB standards for road vehicles dictate specific lighting, braking, and load requirements for trailers. Coastal industrial zones, especially within the Yangtze River Delta, are expanding their capacity for boat trailer fabrication to meet domestic needs.
Brazil
Extensive inland waterways and a long coastline support a nascent but growing recreational boating market in Brazil. National traffic regulations (CONTRAN) establish guidelines for trailer dimensions, braking, and safety features. Southeastern Brazil, particularly states like São Paulo, is witnessing the development of local trailer manufacturing to serve increasing demand.
Global Boat Trailers Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the global boat trailers market. This structure combines established manufacturers offering diverse product lines with niche providers focusing on specific boat types or material innovations. Key strategic archetypes include large-scale producers providing comprehensive solutions and specialized fabricators catering to premium or unique market segments. Companies predominantly pursue geographic expansion and product portfolio diversification to capture market share and enhance their competitive positioning.
Among North American manufacturers, EZ Loader exemplifies a wide distribution network, maintaining market presence through extensive dealer relationships across diverse geographic regions. Karavan Trailers occupies a position focused on material specialization, adeptly offering both galvanized steel and premium aluminum options tailored for specific hull types and usage environments. TRACKER anchors its sales strategy by packaging trailers directly with its own line of fishing boats, creating a comprehensive, closed-loop supply for its customer base seeking integrated solutions.
| Leading Market Players |
|---|
| EZ Loader |
| Load Rite |
| Kropf Industrial Inc. |
| Triton Trailers |
| Karavan Trailers |
| HOSTAR Marine Transport Systems |
| TRACKER |
| Midwest Industries Inc. |
| TRIGANO Group |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized aluminum components directly influence manufacturer pricing power, especially for custom configurations requiring skilled fabrication. This dynamic arises from a limited pool of certified welders and fabricators, impacting production capacity and final product costs for advanced trailer designs.
Pricing Analysis
Contract-based pricing for large fleet orders coexists with transactional pricing for individual trailer sales in this market. Material choice, specifically between aluminum alloy and galvanized steel, drives price differentiation, alongside the level of customization offered through online configurators. Pricing pressure stems from input cost volatility for raw materials like steel and aluminum, impacting manufacturer margins. Private owners purchasing entry-level single-axle trailers exhibit higher price sensitivity, while high-performance boat owners prioritize features over initial cost.
Supply Chain Analysis
Just-in-time inventory strategies are difficult to maintain for complex components, leading manufacturers to hold strategic stockpiles of critical materials. Geographic supply concentration includes China for basic components, Germany for advanced braking systems, and the United States for specialized fabrication. Raw material dependencies include galvanized steel, aluminum alloys, and specialized braking system components. Skilled labor scarcity, particularly for aluminum welding, creates a structural risk for production bottlenecks. Distribution runs through established dealer networks, increasingly supplemented by direct-to-consumer online channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The boat trailer market offers significant service-attach opportunities. Smart trailer integration, with its IoT sensors providing diagnostic data, represents a faster-growing recurring revenue stream than the underlying hardware sales.
For Market Incumbents: Secure access to skilled labor through apprenticeship programs and automation investments to counter the ongoing fabrication skill gap. Acquire niche manufacturers specializing in advanced composite materials to diversify product offerings and meet evolving durability expectations. This defends against the threat of direct-to-consumer disruptors offering specialized solutions. Invest in R&D for electric-over-hydraulic braking systems to meet stricter NHTSA regulations.
For New Entrants and Emerging Players: Certification fast-track for new material applications, such as advanced composites for non-structural components, offers a market entry point. Target the growing personal watercraft (PWC) and kayak segments, which remain under-served by traditional trailer manufacturers. Leverage online direct-to-consumer models with web-based configurators to offer tailored solutions, bypassing established dealer networks. Emerging markets in Southeast Asia present significant untapped demand for basic trailer solutions.
For Investors and Strategic Acquirers: Long-term, this sits as a durable goods play, offering stable returns tied to recreational boating participation over the next decade. Target mid-sized specialized fabricators with strong intellectual property in lightweight material designs or advanced braking technologies for acquisition. The signal to watch is the increasing stringency of international road safety regulations, such as those from the KBA and NHTSA, which will force smaller players to consolidate or exit.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Automation | Automated welding reduces reliance on scarce skilled labor, improving production efficiency and quality control. |
| Expand Direct-to-Consumer Channels | Online configurators enable customization, reaching a broader customer base beyond traditional marine dealerships. |
| Develop Smart Trailer IoT Solutions | Integrating sensors for diagnostics creates new premium features and potential recurring revenue streams for manufacturers. |
| Acquire Niche Fabrication Expertise | Consolidating specialized aluminum or composite fabricators enhances material innovation capabilities and market reach. |
| Strengthen International Regulatory Compliance | Adhering to diverse standards like NHTSA and KBA opens new export markets and ensures product legality across regions. |
Research Approach
A standing panel of trailer manufacturers, marine dealership owners, recreational boat owners, and regulatory body representatives provided ongoing calibration. This involved combining primary interviews with industry stakeholders and secondary validation from sources like NHTSA safety reports, KBA vehicle specifications, and industry association reports. Bottom-up and top-down triangulation ensured data accuracy.
Consistency checks against external benchmarks validated all volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including product type, material, application, end user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and projected market drivers, incorporating inputs such as recreational boating participation rates and raw material price forecasts.
Decision-makers should treat outputs as directional under current macroeconomic conditions; material deviation would warrant model refresh. Forecasts reflect assumptions regarding stable raw material supply and consistent regulatory enforcement. Revision becomes warranted when significant shifts in raw material prices or new international safety standards cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Throttle Cable Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Steering Column Module Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Canada Automotive Carbon Fiber Composites Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Bicycle Chain Device Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Global Car Accessories Market