
 Railway Vehicle Coupler Market | 2026-2036
Railway Vehicle Coupler Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Vehicle Coupler Market Insights
Freight operators is bifurcating from passenger rail as the dominant buyer archetype in coupler procurement. Wabtec Corporation leverages its North American installed base to sustain aftermarket revenue streams. Dellner Couplers anchors European high-speed contracts through specialized automatic coupler engineering. Knorr-Bremse competes across both freight and passenger segments with integrated braking-coupler systems.
A railway vehicle coupler is a mechanical device engineered to connect rolling stock, typically manufactured from high-grade steel or aluminum alloys with fatigue-rated castings and precision-machined locking mechanisms, enabling safe transmission of tensile and compressive forces between wagons or coaches. Automatic couplers now dominate new-build procurement across freight transport applications where interoperability mandates and crew safety regulations eliminate manual coupling operations. Composite materials represent the fastest-growing material segment as manufacturers seek weight reduction for high-speed passenger transport without sacrificing impact resistance. Steel retains margin concentration in heavy-haul freight where durability requirements override lightweighting priorities.
The Federal Railroad Administration enforces mechanical safety standards that dictate coupler strength ratings and inspection intervals across United States rail networks. The European Union Agency for Railways coordinates EN 15566 and TSI freight wagon standards that mandate automatic coupler migration timelines. China's National Railway Administration applies GB standards that require domestic compatibility with CRRC Qingdao Sifang's platform designs. Stakeholders must monitor regulatory divergence between automatic coupler specifications as interoperability investments risk stranding without cross-border standardization.
Market Dynamics
The EU's F-Gas Regulation and EN 15566 standards are compressing migration timelines for automatic coupler adoption, forcing fleet operators across Germany, France, and Poland into accelerated capital deployment cycles.
Growth Catalysts
- Heavy-haul freight renewal:North American operators are replacing legacy Janney couplers in bulk procurement waves to meet Federal Railroad Administration mechanical safety mandates.
- High-speed rail corridor expansion:China's GB standards for domestic compatibility are driving platform-standardized coupler demand along Beijing-Shanghai and Chengdu-Chongqing routes.
- Composite material advancement:Aluminum-titanium hybrid castings are penetrating passenger rail segments where weight reduction directly correlates to energy efficiency gains.
Market Restraints
- Specialized steel input volatility:High-grade alloy steel prices fluctuate with nickel and chromium supply constraints, squeezing margin structures for heavy-haul coupler manufacturers.
- Regional supply concentration:Precision-machined locking mechanism production clusters in Germany's Ruhr industrial belt, creating single-source vulnerability for European procurement.
- Interoperability specification divergence:China's GB standards and EU EN 15566 employ incompatible electrical connector pin configurations, fragmenting cross-border automatic coupler investment.
Strategic Opportunities
- India's dedicated freight corridor buildout:The Dedicated Freight Corporation's electrified routes require automatic coupler retrofits on 1,500+ km of new track, opening procurement windows for specialized engineering.
- Sensor-integrated predictive maintenance:IoT-enabled coupler health monitoring converges with automatic coupling systems to create bundled service revenue streams.
- Poland's TSI compliance acceleration:EU cohesion funding for rail modernization is channeling automatic coupler subsidies to Polish freight operators ahead of 2030 mandates.
Industry Challenges
- Certification timeline compression:EN 15566 Type 10 automatic coupler approval cycles now exceed 18 months, delaying fleet deployment schedules.
- Welding technician scarcity:Fatigue-rated casting repair and precision weld certification programs cannot replenish retiring skilled labor pools in Germany and the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Vehicle Coupler Market |
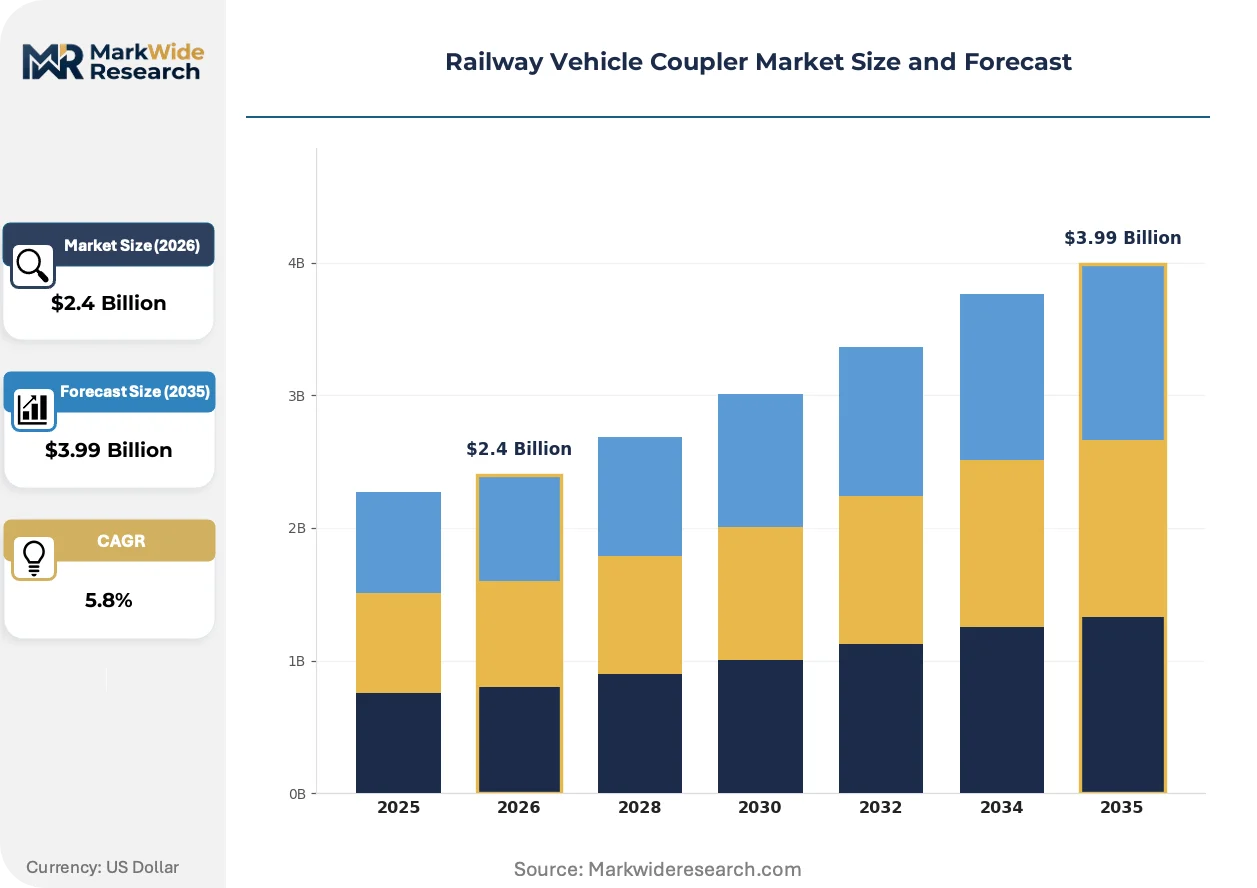
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Couplers, Semi-Automatic Couplers, Manual Couplers, Specialized Couplers Material: Steel, Aluminum, Composite Materials, Plastic Application: Freight Transport, Passenger Transport, Maintenance, Special Operations End User: Railway Operators, Maintenance Providers, OEMs, Infrastructure Companies |
| Companies Covered | Knorr-Bremse, Wabtec Corporation, Dellner Couplers, Voith, CRRC Qingdao Sifang, Huatie Tongda High-speed Railway, Amsted Rail Company, Nippon Steel Corporation, Irwin Car and Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Vehicle Coupler Market Trends and Innovations
Digitalization of coupler diagnostics and material science breakthroughs are restructuring competitive differentiation, shifting value capture from hardware durability toward integrated system intelligence and lifecycle service models.
Composite-reinforced aluminum coupler bodies are supplanting traditional steel castings in European high-speed passenger applications. SNCF and Deutsche Bahn procurement specifications now prioritize these hybrid structures for TGV and ICE fleet renewals. The shift is compressing supplier qualification barriers for non-traditional material specialists while eroding incumbent steel foundry market position.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based pneumatic systems is forcing coupler actuator redesigns across freight wagon standards. Manufacturers must substitute electromechanical alternatives or sealed nitrogen systems to maintain automatic coupling functionality. German freight operators face the steepest compliance curve given their concentration of legacy pneumatic infrastructure.
Asset-light service contracting is displacing traditional equipment purchase models among North American Class I railroads. Union Pacific and BNSF now source coupler systems through availability-based agreements where suppliers retain ownership and perform predictive maintenance. This restructuring concentrates procurement authority with specialized system integrators and marginalizes component-only vendors.
Railway Vehicle Coupler Market Segmentation
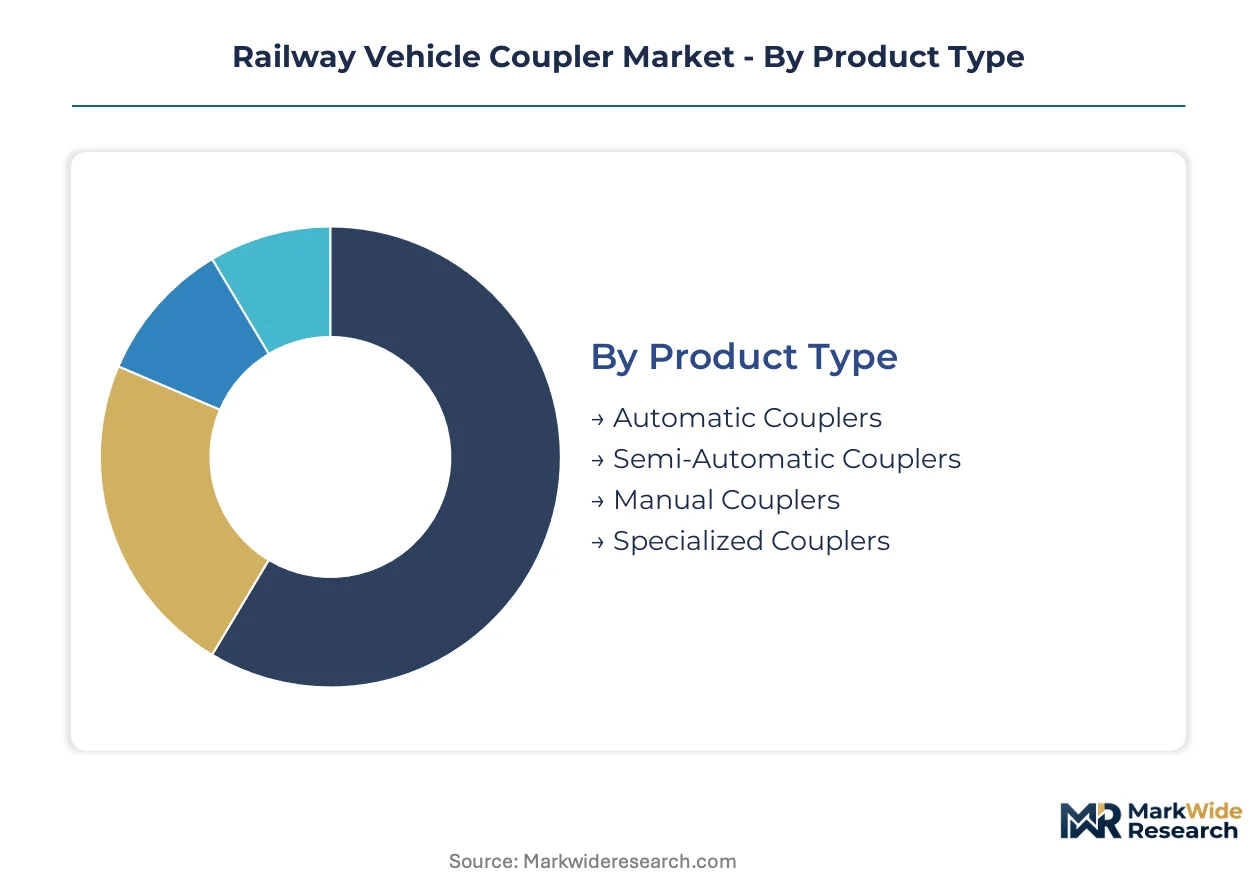
Railway coupler procurement splits sharply between regulatory-mandated automatic systems and legacy manual equipment. Material selection and end-user archetype further stratify supplier relationships and margin structures across freight and passenger applications.
Product Type:
The EU F-Gas Regulation and EN 15566 standards mandate automatic coupler migration timelines, while Federal Railroad Administration mechanical safety rules in the United States enforce strength ratings that favor specific coupling architectures.
- Automatic Couplers:Electromechanical or pneumatic systems enable remote-controlled coupling without crew intervention between rolling stock. Freight operators across Germany, France, and Poland face compressed capital deployment cycles under EU interoperability mandates.
- Semi-Automatic Couplers:Hybrid designs require partial manual engagement while automating mechanical locking functions. These systems dominate transitional fleet retrofits where operators balance upgrade costs against full automatic compatibility requirements.
- Manual Couplers:Traditional link-and-pin or screw couplings demand direct crew handling during train assembly. Legacy installations persist in maintenance yards and specialized industrial spurs where low-frequency coupling justifies retention.
- Specialized Couplers:Custom-engineered variants address narrow-gauge railways, mining operations, and military transport with non-standard gauge or load requirements.
Established volume favors Automatic Couplers; emerging adoption favors Semi-Automatic Couplers.
Material:
Cost tier differentiation separates premium alloy formulations from commodity-grade alternatives, with weight-critical applications commanding substantial material premiums.
- Steel:High-grade alloy castings with fatigue-rated microstructures dominate heavy-haul freight where impact resistance and wear durability override mass considerations. Nickel and chromium supply constraints squeeze margin structures for manufacturers serving North American bulk commodity corridors.
- Aluminum:Lightweight extrusions and castings reduce unsprung mass in high-speed passenger applications. Deutsche Bahn and SNCF procurement specifications prioritize aluminum-titanium hybrid structures for ICE and TGV fleet renewals.
- Composite Materials:Fiber-reinforced polymer matrices bonded to metallic substructures deliver strength-to-weight ratios exceeding conventional alloys. This segment gains share fastest in Asian high-speed networks where energy efficiency targets drive material substitution.
- Plastic:Engineering polymer components serve secondary coupling functions, buffer housings, and electrical connector enclosures where structural loads remain minimal.
Steel retains margin concentration in freight; aluminum and composites climb fastest in passenger specifications.
Application:
Customer type bifurcation splits procurement between asset-owning operators and third-party service providers with divergent lifecycle cost horizons.
- Freight Transport:Heavy-haul bulk commodity and intermodal container operations require couplers rated for extreme tensile loads and repetitive impact cycles. Union Pacific and BNSF availability-based contracting models reshape supplier relationships toward integrated service provision.
- Passenger Transport:High-speed and commuter rail demand precision-machined couplers with integrated electrical and pneumatic pass-through connections. China's GB standards for CRRC Qingdao Sifang platform compatibility standardize coupler specifications across Beijing-Shanghai corridor deployments.
- Maintenance:Workshop equipment and test rig applications utilize standardized coupler interfaces for rolling stock diagnostics and repair verification.
- Special Operations:Military transport, disaster relief, and temporary track installations employ rapid-deployment coupler systems with simplified installation protocols.
Freight Transport commands procurement volume; Passenger Transport drives technology premium extraction.
End User:
Supply concentration in Germany's Ruhr industrial belt for precision-machined locking mechanisms creates sourcing vulnerability that shapes procurement risk management across end-user categories.
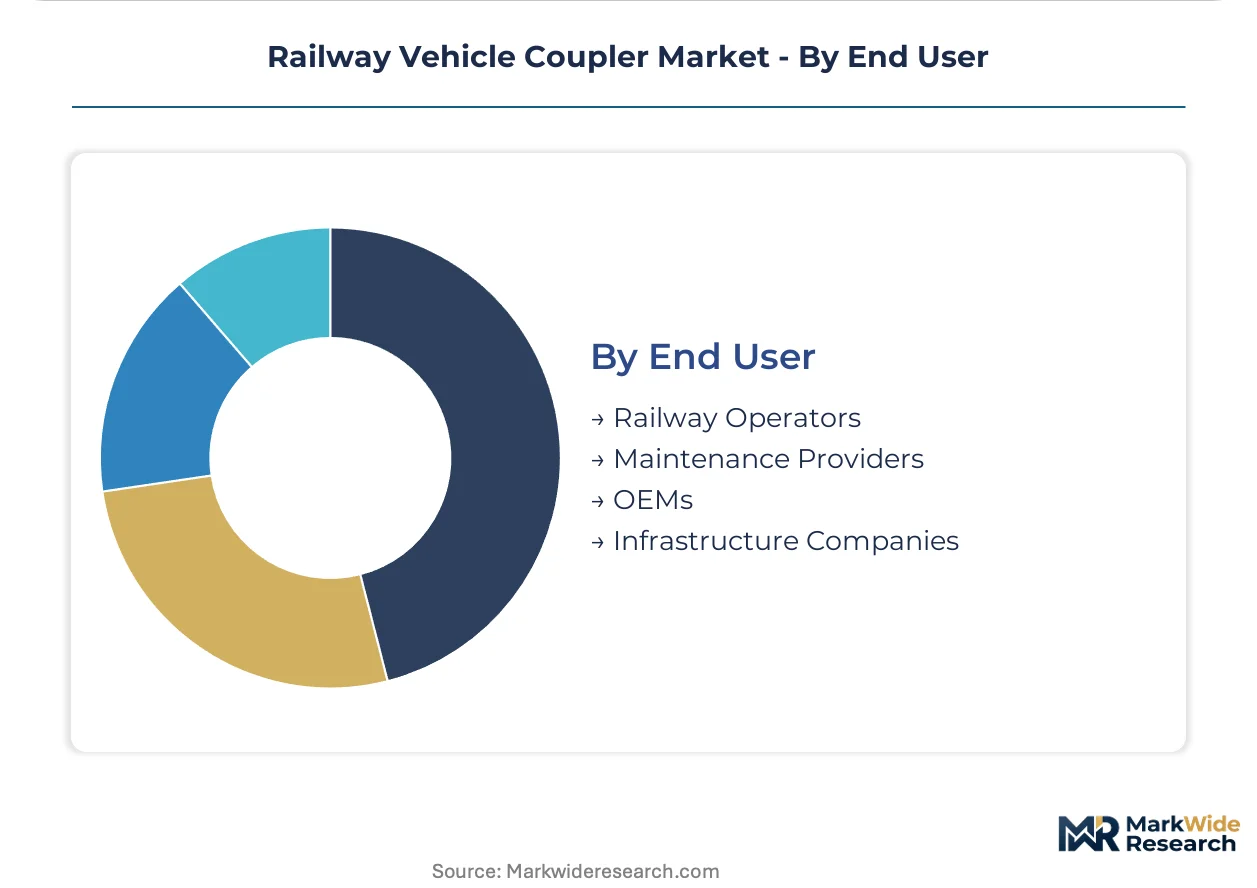
- Railway Operators:Class I railroads and national passenger carriers hold direct procurement authority for fleet-wide coupler specifications. These stakeholders increasingly mandate predictive maintenance integration and lifecycle service bundling.
- Maintenance Providers:Independent repair shops and OEM-authorized service networks source replacement couplers and refurbishment components. Technician scarcity for fatigue-rated casting repair limits expansion capacity in Germany and the United States.
- OEMs:Rolling stock manufacturers integrate coupler systems during new-build production, with platform standardization requirements from CRRC and Alstom constraining supplier selection.
- Infrastructure Companies:Track owners and terminal operators procure specialized couplers for maintenance-of-way equipment and yard infrastructure.
Railway Operators concentrate procurement authority; Maintenance Providers fragment volume across distributed service networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-machined automatic coupler systems to freight operators across Poland and France under compressed EU migration timelines. Chinese manufacturers supply platform-standardized couplers for high-speed corridors throughout Southeast Asia. North American rail networks source heavy-haul replacement units from domestic foundries serving Union Pacific and BNSF procurement waves.
United States
Class I railroads deploy bulk replacement programs for legacy Janney couplers across bulk commodity corridors. The Federal Railroad Administration enforces mechanical safety standards that dictate strength ratings and inspection intervals. Pittsburgh-based foundries concentrate heavy-haul casting production for Union Pacific availability-based contracting models.
Germany
Deutsche Bahn mandates aluminum-titanium hybrid couplers for ICE fleet renewals under energy efficiency targets. The EU F-Gas Regulation and EN 15566 standards compress automatic coupler migration timelines for freight operators. The Ruhr industrial belt hosts precision-machined locking mechanism production for European TSI compliance.
China
CRRC Qingdao Sifang platform designs drive standardized coupler demand along Beijing-Shanghai and Chengdu-Chongqing high-speed routes. The National Railway Administration applies GB standards requiring domestic compatibility across rolling stock procurement. Qingdao manufacturing clusters supply automatic coupler systems for export throughout Southeast Asian rail modernization programs.
Poland
Freight operators accelerate automatic coupler retrofits ahead of 2030 TSI mandates using EU cohesion funding channels. The European Union Agency for Railways coordinates EN 15566 compliance timelines across member state fleets. Silesian industrial zones concentrate workshop capacity for transitional semi-automatic coupler installations.
India
The Dedicated Freight Corporation electrifies 1,500+ km of new track requiring automatic coupler retrofits for heavy-haul operations. The Ministry of Railways channels capital deployment toward interoperability-compliant rolling stock. Gujarat manufacturing hubs produce coupling systems for domestic freight corridor buildout and neighboring Bangladesh export contracts.
Railway Vehicle Coupler Market Competitive Landscape
Listed leaders compete with private specialists across technology integration depth and service model architecture. The vendor base separates into three tiers: multinational system integrators with braking-coupler bundling capability, regional automatic coupler engineering specialists, and steel foundry incumbents defending heavy-haul positions. Consolidation pressure concentrates among component-only vendors as asset-light service contracting displaces traditional equipment purchase models. Dominant competitive moves include predictive maintenance integration partnerships and backward integration into fatigue-rated casting production.
Among European-based engineering specialists, Knorr-Bremse and Dellner Couplers exemplify divergent positioning within the automatic coupler segment. Knorr-Bremse occupies a position across both freight and passenger segments with integrated braking-coupler systems. Dellner Couplers anchors high-speed contracts through specialized automatic coupler engineering. Wabtec Corporation represents the North American integrated model, sustaining aftermarket revenue streams through installed base leverage.
| Leading Market Players |
|---|
| Knorr-Bremse |
| Wabtec Corporation |
| Dellner Couplers |
| Voith |
| CRRC Qingdao Sifang |
| Huatie Tongda High-speed Railway |
| Amsted Rail Company |
| Nippon Steel Corporation |
| Irwin Car and Equipment |
| Others |
Pricing and Supply Chain Analysis
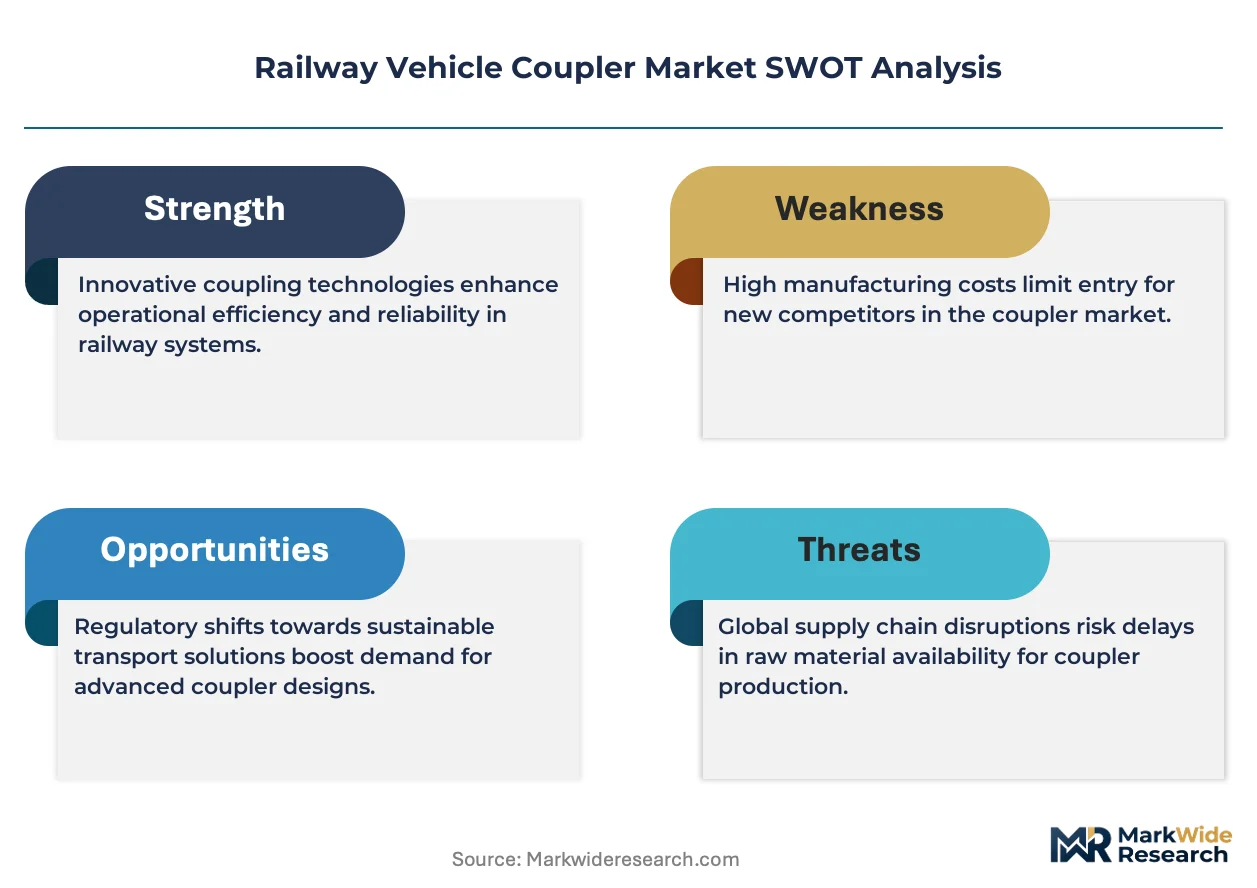
EN 15566 Type 10 certification gates both supplier qualification and price tiering simultaneously, creating a bifurcated market where certified automatic coupler manufacturers command substantial premiums over uncertified competitors while freight operators absorb extended approval timelines as embedded cost.
Pricing Analysis
Next-generation electromechanical automatic couplers trade at substantial premiums over legacy pneumatic systems and transitional semi-automatic designs. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates procurement outcomes. Price differentiation hinges on TSI certification grade and volume scale commitments from Class I railroads. Pricing pressure stems from nickel and chromium alloy cost volatility squeezing heavy-haul steel casting margins. Maintenance providers exhibit highest price sensitivity due to fragmented procurement authority.
Supply Chain Analysis
Inventory cycles for precision-machined locking mechanisms now stretch eighteen months following EN 15566 Type 10 approval bottlenecks. Manufacturing concentrates in Germany, China, and the United States. High-grade alloy steel, aluminum-titanium hybrid castings, and fatigue-rated microstructure components anchor input dependencies. Single-source vulnerability in Germany's Ruhr industrial belt for critical machined components concentrates risk. Distribution runs through OEM-authorized service networks and direct operator contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railway vehicle coupler procurement is consolidating around platform-economics logic as CRRC Qingdao Sifang's standardization mandates and Deutsche Bahn's energy efficiency specifications create winner-take-most dynamics for interoperable system integrators.
For Market Incumbents: Consolidate backward integration into fatigue-rated casting production to defend against aluminum-titanium hybrid specialists eroding steel foundry positions. Capture predictive maintenance bundling revenue through availability-based contracting models that displace component-only vendors. Lock in certification capacity ahead of compressed EU migration timelines. For New Entrants and Emerging Players: Differentiate on composite-reinforced aluminum engineering for Asian high-speed networks where energy efficiency targets drive material substitution. Target India's Dedicated Freight Corporation electrification corridors ahead of full TSI compliance mandates. Pursue joint development partnerships with regional rolling stock manufacturers seeking platform-standardized alternatives. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming rail component divisions lacking predictive maintenance integration capabilities. Five-to-ten year viability favors automatic coupler specialists with captive certification capacity and OEM platform relationships. Monitor EN 15566 approval cycle compression as inflection signal for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Integration | Union Pacific and BNSF availability-based contracts bundle IoT-enabled coupler health monitoring with hardware supply. |
| Backward Integration into Casting | Captive fatigue-rated steel foundry capacity insulates margin structures from nickel and chromium price volatility. |
| Composite Material Certification | Aluminum-titanium hybrid coupler approval unlocks Deutsche Bahn and SNCF high-speed fleet renewal procurement. |
| Regional Manufacturing Footprint | Gujarat production hubs serve India's Dedicated Freight Corporation and Bangladesh export corridor demand. |
| Platform Standardization Partnership | CRRC Qingdao Sifang compatibility mandates concentrate supplier selection for Southeast Asian rail modernization. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement directors, rolling stock OEM platform engineers, aftermarket service managers, and regulatory compliance officers at national railway administrations and refined through secondary validation against customs trade data, EN 15566 certification registries, FRA mechanical safety filings, and CRRC production disclosure statements. Bottom-up segment sizing triangulated against top-down macroeconomic rail infrastructure investment tracking.
Variance decomposition across product type, material grade, application archetype, end-user category, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level unit economics and replacement cycle modeling. Forecast inputs incorporated EU F-Gas Regulation compliance cost curves and China's GB standards platform standardization velocity.
The analysis sits within stated boundaries; outcomes outside sustained rail infrastructure capital deployment or accelerated automatic coupler mandate enforcement would require recalibration. Forecasts reflect documented assumptions regarding alloy input price trajectories and certification timeline stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Saudi Arabia Refrigerated Trailer Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Precision Bearing Market
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Truck Suspension System Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Italy Automotive Composites Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Global Automotive Battery Sensor Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Piston Market