
 Automotive Wheel Hub Bearing Aftermarket Market | 2026-2036
Automotive Wheel Hub Bearing Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wheel Hub Bearing Aftermarket Market Insights
Capital-intensity divergence between integrated bearing manufacturers and parts distributors is bifurcating the competitive landscape. SKF leverages captive steel forging and heat-treatment facilities to control input costs across its hub assembly portfolio. Timken sustains a dense North American distribution footprint that anchors its aftermarket channel dominance. Mevotech competes through specialized coverage of domestic light-truck platforms where OEM part prices create replacement demand.
Automotive wheel hub bearings are precision rotational components that integrate inner and outer races, rolling elements, and sealing systems into a pre-assembled, greased-for-life unit designed to support wheel loads while enabling free rotation. These assemblies typically operate at temperatures between minus forty and one hundred fifty degrees Celsius and must resist contamination from road debris, water ingress, and corrosive de-icing chemicals across multi-year service intervals. Roller bearing configurations command the largest installed base in heavy-duty truck applications where radial load capacity outweighs friction efficiency priorities. Ball bearing variants are gaining share in passenger car front axle positions as vehicle weight reduction targets intensify. Tapered bearing designs retain strong positioning in all-wheel-drive systems where combined axial and radial load management remains critical.
EPA enforcement of emissions-related onboard diagnostic thresholds indirectly accelerates hub bearing replacement when wheel speed sensor faults trigger diagnostic trouble codes. NHTSA defect investigation protocols and EU REACH restrictions on specific grease formulations shape material selection and supplier qualification requirements across the value chain. The EU F-Gas Regulation and evolving ISO vibration standards for rotating machinery further constrain design flexibility and testing protocols. Stakeholders must monitor how embedded sensor integration in next-generation hub units reshapes replacement intervals and service procedures.
Market Dynamics
Commercial fleet operators are extending vehicle service life through predictive maintenance protocols, accelerating replacement demand for hub assemblies as aging parc accumulates wear-related failures across North America and Europe.
Growth Catalysts
- EPA emissions enforcement:Diagnostic trouble codes triggered by wheel speed sensor faults mandate hub bearing replacement during emissions compliance repairs in the United States.
- EU Green Deal vehicle safety directives:Accelerated inspection cycles for commercial vehicles in Germany and France compress replacement intervals for worn hub assemblies.
- Integrated sensor hub units:Embedded ABS and traction control sensors in next-generation assemblies create upgrade-driven replacement demand as legacy units fail.
Market Restraints
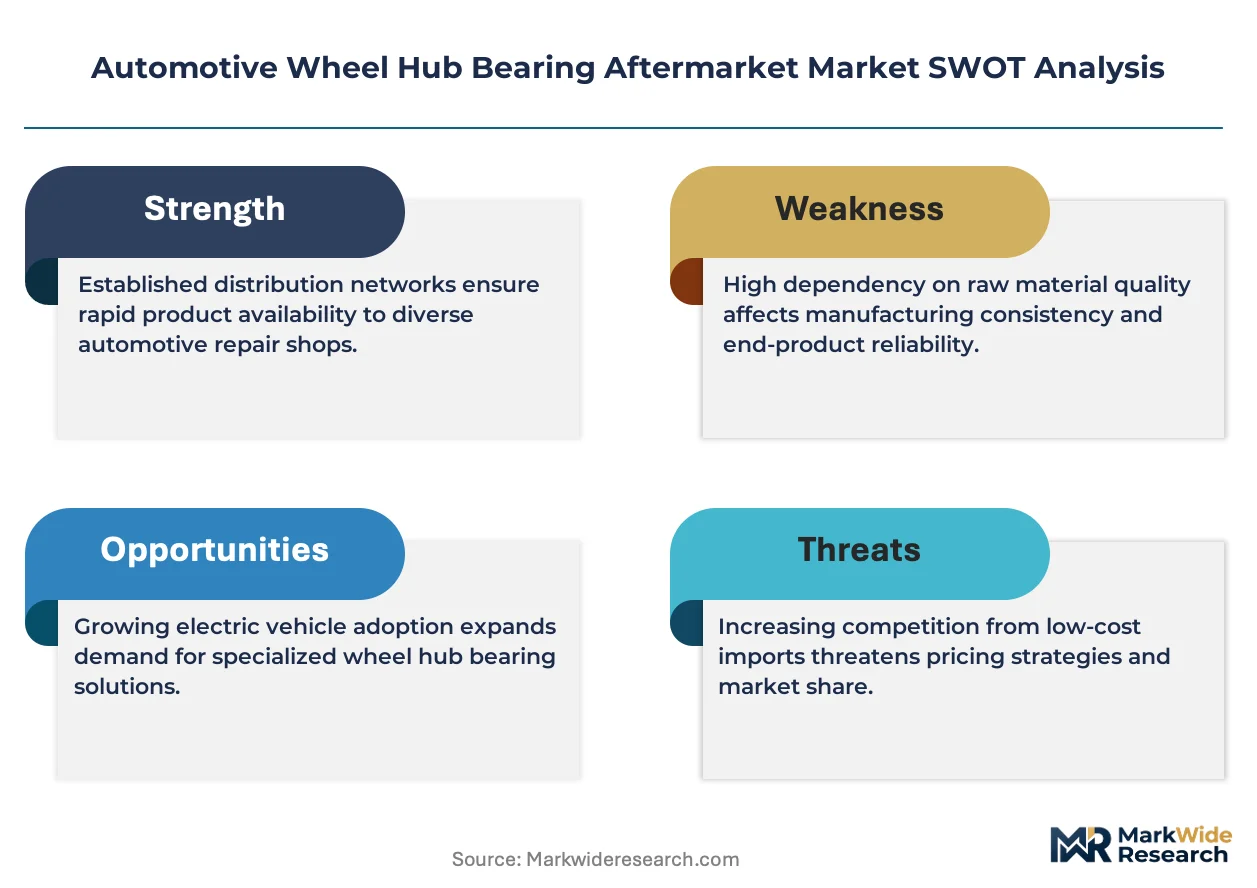
- Specialized steel alloying costs:Chrome-molybdenum bearing steel price volatility squeezes margin structures for non-integrated manufacturers dependent on spot market procurement.
- Grease formulation restrictions:EU REACH limitations on specific thickener chemistries force reformulation investments and supplier requalification timelines.
- Remanufactured assembly competition:Rebuilt hub units priced at 40-60 percent of new assembly cost capture price-sensitive fleet maintenance budgets.
Strategic Opportunities
- China's aging commercial vehicle parc:Heavy-duty trucks exceeding seven years of service create concentrated replacement demand in Shandong and Hebei provinces.
- E-commerce direct-to-garage distribution:Bypassing traditional parts distributors to reach independent repair shops reduces channel margin capture.
- ISO vibration standard convergence:Unified international testing protocols enable single-SKU global sourcing strategies for tier-one suppliers.
Industry Challenges
- Tribology engineering talent scarcity:Specialized grease formulation expertise for sealed-for-life bearings concentrates at legacy European and Japanese suppliers.
- Heat-treatment furnace capacity constraints:Controlled atmosphere brazing and through-hardening equipment requires seven-figure capital deployment with multi-year lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wheel Hub Bearing Aftermarket Market |
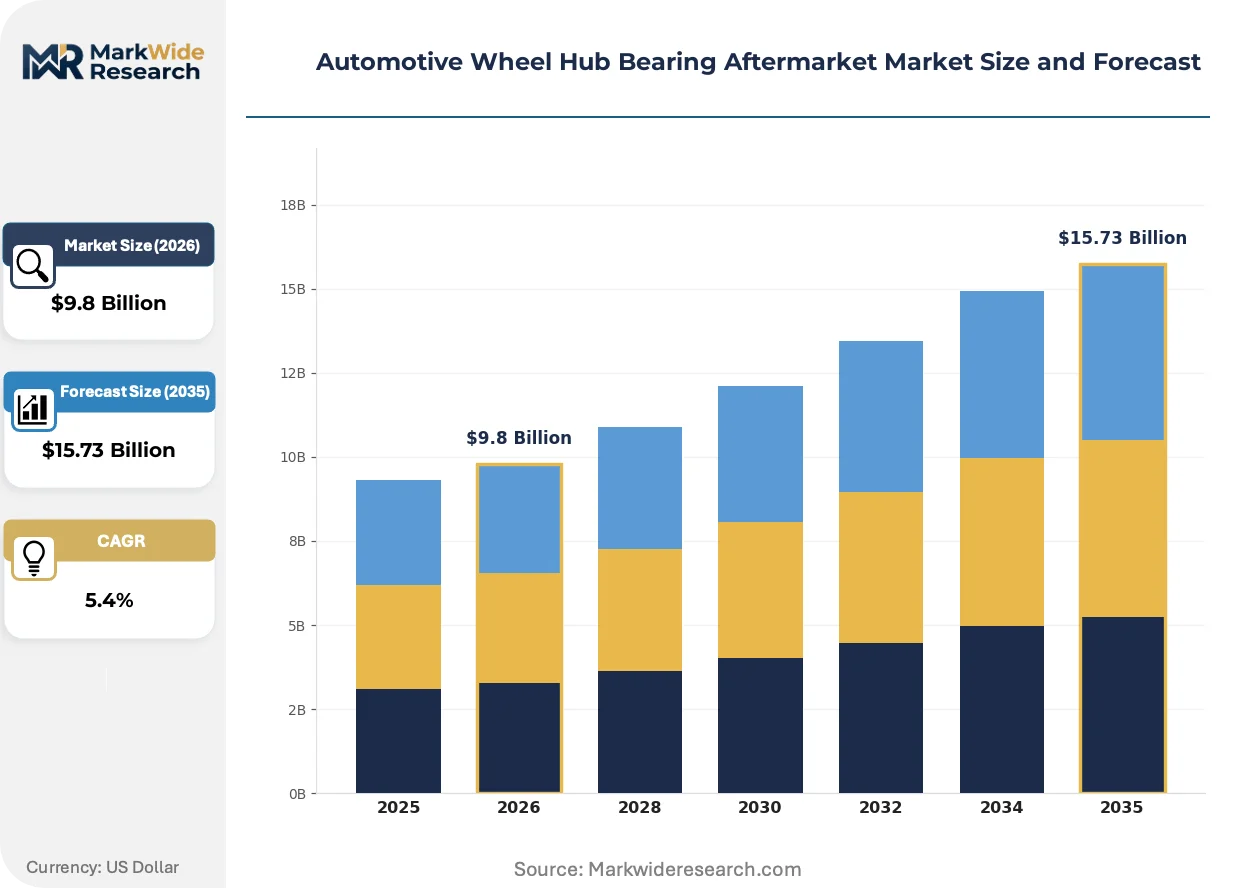
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearing, Roller Bearing, Tapered Bearing, Angular Contact Bearing End User: OEMs, Retailers, Wholesalers, Aftermarket Providers Vehicle Type: Passenger Cars, Light Trucks, Heavy-Duty Trucks, Motorcycles Installation Type: Front Axle, Rear Axle, All-Wheel Drive, Independent Suspension |
| Companies Covered | SKF, Timken, NSK, Schaeffler, NTN, JTEKT, ILJIN, GMB, Mevotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wheel Hub Bearing Aftermarket Market Trends and Innovations
Embedded intelligence and material science advances are redefining hub assembly value propositions, shifting competition from mechanical durability toward integrated diagnostic capability and predictive failure detection.
Magnetic encoder rings integrated directly into bearing seals are bifurcating the aftermarket into sensor-equipped and sensor-free replacement paths. Heavy-duty truck fleets in the United States are adopting encoded hub assemblies at replacement rates exceeding passenger car segments by a factor of three. This technology is bifurcating distributor inventory requirements and compressing margins on legacy non-encoded SKUs as encoded units command price premiums.
EU F-Gas Regulation phase-down schedules are forcing reformulation of hub assembly lubricants away from fluorinated polymer thickeners. Manufacturers serving European aftermarket channels must validate alternative polyurea and lithium-complex greases under revised REACH registration timelines. German commercial vehicle inspection authorities are rejecting assemblies bearing non-compliant lubricant certifications, channeling demand toward pre-certified suppliers.
Fleet maintenance departments are consolidating procurement through integrated vehicle health management platforms that automate hub bearing replacement scheduling based on vibration telemetry. Independent repair shops in the United States are losing share to dealer-affiliated service centers equipped with manufacturer-specific diagnostic interfaces. This consolidation is most visible in long-haul trucking corridors through Texas and California where telematics penetration exceeds eighty percent.
Automotive Wheel Hub Bearing Aftermarket Market Segmentation
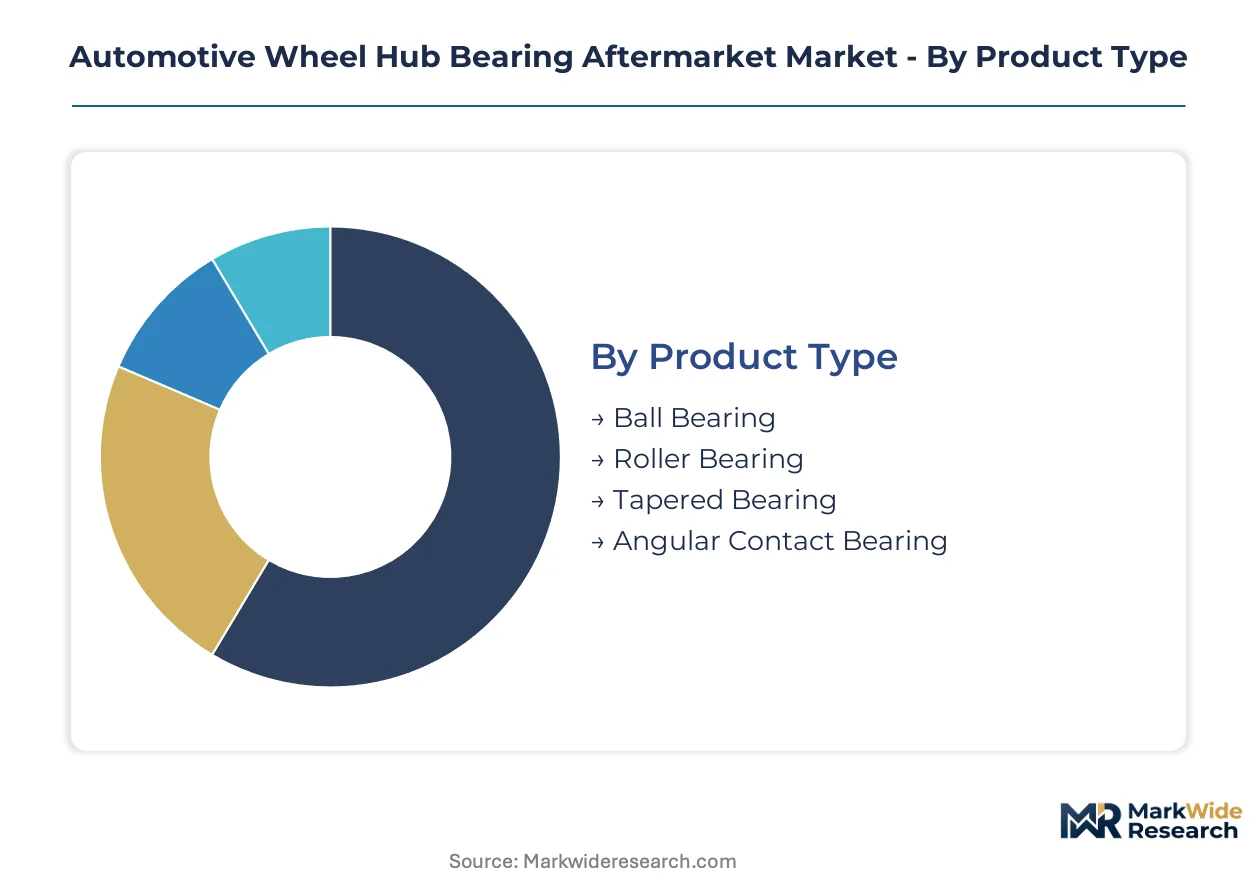
Hub bearing aftermarket demand fragments across mechanical configurations, procurement channels, vehicle duty cycles, and axle positions. Each segmentation axis carries distinct margin profiles and regulatory exposure that shape supplier portfolio priorities.
Product Type:
REACH compliance timelines and EPA durability testing differentiate certification pathways across bearing architectures.
- Roller Bearing:Cylindrical or spherical rolling elements distribute radial loads across heavy-duty truck wheel positions. Fleet maintenance departments in Texas and California specify these units for drive axles where load capacity outweighs friction penalties.
- Ball Bearing:Lower rotational resistance suits passenger car front hubs where fuel efficiency targets dominate specification sheets. German vehicle inspection authorities increasingly require sealed-for-life units with integrated magnetic encoders for ABS compatibility.
- Tapered Bearing:Conical raceways manage combined axial and radial loads in all-wheel-drive transfer cases and steering knuckles.
- Angular Contact Bearing:Asymmetric raceway angles handle thrust loads in performance-oriented suspension geometries and motorcycle front forks.
Established volume favors Roller Bearing; emerging adoption favors Ball Bearing.
End User:
Procurement authority concentrates differently across direct manufacturer relationships versus fragmented distribution channels.
- Aftermarket Providers:Independent distributors and garage chains capture replacement demand from aging vehicle parc in the United States, Germany, and China. These entities negotiate volume rebates with bearing manufacturers while managing encoded versus non-encoded SKU complexity.
- OEMs:Original equipment manufacturers specify hub assemblies for new vehicle production and service-part fulfillment through captive dealer networks.
- Retailers:Auto parts chains stock DIY-grade units for consumer self-installation on light trucks and passenger cars.
- Wholesalers:Regional distributors aggregate demand from independent repair shops and sub-distributors across multi-state territories.
Channel margin capture runs deepest through Aftermarket Providers; direct procurement discipline concentrates at OEMs.
Vehicle Type:
Duty cycle severity and inspection frequency create divergent replacement intervals across transportation modes.
- Heavy-Duty Trucks:Class 8 commercial vehicles accumulate hub bearing wear through sustained highway operation and maximum gross vehicle weight loading. Shandong and Hebei provinces in China host concentrated replacement demand as trucks exceed seven years of service.
- Passenger Cars:Lighter axle loads extend nominal service life, though embedded sensor failures accelerate replacement cycles in newer vehicles.
- Light Trucks:Pickup and van platforms split demand between consumer durability expectations and commercial fleet utilization patterns.
- Motorcycles:Exposed wheel positions and high-revving operation demand specialized sealing systems against water and debris ingress.
Replacement frequency peaks at Heavy-Duty Trucks; unit volume concentrates at Passenger Cars.
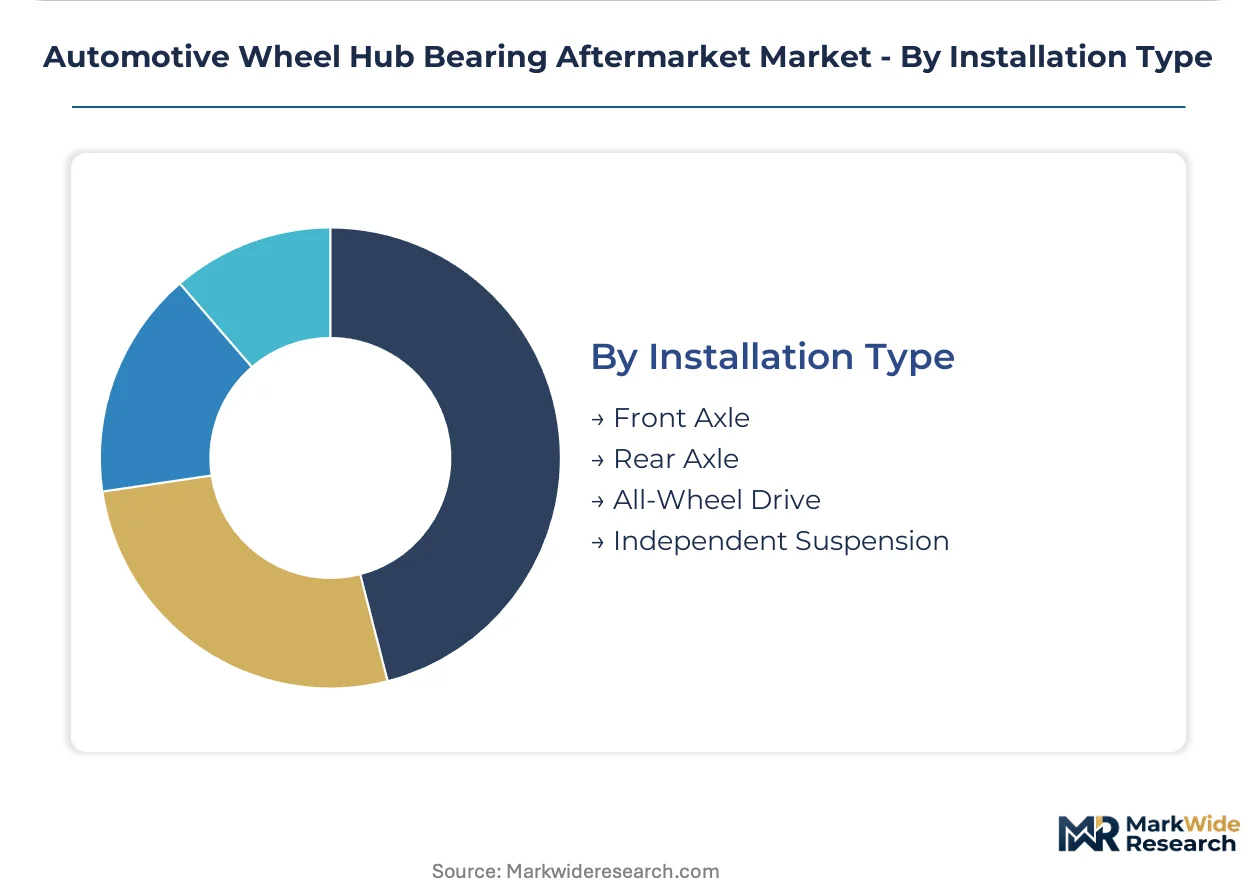
Installation Type:
Axle position determines load vector complexity and sensor integration requirements.
- Front Axle:Steering loads, braking torque, and ABS sensor integration concentrate wear factors and diagnostic sensitivity. NHTSA defect investigations target front hub assemblies for wheel separation risks.
- Rear Axle:Drive torque transmission and parking brake integration define specification requirements for solid axle and independent suspension variants.
- All-Wheel Drive:Power transfer unit connections and variable torque distribution demand tapered bearing configurations managing multi-directional load cases.
- Independent Suspension:Hub carrier geometries in multi-link and MacPherson strut designs require compact bearing packages with specific flange interfaces.
Technical complexity concentrates at Front Axle; system integration challenges expand fastest at All-Wheel Drive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German distribution channels where REACH-certified hub assemblies command 15-20% premiums over non-compliant alternatives, while Chinese manufacturers compete on volume through Shandong's forging clusters.
United States
Class 8 truck fleets in Texas and California drive replacement demand through predictive maintenance protocols. EPA emissions enforcement mandates hub bearing replacement when wheel speed sensor faults trigger diagnostic trouble codes. The I-35 corridor through Dallas-Fort Worth hosts dense distributor networks serving long-haul operators.
Germany
Commercial vehicle inspection cycles under EU Green Deal directives compress replacement intervals for worn hub assemblies. KBA enforcement of lubricant certifications rejects non-REACH-compliant grease formulations. Stuttgart's automotive supplier ecosystem concentrates R&D for encoded hub units with integrated magnetic sensors.
China
Heavy-duty trucks exceeding seven years of service in Shandong and Hebei provinces generate concentrated aftermarket demand. MIIT durability standards for commercial vehicle components accelerate replacement cycles in aging parc. Zhejiang's bearing manufacturing clusters supply domestic aftermarket channels with cost-optimized roller configurations.
Japan
Precision bearing exports from Kansai region sustain aftermarket presence in Southeast Asian markets. METI industrial standards for rotating machinery enforce strict vibration tolerance thresholds. Nagoya's automotive component suppliers specialize in compact ball bearing units for hybrid vehicle platforms.
India
Commercial vehicle parc expansion in Maharashtra and Gujarat creates replacement demand for hub assemblies in logistics corridors. BIS certification requirements for automotive components filter substandard imports from unorganized suppliers. Chennai's OEM supplier base extends into aftermarket distribution for South Indian fleet operators.
Automotive Wheel Hub Bearing Aftermarket Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the hub bearing aftermarket. Integrated manufacturers with captive steel forging and heat-treatment facilities command input cost advantages, while specialized distributors compete through dense service networks and platform-specific coverage. The competitive terrain splits between premium-tier suppliers certified to REACH and ISO vibration standards, and value-tier competitors serving price-sensitive fleet maintenance budgets. Dominant competitive moves include backward integration into steel alloying operations and e-commerce channel expansion bypassing traditional parts distributors.
Within the integrated manufacturing tier, SKF and Timken exemplify divergent strategic positioning. SKF leverages European-based metallurgical capabilities to control alloy specifications across hub assembly portfolios. Timken anchors North American aftermarket channels through established distributor relationships and specialized coverage of domestic light-truck platforms. Mevotech occupies a position focused on platform-specific replacement demand where OEM part pricing creates aftermarket opportunities.
| Leading Market Players |
|---|
| SKF |
| Timken |
| NSK |
| Schaeffler |
| NTN |
| JTEKT |
| ILJIN |
| GMB |
| Mevotech |
| Others |
Pricing and Supply Chain Analysis
Heat-treatment furnace capacity utilization above eighty percent in European and Japanese forging clusters creates scale-driven barriers that compress margin floors for non-integrated competitors dependent on spot-market steel procurement. This capacity concentration simultaneously elevates REACH-certified assembly premiums and limits price competition at the quality tier where OEM service-part contracts anchor volume.
Pricing Analysis
Configured-to-order hub assemblies with integrated magnetic encoders command forty to sixty percent premiums over standard non-encoded SKUs in North American heavy-duty fleet procurement. Three-tier pricing structure across premium REACH-certified, standard ISO-grade, and economy non-certified levels segments buyer budgets, with German commercial vehicle operators showing lowest price sensitivity due to KBA inspection mandates. Pricing pressure stems from remanufactured assembly competition capturing fleet maintenance spend. Independent repair shops in the United States exhibit highest price sensitivity as telematics-equipped dealer networks consolidate long-haul trucking service relationships.
Supply Chain Analysis
Inventory lead times for chrome-molybdenum bearing steel extend eighteen to twenty-four months for non-integrated manufacturers, forcing working capital intensity that favors captive forging operations. Supply concentrates in Germany, China, and Japan where SKF, Timken, and NSK maintain in-house heat-treatment capacity. Raw material dependencies include vacuum-degassed steel billets, lithium-complex grease formulations, and nitrile rubber sealing compounds. Tariff exposure on Chinese forging imports into the United States creates supply chain risk for distributors dependent on Shandong manufacturing clusters. Distribution runs through regional wholesalers aggregating independent garage demand across multi-state territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story anchored in regulatory entrenchment: REACH certification timelines and KBA lubricant approval protocols create switching costs that lock fleet procurement relationships and elevate replacement barriers for uncertified competitors.
For Market Incumbents: Compound certification advantages by deepening captive steel alloying capabilities and expanding encoded hub assembly SKUs before EU F-Gas grease reformulation deadlines consolidate demand toward pre-qualified suppliers. Defend against remanufactured assembly competition through extended warranty bundling with telematics-integrated fleet management platforms. Prioritize heat-treatment furnace capacity additions in Germany and the United States to maintain input cost control as spot steel volatility squeezes non-integrated distributors. For New Entrants and Emerging Players: Differentiate on e-commerce direct-to-garage distribution bypassing traditional wholesaler margin capture in the United States I-35 corridor. Target China's Shandong and Hebei provinces where aging commercial vehicle parc exceeds seven years and domestic cost-optimized roller bearing demand concentrates. Pursue white-label supply agreements with Indian BIS-certified manufacturers seeking aftermarket channel expansion into Maharashtra logistics corridors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with captive metallurgical capabilities over pure-play distributors exposed to inventory risk. Long-term viability hinges on embedded sensor integration reshaping replacement intervals and service procedures. Acquisition target archetype: European or Japanese suppliers with established REACH grease certifications and heat-treatment furnace assets. Signal to watch: MIIT durability standard enforcement accelerating replacement cycles in China's aging heavy-duty truck parc.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Forging | Captive heat-treatment capacity insulates SKF and Timken from chrome-molybdenum price volatility. |
| REACH-Certified Grease Reformulation | Pre-qualified suppliers capture German commercial vehicle demand as KBA rejects non-compliant assemblies. |
| E-Commerce Direct-to-Garage Expansion | Bypassing traditional distributors reduces channel margin capture in Texas and California fleet corridors. |
| Encoded Hub Assembly SKU Expansion | Magnetic sensor integration commands replacement premiums as ABS diagnostic mandates tighten. |
| Telematics Platform Partnership | Integration with vehicle health management systems automates predictive replacement scheduling for Class 8 operators. |
Research Methodology
Cross-validation between fleet maintenance director interviews and customs trade data anchors the qualitative findings on regional demand concentration. Primary fieldwork engaged Tier 1 supplier procurement leads, aftermarket distributor operations heads, OEM platform engineers, and commercial fleet maintenance directors across the United States, Germany, and China. Secondary validation drew from EPA enforcement databases, EU REACH registration filings, MIIT durability standard notifications, and IHS Markit vehicle registration data. Bottom-up unit demand modeling triangulates against top-down value estimates from steel input cost analysis.
Sensitivity analysis across bearing configuration mix, vehicle age distribution, and regulatory enforcement intensity bounds the forecast range. Segmentation dimensions include product architecture, procurement channel, vehicle duty cycle, and axle position across the projection horizon. CAGRs derive from replacement interval compression rates tied to embedded sensor failure modes and inspection cycle tightening. Industry-specific inputs incorporate heat-treatment furnace capacity utilization and REACH grease certification timelines.
The analysis sits within stated boundaries; outcomes outside sustained EPA emissions enforcement or accelerated EU Green Deal implementation would require recalibration. Forecasts reflect assumptions on fleet telematics penetration and remanufactured assembly pricing discipline. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Air Suspension Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Autonomous Trains Components Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Limited Slip Differential (LSD) Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
Vehicle Retarder Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Chassis Sensors Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market