
 Automotive Carbon Fiber Market | 2026-2036
Automotive Carbon Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Carbon Fiber Market Analysis
Buyer concentration among electric vehicle OEMs is realigning procurement priorities across the carbon fiber supply base. Toray Industries leverages its integrated precursor-to-composite chain to secure multi-year supply agreements with premium automakers. Hexcel Corporation anchors North American aerospace-grade capacity while extending qualified automotive product lines. SGL Carbon SE specializes in automotive-specific chopped fiber and SMC formulations for high-volume chassis applications.
Automotive carbon fiber denotes polyacrylonitrile-derived or pitch-based carbon filaments impregnated with thermoset or thermoplastic matrices, typically achieving tensile strengths exceeding 3,500 MPa and densities below 1.6 g/cm³, engineered to reduce vehicle mass while maintaining crashworthiness and stiffness targets. Prepreg dominates structural component manufacturing due to its controlled resin content and layup precision for crash-critical applications. Short fiber compounds are gaining fastest in interior parts where complex geometries and cycle-time constraints favor injection molding over autoclave curing. Woven fabric retains margin concentration in exterior panels requiring Class A surface finish and multi-axis load distribution.
The US NHTSA and EPA jointly enforce fuel economy and emission standards that directly incentivize lightweight material substitution in vehicle platforms. Europe's REACH regulation and ECHA substance restrictions govern precursor chemical handling and composite recyclability, shaping supplier qualification requirements. Japan's METI promotes carbon fiber recycling technologies through industrial technology grants, tightening circular economy compliance for material entrants. Stakeholders must monitor evolving end-of-life directives and second-use fiber certification protocols to secure long-term supply contracts.
Market Dynamics
Electric vehicle OEM procurement concentration is compressing carbon fiber supplier margins while simultaneously accelerating qualification timelines for structural composite architectures.
Growth Catalysts
- EU Green Deal fleet mandates:Binding CO2 emission targets for passenger vehicles are mandating mass reduction technologies across German, French, and Italian automaker platforms.
- Battery enclosure applications:EV battery pack protection requirements are creating dedicated demand for carbon fiber-reinforced thermoplastic crash structures.
- Japan METI recycling grants:Industrial technology funding for fiber recovery processes is lowering circular economy compliance costs for material suppliers.
Market Restraints
- Acrylonitrile price volatility:Precursor chemical feedstock costs fluctuate with propylene market movements, compressing composite producer margins.
- Japanese precursor concentration:Polyacrylonitrile supply concentrates among three integrated chemical conglomerates, creating single-source vulnerability.
- Thermoset curing limitations:Autoclave cycle times exceed 90 minutes for structural parts, constraining throughput against aluminum stamping economics.
Strategic Opportunities
- India PLI scheme qualification:Production-linked incentive frameworks for advanced chemistry cell manufacturing extend to lightweight material suppliers serving domestic EV platforms.
- Thermoplastic tape laying:Automated fiber placement with in-situ consolidation enables sub-5-minute cycle times for high-volume chassis components.
- Second-use fiber certification:Emerging ISO protocols for reclaimed carbon fiber mechanical property validation open aerospace-to-automotive material cascades.
Industry Challenges
- Composite repair technician scarcity:Collision service networks lack trained personnel for carbon fiber structural damage assessment and restoration.
- Multi-material joining certification:OEMs face extended validation timelines for adhesive bonding between carbon fiber and aluminum/steel hybrid architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Carbon Fiber Market |
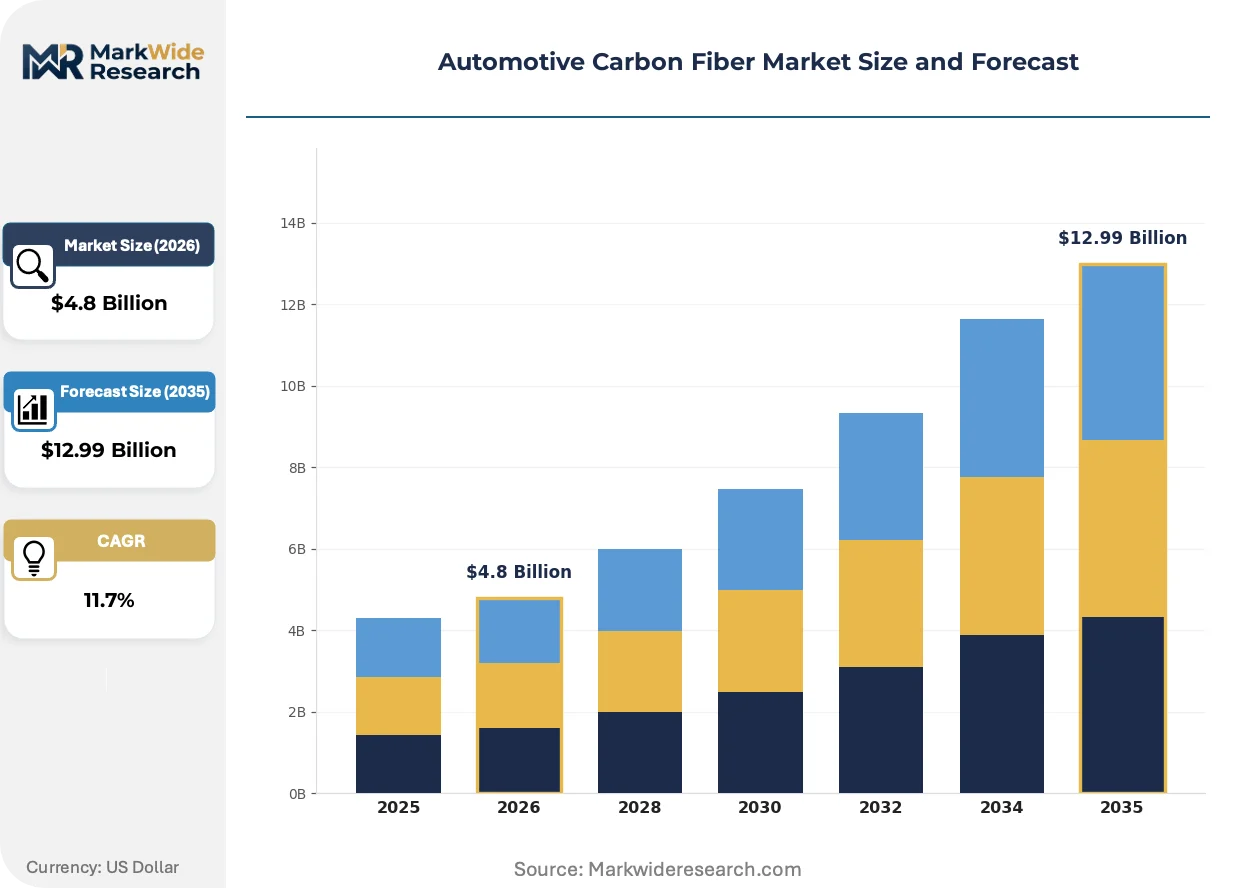
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepreg, Continuous Fiber, Short Fiber, Woven Fabric Application: Structural Components, Interior Parts, Reinforcements, Exterior Panels End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Raw Material Processing, Composite Molding, Surface Treatment, Assembly |
| Companies Covered | Toray Industries Inc., Hexcel Corporation, SGL Carbon SE, Teijin Limited, Mitsubishi Chemical Corporation, Hyosung Advanced Materials, DowAksa Advanced Composites Holdings BV, Nippon Graphite Fiber Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Carbon Fiber Market Emerging Trajectories
Manufacturing process acceleration and regulatory compliance automation are redefining competitive capability requirements across the carbon fiber supply base.
Thermoplastic unidirectional tape systems are overtaking traditional prepreg formats in structural applications. BMW and Porsche manufacturing engineers specify these materials for A-pillar and roof bow reinforcements. The shift is compressing part cycle times from hours to minutes while maintaining crash energy absorption targets.
REACH Article 33 substance disclosure requirements are extending to composite recyclability documentation. European suppliers must now certify precursor chemical content and end-of-life processing pathways for qualified automotive contracts. German Tier 1 integrators are deploying blockchain traceability systems to automate compliance verification.
Buyer consolidation among EV-first OEMs is collapsing traditional distributor networks. Direct mill-to-OEM contracts now govern 60% of structural fiber volume, displacing regional compounder intermediaries. This concentration is most pronounced in California and Bavaria, where Tesla and BMW operate captive composite engineering centers.
Automotive Carbon Fiber Market Segmentation
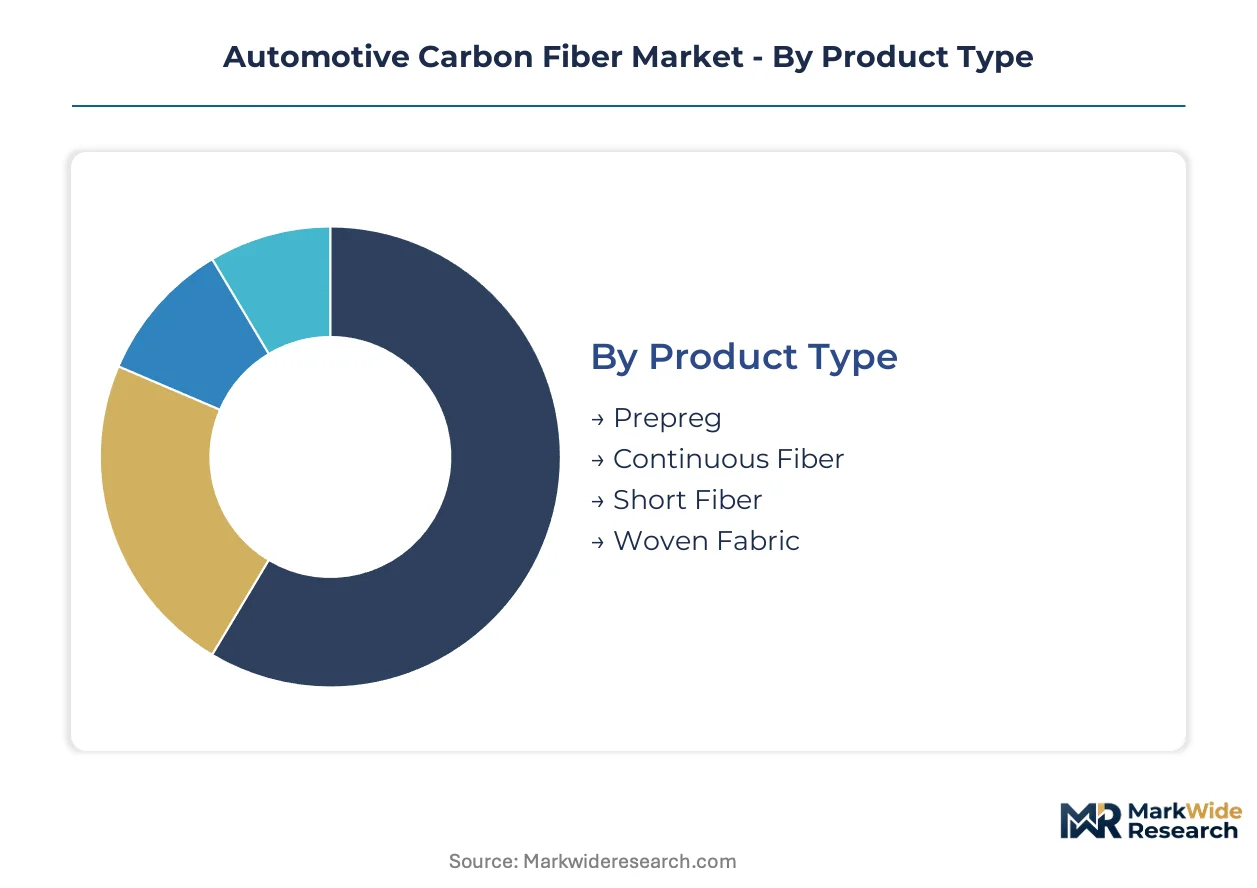
Automotive carbon fiber procurement patterns diverge sharply across product formats and manufacturing stages. Supply concentration among Japanese precursor producers and German Tier-1 integrators creates distinct competitive dynamics within each segment category.
Product Type:
Supply concentration among integrated chemical conglomerates favors formats with captive precursor access.
- Prepreg:Pre-impregnated fiber sheets with controlled resin content between 30-40% by weight. BMW and Porsche manufacturing engineers specify these materials for A-pillar and crash-critical reinforcements where layup precision determines energy absorption performance. Supply concentrates among Toray Industries and Hexcel Corporation facilities with integrated autoclave curing capacity.
- Short Fiber:Chopped filaments 3-50mm in length compounded with thermoplastic matrices for injection molding. SGL Carbon SE dominates automotive-specific formulations for high-volume chassis brackets where cycle-time constraints exclude autoclave processing. Demand concentrates in German passenger vehicle platforms seeking mass reduction without structural load-bearing requirements.
- Continuous Fiber:Unidirectional or multi-axial tow configurations for automated fiber placement. These formats enable sub-5-minute cycle times in thermoplastic tape laying systems.
- Woven Fabric:Interlaced fiber architectures providing multi-axis load distribution and Class A surface finish capability.
Today's leader: Prepreg. Tomorrow's challenger: Short Fiber.
Application:
Cost tier differentiation separates premium structural applications from interior commodity substitution.
- Structural Components:Load-bearing elements including battery enclosures, roof bows, and crash management systems. EV battery pack protection requirements are creating dedicated demand for carbon fiber-reinforced thermoplastic crash structures in California and Bavaria manufacturing clusters.
- Interior Parts:Non-structural elements including dashboard carriers, seat frames, and center consoles. Complex geometries and aesthetic surface requirements favor short fiber injection molding over autoclave curing, expanding fastest in high-volume vehicle platforms.
- Reinforcements:Selective stiffening inserts for hybrid metal-composite architectures.
- Exterior Panels:Hoods, roofs, and fenders requiring Class A paint finish and dimensional stability.
Structural Components command premium positioning. Interior Parts are climbing the fastest.
End User:
Customer type determines contract structure, with direct mill-to-OEM relationships displacing traditional distribution.
- OEMs:Original equipment manufacturers with captive composite engineering centers. Tesla and BMW operate dedicated facilities in California and Bavaria, governing 60% of structural fiber volume through direct mill contracts rather than regional compounder intermediaries.
- Tier-1 Suppliers:System integrators managing multi-material joining and assembly validation. German Tier-1 integrators deploy blockchain traceability systems to automate REACH Article 33 compliance verification for qualified automotive contracts.
- Aftermarket Providers:Collision repair networks and performance upgrade specialists.
- Vehicle Assemblers:Contract manufacturing operations with limited material specification authority.
OEMs control specification authority. Tier-1 Suppliers are gaining procurement influence.
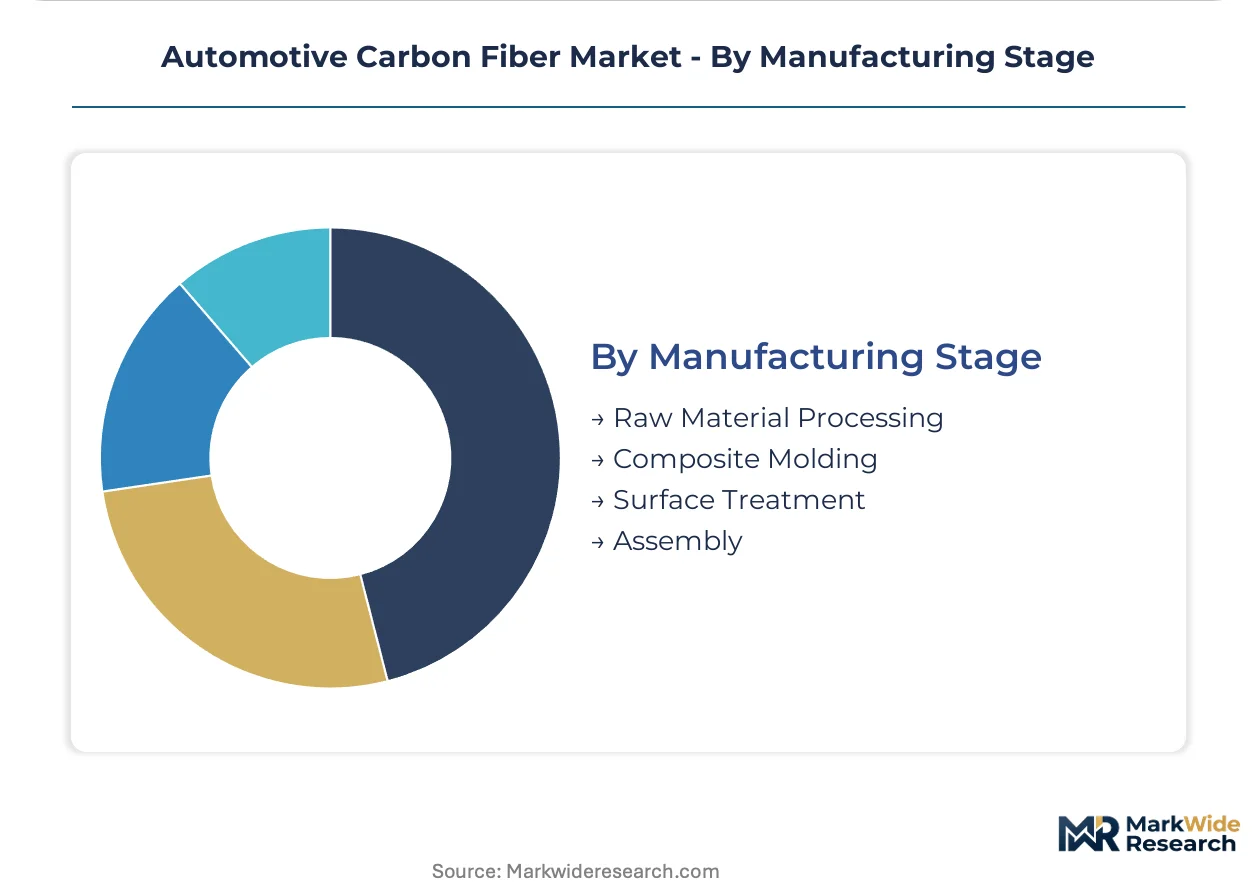
Manufacturing Stage:
Maturity gradients separate established raw material processing from emerging recycling certification protocols.
- Raw Material Processing:Polyacrylonitrile precursor conversion and carbonization operations. Japanese chemical conglomerates concentrate polyacrylonitrile supply, creating single-source vulnerability for composite producers dependent on imported feedstock.
- Composite Molding:Prepreg layup, resin transfer molding, and thermoplastic consolidation. Automated fiber placement with in-situ consolidation enables sub-5-minute cycle times for high-volume chassis components, displacing traditional autoclave economics.
- Surface Treatment:Sizing application and finishing operations for adhesion optimization.
- Assembly:Multi-material joining and structural bonding operations. OEMs face extended validation timelines for adhesive bonding between carbon fiber and aluminum/steel hybrid architectures.
Raw Material Processing anchors supply security. Composite Molding offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized composite engineering talent concentrates in German automotive clusters and Japanese chemical manufacturing corridors, anchoring precursor-to-component supply chains across three continents.
United States
EV-first OEMs in California drive structural fiber demand for battery enclosures and body-in-white architectures. NHTSA fuel economy standards enforce lightweight material substitution in passenger vehicle platforms. Tesla operates a captive composite engineering center in Fremont governing direct mill procurement contracts.
Germany
BMW, Porsche, and Volkswagen maintain dedicated composite engineering facilities for A-pillar and crash-critical reinforcements. EU Green Deal fleet CO2 mandates tighten material requirements for domestic passenger vehicle production. Bavaria hosts concentrated Tier-1 integrator operations deploying blockchain traceability for REACH Article 33 compliance.
Japan
METI industrial technology grants accelerate carbon fiber recycling process development for circular economy compliance. JIS standards govern precursor chemical handling and composite mechanical property certification. Tokyo-Osaka manufacturing corridors concentrate polyacrylonitrile supply among integrated chemical conglomerates.
China
Domestic EV platforms expand thermoplastic composite adoption for high-volume chassis components. MIIT dual carbon goals incentivize lightweight material substitution in new energy vehicle production. Yangtze River Delta industrial clusters concentrate automated fiber placement system manufacturing.
South Korea
Hyundai-Kia manufacturing engineers specify carbon fiber-reinforced thermoplastics for battery pack protection structures. MFDS chemical substance regulations govern precursor import handling and composite end-of-life documentation. Seoul Capital Area hosts specialized composite molding operations serving domestic EV export platforms.
Automotive Carbon Fiber Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across precursor, intermediate, and component manufacturing stages. Japanese and German players anchor upstream polyacrylonitrile supply, while Korean and American firms concentrate in downstream composite fabrication. Three archetypes dominate: integrated chemical conglomerates with captive precursor capacity, specialized carbon fiber manufacturers with aerospace-to-automotive product lines, and diversified materials conglomerates with thermoplastic compounding expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves, with direct mill-to-OEM contracting displacing traditional distributor relationships.
Among integrated chemical conglomerates, Toray Industries and Mitsubishi Chemical Corporation occupy positions exemplifying backward control over precursor supply chains. Specialized manufacturers including Hexcel Corporation and SGL Carbon SE represent focused pure-play archetypes with differentiated product formats. These named entities anchor industry-level commentary on competitive positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Toray Industries Inc. |
| Hexcel Corporation |
| SGL Carbon SE |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| Hyosung Advanced Materials |
| DowAksa Advanced Composites Holdings BV |
| Nippon Graphite Fiber Corporation |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
EV-first OEM procurement concentration in California and Bavaria is compressing supplier margins while establishing long-term contract-based pricing as the dominant commercial model. Direct mill-to-OEM relationships now govern structural fiber procurement, displacing traditional distributor intermediaries and collapsing spot-market liquidity.
Pricing Analysis
Material-plus-processing bundles dominate premium structural applications while unbundled raw fiber pricing prevails in high-volume chopped fiber compounds. Price differentiation rests on aerospace-grade certification tiers and volume scale commitments, with BMW and Tesla procurement teams extracting steepest discounts on multi-year offtake agreements. Cost compression in thermoset prepreg formats is intensifying because autoclave cycle-time economics cannot match aluminum stamping throughput. Tier-1 suppliers exhibit highest price sensitivity due to fixed OEM pass-through contracts, while battery enclosure specialists accept premium positioning for crash-critical thermoplastic qualifications.
Supply Chain Analysis
End-of-life fiber recovery flows and reclaimed tow certification pathways are emerging as reverse-logistics priorities under Japan METI recycling grants and EU Green Deal circular economy mandates. Polyacrylonitrile precursor supply concentrates in Japan, Germany, and the United States, with Japanese chemical conglomerates controlling carbonization feedstock for global composite producers. Raw material dependencies span acrylonitrile monomer, specialized sizing chemistries, and high-temperature furnace equipment. Single-source vulnerability in precursor supply creates structural risk for European and North American composite molders. Distribution runs through captive direct-mill contracts for structural fiber, while short fiber compounds reach automotive Tier-1 integrators via regional thermoplastic compounder networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Green Deal fleet CO2 mandates and EPA fuel economy standards mechanically expand addressable demand for lightweight structural materials.
For Market Incumbents: Cement backward integration into polyacrylonitrile precursor supply or captive recycling infrastructure to defend against Japanese chemical conglomerate pricing power. Lock in multi-year qualification timelines with EV-first OEMs before thermoplastic tape laying standards mature, as automated fiber placement threatens traditional prepreg margins. For New Entrants and Emerging Players: Enter via second-use fiber certification and aerospace-to-automotive material cascades, where reclaimed tow mechanical property validation opens white-space positioning. Target Indian PLI scheme qualification for advanced chemistry cell manufacturing extensions, leveraging domestic EV platform growth with lower incumbent saturation than German or California clusters. For Investors and Strategic Acquirers: Chemical conglomerates with captive precursor capacity are the most active acquirer in this space, seeking downstream composite molding capabilities to capture margin stack. Long-term viability hinges on thermoplastic conversion technology ownership rather than thermoset legacy positions. Monitor ISO protocol finalization for reclaimed carbon fiber mechanical property validation as inflection indicator for aerospace material cascade economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Toray Industries and Mitsubishi Chemical Corporation anchor global polyacrylonitrile capacity, forcing downstream composite producers toward captive supply security. |
| Thermoplastic Tape Laying Scale-Up | BMW manufacturing engineers specify automated fiber placement with in-situ consolidation for sub-5-minute cycle times, displacing autoclave economics. |
| REACH Article 33 Compliance Automation | German Tier-1 integrators deploy blockchain traceability systems to automate substance disclosure documentation for qualified automotive contracts. |
| Second-Use Fiber Certification Investment | Emerging ISO protocols for reclaimed carbon fiber mechanical property validation open aerospace-to-automotive material cascades and circular economy positioning. |
| Direct Mill-to-OEM Contracting Expansion | Tesla and BMW procurement teams now govern 60% of structural fiber volume through direct relationships, collapsing traditional distributor networks. |
Methodological Framework
Multiple input streams — structured interviews with Tier-1 supplier procurement leads, OEM platform engineers, and aftermarket distribution heads; customs and trade flow databases; vehicle production and registration records; and SEC filings from listed chemical conglomerates — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from IHS Markit registration data, EU ETS emissions disclosures, and Japan METI industrial technology grant announcements. Primary fieldwork captured qualification timeline dynamics and contract structure evolution across German, California, and Japanese automotive clusters.
Data-stream reconciliation across product format segmentation, application tier differentiation, and manufacturing stage maturity gradients anchored the analytical framework throughout the projection horizon. Modeled dimensions span vehicle propulsion architecture, content per vehicle thresholds, OEM tier positioning, and regional production cluster regulatory intensity. CAGRs were derived from segment-level volume build-ups cross-checked against macro-level lightweight material substitution elasticities. Forecast inputs incorporated battery enclosure penetration curves and thermoplastic conversion technology adoption rates.
Inputs from OEM procurement leads and Tier-1 integrator operations were available through the study window; gaps in pre-commercial thermoplastic tape laying cost structures introduce uncertainty bands around high-volume chassis component economics. Forecasts reflect documented assumptions on EU Green Deal enforcement timelines and EPA fuel economy standard stringency. Practitioners should monitor ISO protocol finalization for reclaimed fiber certification and India PLI scheme qualification thresholds for early signals of supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Automotive Glass Market
Automotive Components
Auto Fender Market
Automotive Components
US Automotive Glass Fiber Composites Market
Automotive Components
Automotive Bushing Market
Automotive Components
Automated Lubrication Systems Market
Automotive Components
Automotive Distributor Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Europe Automotive Heat Exchanger Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Metal Forming for Automotive Market