
 Bicycle Brake Cable Market | 2026-2036
Bicycle Brake Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Brake Cable Market Analysis
A certified brake cable assembler shortage across Taiwanese and Chinese component hubs is unwinding production schedules for mid-tier bicycle brands. Shimano leverages captive metallurgy facilities to sustain proprietary stainless steel formulations that resist corrosion in coastal climates. SRAM Corporation competes through vertical control over polymer extrusion for compressionless housing, while Jagwire anchors aftermarket distribution through bike shop channel partnerships across North America and Europe.
Bicycle brake cables transmit mechanical force from lever to caliper through stranded stainless steel inner wires sheathed in coiled or compressionless housing, typically rated for pull forces exceeding 800 Newtons and engineered for friction coefficients below 0.15 to ensure modulation precision. Road cycling applications favor compressionless housing with Kevlar-reinforced liners for crisp response under high-tension routing, whereas mountain biking segments dominate volume through demand for sealed systems that exclude contaminants during wet-terrain exposure. Stainless steel material grades command premium positioning due to fatigue resistance, while plastic and nylon sheath variants penetrate entry-level hybrid and commuter builds where cost sensitivity outweighs performance thresholds.
FDA oversight applies indirectly where brake cables integrate into medical-rehabilitation adaptive cycles, though OSHA workplace safety standards more directly shape manufacturing protocols at U.S. assembly facilities. REACH and RoHS frameworks in Europe restrict hazardous substance content in cable coatings and brass end fittings, compelling Jiangyin Gaosheng Metal Manufacturing and ALLIGATOR CABLE ENT. to reformulate plating chemistries for export compliance. Stakeholders must monitor how EU CSRD disclosure requirements will cascade through Tier-2 supplier audits, reshaping sourcing decisions for brands serving European retail channels.
Market Dynamics
Hydraulic disc brake adoption across electric bicycle platforms is compressing demand for traditional mechanical cable systems while simultaneously elevating specifications for remaining cable-dependent applications in entry-level and adaptive cycling segments.
Growth Catalysts
- REACH compliance mandates:European chemical safety frameworks are accelerating supplier migration toward low-cadmium galvanizing processes, creating first-mover advantages for Jiangyin and Dongguan producers who reformulated plating chemistries ahead of enforcement windows.
- Sealed housing technology:Mountain bike OEMs in North America and Europe specify fully sealed cable systems for wet-terrain performance, driving aftermarket replacement cycles and premium housing material demand.
- Electric bicycle production clustering:Manufacturing concentration in China's Jiangsu and Guangdong provinces generates localized procurement efficiencies that compress lead times for brake cable assemblies.
Market Restraints
- Stainless steel wire volatility:Raw material price fluctuations for 304 and 316-grade alloys compress margin buffers for mid-tier cable assemblers lacking captive metallurgy capacity.
- Taiwanese certification bottleneck:Shortage of certified brake cable assemblers across Taichung and Kaohsiung component hubs extends production schedules for brands dependent on Taiwanese supply.
- Hydraulic brake substitution:Disc brake systems with mineral oil or DOT fluid actuation displace mechanical cables in commuter and performance segments above $800 retail price points.
Strategic Opportunities
- Medical-rehabilitation adaptive cycles:FDA oversight of brake systems on therapeutic bicycles creates specialized demand for corrosion-resistant stainless formulations in coastal clinical environments.
- EU CSRD disclosure cascade:Corporate sustainability reporting requirements will force Tier-2 supplier audits, rewarding cable manufacturers with documented low-cadmium processes and transparent metallurgy sourcing.
- Compressionless housing convergence:Road cycling's preference for Kevlar-reinforced liners is penetrating gravel and cyclocross segments, expanding addressable premium housing volume beyond traditional road bike boundaries.
Industry Challenges
- Polymer extrusion capex intensity:In-house production of compressionless housing requires capital deployment into multi-layer co-extrusion lines that strain balance sheets for sub-$50 million revenue assemblers.
- Dual regulatory compliance timelines:Simultaneous REACH reformulation and RoHS brass fitting restrictions compress product revalidation windows, forcing parallel rather than sequential certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Brake Cable Market |
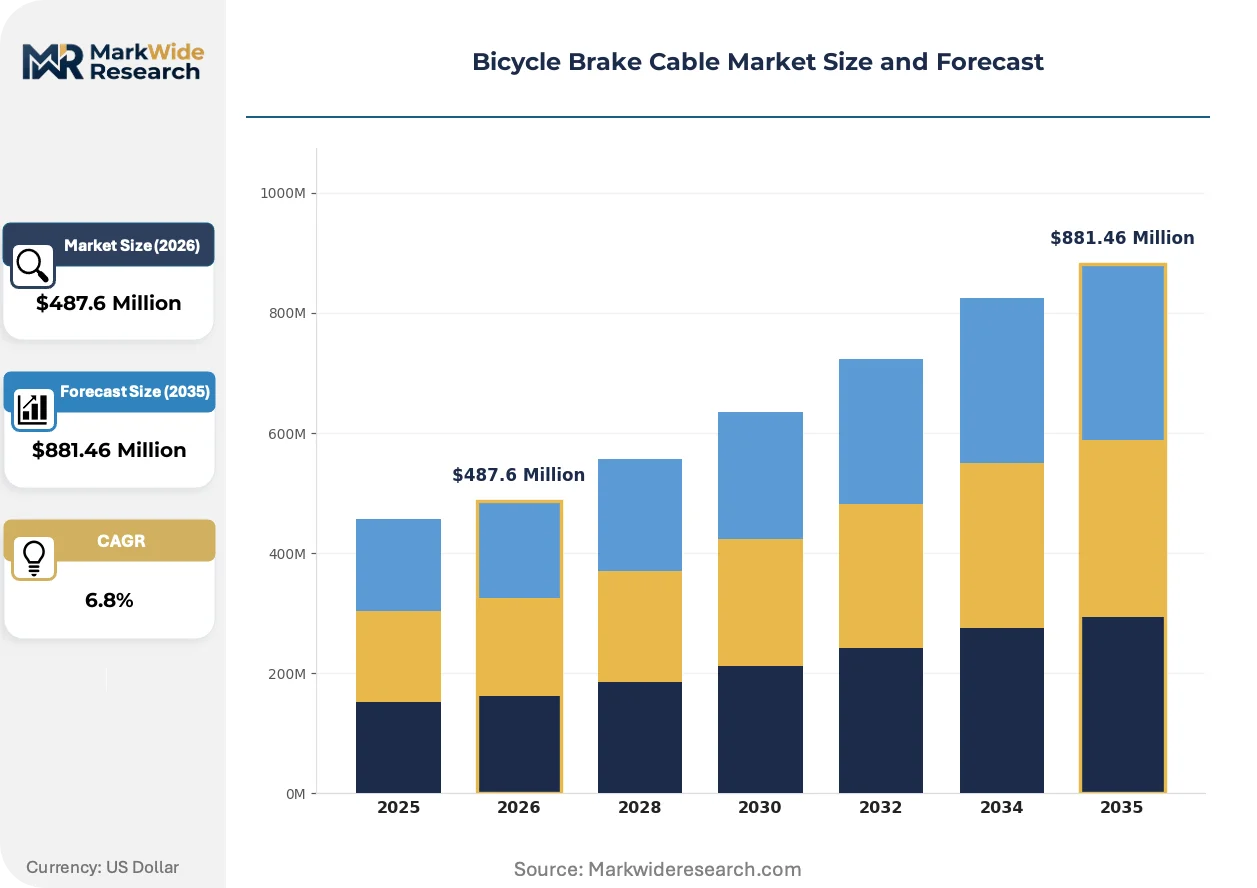
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain, Road, Hybrid, BMX Material: Stainless Steel, Plastic, Copper, Nylon End User: Professional Cyclists, Casual Riders, Bike Shops, Outdoor Enthusiasts Application: Mountain Biking, Commuting, Racing, Touring |
| Companies Covered | Shimano, SRAM Corporation, Jagwire, Dongguan Guofeng Manufacturing Co. Ltd., Lexco Cable Manufacturers, Jiangyin Gaosheng Metal Manufacturing Co. Ltd., ALLIGATOR CABLE ENT. CO. LTD., Tay Young Industrial Co. Ltd., A2Z DESIGN & DEVELOPMENT INC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Brake Cable Market Emerging Trajectories
Material science advances and regulatory chemistry mandates are converging to reshape brake cable specifications, with supplier investment flowing toward corrosion-resistant metallurgy and low-hazard coating processes that satisfy divergent regional compliance frameworks.
Smart cable systems with embedded wear sensors are miniaturizing diagnostic hardware into brake housing liners, enabling real-time friction coefficient monitoring. E-bike fleet operators in Northern Europe specify these assemblies for predictive maintenance scheduling. The technology is miniaturizing sensor packages to sub-2mm diameters that fit standard housing bores without routing modifications.
REACH Annex XVII restrictions on cadmium content in zinc plating are forcing reformulation of end fitting chemistries across export-oriented Chinese suppliers. Jiangyin Gaosheng Metal Manufacturing and comparable producers face 18-month revalidation cycles for new trivalent chromium and zinc-nickel processes. European aftermarket distributors now require batch-level chemical composition certificates, shifting procurement screening criteria toward documentation depth rather than unit cost alone.
Direct-to-consumer brand proliferation is fragmenting traditional bike shop channel dominance for aftermarket brake cables. Canyon, YT Industries, and comparable direct-sales manufacturers bundle proprietary cable sets with complete bicycles, compressing independent retailer attachment rates. North American and German consumers increasingly purchase replacement cables through manufacturer portals rather than local service points, reshaping inventory deployment patterns for Jagwire and comparable aftermarket specialists.
Bicycle Brake Cable Market Segmentation
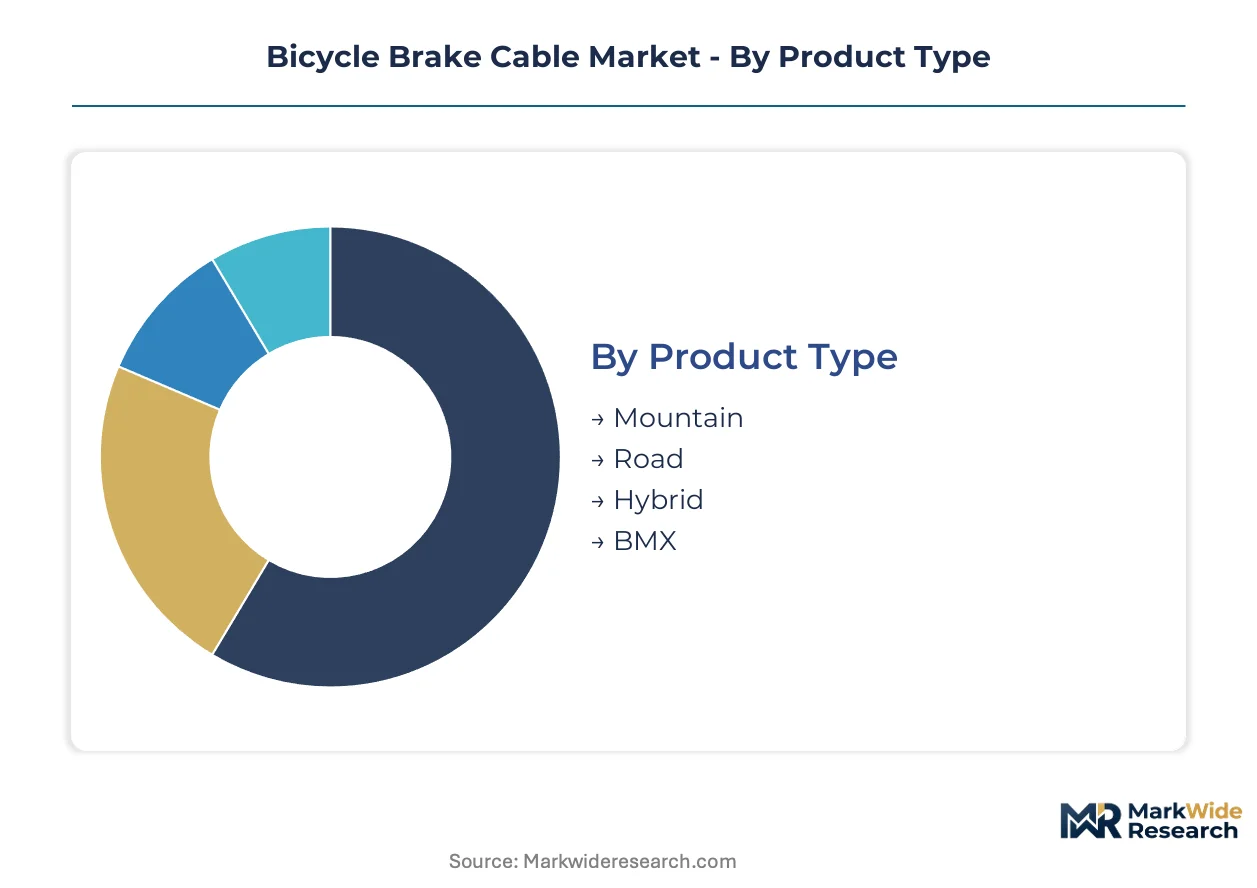
Brake cable segmentation reveals divergent channel economics across cycling disciplines. Material specifications and end-use durability requirements determine whether assemblies flow through OEM supply contracts or aftermarket retail networks.
Product Type:
Mountain and road segments anchor OEM procurement volumes, while hybrid and BMX cables distribute more heavily through independent bike shop channels and direct-to-consumer portals.
- Mountain:Sealed housing systems with polymer-lined compressionless architecture withstand wet-terrain exposure. Demand concentrates in North American and European markets where trail riding penetration drives replacement cycles for contaminated cable sets.
- Road:Kevlar-reinforced compressionless housing delivers sub-0.15 friction coefficients for precise modulation under high-tension routing. Expansion concentrates in gravel and cyclocross subsegments as these disciplines adopt road-derived specifications.
- Hybrid:Entry-level coiled housing with basic stainless inner wires serves commuter platforms where cost sensitivity outweighs performance thresholds.
- BMX:Short-run linear-pull cables with reinforced end fittings absorb repeated impact stress in skatepark and dirt-jump environments.
Mountain dominates installed base. Road is where expansion concentrates.
Material:
Cost tier alignment separates premium metallurgy from commodity polymer alternatives, with stainless steel commanding OEM specification while plastic and nylon penetrate price-sensitive hybrid builds.
- Stainless Steel:304 and 316-grade stranded wires deliver fatigue resistance exceeding 100,000 cycles. Coastal markets in Australia and the Netherlands specify marine-grade formulations to combat salt-air corrosion.
- Plastic:PVC-sheathed housing for entry-level commuter bikes in India and Southeast Asia where unit cost constraints dominate procurement criteria.
- Copper:Legacy brass end fittings face REACH-mandated plating reformulation as European distributors require batch-level chemical certificates.
- Nylon:Compressionless liner material co-extruded with Kevlar reinforcement for road and gravel applications demanding minimal compression under load.
Stainless steel commands margin premiums. Nylon is gaining share fastest in housing liner applications.
End User:
Customer type determines service intensity, with professional cyclists and bike shops specifying premium assemblies while casual riders and outdoor enthusiasts default to standard replacement intervals.
- Professional Cyclists:Team mechanics specify corrosion-resistant stainless formulations with documented metallurgy for UCI-sanctioned events.
- Casual Riders:Price-elastic demand for basic cable sets through mass-market sporting goods retailers.
- Bike Shops:Service departments stock mid-tier stainless assemblies with universal compatibility across major brake lever platforms.
- Outdoor Enthusiasts:Self-service replacement demand through e-commerce channels for mountain and gravel bike maintenance.
Bike shops anchor aftermarket volume. Outdoor enthusiasts are climbing the fastest as direct-to-consumer brand proliferation shifts maintenance behavior.
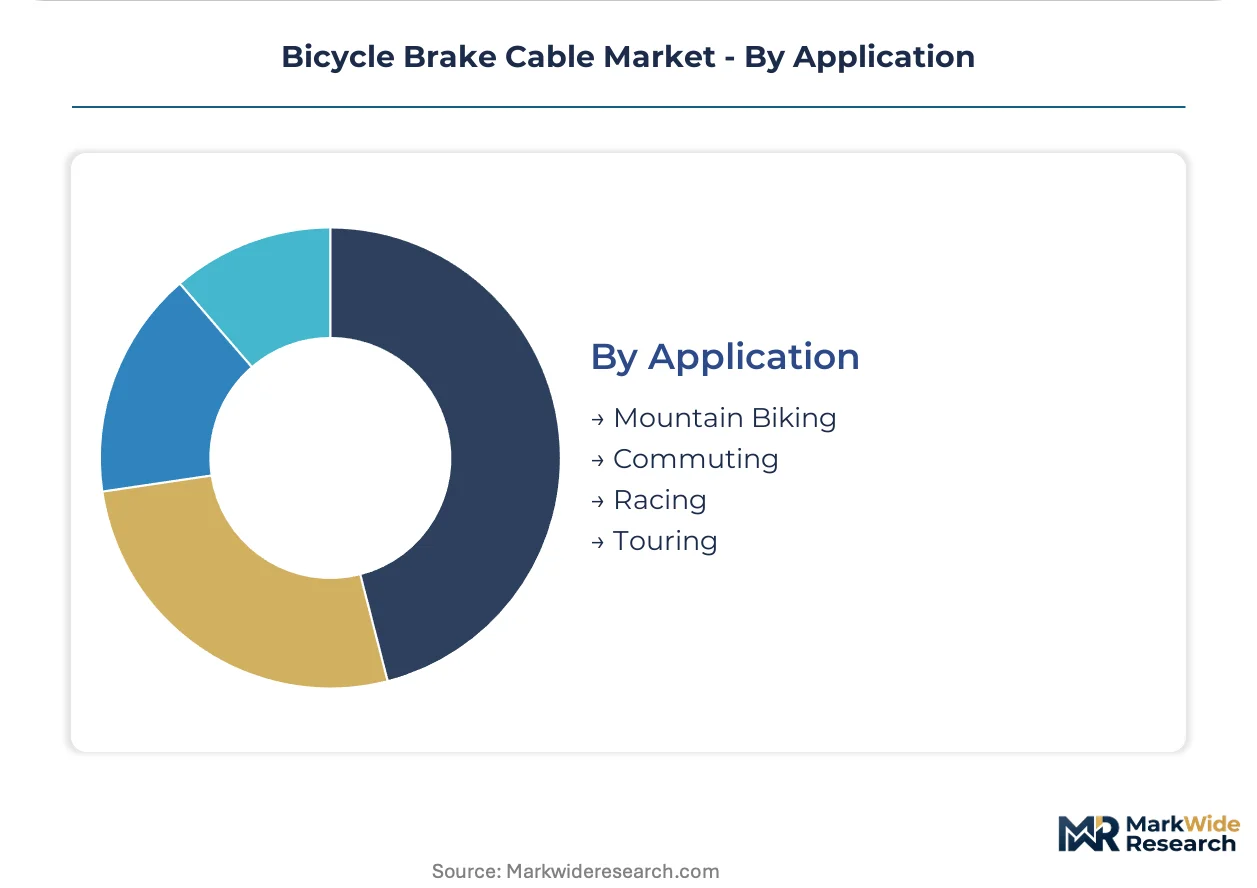
Application:
Usage intensity and environmental exposure separate racing specifications from daily commuter durability requirements, with mountain biking and touring demanding sealed systems against contamination.
- Mountain Biking:Full-sealed housing with internal lubrication maintains function through mud and grit exposure in Pacific Northwest and Alpine terrain.
- Commuting:Basic coiled housing suffices for urban flat-bar platforms where weather protection takes priority over modulation precision.
- Racing:Weight-minimized compressionless sets with titanium end fittings serve criterium and stage race applications.
- Touring:Long-cable-run compatibility for tandems and recumbents requires extended housing lengths with consistent pull ratios.
Commuting dominates unit volume. Mountain biking is where technology premiums sustain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies. European markets prioritize corrosion-resistant marine-grade formulations for coastal exposure, while Asian procurement concentrates on high-volume OEM supply for electric bicycle production clusters. North American demand splits between premium aftermarket channels and direct-to-consumer bundled assemblies.
China
Jiangsu and Guangdong provinces generate the majority of global brake cable output through Dongguan and Jiangyin manufacturing clusters. MIIT industrial standards govern stainless steel wire specifications for domestic e-bike integration. These production hubs supply both captive OEM demand and export aftermarket volumes to European and North American distributors.
Germany
KBA vehicle safety protocols extend to brake system components on speed-pedelecs and cargo e-bikes, elevating certification requirements for cable assemblies. Bavarian and Baden-Württemberg industrial zones host precision metalworking facilities that serve premium European bicycle brands. REACH compliance documentation has become a non-negotiable procurement filter for distributors serving German retail channels.
United States
OSHA workplace safety standards shape assembly protocols at domestic cable fabrication facilities, particularly in California and Pacific Northwest manufacturing locations. FDA oversight applies indirectly where brake cables integrate into medical-rehabilitation adaptive cycles for veterans' healthcare programs. Colorado and Utah mountain bike OEMs drive specification innovation for sealed housing systems in wet-terrain applications.
Netherlands
Coastal salt-air exposure in Amsterdam-Rotterdam-The Hague metropolitan corridors creates specialized demand for 316-grade marine stainless formulations. The country's national environmental regulator enforces strict chemical safety frameworks that exceed baseline REACH requirements for plating chemistries. Randstad logistics infrastructure enables rapid distribution of corrosion-resistant cable sets to Benelux and Northern European markets.
Taiwan
Taichung and Kaohsiung component hubs face acute certified assembler shortages that extend production schedules for mid-tier bicycle brands. The island's precision manufacturing ecosystem supplies high-specification cable assemblies to Japanese and North American premium OEMs. Labor constraints are redirecting some procurement toward mainland Chinese suppliers with documented metallurgy capabilities.
Bicycle Brake Cable Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive metallurgy and polymer extrusion capabilities separating premium positioning from commodity supply. The market structures around three archetypes: vertically integrated component conglomerates controlling raw material formulations, housing specialists with co-extrusion expertise, and regional metal fabricators serving cost-sensitive OEM procurement. Competitive moves concentrate on backward integration into stainless wire drawing and strategic partnerships with e-bike platform manufacturers.
Among Japanese and American component conglomerates, Shimano and SRAM Corporation exemplify the integrated-leader archetype through captive control over metallurgy and polymer processes. Within the Taiwanese-Chinese supplier tier, Jiangyin Gaosheng Metal Manufacturing Co. Ltd. and ALLIGATOR CABLE ENT. CO. LTD. occupy positions shaped by REACH-mandated plating reformulation requirements. Dongguan Guofeng Manufacturing Co. Ltd. represents the scale-driven fabrication model serving high-volume electric bicycle production clusters.
| Leading Market Players |
|---|
| Shimano |
| SRAM Corporation |
| Jagwire |
| Dongguan Guofeng Manufacturing Co. Ltd. |
| Lexco Cable Manufacturers |
| Jiangyin Gaosheng Metal Manufacturing Co. Ltd. |
| ALLIGATOR CABLE ENT. CO. LTD. |
| Tay Young Industrial Co. Ltd. |
| A2Z DESIGN & DEVELOPMENT INC |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Dongguan and Jiangyin producers and European OEMs lock in stainless steel wire allocations while capping price volatility exposure for premium cable assemblies. These multi-year contracts anchor supply access for REACH-compliant manufacturers facing 18-month plating chemistry revalidation cycles.
Pricing Analysis
Contract-based long-term offtake dominates premium tier procurement, with pricing stratifying across marine-grade certification, volume scale, and after-sales bundling. Cost compression in entry-level coiled housing intensifies because Taiwanese certification bottlenecks redirect volume toward mainland Chinese suppliers. Casual riders through mass-market retailers exhibit highest price sensitivity; professional cycling teams and e-bike fleet operators show least.
Supply Chain Analysis
Taiwan Strait shipping lanes constitute a critical chokepoint for precision-machined end fittings transiting from Taichung to Japanese and North American OEMs. Supply concentrates in China, Taiwan, and Germany, drawing from 304-grade stainless wire, Kevlar fiber, and trivalent chromium plating chemistries. Single-source vulnerability runs through Jiangsu province's wire-drawing capacity. Distribution runs through bike shop service departments and direct-to-consumer manufacturer portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH-compliant plating processes creates defensive moats for first-mover suppliers who completed trivalent chromium reformulation ahead of enforcement windows.
For Market Incumbents: Compound captive metallurgy advantages by deepening backward integration into 316-grade marine stainless formulations for Netherlands and Australian coastal markets. Prioritize certification investment to offset hydraulic brake substitution threat in commuter segments above $800 retail. Channel control through bike shop partnerships defends aftermarket attachment rates against direct-to-consumer brand bundling.
For New Entrants and Emerging Players: Lead with medical-rehabilitation adaptive cycles as the most penetrable segment, where FDA oversight and corrosion-resistant specifications deter commodity competition. Target coastal clinical environments in the United States and Netherlands with documented metallurgy certificates. Go-to-market through veterans' healthcare procurement channels and therapeutic equipment distributors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among housing specialists with co-extrusion expertise serving sealed-system replacement cycles in mountain bike segments. Long-term viability across the analysis window favors producers with documented low-cadmium processes and transparent supply chain audit trails. Watch EU CSRD disclosure implementation as the inflection signal for Tier-2 supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Wire Drawing | Captive 304 and 316-grade metallurgy secures margin buffers against raw material volatility. |
| REACH-Compliant Plating Chemistry Reformulation | Trivalent chromium and zinc-nickel processes unlock European aftermarket distribution access. |
| Sealed Housing Technology Investment | Multi-layer co-extrusion lines serve Pacific Northwest and Alpine wet-terrain replacement demand. |
| Medical-Rehabilitation Segment Certification | FDA-compliant corrosion-resistant formulations access veterans' healthcare procurement channels. |
| Direct-to-Consumer Portal Partnership | Manufacturer bundling agreements with Canyon and YT Industries compress bike shop dependency. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brake cable assemblers, OEM procurement managers at e-bike manufacturers, bike shop service directors, and metallurgy specialists at stainless wire producers. Secondary validation drew from MIIT industrial standards documentation, REACH Annex XVII regulatory filings, KBA vehicle safety protocols, and customs trade data for wire and housing components. Bottom-up volume estimates triangulated against top-down market sizing across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation by cycling discipline, material grade tier, end-user service intensity, and regional regulatory cluster. CAGRs derived from production volume trajectories at Jiangsu and Guangdong manufacturing clusters, e-bike platform shipment forecasts, and replacement cycle frequency for sealed versus unsealed housing systems. Industry-specific inputs included REACH compliance cost pass-through assumptions and hydraulic brake substitution elasticities by retail price tier.
Underlying assumptions cover sustained electric bicycle production growth, stable stainless steel alloy pricing, and phased REACH enforcement timelines, with deviation risk concentrated in Taiwanese labor constraints and raw material volatility. Practitioners should keep alternative scenarios live as regulatory disclosure requirements and brake system technology transitions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
Industrial Gearbox Market
Vehicle Components
Steel and Rubber Tracks Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
Oil Filter Elements Market
Vehicle Components
Refrigerated Trailer Door Lock Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Steering Knuckle Market