
 Electric Vehicle Skateboard Platform Market | 2026-2036
Electric Vehicle Skateboard Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Skateboard Platform Market Insights
Software-defined battery management is hardening as the core monetizable layer above commodity hardware. Tesla leverages over-the-air thermal calibration to sustain recurring revenue streams across its fleet base. Rivian anchors its adventure-truck positioning through proprietary drive-mode programming that controls terrain response. BYD dominates cost-optimized cell-to-pack integration, which extends its manufacturing scale advantage across multiple vehicle classes.
An electric vehicle skateboard platform is a flat, modular chassis architecture integrating battery packs, electric motors, power electronics, and thermal management into a single structural floorpan, typically achieving a center of gravity below 500 mm to maximize cabin volume and crash performance. Its primary commercial purpose is to decouple body design from propulsion engineering, enabling OEMs to develop multiple vehicle silhouettes on one validated underbody. Battery Electric configurations currently occupy the largest margin pool due to cell chemistry standardization and volume scale, while Solid-state Battery technology is attracting the fastest development capital as manufacturers chase energy density targets above 400 Wh per kilogram. Modular Platform architectures are maturing fastest in delivery van applications, where uniform load floors and standardized wheelbases reduce fleet operator procurement complexity.
The EPA tailpipe standards and NHTSA crashworthiness protocols in the United States are forcing structural reinforcement of battery enclosures, which adds mass but protects platform integrity. EMA battery safety guidelines and EU Green Deal carbon-border adjustments are shaping European sourcing rules for cell materials and recycled content thresholds. China's MIIT and SAMR enforce GB standards that mandate thermal runaway propagation resistance, directly influencing platform cooling circuit design. Stakeholders must monitor how divergent thermal-test protocols across these jurisdictions affect single-platform export economics.
Market Dynamics
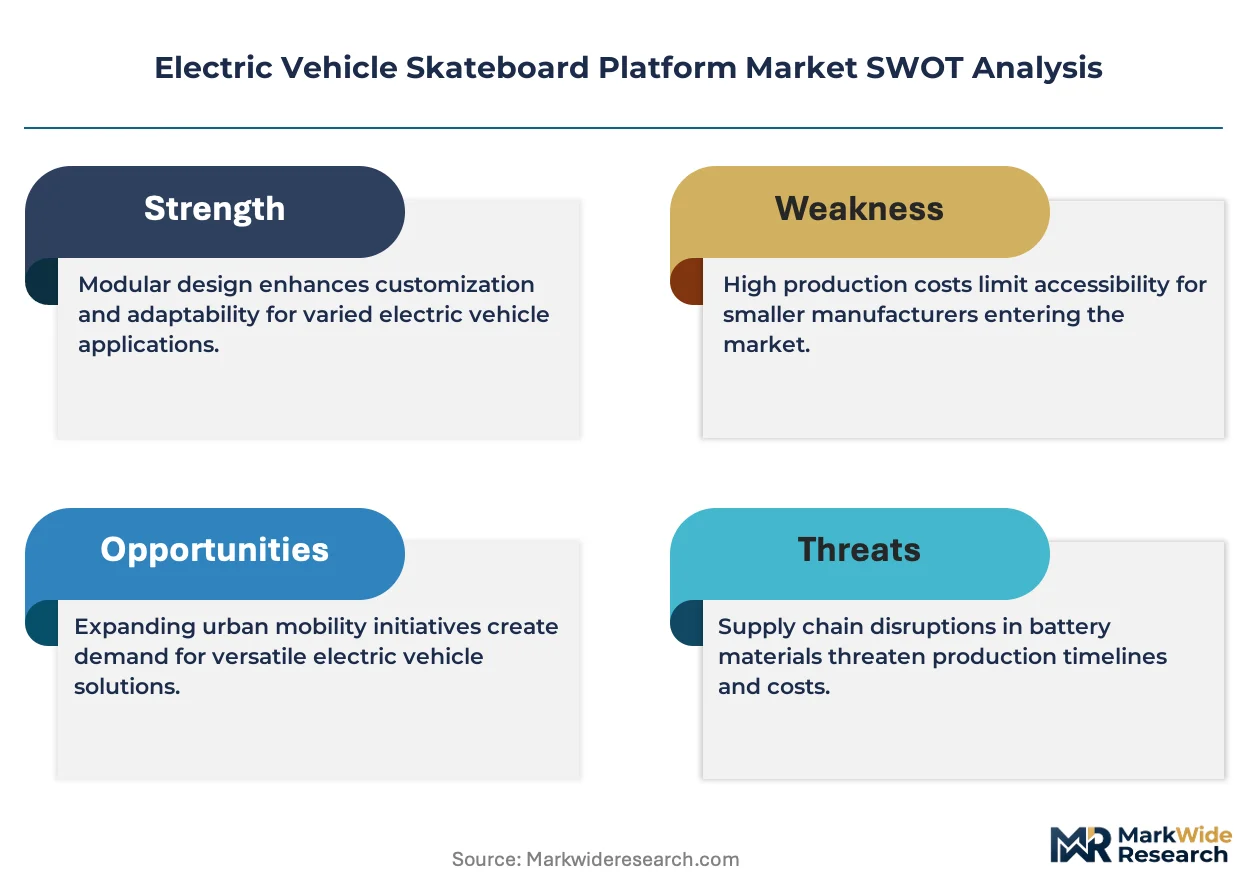
Modular battery-integrated floorpans are compressing vehicle development cycles from 48 months to under 30 months, forcing incumbent OEMs to abandon legacy ladder-frame engineering for flat-deck architectures that accommodate multiple body styles on shared thermal and crash-tested foundations.
Growth Catalysts
- Cell-to-pack thermal integration:Eliminating module housings reduces mass and cost while improving volumetric energy density, accelerating adoption in commercial delivery fleets.
- China's MIIT dual carbon mandates:Updated GB standards for EV safety and carbon intensity are compelling domestic manufacturers to standardize platform architectures across vehicle classes.
- Fleet operator TCO pressure:Logistics providers in Germany and the Netherlands are consolidating procurement around standardized wheelbases and uniform load floors to reduce spare parts complexity.
Market Restraints
- Lithium price volatility:Raw material cost swings between extraction regions in South America and Australia compress gross margins on battery-dominant platform cost structures.
- Single-source thermal management components:Concentration of precision cooling circuit suppliers in East Asian manufacturing clusters creates vulnerability to regional logistics disruptions.
- Crash-test protocol divergence:NHTSA side-pole impact requirements differ materially from EU Green Deal-aligned testing, forcing redundant structural reinforcement for export platforms.
Strategic Opportunities
- Indian commercial vehicle electrification:BIS standards alignment with global platform specifications creates entry paths for modular architectures in the sub-3.5-tonne delivery segment.
- Solid-state battery convergence:Integration of ceramic electrolyte cells with existing thermal management hardware enables 400 Wh/kg energy density without complete platform redesign.
- Brazilian flex-fuel hybrid platforms:ANVISA-aligned safety frameworks for biofuel-compatible battery enclosures open white space in Latin American light-commercial applications.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineering for ASIL-D-rated battery management systems outpaces university pipeline output in European automotive regions.
- Multi-jurisdiction homologation timelines:Simultaneous EPA, EMA, and MIIT certification cycles extend platform validation from 18 to 32 months.
- Legacy supplier contract renegotiation:Powertrain component agreements with tiered volume commitments conflict with platform consolidation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Skateboard Platform Market |
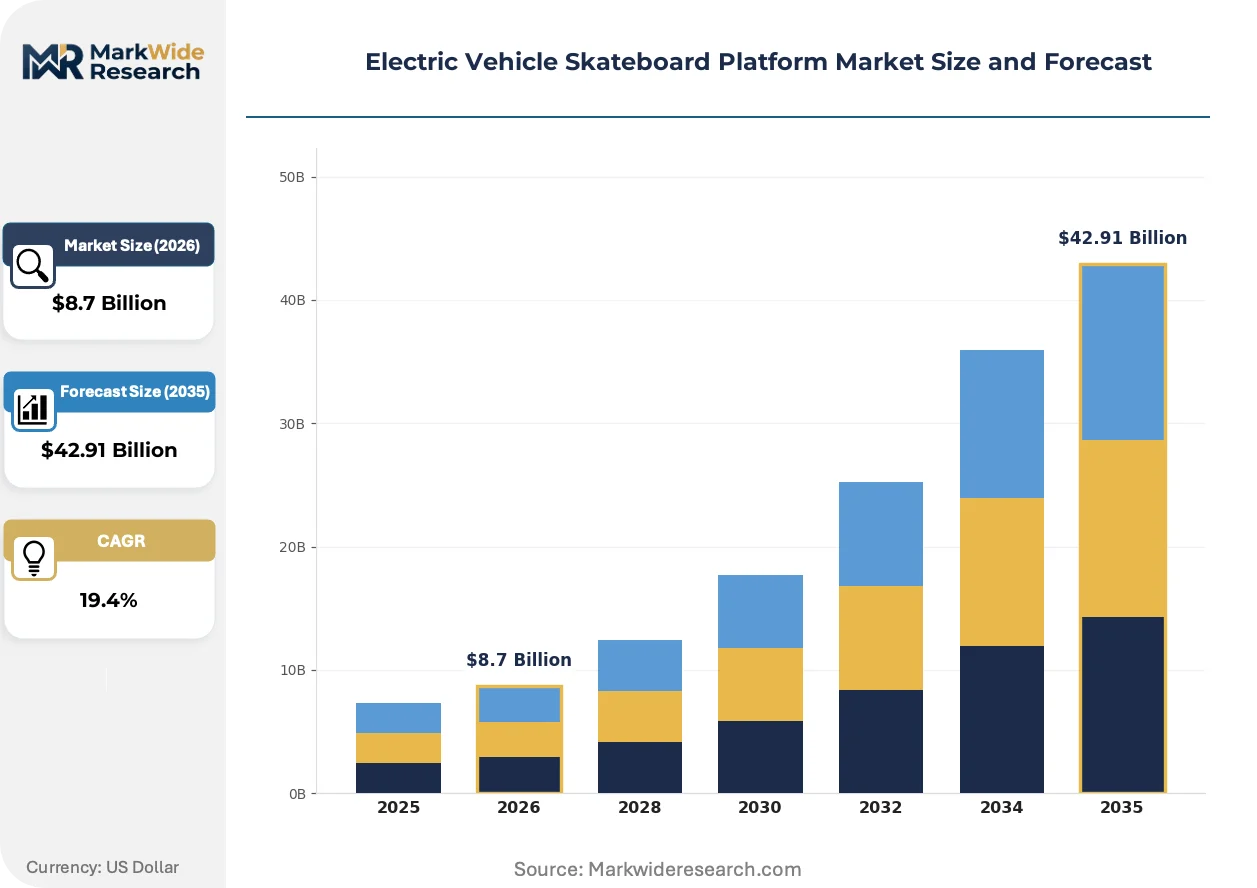
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric, Hybrid Electric, Fuel Cell Electric, Plug-in Hybrid End User: OEMs, Fleet Operators, Aftermarket Manufacturers, Logistics Providers Technology: Li-ion Battery, Solid-state Battery, Modular Platform, Wireless Charging Application: Urban Mobility, Delivery Services, Recreational Vehicles, Industrial Automation |
| Companies Covered | Tesla, Rivian, General Motors, Volkswagen Group, BYD, Hyundai Motor Group, Canoo, REE Automotive, Foxconn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Skateboard Platform Market Trends and Innovations
Software-defined thermal architectures are replacing fixed cooling circuits as the primary differentiation layer, enabling real-time battery conditioning that adapts to route topography and charging infrastructure availability without hardware changes.
Structural battery enclosures are absorbing crash-energy management functions previously handled by separate frame rails, allowing Volkswagen Group and Hyundai Motor to reduce underbody part counts by 40 percent while maintaining NHTSA five-star ratings. Commercial van manufacturers in Germany are adopting these integrated floorpans fastest, leveraging the mass reduction to extend range without enlarging cell packs. The shift is compressing supplier tiers as stamping houses acquire thermal engineering capabilities to retain platform contracts.
EU Green Deal carbon-border adjustments are forcing platform manufacturers to document recycled aluminum and lithium content across supply chains, with ECHA REACH compliance now requiring material passports tracing cell chemistry to mine origin. European OEMs are responding by regionalizing battery enclosure production near Dresden and Zwickau to shorten carbon-intensity audit trails. The regulatory friction is favoring integrated platform specialists over body-on-frame assemblers lacking upstream material control.
Leasing structures for commercial fleets are displacing outright purchase as the dominant procurement model, with operators in the Netherlands and Denmark prioritizing platforms offering guaranteed battery residual value and bundled thermal maintenance. This shift concentrates buyer power among three or four national fleet aggregators capable of standardizing specifications across thousands of units. Platform vendors must now price hardware as a subscription component rather than capital equipment, restructuring revenue recognition and service organization incentives.
Electric Vehicle Skateboard Platform Market Segmentation
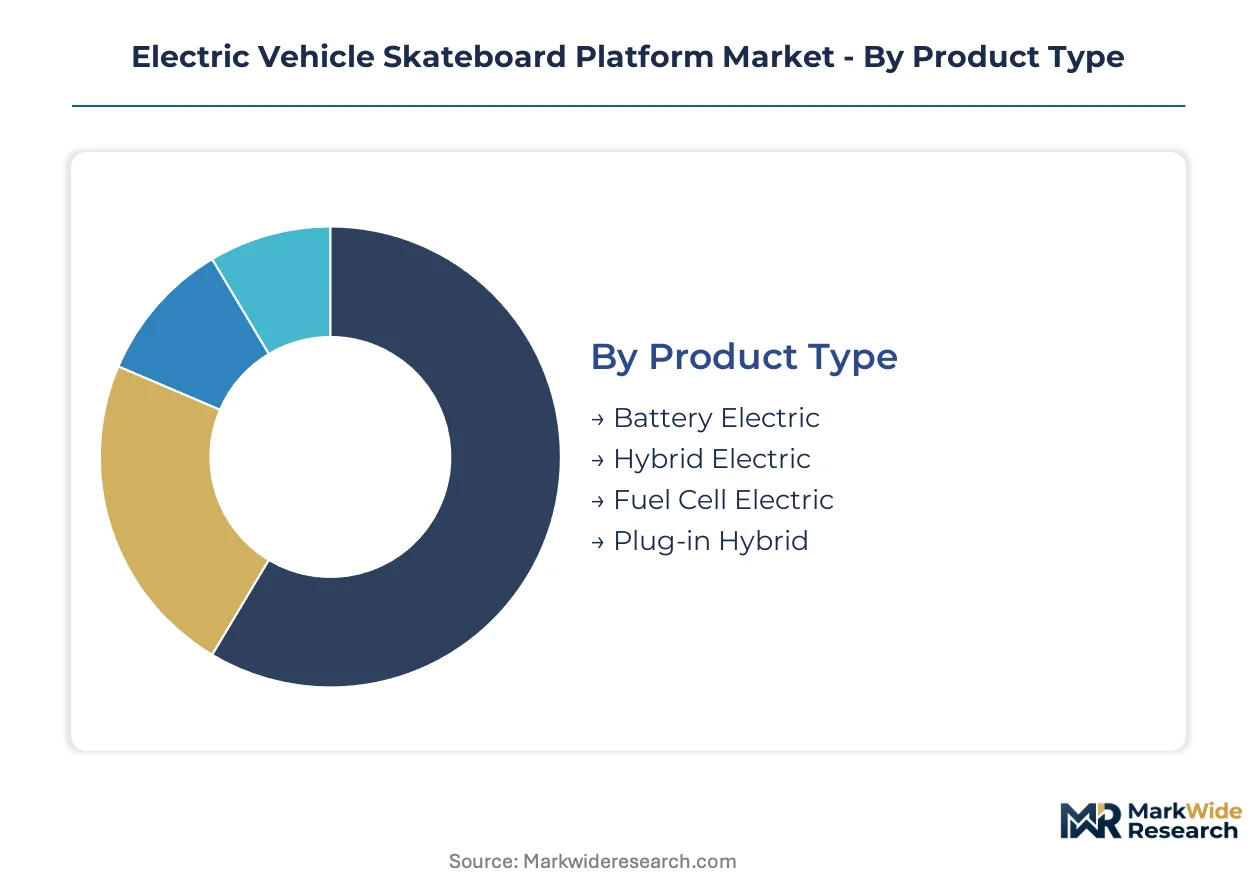
Platform segmentation reveals how technical choices lock in cost structures and service revenue models across vehicle lifecycles. Each dimension—propulsion chemistry, buyer type, thermal architecture, and duty cycle—creates distinct margin profiles and supplier ecosystems.
Product Type:
Battery Electric platforms command the volume tier through cell chemistry standardization and manufacturing scale, while Fuel Cell Electric architectures occupy the premium niche requiring specialized hydrogen infrastructure.
- Battery Electric:Flat floorpans integrate cell-to-pack architectures achieving center-of-gravity targets below 500 mm. Demand concentrates in German commercial van manufacturing near Dresden and Zwickau, driven by fleet operator pressure for uniform load floors and reduced spare parts complexity.
- Hybrid Electric:Dual-powertrain compatibility demands structural reinforcement for thermal isolation between battery enclosures and combustion components. Procurement is shifting toward Indian sub-3.5-tonne delivery applications where BIS standards alignment creates modular entry paths.
- Fuel Cell Electric:High-pressure hydrogen storage integration requires specialized crash-tested floorpan modifications. Japanese METI hydrogen corridor investments anchor current demand.
- Plug-in Hybrid:Transitional architecture blending battery-dominant range with range-extender packaging. European EMA battery safety guidelines shape cooling circuit specifications.
Today's leader: Battery Electric. Tomorrow's challenger: Fuel Cell Electric.
End User:
Procurement authority is concentrating among fleet aggregators capable of standardizing specifications across thousands of units, displacing fragmented OEM decision-making.
- OEMs:Volkswagen Group and Hyundai Motor leverage validated underbodies to compress development cycles from 48 months to under 30 months across multiple body styles. Platform consolidation conflicts with legacy tiered supplier volume commitments.
- Fleet Operators:Dutch and Danish logistics providers now prioritize guaranteed battery residual value and bundled thermal maintenance in leasing structures. This buyer concentration forces hardware pricing as subscription components rather than capital equipment.
- Aftermarket Manufacturers:Conversion specialists require backward-compatible thermal management interfaces. China's SAMR enforcement of GB thermal runaway standards limits retrofit architecture flexibility.
- Logistics Providers:German and Netherlands operators consolidate procurement around standardized wheelbases. NHTSA side-pole impact divergence from EU protocols forces redundant structural reinforcement for export flexibility.
Contracting authority clusters with Fleet Operators. Technology specification power remains with OEMs.
Technology:
Software-defined layers are displacing fixed hardware as the primary differentiation mechanism, with thermal architecture programmability determining service revenue potential.
- Li-ion Battery:Dominant chemistry with established cell-to-pack integration pathways. BYD's cost-optimized manufacturing scale extends across multiple vehicle classes through standardized module elimination.
- Solid-state Battery:Ceramic electrolyte cells promise energy density above 400 Wh per kilogram without complete platform redesign. Development capital is concentrating fastest here as manufacturers chase volumetric efficiency gains.
- Modular Platform:Shared thermal and crash-tested foundations accommodate multiple body styles. Delivery van applications mature fastest due to uniform load floor requirements.
- Wireless Charging:Inductive pad integration demands precise coil alignment tolerances in floorpan stamping. Urban mobility pilots in Chinese megacities test fleet-scale deployment economics.
Li-ion Battery anchors current production. Solid-state Battery offers the steepest expansion trajectory.
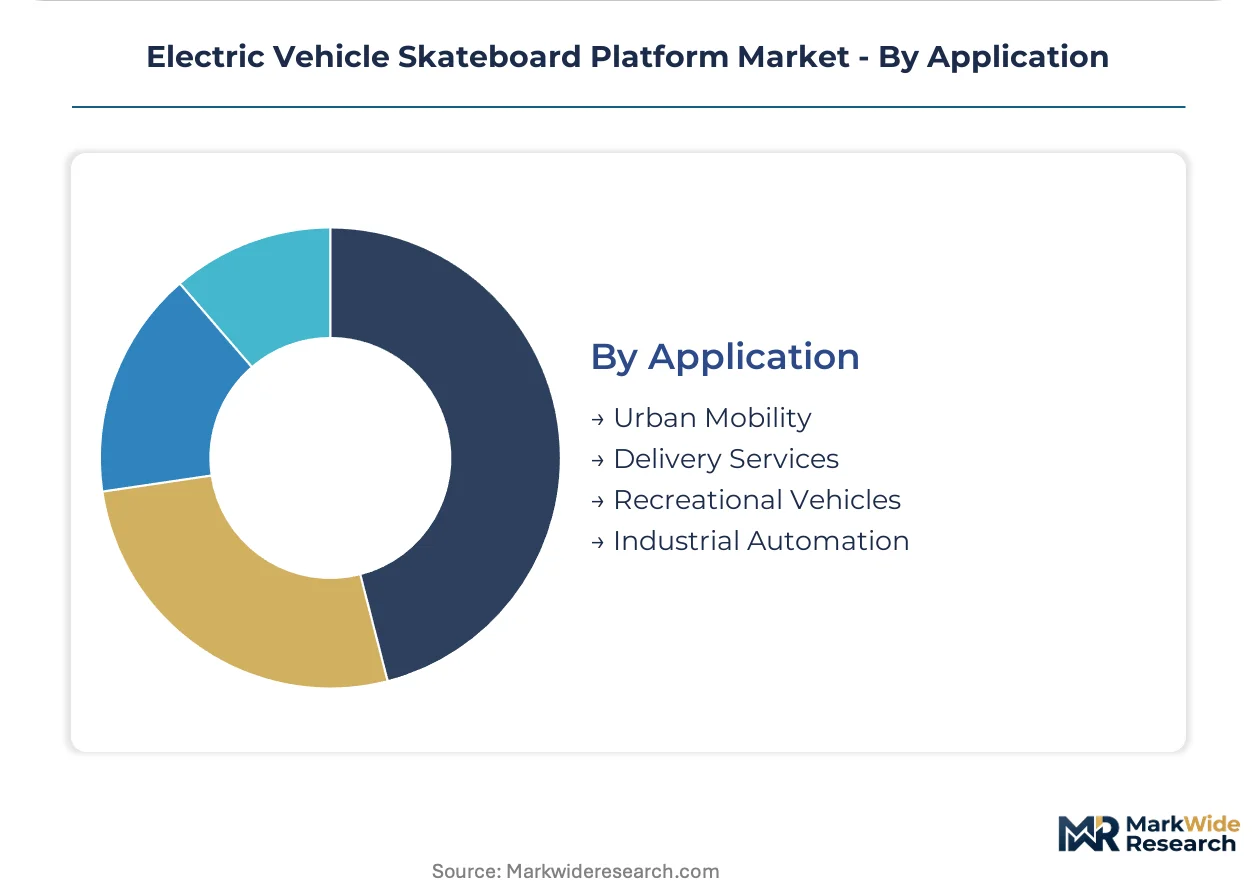
Application:
Duty cycle intensity determines thermal management hardware specifications and battery residual value guarantee structures.
- Urban Mobility:Frequent stop-start operation demands aggressive regenerative braking integration and real-time thermal calibration. Tesla's over-the-air thermal management sustains recurring revenue across fleet bases.
- Delivery Services:Predictable route topography enables pre-conditioning algorithms that extend range without cell pack enlargement. Rivian's proprietary drive-mode programming controls terrain response for adventure positioning.
- Recreational Vehicles:Variable load and grade profiles require adaptive suspension-thermal coordination. Brazilian ANVISA-aligned safety frameworks for biofuel-compatible enclosures open Latin American white space.
- Industrial Automation:Fixed-route autonomous operation permits simplified cooling circuits with scheduled maintenance windows. EU ECHA REACH material passport requirements complicate recycled content documentation.
Delivery Services dominate volume deployment. Industrial Automation presents the highest service attach rate potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial policy accelerates platform standardization faster than the United States' fragmented regulatory environment, while China's MIIT mandates compress development timelines beyond what European OEMs can match independently.
United States
Fleet electrification mandates in California and New York drive standardized underbody procurement among logistics operators. NHTSA crashworthiness protocols force structural reinforcement of battery enclosures that adds mass but protects platform integrity. Detroit-area engineering centers concentrate legacy OEM retooling efforts toward flat-deck architectures.
Germany
Volkswagen Group and component suppliers build dedicated skateboard assembly lines near Dresden and Zwickau to serve pan-European van demand. EMA battery safety guidelines and EU Green Deal carbon-border adjustments shape recycled content thresholds for cell materials. The Saxony manufacturing cluster anchors continental platform production capacity.
China
MIIT dual carbon goals and updated GB standards for EV safety accelerate platform modularization requirements across domestic manufacturers. SAMR enforcement mandates thermal runaway propagation resistance, directly influencing cooling circuit design specifications. Shenzhen and Shanghai house the dominant cell-to-pack integration specialists.
India
BIS standards alignment with global platform specifications creates entry paths for modular architectures in the sub-3.5-tonne delivery segment. Central government PLI scheme incentives for commercial vehicle electrification attract foreign platform licensing agreements. Tamil Nadu and Gujarat host emerging assembly partnerships between domestic fleet operators and international chassis suppliers.
Japan
METI hydrogen corridor investments anchor current demand for fuel cell-compatible floorpan modifications. JIS standards for high-pressure storage integration require specialized crash-tested designs that diverge from battery-dominant architectures. Nagoya-area engineering groups concentrate on dual-chemistry platform adaptability.
Electric Vehicle Skateboard Platform Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs controlling premium passenger applications while electronics fabricators capture commercial van volume. The vendor base organizes into three tiers: full-stack platform owners, modular component licensors, and contract assembly operators. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players race to secure thermal management supplier relationships and fleet operator subscription contracts.
Within the full-stack platform tier, Tesla and Rivian exemplify the vertically integrated archetype that controls software-defined thermal architectures as a monetizable layer above commodity hardware. BYD occupies a position representing the cost-optimized manufacturing scale advantage through standardized cell-to-pack elimination across multiple vehicle classes. These three anchors demonstrate how geographic origin and corporate structure correlate with divergent strategic positioning in battery-dominant versus software-dominant platform economics.
| Leading Market Players |
|---|
| Tesla |
| Rivian |
| General Motors |
| Volkswagen Group |
| BYD |
| Hyundai Motor Group |
| Canoo |
| REE Automotive |
| Foxconn |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ASIL-D-rated battery management systems and commodity thermal hardware manifests in both pricing stratification and supply chain configuration, with German and Chinese regulatory tiers commanding premium procurement while standard-grade platforms compete on cell-to-pack integration scale.
Pricing Analysis
Capacity additions in China's Shenzhen and Shanghai manufacturing clusters are reshaping price floors for standardized cell-to-pack architectures. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-D certification status, OEM brand positioning, and bundled thermal maintenance guarantees. Pricing pressure stems from lithium price volatility between South American and Australian extraction regions. Fleet aggregators in the Netherlands and Denmark exhibit highest price sensitivity due to subscription-model procurement, while premium passenger OEMs absorb certification premiums with least negotiation leverage.
Supply Chain Analysis
EU Green Deal carbon-border adjustments and China's MIIT domestic-content mandates are reshaping sourcing patterns for battery enclosure materials. Production gravity centers on China, South Korea, and Germany for cell-to-pack integration, with precision cooling circuit suppliers concentrated in East Asian manufacturing clusters. Raw material dependencies include lithium carbonate from South America, nickel from Indonesia, and recycled aluminum from European smelters. Single-source thermal management component vulnerability creates exposure to regional logistics disruptions. Distribution runs through fleet operator aggregators capable of standardizing specifications across thousands of units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with China's updated GB standards for EV safety and thermal runaway propagation resistance driving platform modularization demand across domestic and export-oriented manufacturers.
For Market Incumbents: Lock in thermal management supplier relationships through long-term offtake agreements before capacity constraints tighten. Consolidate platform engineering centers near Dresden and Zwickau to satisfy EU Green Deal carbon-border audit requirements. Defend against solid-state battery entrants by accelerating cell-to-pack cost reduction through module elimination at scale.
For New Entrants and Emerging Players: The premium-economy price-point gap in Indian sub-3.5-tonne commercial delivery applications offers white-space entry with BIS standards alignment as the regulatory pathway. Brazilian ANVISA-aligned biofuel-compatible battery enclosures present underserved Latin American light-commercial demand. Target fleet operator subscription contracts with guaranteed residual value structures rather than capital equipment sales.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated platform specialists controlling upstream material passports and downstream thermal maintenance revenue. Five-to-ten-year viability favors vendors with captive cell-to-pack integration and software-defined thermal architecture monetization. Monitor solid-state battery ceramic electrolyte cell qualification timelines as the inflection signal for platform redesign cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen Group's dedicated Dresden assembly lines compress development cycles across van silhouettes. |
| Battery Supply Agreement | Long-term cell-to-pack partnerships with Chinese MIIT-certified suppliers secure GB thermal runaway compliance. |
| Software-Defined Vehicle Investment | Tesla's over-the-air thermal calibration sustains recurring revenue streams independent of hardware refresh cycles. |
| Geographic Manufacturing Footprint | Regionalizing enclosure production near Zwickau shortens EU ECHA REACH carbon-intensity audit trails. |
| Charging Infrastructure Partnership | Wireless charging coil alignment tolerances in floorpan stamping enable urban mobility pilot scaling in Chinese megacities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator aggregators in Germany and the Netherlands, and thermal management specialists with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and MIIT GB standards documentation. Bottom-up segment sizing triangulated against top-down market envelope checks.
Segment-weighting across the analysis window applied propulsion architecture, vehicle class, and regional regulatory cluster as primary dimensions, with CAGRs derived from slope analysis of technology adoption curves and fleet procurement cycle timing. Forecast inputs incorporated lithium price trajectory assumptions and solid-state battery ceramic electrolyte development timelines without specifying commercialization dates.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery integration would alter the outlook if ceramic electrolyte cells achieve 400 Wh per kilogram targets ahead of thermal management hardware compatibility schedules. Forecasts reflect assumptions about regulatory harmonization between NHTSA, EMA, and MIIT protocols that may diverge rather than converge. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Rental Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
Electric Vehicle Helmet Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
GCC Electric Vehicle Market
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Vehicle Battery Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
Netherlands Solar E-Bike Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market