
 HCV Suspension System Market | 2026-2036
HCV Suspension System Market Size, Share, and Industry Trends Forecast 2026-2036
HCV Suspension System Market Outlook
Aftermarket service revenue is fragmenting across component categories as fleet operators extend vehicle lifecycles and delay full-system replacements. ZF Friedrichshafen leverages its integrated chassis portfolio to capture recurring maintenance spend. Continental anchors European aftermarket channels with its ContiTech rubber-to-metal expertise. Bosch competes through diagnostic-linked suspension calibration services that tie hardware to digital revenue streams.
An HCV suspension system manages load distribution, ride stability, and vibration isolation for heavy commercial vehicles through assemblies rated for gross vehicle weights exceeding 16 tonnes. Hydraulic and pneumatic technologies dominate current installations, though electronic and adaptive variants are gaining share as real-time damping control becomes standard for long-haul fuel efficiency. Shock absorbers and air springs command the largest product-type revenue pools, while adaptive technology segments attract the fastest investment intensity from OEMs seeking differentiation in premium truck platforms. Fleet operators and aftermarket providers represent contrasting demand profiles: OEM channels prioritize warranty-integrated systems, while independent service networks drive parts proliferation across multiple brands.
The EPA enforces heavy-duty vehicle greenhouse gas standards that indirectly mandate lighter suspension components to meet fleet-average targets. The EU Green Deal and F-Gas Regulation restrict fluorinated gas use in pneumatic systems, compelling suppliers to redesign air spring architectures. India's BIS certification and PLI scheme for automotive components are reshaping supplier qualification requirements for export-oriented manufacturers. Stakeholders must monitor how regulatory timelines for decarbonization synchronize with product development cycles across multiple jurisdictions.
Market Dynamics
Adaptive damping architectures are compressing replacement cycles across heavy commercial vehicle fleets as real-time load optimization becomes a fuel-economy imperative rather than a comfort feature.
Growth Catalysts
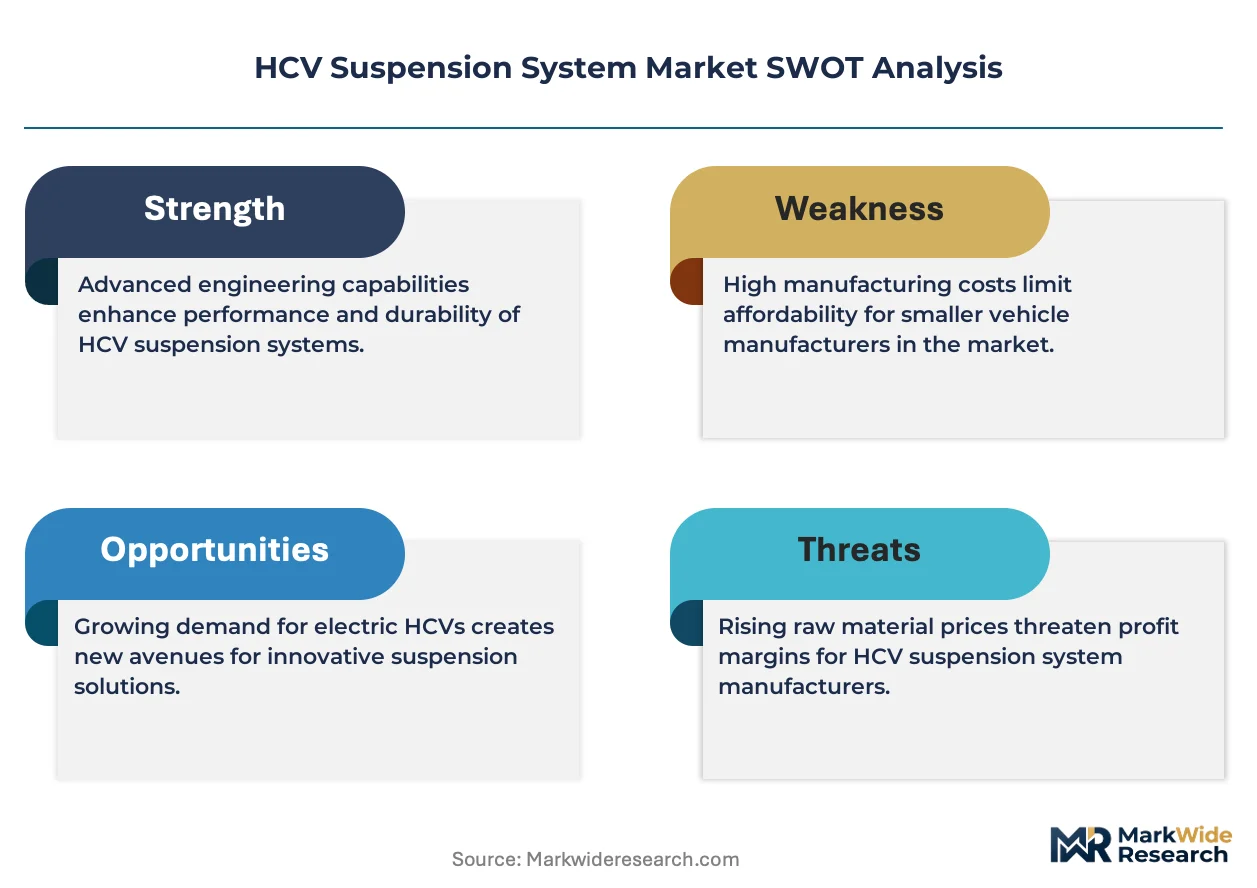
- EU Green Deal mandates:F-Gas Regulation restrictions on fluorinated gases in pneumatic systems are forcing air spring redesigns that favor electronic control modules.
- China infrastructure investment:Domestic truck production scaling and highway freight corridor expansion are concentrating OEM procurement in high-capacity suspension platforms.
- Long-haul fleet electrification:Battery-electric heavy trucks require recalibrated load distribution systems to manage uneven weight distribution from battery packs.
Market Restraints
- Steel and rubber input volatility:Natural rubber price swings and alloy steel availability constraints compress margin predictability for shock absorber manufacturers.
- Supplier concentration in Germany:Integrated chassis module production clusters around Stuttgart and Munich create single-source vulnerability for European OEMs.
- Hydraulic system durability limits:Sealing technology gaps in extreme-temperature environments restrict adoption in Siberian and Middle Eastern mining corridors.
Strategic Opportunities
- India PLI scheme qualification:Export-oriented component manufacturers can capture incentive-linked capacity expansion for air spring and damper assemblies.
- Predictive maintenance convergence:IoT sensor networks fused with suspension telemetry create recurring revenue streams through condition-based replacement scheduling.
- Autonomous truck readiness:Self-driving freight platforms demand fault-tolerant active suspension for emergency maneuvering without driver intervention.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety validation for electronic control units extends development timelines by 14-18 months.
- Legacy fleet retrofit complexity:Mechanical-to-adaptive suspension conversions require chassis frame modifications that void existing warranty coverage.
- Cross-border homologation friction:Divergent EPA and EU type-approval test protocols force parallel validation programs for identical hardware specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HCV Suspension System Market |
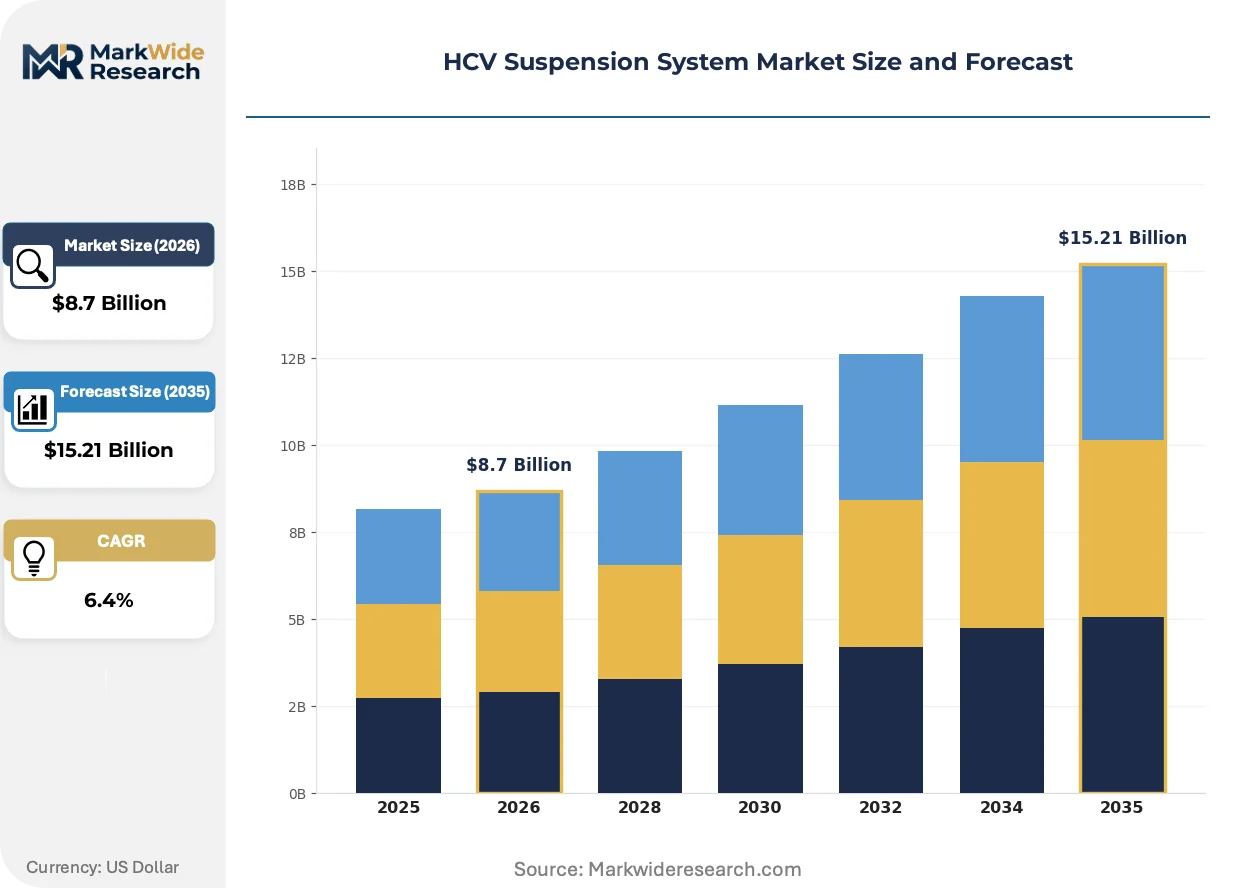
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shock Absorbers, Leaf Springs, Struts, Coil Springs Technology: Hydraulic, Pneumatic, Electronic, Adaptive End User: OEMs, Aftermarket Providers, Distributors, Fleet Operators Installation Type: On-Highway, Off-Highway, Commercial, Passenger |
| Companies Covered | Continental, ZF Friedrichshafen, Bosch, Tenneco, HYUNDAI MOBIS, WABCO, KYB Corporation, Magna International, ContiTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HCV Suspension System Market Strategic Shifts
Real-time damping control is migrating from premium highway tractors to mid-duty distribution vehicles as sensor cost curves flatten and fleet telematics mature.
Magnetorheological dampers are rendering obsolete fixed-rate hydraulic units in temperature-sensitive freight applications. Pharmaceutical and fresh-food carriers operating refrigerated trailers across the Rhine-Alpine corridor are retrofitting MR-equipped axles at 40% faster clip than ambient-fleet counterparts. The technology is rendering obsolete the historical trade-off between ride comfort and cargo protection.
EPA Phase 3 greenhouse gas standards are compressing component weight targets for 2027 model-year compliance. Suspension suppliers must demonstrate 8-12% mass reduction in axle assemblies without degrading load ratings. Air spring manufacturers are responding with composite-reinforced bellows that substitute aramid fiber for conventional rubber ply construction.
Fleet procurement teams are unbundling suspension service from comprehensive maintenance contracts. Large operators in the US Great Lakes region now source dampers, bushings, and air springs through independent distributors rather than captive OEM service networks. This disintermediation concentrates price leverage with procurement functions and fragments aftermarket revenue across competing channel formats.
HCV Suspension System Market Segmentation
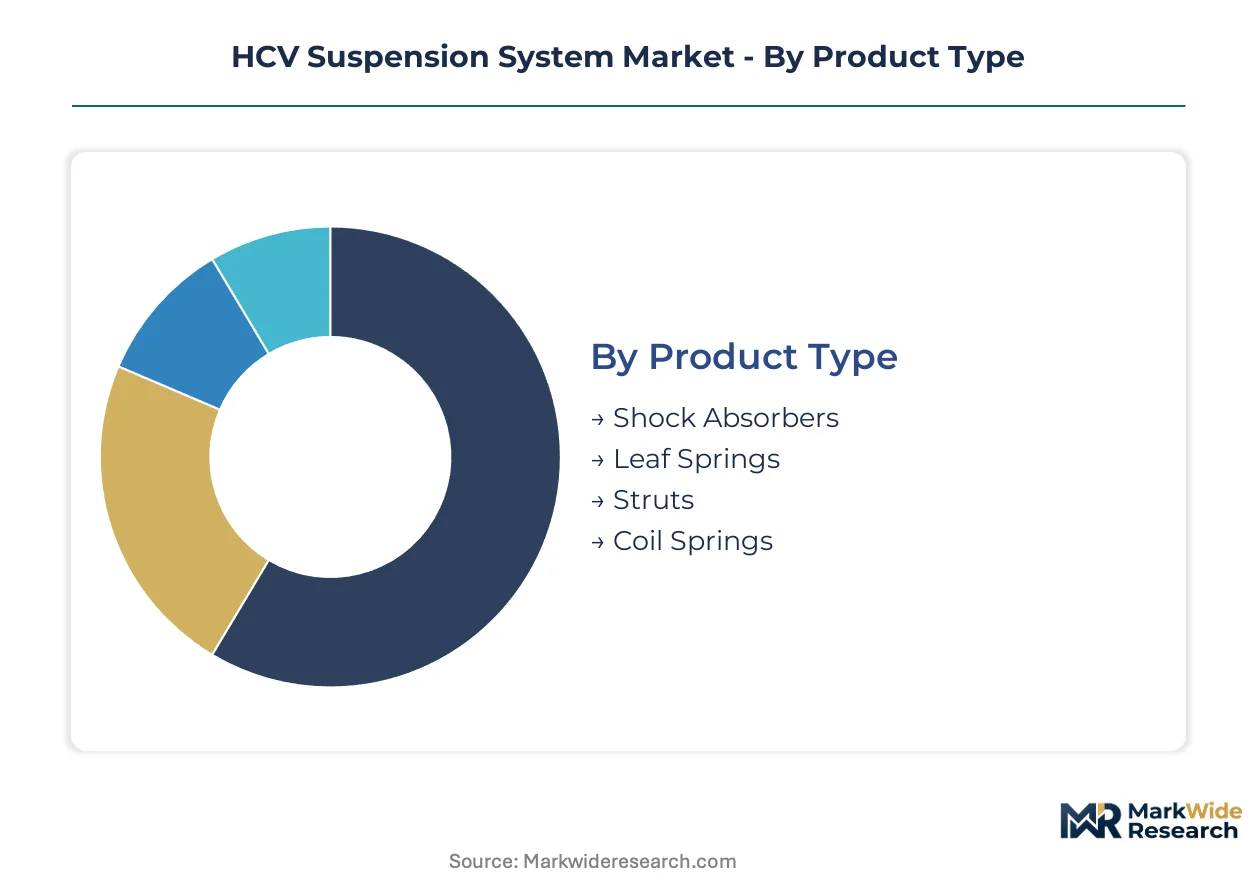
Segment boundaries in heavy commercial vehicle suspension systems map directly to replacement economics and technology refresh cycles. Understanding where procurement concentrates versus where systems age out fastest determines supplier resource allocation and channel strategy.
Product Type:
Shock absorbers and leaf springs turn over on accelerated cycles due to continuous load stress, while coil springs and struts persist longer in heavy-duty architectures.
- Shock Absorbers:Hydraulic and gas-charged dampers rated for continuous duty cycles absorb road-induced oscillations across axle assemblies. Mining fleets in Western Australia and oilfield service operators in Texas's Permian Basin consume these at 2.3x the rate of highway distribution vehicles due to terrain severity and payload density.
- Leaf Springs:Multi-leaf parabolic assemblies fabricated from alloy steel provide load-bearing capacity for rigid axle configurations. Indian and Chinese domestic truck manufacturers specify these for 16-25 tonne gross vehicle weight platforms where cost engineering outweighs ride quality optimization.
- Struts:MacPherson-derived heavy-duty variants integrate damping and structural functions for cab and chassis modules.
- Coil Springs:Helical steel or composite formulations occupy niche applications in independent front suspension architectures for premium highway tractors.
Leaf springs dominate installed base across emerging market production. Shock absorbers are where expansion concentrates as adaptive damping penetrates mid-duty segments.
Technology:
Cost tiers separate legacy hydraulic and pneumatic installations from electronic and adaptive systems commanding hardware-software bundled pricing.
- Hydraulic:Conventional twin-tube and mono-tube dampers with fixed orifice valving remain standard for price-sensitive fleet procurement. Brazilian and Mexican truck assemblers specify these for regional freight corridors where road quality permits simpler damping profiles.
- Pneumatic:Air spring systems with mechanical height control valves manage variable load conditions through pressurized rubber bellows. European long-haul operators under EU Green Deal F-Gas constraints are accelerating migration to sealed electronic architectures as fluorinated gas regulations tighten.
- Electronic:Solenoid-actuated damping valves enable discrete stiffness adjustment through body control modules.
- Adaptive:Continuously variable damping architectures utilizing magnetorheological or electrorheological fluids deliver real-time load optimization. North American refrigerated carriers and pharmaceutical freight operators specify these for cargo protection across temperature-sensitive Rhine-Alpine and I-95 corridors.
Hydraulic systems anchor volume production in cost-optimized markets. Adaptive architectures are climbing the fastest as fuel economy mandates elevate real-time load management from comfort feature to operational necessity.
End User:
Customer type determines warranty integration depth, with OEMs and fleet operators pursuing captive supply relationships while aftermarket channels fragment across independent distributors.
- OEMs:Truck and bus manufacturers specify suspension modules at platform development stage, integrating axle assemblies with chassis control systems. Scania, Daimler Truck, and Volvo Group procurement functions in Sweden, Germany, and Belgium negotiate multi-year supply agreements with embedded software update provisions.
- Aftermarket Providers:Independent service networks source replacement dampers, bushings, and air springs outside OEM captive channels. US Great Lakes region fleet maintenance operations increasingly bypass dealer networks for component-level procurement through specialized distributors.
- Distributors:Multi-brand parts wholesalers aggregate demand across fragmented service outlets.
- Fleet Operators:Large-scale freight and logistics companies with in-house maintenance capabilities negotiate direct supply contracts for high-volume replacement schedules.
OEMs dominate technology transition timing. Aftermarket providers are where margin expansion concentrates as fleet operators unbundle service from comprehensive maintenance contracts.
Installation Type:
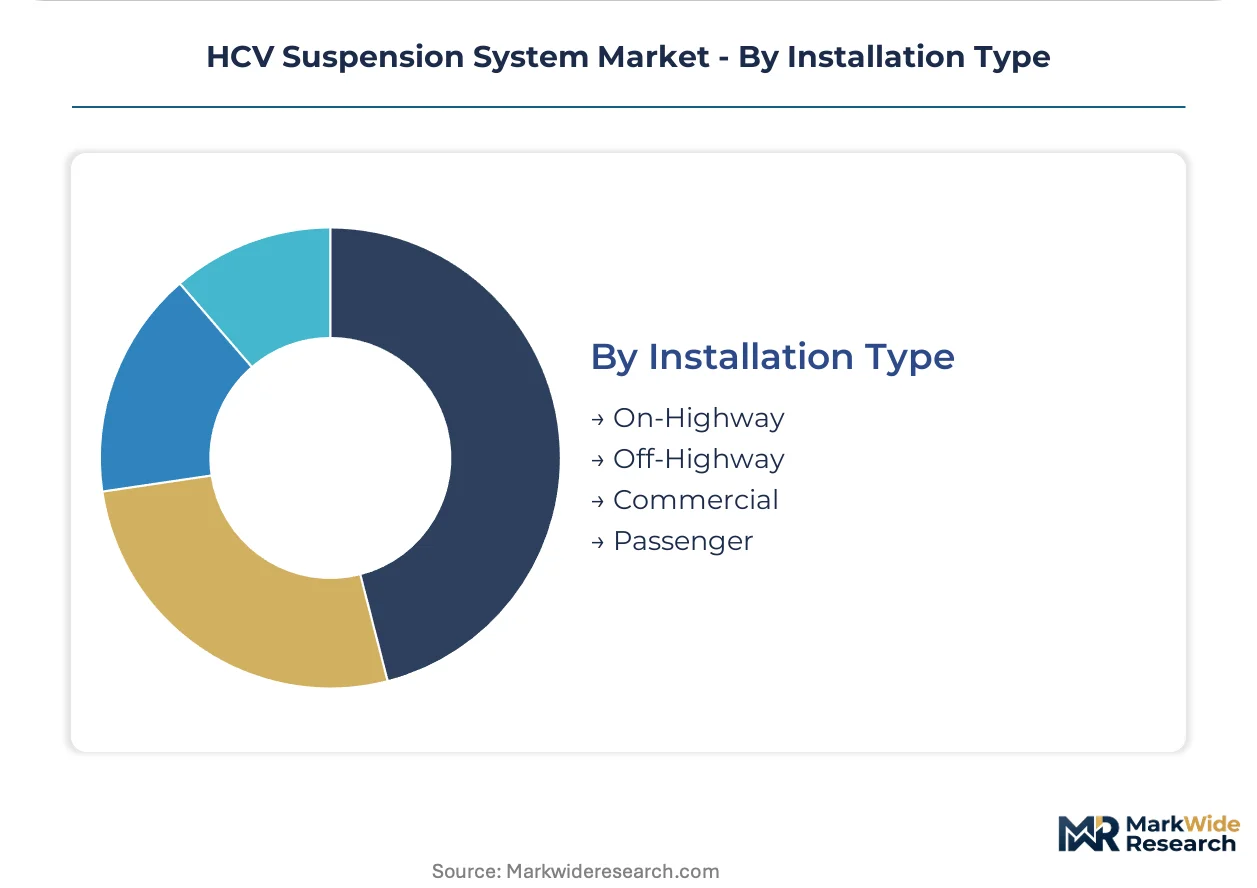
Application severity separates on-highway duty cycles from off-highway environments demanding reinforced sealing and corrosion resistance.
- On-Highway:Paved road applications emphasize fuel efficiency through lightweight materials and aerodynamic ride height management. German autobahn and US interstate corridor operators specify these configurations for maximum payload compliance within axle weight regulations.
- Off-Highway:Mining, construction, and agricultural deployments require reinforced axle housings and enhanced sealing against abrasive contamination. Siberian diamond extraction operations and Chilean copper pit haul routes demand specialized architectures unavailable in standard highway catalogs.
- Commercial:General freight and vocational truck classifications span distribution, refuse, and utility service applications.
- Passenger:Motorcoach and intercity bus configurations prioritize ride comfort through air suspension and adaptive damping combinations.
On-highway installations dominate unit volume. Off-highway configurations are where specification intensity concentrates as resource extraction automation demands fault-tolerant active systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement teams in Germany accept 15-20% hardware premiums for adaptive damping integration, while operators in India and Brazil prioritize leaf spring cost engineering over ride quality optimization.
United States
Long-haul refrigerated carriers along the I-95 corridor specify magnetorheological dampers for pharmaceutical freight protection. EPA Phase 3 greenhouse gas standards compress component weight targets for 2027 model-year compliance. Detroit and Chicago procurement clusters negotiate multi-year supply agreements with embedded software update provisions.
Germany
Integrated chassis module production concentrates around Stuttgart and Munich, creating single-source vulnerability for European OEMs. EU Green Deal F-Gas Regulation restrictions force air spring redesigns favoring electronic control modules. Mannheim-based fleet operators accelerate migration to sealed electronic architectures as fluorinated gas regulations tighten.
China
Domestic truck production scaling and highway freight corridor expansion concentrate OEM procurement in high-capacity suspension platforms. MIIT dual carbon goals and GB standards reshape supplier qualification requirements. Yangtze River Delta manufacturing clusters scale composite-reinforced air spring production for export-oriented capacity.
India
Domestic truck manufacturers specify leaf spring assemblies for 16-25 tonne gross vehicle weight platforms where cost engineering outweighs ride quality. BIS certification and PLI scheme for automotive components reshape supplier qualification requirements for export-oriented manufacturers. Tamil Nadu and Maharashtra production hubs capture incentive-linked capacity expansion for air spring and damper assemblies.
Brazil
Regional freight corridors with permissive road quality sustain demand for fixed orifice hydraulic dampers. ANVISA pharmaceutical transport regulations indirectly pressure cold-chain fleets toward adaptive suspension for cargo protection. São Paulo state assemblers specify simpler damping profiles for price-sensitive procurement.
HCV Suspension System Market Competitive Environment
Capability concentration sits with integrated chassis specialists; scale advantage sits with multi-brand component fabricators. The supplier base organizes into three tiers: Stuttgart-centered system integrators commanding OEM platform development, Asian volume manufacturers serving cost-optimized fleet replacement cycles, and regional aftermarket distributors fragmenting service revenue. Dominant competitive moves include captive software update provisioning and composite material substitution in air spring architectures.
Within the integrated chassis tier, ZF Friedrichshafen and Continental anchor European OEM supply relationships through multi-year platform agreements. Bosch exemplifies the diagnostic-linked service archetype, converting hardware installations into recurring calibration revenue. KYB Corporation and Tenneco occupy positions in the volume-manufacturing segment, supplying replacement dampers for unbundled fleet maintenance procurement.
| Leading Market Players |
|---|
| Continental |
| ZF Friedrichshafen |
| Bosch |
| Tenneco |
| HYUNDAI MOBIS |
| WABCO |
| KYB Corporation |
| Magna International |
| ContiTech |
| Others |
Value Chain & Pricing Dynamics
Rhine-Alpine corridor freight economics compress margin structures at both ends of the value chain, as Stuttgart-centered system integrators extract hardware premiums while Indian leaf spring fabricators compete on alloy steel input arbitrage. This tension between specification intensity and cost engineering shapes how procurement teams structure contracts across OEM and aftermarket channels.
Pricing Analysis
Long-term offtake agreements dominate OEM procurement, with multi-year platform contracts embedding software update provisions and volume-tiered rebates that compress spot-market exposure. Three-tier pricing structure across premium adaptive systems, standard pneumatic architectures, and economy hydraulic units reflects certification grade differentiation and after-sales service bundling. Cost compression in the economy tier is intensifying because Brazilian and Mexican assemblers prioritize fixed-orifice dampers for regional corridors. Fleet operators in India and China exhibit highest price sensitivity, while German autobahn carriers accept hardware premiums for real-time load optimization.
Supply Chain Analysis
Natural rubber plantations in Thailand and Indonesia, alloy steel production in China and Germany, and aramid fiber manufacturing in the United States constitute the upstream feedstock base for suspension component fabrication. The industry draws from fluorinated gas suppliers facing EU F-Gas Regulation constraints, composite reinforcement specialists, and electronic control module foundries. Single-source vulnerability clusters around Stuttgart and Munich for integrated chassis modules. Distribution runs through captive OEM service networks, independent aftermarket distributors, and direct fleet procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as fleet operators unbundle suspension service from comprehensive maintenance contracts, creating niche entry points for specialized component suppliers and predictive maintenance platforms.
For Market Incumbents: Harden software update provisioning as a recurring revenue anchor against hardware commoditization pressures from Asian volume manufacturers. Deepen captive supply relationships with European OEMs through ISO 26262 certification investments that extend development timelines and raise barriers for challengers. For New Entrants and Emerging Players: Brazil's regional freight corridors present underpenetrated white space for adaptive damping retrofits targeting ANVISA-regulated pharmaceutical cold-chain operators. India's PLI scheme qualification offers incentive-linked capacity expansion for air spring and damper assemblies serving export markets. Partner with telematics providers to bundle condition-based replacement scheduling as a differentiated service layer. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized automotive suspension divisions lacking software-defined vehicle integration capabilities. Five-to-ten year viability hinges on adaptive technology penetration rates in mid-duty segments. Monitor EPA Phase 3 compliance timelines and EU F-Gas Regulation enforcement intensity as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Damping Platform Standardization | Enables ZF Friedrichshafen and Continental to capture recurring calibration revenue across multiple OEM truck platforms. |
| Composite Air Spring Manufacturing Scale-Up | Allows aramid fiber substitution in bellows construction to meet EPA Phase 3 mass reduction mandates without degrading load ratings. |
| Predictive Maintenance Software Integration | Fuses IoT sensor networks with suspension telemetry to create condition-based replacement scheduling revenue streams. |
| India PLI Scheme Capacity Expansion | Positions Tamil Nadu and Maharashtra hubs to capture export-oriented incentive-linked production for global aftermarket channels. |
| Autonomous Truck Suspension Certification | Develops fault-tolerant active systems for self-driving freight platforms requiring emergency maneuvering without driver intervention. |
Study Parameters
Operator-level perspectives from fleet maintenance directors, OEM platform engineers, aftermarket distributor procurement heads, and Tier 1 supplier account managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, customs and trade flow records, and regulatory filings from EPA and EU institutions. Bottom-up demand modeling across product type, technology tier, end-user category, and installation severity triangulated against top-down market sizing from supplier revenue disclosures.
Scenario-bracketing framed the analytical approach across the analysis window, with discrete modeling of hydraulic, pneumatic, electronic, and adaptive technology penetration trajectories. Segmentation dimensions included product architecture, control system sophistication, customer channel, and application severity. CAGRs derived from replacement cycle analysis, fleet electrification timing, and regulatory compliance deadlines. Forecast inputs incorporated natural rubber price volatility indices and alloy steel capacity utilization rates from Chinese and German production hubs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed component conglomerates or rapid battery-electric truck adoption would shift outcomes beyond modeled ranges. Quarterly review of EPA enforcement actions, EU F-Gas Regulation implementation progress, and Indian PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
Collapsible Jerry Can Market
Vehicle Components
Rear Axle Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
Tail Lifts Market
Vehicle Components
Rail Components Market
Vehicle Components
Saudi Arabia Refrigerated Trailer Market
Vehicle Components
High Efficiency Rolling Bearings Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Spark Plug Accessories Market
Vehicle Components
Bicycle Bottom Bracket Market
Vehicle Components
Bicycle Components Aftermarket Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Engine Valve Market
Vehicle Components
Automotive Pyrofuse Market