
 Aircraft and Marine Turbochargers Market | 2026-2036
Aircraft and Marine Turbochargers Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft and Marine Turbochargers Market Analysis
Modular turbocharger cartridge replacement is rebalancing aftermarket purchasing decisions away from full-unit replacement. General Electric leverages its aviation OEM relationships to sustain captive demand for integrated engine-turbo systems. BorgWarner anchors its marine position through specialized saltwater corrosion-resistant product lines. Kawasaki Heavy Industries differentiates via in-house production of precision turbine castings that reduce external supplier dependency.
Aircraft and marine turbochargers are forced-induction devices that compress intake air to increase engine power density, typically operating at turbine inlet temperatures exceeding 650°C and rotor speeds above 100,000 RPM in aviation applications. Their primary purpose is to restore sea-level power output at altitude or to boost brake mean effective pressure in marine diesels without proportional displacement growth. Centrifugal designs dominate aviation due to compact diameter constraints in nacelle installations, while axial configurations retain share in large two-stroke marine engines where flow capacity governs. Electric turbocharging represents the fastest-growing technology segment as ship operators seek waste-heat recovery compliance pathways under tightening NOx limits.
The US EPA, the International Maritime Organization, and the EU F-Gas Regulation collectively shape turbocharger demand through emission thresholds that effectively mandate boosted combustion architectures. FAA airworthiness certification requirements for turbine engine components create additional barriers that favor established suppliers with prior type certificate experience. Stakeholders must monitor how emerging sustainable aviation fuel compatibility standards alter turbocharger thermal management specifications.
Market Dynamics
Emission compliance deadlines are compressing engine redesign cycles across both aviation and maritime propulsion systems, forcing turbocharger architectures to absorb thermal loads and pressure ratios beyond legacy specifications.
Growth Catalysts
- EPA Tier 4 and IMO Tier III mandates:These emission thresholds require boosted combustion architectures in marine diesels, expanding addressable unit demand for high-pressure turbocharger systems.
- Naval defense procurement programs:South Korea, Japan, and Australia are expanding orders for marine propulsion systems with integrated turbocharging for surface combatant and auxiliary vessel fleets.
- Electric turbocharging technology:Waste-heat recovery compliance pathways under tightening NOx limits are accelerating ship operator adoption of hybrid-electric turbocharger configurations.
Market Restraints
- Inconel and titanium input cost volatility:Superalloy price swings compress margin stability for precision turbine casting operations.
- Supply concentration in South Korean shipbuilding:Ulsan and Geoje clusters create geographic dependency risk for marine turbocharger demand aggregation.
- FAA airworthiness certification barriers:Prior type certificate experience requirements favor established suppliers and constrain new entrant qualification timelines.
Strategic Opportunities
- Modular cartridge replacement models:Aftermarket purchasing is rebalancing toward component-level service rather than full-unit replacement, opening recurring revenue streams.
- Sustainable aviation fuel compatibility standards:Emerging thermal management specifications for SAF-operated turbines create upgrade cycles for existing installed base.
- EU F-Gas Regulation compliance services:Refrigerant containment and leak detection integration with turbocharger cooling systems offers technical service expansion.
Industry Challenges
- Precision casting skill scarcity:In-house turbine blade production requires metallurgical expertise that competes with aerospace and power generation sectors for limited talent pools.
- Rotor dynamics certification complexity:High-speed balancing and vibration analysis for 100,000+ RPM aviation applications extend validation timelines.
- Saltwater corrosion specification divergence:Marine product lines require specialized coatings and materials that fragment production runs and complicate inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft and Marine Turbochargers Market |
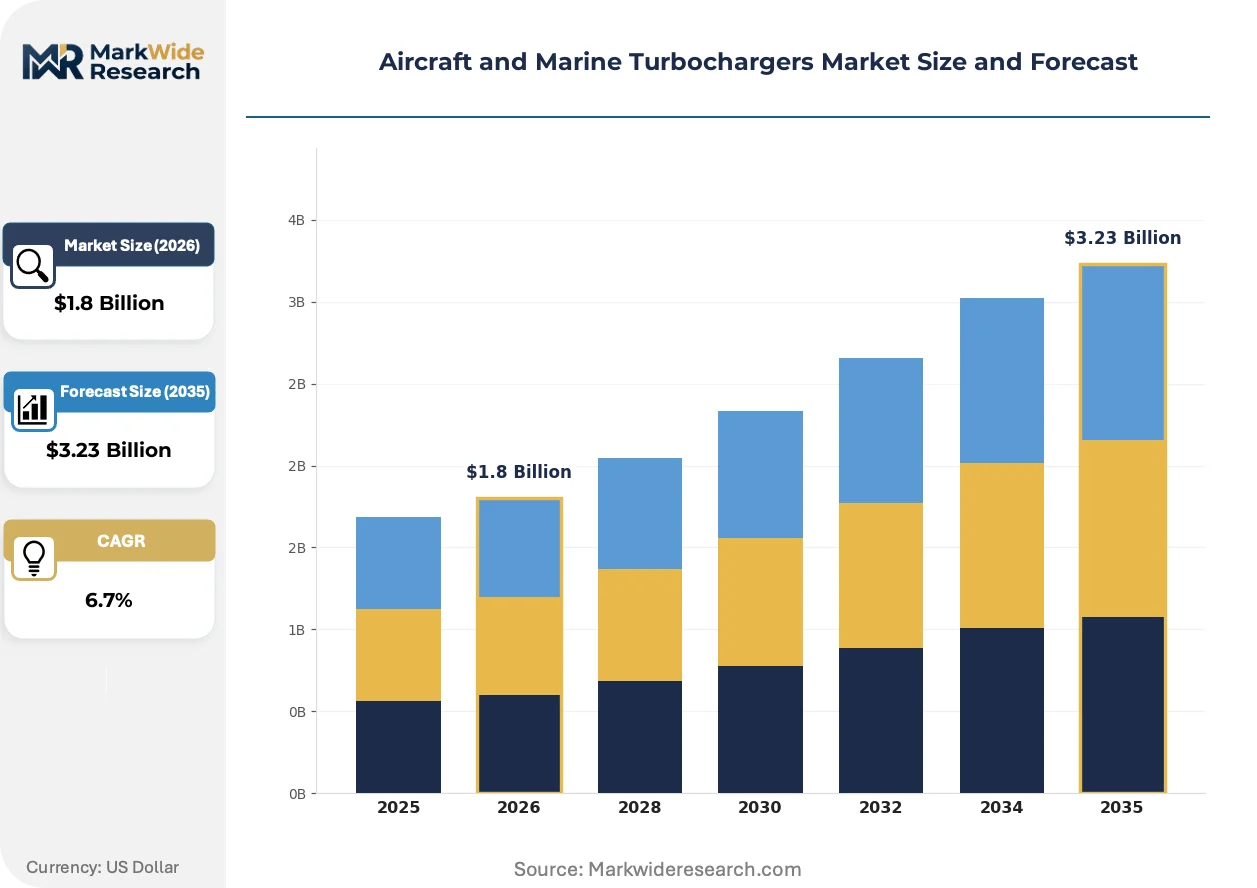
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial, Centrifugal, Twin-scroll, Variable Geometry Application: Aviation Engines, Marine Engines, Industrial Equipment, Power Generation Technology: Sequential Turbocharging, Electric Turbocharging, Wastegate Turbocharging, Hybrid Turbocharging End User: Aerospace OEMs, Marine Vessel Manufacturers, Power Plant Operators, Engine Rebuilders |
| Companies Covered | General Electric, BorgWarner, ABB, Kawasaki Heavy Industries, MAN Energy Solutions, Mitsubishi Heavy Industries, Cummins, Rolls-Royce, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft and Marine Turbochargers Market Emerging Trajectories
Technology trajectories in this market center on thermal efficiency extraction, regulatory compliance automation, and service model unbundling that separates hardware ownership from performance outcomes.
Electric turbocharging is absorbing waste-heat recovery functions previously handled by standalone organic Rankine cycle systems. Container ship operators deploying these configurations achieve IMO compliance without exhaust aftertreatment hardware. The technology is absorbing capital allocation that would otherwise flow to scrubber installations or LNG fuel conversion.
The EU F-Gas Regulation is tightening refrigerant containment requirements for vessel cooling circuits. Turbocharger intercooler systems must now integrate leak detection and automated isolation protocols. Marine engine integrators in Germany and the Netherlands are redesigning auxiliary system interfaces to accommodate these monitoring layers.
Aftermarket service unbundling is fragmenting traditional OEM-captive relationships. Third-party maintenance providers now offer cartridge exchange programs with performance guarantees independent of original equipment procurement. This pattern is most visible in Southeast Asian port hubs where vessel operators prioritize turnaround speed over brand continuity.
Aircraft and Marine Turbochargers Market Segmentation
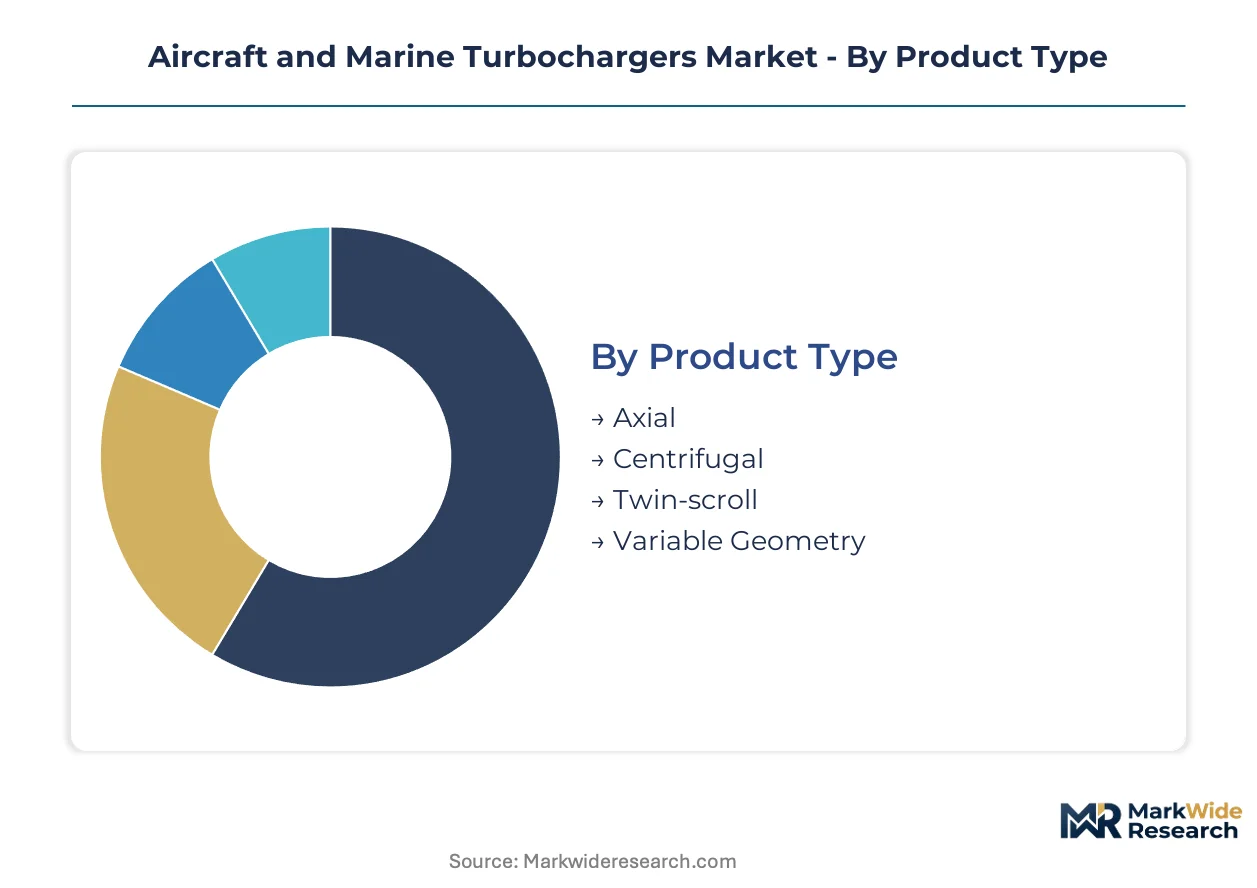
Turbocharger segmentation reveals how design specifications map to divergent thermal and aerodynamic requirements across aviation and marine propulsion. Product architecture choices directly determine rotor speed tolerance, pressure ratio ceilings, and compliance pathways under emission mandates.
Product Type:
Compressor wheel geometry governs flow efficiency, surge margin, and packaging constraints in nacelle or engine room installations.
- Axial:Multi-stage blade rows achieve high mass flow rates in large two-stroke marine diesels. South Korean shipbuilders at Ulsan specify axial configurations for container vessel main engines subject to IMO Tier III NOx limits.
- Centrifugal:Single-stage impeller designs dominate aviation where diameter constraints in wing-mounted nacelles limit radial envelope. FAA-certified units operate above 100,000 RPM with Inconel turbine wheels.
- Twin-scroll:Divided turbine housings separate exhaust pulses to reduce turbo lag in medium-speed marine propulsion.
- Variable Geometry:Articulated nozzle rings optimize turbine swallowing capacity across engine load ranges in naval auxiliary vessels.
Centrifugal configurations lead on scale; variable geometry leads on momentum.
Application:
Operating environment dictates corrosion protection, altitude compensation, and duty cycle specifications.
- Aviation Engines:Sea-level power restoration at altitude requires pressure ratios exceeding 4:1 with titanium compressor wheels. FAA airworthiness certification creates supplier concentration around incumbent type certificate holders.
- Marine Engines:Saltwater corrosion-resistant coatings and duplex stainless steel housings address constant humidity exposure. Japanese and Australian naval procurement programs specify integrated turbocharger-marine diesel packages.
- Industrial Equipment:Stationary power units favor robust bearing systems over weight optimization.
- Power Generation:Continuous-duty specifications prioritize thermal efficiency over transient response in offshore platform installations.
Marine engines lead on scale; aviation engines lead on specification intensity.
Technology:
System architecture determines waste heat recovery potential and electric integration depth.
- Sequential Turbocharging:Staged small-large compressor combinations broaden operating maps for variable-speed marine diesels.
- Electric Turbocharging:Motor-generator integration on the turbo shaft enables waste-heat recovery without standalone Rankine cycle hardware. Container ship operators achieve IMO compliance through this pathway.
- Wastegate Turbocharging:Bypass valve control limits boost pressure in cost-sensitive auxiliary engines.
- Hybrid Turbocharging:Combines mechanical and electric assist for load-following power generation applications.
Wastegate systems lead on installed base; electric turbocharging leads on adoption velocity.
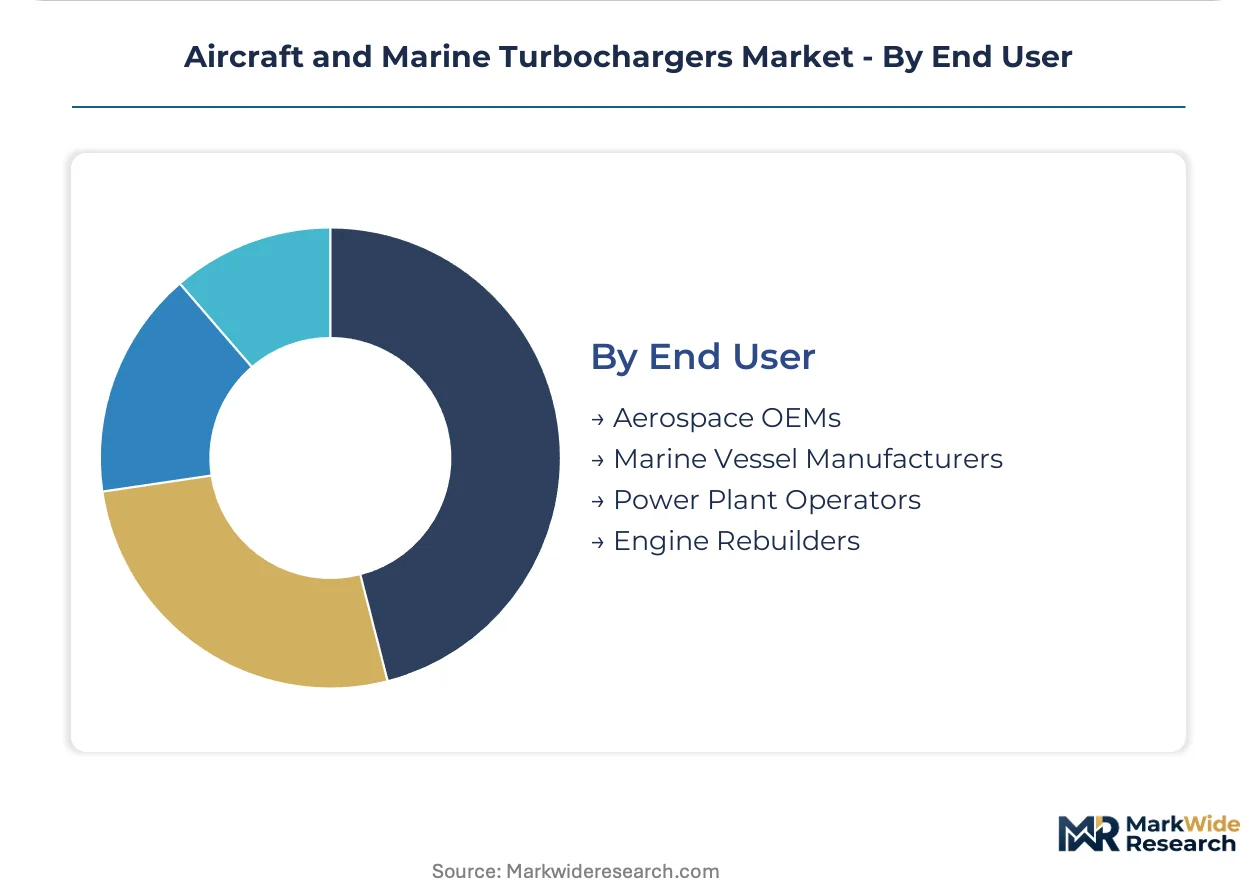
End User:
Procurement authority and technical specification control vary sharply across buyer categories.
- Aerospace OEMs:Integrated engine-turbo system design locks in captive supplier relationships through airframe-engine certification bundles.
- Marine Vessel Manufacturers:South Korean yards at Geoje consolidate demand for high-pressure turbocharger systems in LNG carrier newbuilds.
- Power Plant Operators:Long-term service agreements prioritize availability guarantees over initial capital cost.
- Engine Rebuilders:Modular cartridge replacement programs rebalance aftermarket purchasing toward component-level service rather than full-unit procurement.
Marine vessel manufacturers lead on volume concentration; engine rebuilders lead on service model transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aircraft and marine turbocharger industry traces its industrial lineage to early 20th-century Swiss and German precision engineering clusters, where centrifugal compressor technology first scaled for aviation applications before migrating to maritime propulsion systems.
United States
Naval defense procurement programs at Newport News Shipbuilding and General Dynamics Electric Boat drive demand for integrated marine propulsion systems. The FAA enforces airworthiness certification requirements that favor established suppliers with prior type certificate experience. Connecticut and Virginia host concentrated engineering capabilities for high-pressure turbocharger development.
Germany
Marine engine integrators in Hamburg and Augsburg redesign auxiliary system interfaces to accommodate EU F-Gas Regulation leak detection protocols. The country's national maritime regulator enforces refrigerant containment standards for vessel cooling circuits. German shipyards specify turbocharger-marine diesel packages for container vessel newbuilds.
Japan
Naval surface combatant programs at Mitsubishi Heavy Industries and Kawasaki Heavy Industries expand orders for integrated propulsion systems. METI coordinates precision casting skill development for turbine blade production. Nagoya and Kobe industrial clusters concentrate in-house metallurgical expertise for superalloy component manufacturing.
South Korea
Shipbuilders at Ulsan and Geoje consolidate demand for high-pressure turbocharger systems in LNG carrier and container vessel newbuilds. The Korean Register of Shipping enforces IMO Tier III compliance verification for marine diesel installations. Daewoo Shipbuilding and Hyundai Heavy Industries anchor procurement aggregation for axial and centrifugal configurations.
China
State-owned shipyards at Shanghai and Dalian scale two-stroke marine engine production requiring axial turbocharger configurations. The Ministry of Industry and Information Technology coordinates emission compliance timelines under domestic maritime regulations. Yangtze River Delta manufacturing clusters compete for precision turbine casting contracts.
Aircraft and Marine Turbochargers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and metallurgical capability dimensions. The vendor base organizes into three tiers: integrated engine-turbo system designers, specialized marine corrosion-resistant product specialists, and precision casting in-house producers. Two dominant competitive moves define current positioning: backward integration into superalloy supply chains and geographic expansion toward South Korean shipbuilding clusters.
Within the integrated systems tier, General Electric exemplifies aviation OEM relationship leverage for captive engine-turbo demand. BorgWarner occupies a position among corrosion-resistant marine specialists through saltwater-hardened product lines. Kawasaki Heavy Industries anchors the precision casting archetype via in-house turbine wheel production that reduces external supplier dependency.
| Leading Market Players |
|---|
| General Electric |
| BorgWarner |
| ABB |
| Kawasaki Heavy Industries |
| MAN Energy Solutions |
| Mitsubishi Heavy Industries |
| Cummins |
| Rolls-Royce |
| Honeywell International |
| Others |
Supply Flow & Price Mechanics
Electric turbocharging motor-generator integration is simultaneously compressing manufacturing cost curves and concentrating procurement authority among South Korean shipbuilders with sufficient scale to negotiate system-level contracts. This technology shift rebalances supplier margins toward aftermarket service components while fragmenting upfront hardware pricing across certification tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aviation units with Inconel turbine wheels from IMO-compliant marine systems with corrosion-resistant coatings and non-certified auxiliary engine configurations. Price differentiation hinges on certification grade and volume scale, with naval procurement programs commanding fixed-price long-term contracts. Cost compression in the economy tier is intensifying because Chinese state-owned shipyards are scaling two-stroke production with axial configurations. Engine rebuilders exhibit highest price sensitivity; aerospace OEMs locked into type certificate relationships show lowest.
Supply Chain Analysis
South Korean domestic-content mandates for naval propulsion systems are reshaping sourcing patterns, requiring local assembly of turbocharger-marine diesel packages for surface combatant programs. Precision turbine casting draws from Japan, Germany, and the United States for superalloy metallurgical expertise. Inconel and titanium input cost volatility creates commodity price exposure for precision casting operations. Distribution runs through marine engine integrators in Hamburg, Nagoya, and Ulsan who bundle turbocharger specification into vessel newbuild contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
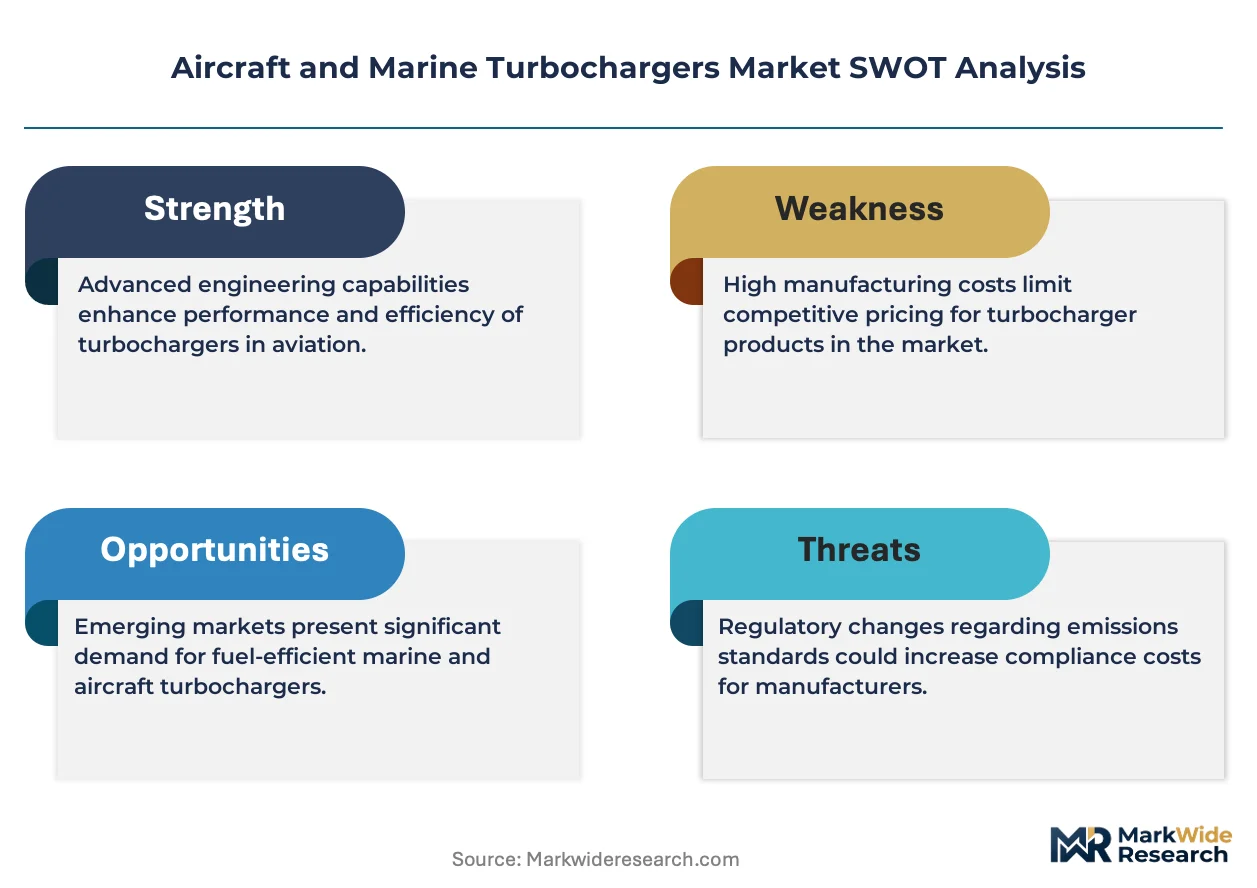
This market reads as a late-cycle quality story where EPA Tier 4 and IMO Tier III emission deadlines are forcing engine redesigns toward premium thermal management specifications that command sustained margin premiums.
For Market Incumbents: Deploy backward integration into superalloy supply chains to defend margin stability against Inconel price volatility threatening precision turbine casting operations. Anchor captive demand through integrated engine-turbo system design that locks airframe-engine certification bundles against emerging modular cartridge replacement providers. Expand engineering capabilities in Connecticut and Virginia to maintain proximity to Newport News Shipbuilding and Electric Boat naval procurement programs. For New Entrants and Emerging Players: Digital-channel aftermarket platforms offering cartridge exchange programs with performance guarantees represent the most penetrable entry vector, particularly in Southeast Asian port hubs where vessel operators prioritize turnaround speed over brand continuity. Target engine rebuilders with component-level service models that bypass FAA airworthiness certification barriers constraining full-system qualification timelines. White-space exists in EU F-Gas Regulation compliance services for refrigerant leak detection integration with turbocharger cooling circuits. For Investors and Strategic Acquirers: Valuations sit cheapest among precision casting specialists with in-house turbine blade production capability that reduces external supplier dependency in a talent-constrained environment. Long-term viability favors suppliers with demonstrated type certificate experience and established relationships with General Electric, BorgWarner, or Kawasaki Heavy Industries. Watch electric turbocharging adoption velocity among container ship operators as the signal for when waste-heat recovery compliance pathways displace scrubber and LNG conversion capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Supply | In-house Inconel sourcing insulates margin stability against raw material price swings. |
| Modular Cartridge Replacement Programs | Component-level service models rebalance aftermarket revenue toward recurring streams. |
| Electric Turbocharging Capacity Expansion | Waste-heat recovery systems capture IMO compliance spending from scrubber alternatives. |
| Naval Defense Procurement Certification | FAA and Korean Register type certificates lock in long-term surface combatant demand. |
| EU F-Gas Compliance Service Integration | Refrigerant containment protocols open technical service expansion in German and Dutch ports. |
Methodological Framework
Multiple input streams — primary interviews with marine propulsion engineers, aviation certification specialists, and shipyard procurement directors; secondary validation through EPA regulatory filings, IMO Marine Environment Protection Committee protocols, and Korean Register of Shipping compliance databases; customs and trade data from precision turbine casting operations — were reconciled through bottom-up unit demand modeling and top-down market size triangulation.
Data-stream reconciliation applied across product type, application, technology, and end-user segmentation dimensions over the projection horizon. CAGRs were derived from installed base turnover analysis and newbuild orderbook trajectories, incorporating naval defense procurement cycle timing and emission compliance deadline phasing as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for electric turbocharging penetration would alter the outlook if organic Rankine cycle systems achieve cost parity or LNG fuel conversion economics shift. Forecasts reflect assumptions regarding superalloy supply stability, precision casting labor availability, and regulatory enforcement consistency across flag states. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
4x4 Vehicle Parts and Accessories Market
Vehicle Components
Vehicle Retarder Market
Vehicle Components
Snowplows Market
Vehicle Components
Self Loading Trailer Market
Vehicle Components
Wheel Spindle Market
Vehicle Components
Railroad Equipment Manufacturing Market
Vehicle Components
Limited Slip Differential (LSD) Market
Vehicle Components
Hydrostatic Transmission Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Injector Deposit-Resistant Fuel Injection Component Platforms Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market