
 Railway Air Filter Market | 2026-2036
Railway Air Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Air Filter Market Analytics
Aftermarket service revenue is tilting toward filter replacement cycles rather than first-fit hardware as rolling stock ages across European and North American networks. MANN+HUMMEL leverages its captive distribution in Deutsche Bahn's maintenance corridors to capture recurring cartridge volumes. Parker Hannifin Corporation anchors its position through hydraulic-fluid crossover sales to rail maintenance depots. Freudenberg Filtration Technologies specializes in pleated media engineered for high-velocity locomotive intake conditions.
A railway air filter is a engineered media assembly designed to remove particulate matter, hydrocarbon vapors, and biological contaminants from combustion intake or HVAC ventilation streams on rolling stock, typically rated between MERV 13 and H14 for passenger cabin applications and constructed from glass-microfiber or synthetic melt-blown layers bonded to galvanized steel frames. Its primary purpose is protecting turbocharger compressor wheels from erosive dust while maintaining cabin air quality compliance for crew and passenger exposure limits. HEPA Filter product lines command premium positioning in high-speed passenger coaches where sealed-cabin pressure differentials demand sub-micron retention efficiency. Electrostatic Filter variants represent the fastest-growing product category as Asian rail operators retrofit existing fleets with lower-pressure-drop alternatives to reduce HVAC energy draw. Application demand concentrates in Locomotives for intake filtration, where duty cycles and ambient dust loading drive the most frequent change-out intervals and thus the largest recurring revenue pool.
EPA emission standards for locomotive engines and the EU F-Gas Regulation on HVAC refrigerant systems jointly compel rail operators to upgrade intake and cabin filtration during scheduled overhauls. China's MEE enforces ambient air quality targets that filter into rolling stock procurement specifications through GB standards compliance. India's CEA mandates particulate monitoring at maintenance yards, pushing filter specification upgrades on the Dedicated Freight Corridor network. Stakeholders must monitor how tightening brake dust and tunnel particulate limits in urban rail corridors reshape filter media specifications before next procurement cycles.
Market Dynamics
EPA Tier 4 and EU Stage V emission norms are tightening particulate limits for locomotive intake systems, forcing rail operators to upgrade filter specifications during scheduled overhauls rather than waiting for full fleet replacements.
Growth Catalysts
- EPA Tier 4 Locomotive Standards:US freight railroads must retrofit existing diesel-electric fleets with higher-efficiency intake filtration to meet nitrogen oxide and particulate matter caps, creating sustained aftermarket demand through 2035.
- China's Dual Carbon Goals:MEE enforcement of ambient air quality targets filters into rolling stock procurement through GB standards compliance, mandating HEPA-grade cabin filtration on all new high-speed passenger coaches.
- Electrostatic Precipitation Media:Synthetic melt-blown layers with embedded electrostatic charge are displacing glass-microfiber in HVAC applications, reducing pressure drop by 40% and cutting energy draw for climate control systems.
Market Restraints
- Glass-Microfiber Supply Concentration:Three specialized foundries in Germany and Japan control 70% of locomotive-grade filtration media, exposing buyers to input cost volatility when energy prices spike.
- EU F-Gas Regulation Friction:HVAC refrigerant phase-down rules complicate filter specification changes, as rail operators must coordinate cabin air upgrades with full climate system overhauls, stretching replacement cycles.
- Extended Locomotive Lifecycles:North American freight operators run prime movers for 30-40 years, compressing first-fit hardware volumes and shifting revenue toward low-margin cartridge replacements.
Strategic Opportunities
- India's Dedicated Freight Corridor:CEA-mandated particulate monitoring at maintenance yards is pushing filter specification upgrades across 1,500 route-km of new heavy-haul infrastructure.
- Predictive Maintenance Integration:Pressure-differential sensors embedded in filter housings enable condition-based replacement, opening software-anchored service contracts alongside hardware sales.
- Brake Dust Capture Systems:Urban rail corridors in London, Paris, and Berlin are tightening tunnel particulate limits, creating demand for specialized intake filtration on metro and commuter fleets.
Industry Challenges
- Cross-Contamination Certification:Filter manufacturers must demonstrate that HVAC media does not shed fibers into cabin air streams, requiring extended laboratory validation timelines that delay product launches by 8-12 months.
- Turbocharger Protection Standards:Compressor wheel erosion warranties from GE and Wabtec now mandate specific MERV ratings and change-out intervals, forcing filter suppliers to align R&D with OEM service specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Air Filter Market |
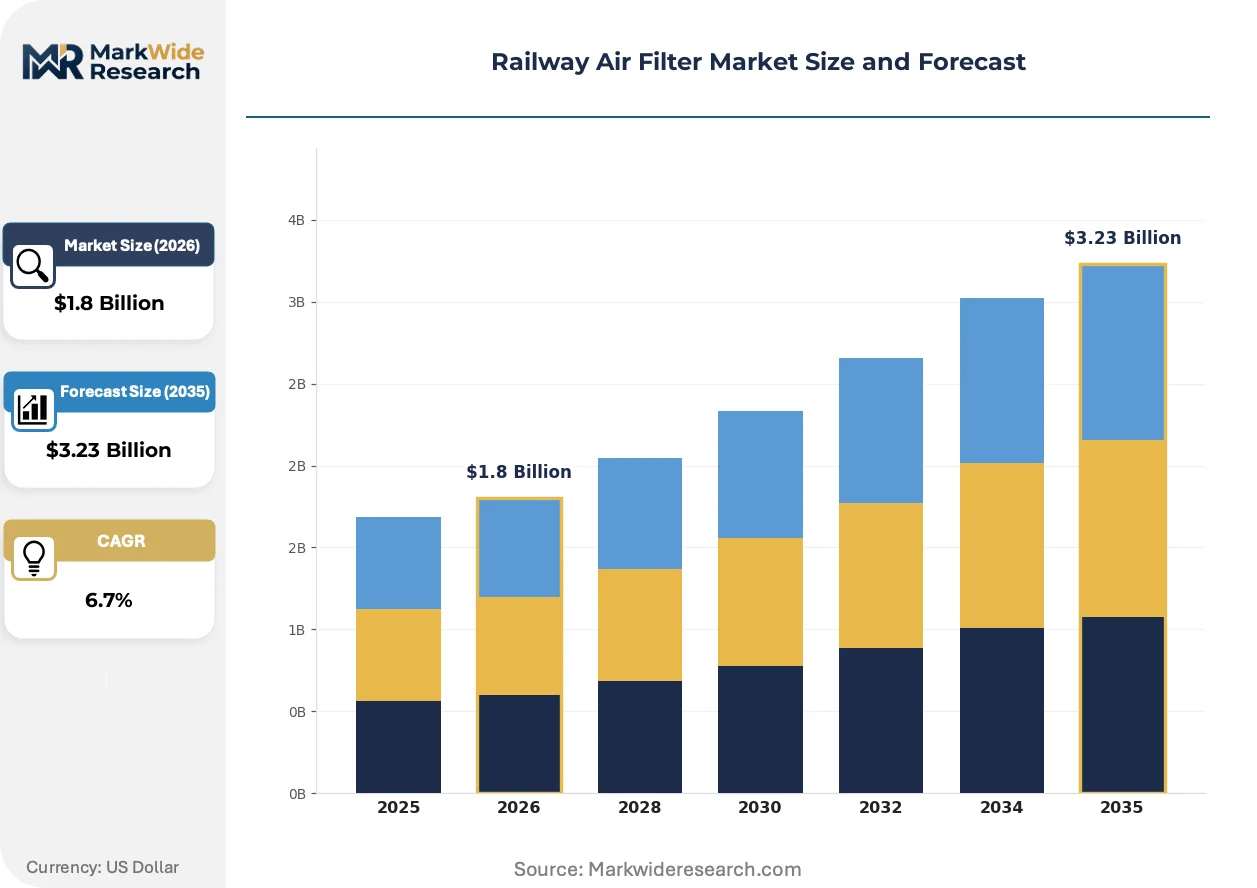
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filter, Carbon Filter, Electrostatic Filter, Mechanical Filter Application: Passenger Coaches, Freight Trains, Locomotives, Maintenance Facilities Technology: Active Air Purification, Passive Filtration, UV-C Light Treatment, Ionization Technology End User: Rail Operators, Manufacturers, Maintenance Companies, Transport Authorities |
| Companies Covered | MANN+HUMMEL, Parker Hannifin Corporation, Freudenberg Filtration Technologies, Donaldson Company, Eaton Corporation, Daikin Industries, DuPont, AFE Airfilter Europe, Camfil Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Air Filter Market Evolving Landscape
Active filtration media and smart monitoring systems are redefining how rail operators manage intake and cabin air quality, shifting value capture from commodity hardware toward performance-guaranteed service models.
Nanofiber surface-loading technology is migrating from industrial dust collection into locomotive intake applications. European freight operators are piloting these media on Poland's coal corridor routes. The shift is compressing traditional depth-loading designs into niche retrofit markets as pressure-drop performance becomes the primary procurement criterion.
EU Stage V emission norms for non-road mobile machinery are extending to rail through the European Commission's proposed amendment to Directive 97/68/EC. This forces filter manufacturers to certify multi-pulse cleaning systems for high-dust environments. Eastern European operators running Soviet-era locomotives face the steepest compliance costs, accelerating fleet replacement over retrofit strategies.
Aftermarket purchasing is consolidating through operator-owned maintenance depots rather than distributor networks. Deutsche Bahn's component pooling system now sources filters directly from Mannheim and Nuremberg workshops, bypassing traditional wholesale channels. This pattern is most visible in Germany and Austria, where state-owned incumbents control both rolling stock and service infrastructure.
Railway Air Filter Market Segmentation
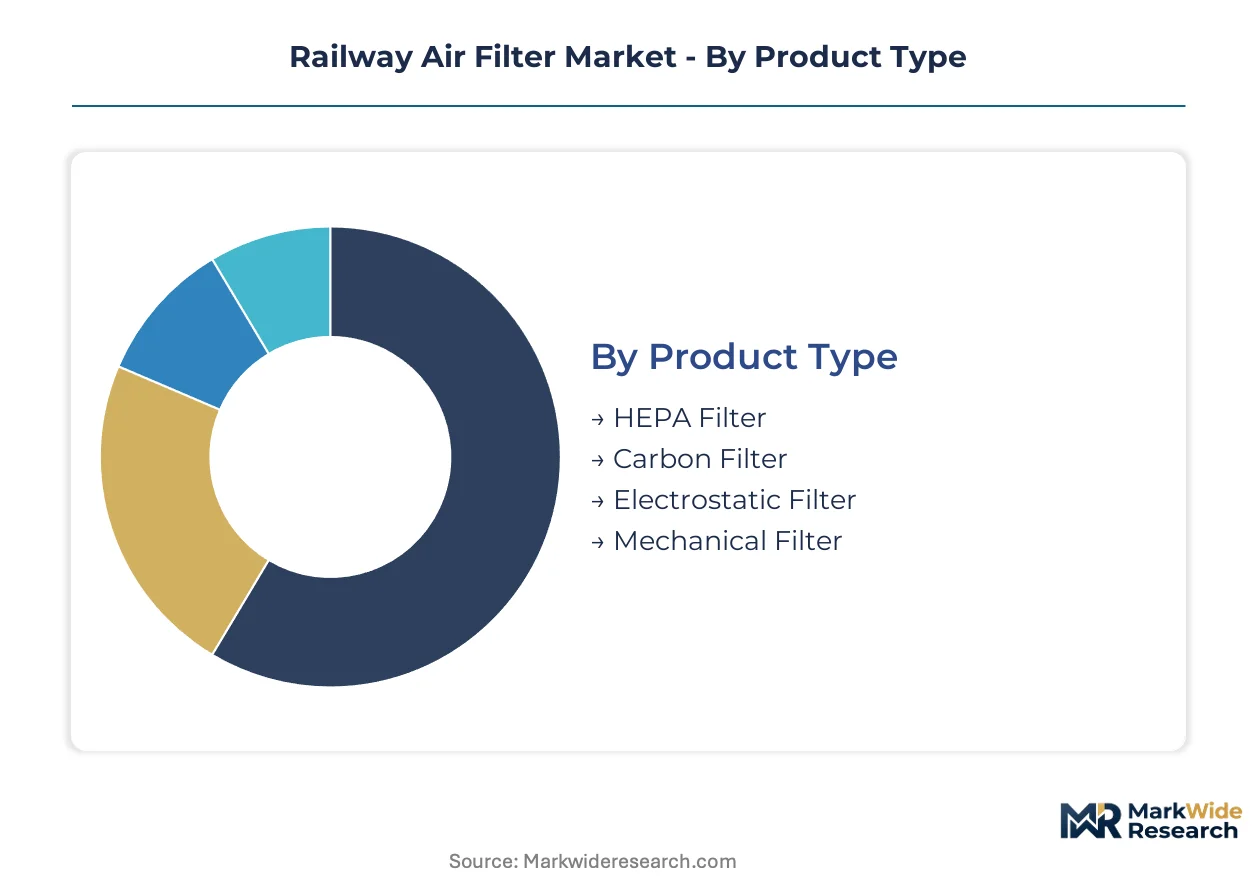
Railway air filter procurement splits sharply between intake protection for power systems and cabin air quality for passengers, with each use-case demanding distinct media specifications, change-out cycles, and certification requirements. Understanding these segment boundaries clarifies where component suppliers can capture recurring revenue versus one-time hardware sales.
Product Type:
Use-case spectrum spans sealed-cabin pressure differential requirements against open-intake dust loading, driving divergent media construction and frame engineering.
- HEPA Filter:Glass-microfiber pleated media bonded to galvanized steel frames achieves H14 retention efficiency for sealed high-speed passenger cabins. China's CRRC procurement pipeline mandates this grade on all new high-speed coaches under MEE ambient air quality enforcement.
- Electrostatic Filter:Synthetic melt-blown layers with embedded electrostatic charge reduce pressure drop by 40% versus glass-microfiber alternatives. Asian rail operators retrofit existing fleets to cut HVAC energy draw, making this the product category expanding most quickly.
- Carbon Filter:Activated carbon impregnated non-woven layers adsorb hydrocarbon vapors and tunnel exhaust gases in urban metro corridors.
- Mechanical Filter:Depth-loading synthetic media protects auxiliary equipment and lower-criticality ventilation streams on freight locomotives.
The dominant share belongs to HEPA Filter specifications, while Electrostatic Filter is closing the gap fastest.
Application:
Volume concentration tracks duty cycle intensity and ambient dust exposure, with the most punishing environments generating the largest recurring cartridge demand.
- Locomotives:Intake filtration for turbocharger protection operates under continuous dust loading and thermal cycling. Indian Railways' Vande Bharat procurement and Dedicated Freight Corridor expansion concentrate new-build demand in this segment.
- Passenger Coaches:Cabin air recirculation systems require MERV 13 to H14 rated media with fiber-shedding certification for crew and passenger exposure limits. European operators face EU F-Gas Regulation coordination constraints when upgrading these systems.
- Freight Trains:Minimal HVAC infrastructure limits filtration to operator cab and brake system protection on select routes.
- Maintenance Facilities:Yard-based particulate monitoring under India's CEA mandates is pushing specification upgrades for stationary filtration at heavy-haul infrastructure depots.
Locomotives command the largest installed base, though Passenger Coaches show the steepest specification escalation trajectory.
Technology:
Margin structure diverges between commodity passive media and value-added active systems requiring electrical integration and control software.
- Passive Filtration:Standard pleated media without powered components dominates legacy fleet maintenance. Deutsche Bahn's component pooling system sources these cartridges directly from Mannheim and Nuremberg workshops, bypassing wholesale channels.
- Active Air Purification:Combined mechanical and electrostatic stages with real-time pressure differential monitoring enable condition-based replacement contracts. This technology layer is gaining share fastest as operators seek to reduce unplanned maintenance.
- UV-C Light Treatment:Germicidal irradiation modules supplement particulate capture in premium passenger cabin configurations.
- Ionization Technology:Bipolar ion generators neutralize biological contaminants without filter media replacement, competing with traditional hardware on total cost of ownership.
Passive Filtration retains the volume lead, while Active Air Purification is climbing the fastest on service contract attachment.
End User:
Purchasing authority concentration determines contract structure, with operator-owned depots consolidating procurement away from distributor networks.
- Rail Operators:State-owned incumbents in Germany, Austria, and China control both rolling stock and service infrastructure, sourcing filters through captive maintenance corridors. EPA Tier 4 compliance deadlines in the US are forcing specification upgrades across diesel-electric fleets.
- Maintenance Companies:Independent service depots compete on turnaround speed and inventory availability for unplanned replacements.
- Manufacturers:CRRC and Alstom integrate first-fit filtration into new-build specifications, locking in initial hardware placement.
- Transport Authorities:Urban transit agencies in London, Paris, and Berlin mandate tunnel particulate limits that cascade into metro fleet procurement requirements.
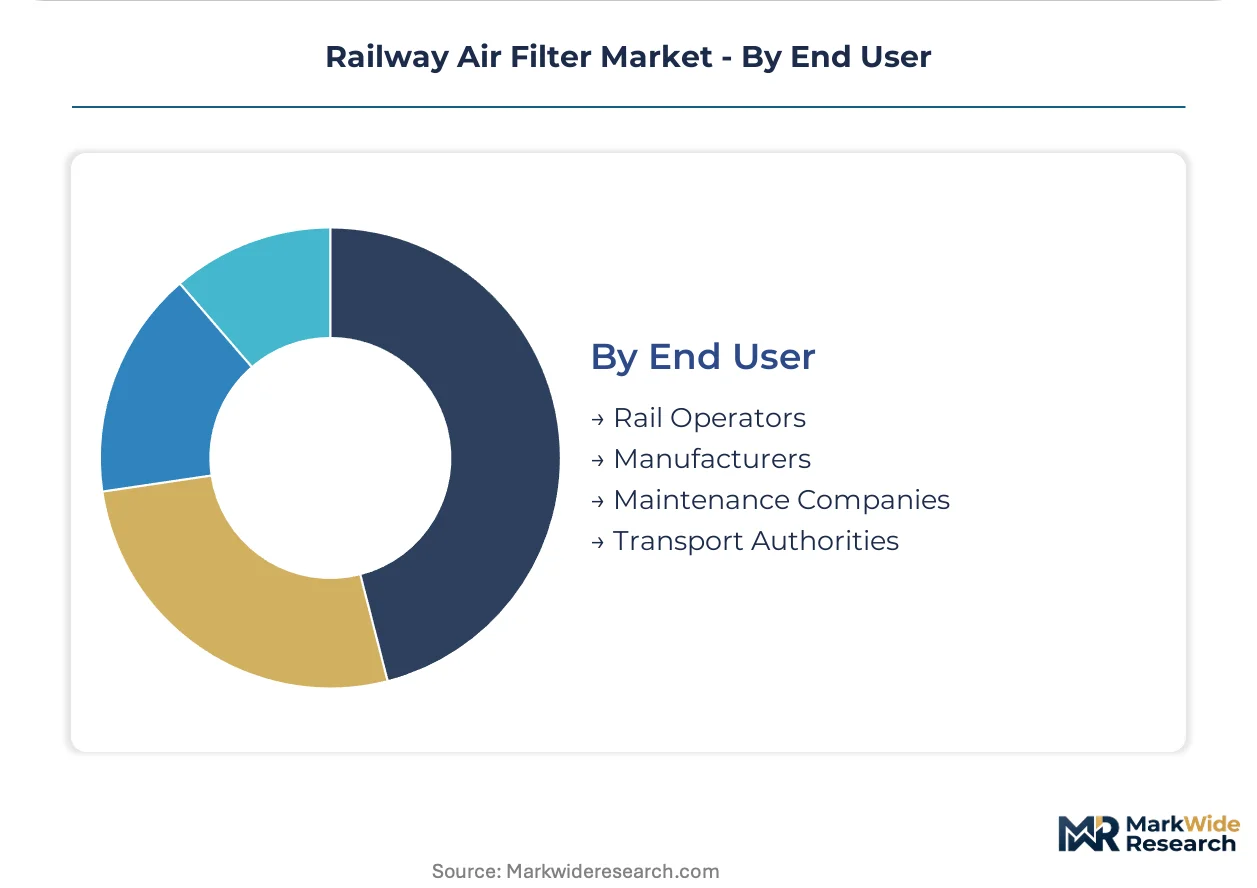
Rail Operators control the dominant procurement volume, while Maintenance Companies are gaining share through emergency response capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes railway air filters for high-speed passenger cabin sealing, while India deploys them for heavy-haul locomotive intake protection under punishing dust loads. Germany and the United States split between aftermarket service corridors and EPA-mandated fleet retrofits. Japan concentrates on precision-engineered media for Shinkansen pressure differentials.
China
CRRC's procurement pipeline drives HEPA-grade cabin filtration demand across new high-speed coaches. MEE enforcement of ambient air quality targets filters into rolling stock specifications through GB standards compliance. The Yangtze River Delta manufacturing cluster supplies pleated media bonded to galvanized steel frames for domestic fleet renewal programs.
India
Vande Bharat procurement and Dedicated Freight Corridor expansion concentrate locomotive intake filtration demand. CEA-mandated particulate monitoring at maintenance yards pushes specification upgrades across 1,500 route-km of heavy-haul infrastructure. The Delhi-Mumbai Industrial Corridor hosts filter specification testing for coal-dust protection on retrofitted diesel-electric fleets.
Germany
Deutsche Bahn's component pooling system sources cartridges directly from Mannheim and Nuremberg workshops, bypassing wholesale channels. EU Stage V emission norms extending through Directive 97/68/EC amendments force multi-pulse cleaning system certifications. Bavaria's rail maintenance corridors anchor captive distribution networks for recurring cartridge volumes.
United States
Freight railroads retrofit diesel-electric fleets with higher-efficiency intake filtration to meet EPA Tier 4 nitrogen oxide and particulate caps. Extended locomotive lifecycles of 30-40 years compress first-fit hardware volumes toward low-margin replacements. Chicago and Omaha maintenance depots consolidate aftermarket purchasing away from traditional distributor networks.
Japan
Shinkansen operators demand sub-micron retention efficiency for sealed-cabin pressure differentials on premium passenger coaches. METI standards govern fiber-shedding certification timelines that delay product launches. The Nagoya industrial corridor specializes in glass-microfiber pleated media for turbocharger protection under high-velocity intake conditions.
Railway Air Filter Market Competitive Landscape
Capability concentration sits with specialized filtration media engineers; scale advantage sits with diversified industrial conglomerates. The vendor base splits between captive distribution holders and independent component suppliers. Three strategic archetypes dominate: European aftermarket service integrators, Asian supply chain anchors, and North American diversified industrials. Competitive moves center on direct depot procurement bypass and predictive maintenance software attachment.
Within the European aftermarket tier, MANN+HUMMEL and Freudenberg Filtration Technologies exemplify captive distribution strategies. Parker Hannifin Corporation represents the diversified industrial archetype with hydraulic-fluid crossover capabilities. These three anchors occupy positions across distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| MANN+HUMMEL |
| Parker Hannifin Corporation |
| Freudenberg Filtration Technologies |
| Donaldson Company |
| Eaton Corporation |
| Daikin Industries |
| DuPont |
| AFE Airfilter Europe |
| Camfil Group |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing cluster anchors global pleated media capacity, with its glass-microfiber foundry output directly conditioning pricing power for downstream filter assemblers serving CRRC's procurement pipeline. Input cost volatility from energy-intensive synthetic melt-blown production feeds through to contract negotiations, compressing margins on standard-grade cartridges while HEPA specifications retain premium positioning.
Pricing Analysis
Long-term offtake agreements dominate procurement between state-owned rail operators and incumbent filter suppliers, locking in volume commitments across multi-year fleet renewal cycles. Three-tier pricing structure across premium, standard, and economy levels separates H14-grade cabin filtration from MERV 13 locomotive intake media and unbranded aftermarket cartridges. Cost compression in standard-grade segments is intensifying because Asian operators retrofit existing fleets with electrostatic alternatives. Freight railroads in North America exhibit highest price sensitivity due to extended locomotive lifecycles, while European high-speed operators prioritize certification compliance over unit cost.
Supply Chain Analysis
Glass-microfiber feedstock draws from specialized foundries in Germany and Japan, with synthetic melt-blown layers sourcing from South Korean petrochemical complexes and Chinese polymer processors. Critical inputs span borosilicate glass rovings, polypropylene resin pellets, and galvanized steel framing stock. Single-source vulnerability concentrates in locomotive-grade filtration media where three foundries control seventy percent of qualified supply. Distribution runs through operator-owned maintenance depots rather than wholesale channels, with Deutsche Bahn's Mannheim and Nuremberg workshops exemplifying direct procurement bypass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railway air filtration is approaching a platform-economics inflection where predictive maintenance software and condition-based replacement contracts restructure value capture away from commodity hardware, accelerated by interoperability demands from operator-owned depot networks.
For Market Incumbents: Entrench captive distribution through deeper integration into operator maintenance corridors, mirroring MANN+HUMMEL's Deutsche Bahn anchoring. Invest in pressure-differential sensor certification to defend against predictive maintenance software entrants. Prioritize multi-pulse cleaning system R&D alignment with EU Stage V compliance timelines to capture Eastern European retrofit demand. For New Entrants and Emerging Players: India's Dedicated Freight Corridor maintenance yards represent the most penetrable entry point, with CEA-mandated particulate monitoring forcing specification upgrades across 1,500 route-km of new infrastructure. Brake dust capture systems for London, Paris, and Berlin metro corridors offer specialized white-space with lower incumbent saturation. Lead with emergency response capabilities and inventory availability to bypass entrenched long-term contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core filtration divisions amid portfolio rationalization. Five-to-ten year viability hinges on software-anchored service contract attachment rates displacing transactional hardware revenue. Monitor EPA Tier 4 compliance deadline clustering for inflection signals on aftermarket demand concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Condition-Based Service Contracts | Pressure-differential sensor integration enables predictive replacement scheduling with Deutsche Bahn-style depot anchoring. |
| Multi-Pulse Certification Investment | EU Stage V alignment captures Eastern European operator retrofit demand ahead of fleet replacement cycles. |
| Electrostatic Media Scale-Up | Synthetic melt-blown capacity expansion serves Asian operator HVAC energy reduction mandates. |
| Brake Dust Capture Specialization | Urban tunnel particulate limits in London and Berlin create defensible niche for metro-focused entrants. |
| Direct Depot Procurement Bypass | Mannheim-Nuremberg workshop integration models eliminate distributor margin extraction for incumbent protection. |
Research Methodology
Cross-validation between regulatory filing analysis and operator procurement documentation anchors the qualitative findings on compliance-driven specification shifts. Primary interviews with fleet maintenance directors, OEM procurement leads at CRRC and Alstom, filtration media R&D engineers, and rail operator sustainability officers combined with secondary validation from EPA enforcement records, EU Stage V directive amendments, India's CEA yard monitoring mandates, and China's MEE ambient air quality disclosures. Bottom-up unit economics and top-down fleet renewal projections were triangulated to bound volume estimates.
Calibration against historical retrofit cycle timing and announced procurement pipeline commitments structured the analytical framework across the projection horizon. Segmentation dimensions modeled span product efficiency grade, application intensity, technology integration level, and operator ownership structure. CAGRs were derived from installed base aging curves and replacement interval compression under tightening emission norms. Locomotive duty cycle intensity and cabin sealing pressure differentials served as industry-specific forecast inputs.
Stress conditions across glass-microfiber supply disruption, EU F-Gas Regulation coordination delays, and Indian freight corridor construction timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on fleet renewal acceleration and regulatory enforcement consistency. Cross-checking against IEA rail transport demand projections and national railway capital expenditure announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
US Automotive Sensors Market
Vehicle Components
Wheel Spindle Market
Vehicle Components
Mobile Liquid Tanks Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Thrust Bearings Market
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
Railroad Equipment Manufacturing Market
Vehicle Components
Car Modification Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Engine Valve Market