
 Global Automotive EGR Valves Market | 2026-2036
Global Automotive EGR Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive EGR Valves Market Intelligence
Aftermarket service revenue is reconfiguring margin distribution across the EGR valve value chain. BorgWarner Inc leverages its thermal management expertise to dominate OEM supply contracts for commercial vehicle platforms. Rheinmetall Automotive AG anchors its position through specialized military and off-road applications with extreme durability requirements. Denso Corporation extends its footprint via integrated electronic control modules that bundle valve actuation with engine management software.
Automotive EGR valves are precision-engineered flow-control devices that redirect measured portions of exhaust gas back into the intake manifold, typically operating at temperatures between 150°C and 650°C depending on engine load and duty cycle; their primary purpose is to suppress combustion temperatures and reduce nitrogen oxide formation in diesel and gasoline engines. Electric EGR valves command the dominant share of new platform designs because electronic actuation enables millisecond-level positioning accuracy demanded by modern engine control units. Pneumatic EGR valves retain substantial aftermarket volume in older commercial vehicle populations where retrofit economics favor simpler replacement parts. Passenger vehicles represent the largest application segment by unit volume, though heavy duty vehicles generate higher per-unit pricing due to larger bore diameters and reinforced materials.
The EPA enforces Tier 3 emission standards that mandate specific NOx reduction thresholds, compelling North American manufacturers to specify high-precision EGR systems with closed-loop feedback. The EU Green Deal and associated Euro 7 preparatory rules are forcing European suppliers to validate valve durability under extended lean-burn operating conditions. China's MIIT administers national VI emission standards that require domestic engine builders to source EGR valves with enhanced corrosion resistance for high-sulfur fuel environments. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether platform standardization or regional customization offers superior returns on engineering investment.
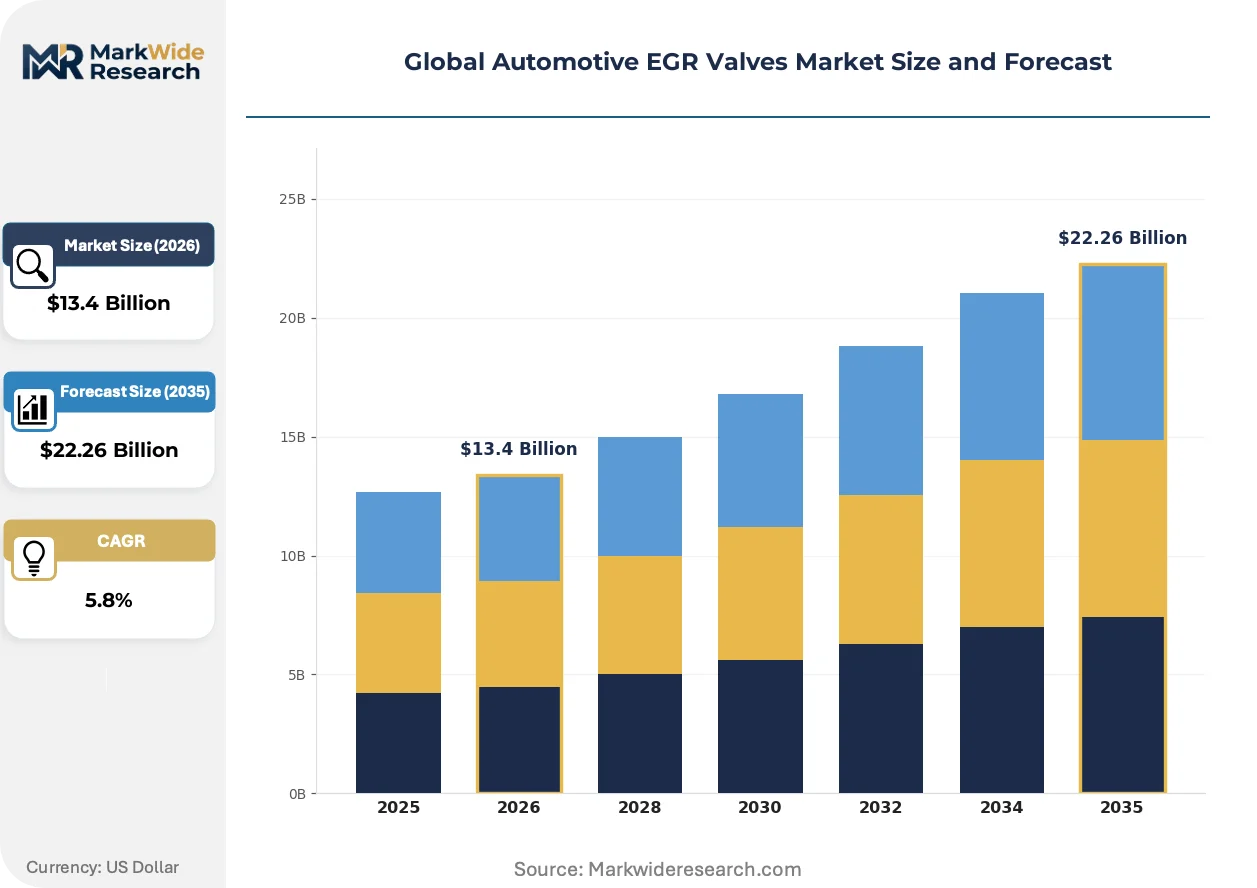
Market Dynamics
Electric actuation architectures are compressing design cycles across heavy-duty engine platforms as EPA Phase 3 and Euro 7 preparatory rules force simultaneous gains in precision and thermal resilience.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:North American commercial vehicle fleets face binding NOx reduction mandates that require closed-loop EGR systems with millisecond positioning accuracy.
- Electric EGR valve technology:Electronic actuation enables precise exhaust gas recirculation control demanded by modern engine management units in both diesel and gasoline applications.
- China's national VI emission standards:Domestic engine builders must source corrosion-resistant EGR valves capable of operating in high-sulfur fuel environments prevalent across Chinese provinces.
Market Restraints
- Stainless steel and high-nickel alloy input costs:Valve bodies require heat-resistant materials that fluctuate with commodity markets, compressing margin predictability for component suppliers.
- Pneumatic valve aftermarket lock-in:Aging commercial vehicle populations in Eastern Europe and Latin America sustain demand for legacy pneumatic designs that delay platform upgrade cycles.
- Thermal fatigue limitations:Extended lean-burn operating conditions under Euro 7 validation protocols accelerate valve seat degradation, forcing premature replacement intervals.
Strategic Opportunities
- India's BS VI emission enforcement:Domestic commercial vehicle production is expanding EGR specification rates as the country's automotive regulator tightens particulate matter thresholds.
- Integrated electronic control modules:Convergence of valve actuation hardware with engine management software creates bundled procurement opportunities for tier-one suppliers.
- Military and off-road durability segments:Extreme duty-cycle applications require reinforced materials and specialized sealing technologies that command premium positioning.
Industry Challenges
- Embedded software certification timelines:Functional safety validation under ISO 26262 extends development cycles for electronically actuated valve systems.
- Legacy engine control unit integration:Backward compatibility requirements with existing CAN bus architectures constrain firmware architecture choices.
- Cross-jurisdictional platform divergence:Engineering teams must reconcile EPA, EU Green Deal, and MIIT validation protocols that specify incompatible test cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive EGR Valves Market |
| Market Size in 2026 | $13.4 Billion |
| Market Size in 2035 | $22.26 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric EGR Valve, Pneumatic EGR Valve, Vacuum EGR Valve, Diesel EGR Valve Technology: Exhaust Gas Recirculation, Valve Positioning, Electronic Control, Thermal Management Application: Passenger Vehicles, Commercial Vehicles, Heavy Duty Vehicles, Off-road Vehicles End User: OEMs, Aftermarket Suppliers, Fleet Operators, Repair Workshops |
| Companies Covered | Mahle GmbH, Valeo SA, BorgWarner Inc, Delphi Technologies, Rheinmetall Automotive AG, Continental AG, Robert Bosch GmbH, Eberspächer Group of Companies, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive EGR Valves Market Strategic Shifts & Innovations
Digital twin methodologies are compressing thermal validation cycles while regulatory divergence between major automotive markets forces parallel development tracks rather than unified global platforms.
Sensor-integrated EGR valves with embedded temperature and position feedback are virtualizing the traditional boundary between mechanical actuation and engine control electronics. Heavy-duty truck manufacturers in Germany and the United States are specifying these smart valves for 2026 platform launches. This convergence is virtualizing supplier relationships as electronics specialists capture valve actuation contracts previously held by pure-play thermal component vendors.
The EU Green Deal and associated Euro 7 preparatory rules are mandating extended durability validation under real-driving emission test conditions. European suppliers must now demonstrate valve sealing integrity across 300,000 kilometer equivalent cycles. Passenger vehicle applications face the steepest compliance cost escalation as compact packaging constraints conflict with reinforced material requirements.
Fleet operators in North America are consolidating procurement decisions at the powertrain system level rather than component level. This behavioral shift disintermediates traditional aftermarket distributors as direct OEM service contracts capture replacement volume. The concentration is most visible among long-haul trucking fleets operating across the United States interstate corridor, where unified maintenance scheduling favors single-source supplier relationships.
Global Automotive EGR Valves Market Segmentation
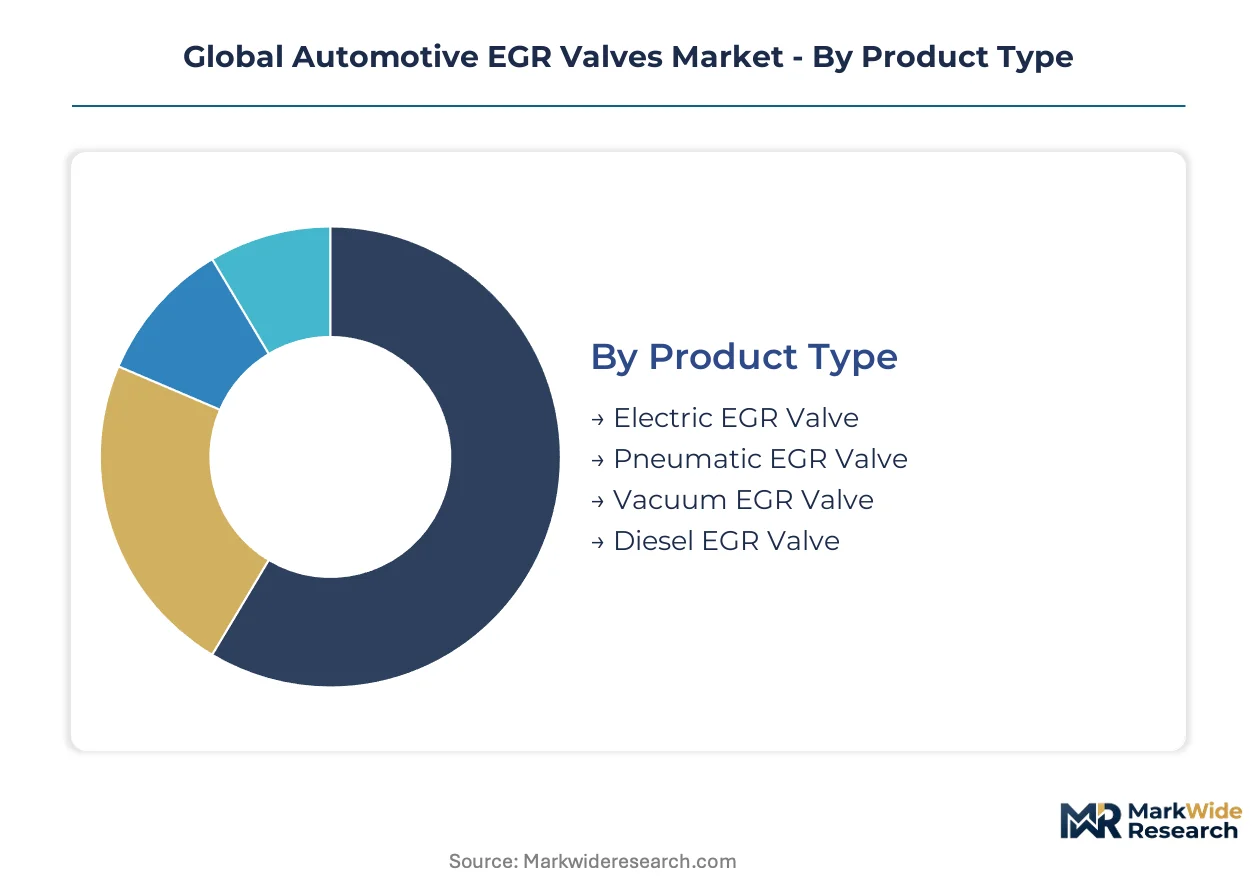
EGR valve procurement patterns diverge sharply across actuator technologies, vehicle duty cycles, and supply channel structures. Understanding these divides reveals where engineering investment concentrates and which customer relationships command premium positioning.
Product Type:
Use cases span precision-controlled electric actuation for modern engine management to legacy pneumatic systems serving aging fleet populations.
- Electric EGR Valve:Electronic actuation delivers millisecond-level positioning accuracy required by closed-loop engine control units in both diesel and gasoline platforms. Demand concentrates in Germany and the United States where EPA Phase 3 and Euro 7 preparatory rules mandate precise NOx suppression. Thermal resilience requirements under extended lean-burn validation protocols drive material specification toward high-nickel alloys.
- Pneumatic EGR Valve:Compressed-air actuation retains substantial aftermarket volume in commercial vehicle populations where retrofit economics favor simpler replacement economics. Eastern European and Latin American fleets sustain procurement of these designs, delaying platform upgrade cycles despite tightening emission enforcement in primary markets.
- Vacuum EGR Valve:Engine vacuum-powered designs persist in older passenger vehicle segments with less sophisticated engine management architectures.
- Diesel EGR Valve:Specialized corrosion-resistant variants address high-sulfur fuel environments prevalent across Chinese provinces under national VI standards.
The dominant share belongs to Electric EGR Valve, while Diesel EGR Valve is closing the gap fastest.
Technology:
Cost tiers separate basic flow-control hardware from integrated electronic systems that bundle sensing, actuation, and thermal management.
- Exhaust Gas Recirculation:Core flow-control functionality redirects measured exhaust portions into intake manifolds, operating between 150°C and 650°C depending on engine load. OEM powertrain contracts in North America specify these systems for EPA Tier 3 compliance.
- Valve Positioning:Precision feedback mechanisms enable real-time adjustment accuracy demanded by modern engine control units. Fleet operators in the United States interstate corridor prioritize these capabilities for unified maintenance scheduling.
- Electronic Control:Embedded software architectures face extended ISO 26262 functional safety validation timelines.
- Thermal Management:Heat dissipation and material durability features address Euro 7 requirements for 300,000 kilometer equivalent sealing integrity.
Electronic Control commands the steepest investment trajectory, though Thermal Management is expanding most quickly as durability requirements intensify.
Application:
Volume concentration sits with passenger vehicles, while margin structure favors heavy-duty platforms with reinforced material requirements.
- Passenger Vehicles:Largest unit volume segment faces steepest compliance cost escalation as compact packaging constraints conflict with reinforced material demands under Euro 7 real-driving emission test conditions. German and United States manufacturers specify sensor-integrated smart valves for platform launches.
- Heavy Duty Vehicles:Larger bore diameters and extreme duty-cycle requirements generate premium per-unit pricing. Military and off-road durability specifications command specialized sealing technologies and reinforced alloys.
- Commercial Vehicles:Fleet-level procurement consolidation at powertrain system level disintermediates traditional aftermarket distributors.
- Off-road Vehicles:Extreme operating environments drive specification of military-grade durability variants.
Passenger Vehicles retains volume leadership, though Heavy Duty Vehicles is gaining share fastest on pricing power.
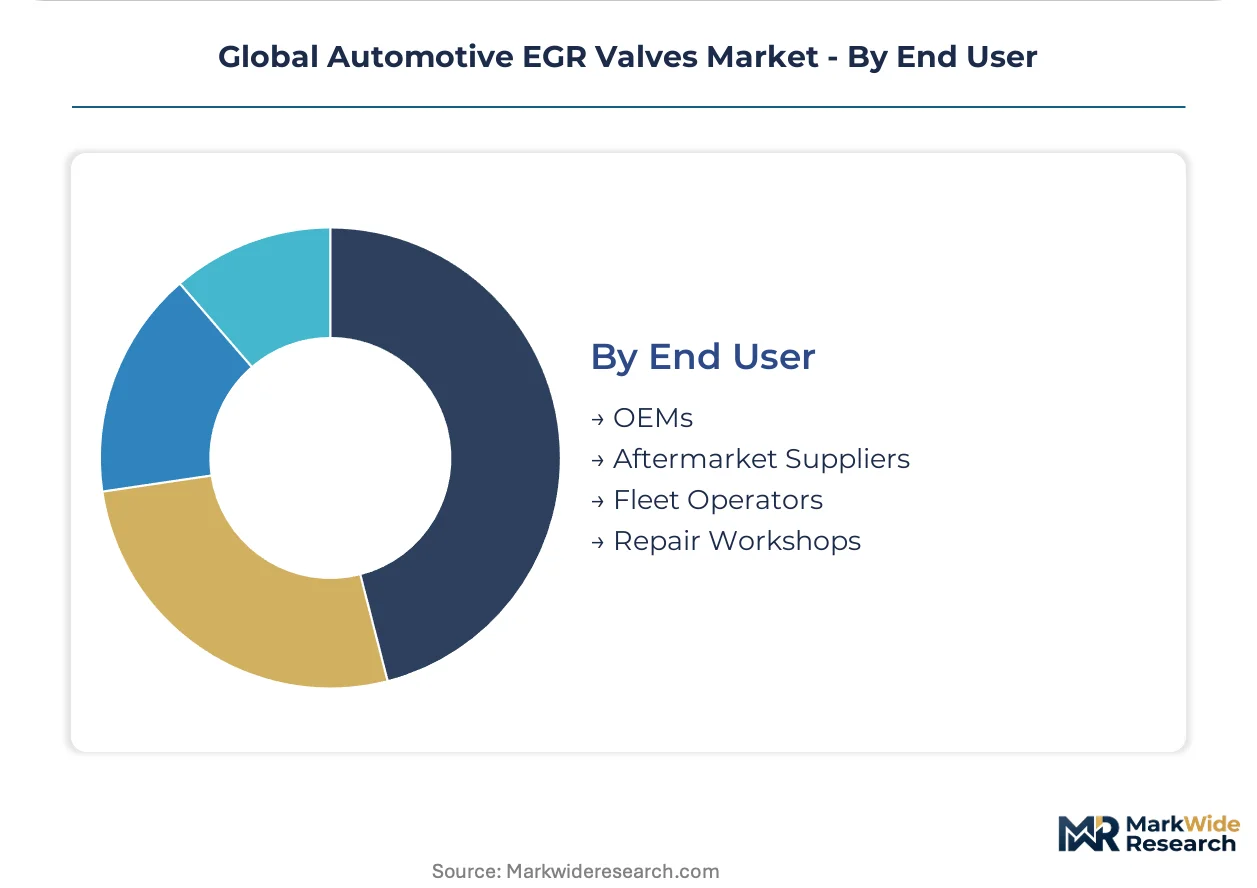
End User:
Customer type determines whether procurement flows through direct OEM contracts, fragmented aftermarket channels, or consolidated fleet arrangements.
- OEMs:Direct supply relationships dominate new platform specification, with thermal management specialists capturing actuation contracts through bundled electronic control modules. BorgWarner leverages this channel for commercial vehicle platform dominance.
- Fleet Operators:Long-haul trucking consolidation across the United States interstate corridor favors single-source supplier relationships and unified maintenance scheduling, disintermediating traditional distributors.
- Aftermarket Suppliers:Legacy pneumatic valve demand sustains this channel in aging vehicle populations.
- Repair Workshops:Service-level procurement captures replacement volume as EPA Phase 3 enforcement expands.
OEMs control specification authority, while Fleet Operators are climbing the fastest as procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys electric EGR valves at the highest penetration rate for heavy-duty platforms, while China sources corrosion-resistant variants for high-sulfur fuel environments, and the United States concentrates procurement among consolidated fleet operators. This tripartite consumption pattern reflects divergent regulatory enforcement timelines and fuel infrastructure conditions across the three dominant automotive manufacturing clusters.
United States
Long-haul trucking fleets operating across the interstate corridor drive specification of closed-loop EGR systems with millisecond positioning accuracy. EPA Phase 3 greenhouse gas standards bind commercial vehicle operators to precise NOx reduction thresholds. Detroit and the broader Midwest manufacturing belt anchor OEM supply relationships for heavy-duty platform launches.
Germany
Heavy-duty truck manufacturers specify sensor-integrated smart valves for 2026 platform introductions requiring Euro 7 preparatory validation. The EU Green Deal mandates extended durability testing across 300,000 kilometer equivalent cycles. Stuttgart and Munich host concentrated development activity for thermal management and electronic control integration.
China
Domestic engine builders source specialized EGR valves with enhanced corrosion resistance for high-sulfur fuel environments prevalent across interior provinces. MIIT-administered national VI emission standards compel powertrain suppliers to validate components under localized operating conditions. Shanghai and the Yangtze River Delta cluster manufacturing capacity for both domestic OEM supply and export markets.
India
Commercial vehicle production is expanding EGR specification rates as BS VI enforcement tightens particulate matter thresholds for diesel platforms. The country's automotive regulator has accelerated compliance timelines for domestic manufacturers. Pune and Tamil Nadu industrial corridors concentrate supplier development activity for localized platform adaptation.
Japan
Precision engineering specialists advance integrated electronic control modules that bundle valve actuation with engine management software. METI-aligned industrial policy supports development of functional safety architectures under ISO 26262 protocols. Nagoya and the broader Chubu region maintain concentrated expertise in mechatronic system integration for hybrid powertrain applications.
Global Automotive EGR Valves Market Key Industry Players
Capability concentration sits with thermal management specialists and electronics integrators; scale advantage sits with diversified automotive component conglomerates. The vendor base organizes into three strategic tiers: precision actuation technology leaders, integrated powertrain system suppliers, and aftermarket-focused legacy manufacturers. Consolidation pressure intensifies as fleet-level procurement decisions migrate from component-level to system-level specifications. Dominant competitive moves include strategic partnerships for electronic control module bundling and geographic expansion into emission enforcement acceleration zones.
Among diversified automotive suppliers, BorgWarner Inc and Denso Corporation exemplify the integrated system supplier archetype, while Rheinmetall Automotive AG occupies a specialized position within extreme durability segments. Mahle GmbH and Continental AG represent the European fabrication cluster with concentrated thermal engineering expertise. Robert Bosch GmbH anchors the electronics integration tier through embedded control software capabilities. These named entities illustrate the competitive structure without exhaustively mapping individual strategic postures.
| Leading Market Players |
|---|
| Mahle GmbH |
| Valeo SA |
| BorgWarner Inc |
| Delphi Technologies |
| Rheinmetall Automotive AG |
| Continental AG |
| Robert Bosch GmbH |
| Eberspächer Group of Companies |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta port congestion during peak shipping seasons feeds directly into landed cost differentials for German and United States manufacturers, compressing margin buffers for tier-one suppliers while amplifying price premiums for corrosion-resistant valve variants bound for China's high-sulfur fuel markets.
Pricing Analysis
Long-term offtake agreements dominate OEM procurement for heavy-duty platforms, with spot-market exposure concentrated in aftermarket channels serving Eastern European and Latin American pneumatic valve replacement demand. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated smart valves with embedded ISO 26262 certification from basic flow-control hardware. Cost compression in the economy tier is intensifying because stainless steel and high-nickel alloy input volatility erodes supplier predictability. Fleet operators operating across the United States interstate corridor exhibit lowest price sensitivity due to unified maintenance scheduling economies, while fragmented repair workshops in aging vehicle populations remain most price-sensitive.
Supply Chain Analysis
Stainless steel and high-nickel alloy feedstock draws from concentrated mining and refining operations in Indonesia, the Philippines, and Russia, creating input cost volatility that propagates through valve body fabrication. Specialized sealing technologies and precision electronic actuation components rest on semiconductor supply from Taiwan and South Korea. Single-source vulnerability in rare earth magnet procurement for electric valve motors exposes European and North American assemblers to export restriction risk. Distribution runs through direct OEM contracts for new platforms, with aftermarket volume fragmenting across regional distributors and consolidated fleet service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-enabled predictive maintenance contracts for EGR valve systems are expanding faster than hardware unit sales, creating recurring revenue pools that reconfigure supplier-customer relationships around uptime guarantees rather than component transactions.
For Market Incumbents: Build switching-cost moats through embedded electronic control modules that integrate valve actuation with proprietary engine management firmware, locking OEM platform engineers into multi-year validation cycles. Deepen backward integration into high-nickel alloy supply through captive offtake agreements with Indonesian mining consortia, insulating margin structures from commodity volatility. Defend against electronics specialists capturing actuation contracts by accelerating ISO 26262 functional safety certification timelines that pure-play thermal vendors cannot match. For New Entrants and Emerging Players: India's BS VI enforcement acceleration represents the most penetrable entry point, as domestic commercial vehicle production expands EGR specification rates faster than localized supplier capacity can respond. Military and off-road durability segments offer premium positioning with less entrenched incumbent control due to specialized sealing technology requirements. Target direct fleet operator relationships in the United States interstate corridor, bypassing traditional aftermarket distributor networks through predictive maintenance service bundling. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized automotive thermal management divisions lacking electronic control integration capabilities. Five-to-ten year viability hinges on regulatory enforcement durability across EPA Phase 3, Euro 7, and China's national VI standards rather than technology substitution risk. Watch for fleet-level procurement consolidation crossing critical mass thresholds as signal that component-level supplier margins face permanent compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering validation burden across EPA, Euro 7, and MIIT compliance protocols. |
| Electronic Control Module Integration | Bundles valve actuation with Denso and Bosch engine management software architectures. |
| Corrosion-Resistant Material Development | Addresses high-sulfur fuel environments prevalent across Chinese interior provinces. |
| Predictive Maintenance Service Launch | Captures fleet operator relationships through uptime-based contracts rather than part sales. |
| Geographic Manufacturing Footprint Expansion | Localizes production near Pune and Tamil Nadu corridors for India's BS VI enforcement. |
Research Approach
Desk research of vehicle production databases, IHS Markit registration data, and EPA emission certification filings preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet maintenance directors. Primary fieldwork combined telephone and video interviews with secondary validation against customs records, SEC 10-K thermal segment disclosures, and MIIT component certification registries. Bottom-up unit demand estimates triangulated against top-down powertrain production forecasts across passenger, heavy-duty, and commercial vehicle categories.
Assumptions held fixed include regulatory enforcement timelines for EPA Phase 3, Euro 7 preparatory rules, and China's national VI standards, while fuel sulfur content trajectories and fleet replacement cycle lengths varied across sensitivity scenarios. Segmentation modeling spanned actuator technology, vehicle duty cycle, thermal management integration level, and regional production cluster. CAGRs derived from regression analysis of historical platform adoption curves against emission standard phase-in schedules, incorporating electric vehicle penetration as demand displacement input.
Practitioners should monitor stainless steel and high-nickel alloy price volatility, Euro 7 final rule durability test cycle modifications, and fleet operator procurement consolidation velocity for early signals requiring forecast revision. Cross-checking against IEA heavy-duty vehicle stock projections and EPA certification database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Engine Components Market
Vehicle Components
Chassis Sensors Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Bicycle Components Aftermarket Market
Vehicle Components
Towing Ropes Market
Vehicle Components
Vehicle Retarder Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Gas Station Equipment Market
Vehicle Components
Precision Bearing Market