
 Truck Axle Market | 2026-2036
Truck Axle Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Axle Market Analysis
Lightweight axle design is tilting the commercial vehicle supply chain toward aluminum-intensive and composite-integrated architectures. Dana Inc. leverages in-house forging capabilities to control material costs across North American heavy-duty platforms. Meritor, Inc. sustains technology leadership in air disc brake integration with its proprietary axle housing designs. ZF Friedrichshafen AG anchors European demand through automated manufacturing lines producing precision-machined axle shafts for OEM assembly.
A truck axle is a central shaft assembly connecting a pair of wheels to the vehicle chassis, typically forged from alloy steel or aluminum and rated for load capacities spanning 12,000 to 46,000 pounds per axle depending on application class. Its primary function transmits driving torque to the wheels while supporting vehicle weight, braking forces, and suspension loads across highway, off-road, and vocational duty cycles. Tandem axle configurations dominate revenue pools in long-haul transportation where weight distribution regulations mandate dual-axle setups for trailers above threshold gross vehicle weights. Aluminum material adoption grows fastest in light-duty and medium-duty segments where OEMs pursue curb weight reduction to meet corporate average fuel economy targets without sacrificing payload ratings. Fleet operator end users concentrate procurement volume through multi-year supply agreements that lock pricing and prioritize warranty coverage over upfront component cost.
EPA greenhouse gas standards for medium- and heavy-duty engines cascade into axle design requirements through downstream OEM fuel economy targets. NHTSA Federal Motor Vehicle Safety Standards govern axle housing integrity, wheel retention, and brake system compatibility across interstate commerce. China's MIIT implements GB standards for commercial vehicle axle load limits and durability testing protocols that shape export qualification requirements. Stakeholders must monitor how regulatory divergence between US, European, and Chinese test cycles affects validation costs and platform commonality decisions.
Market Dynamics
EPA Phase 3 greenhouse gas standards and NHTSA fuel economy mandates are forcing axle suppliers to re-engineer housing geometries and material specifications across North American heavy-duty platforms.
Growth Catalysts
- E-commerce logistics expansion:Parcel delivery fleets in the United States and Germany are scaling last-mile truck deployments that require lighter tandem axle configurations to maximize payload within bridge formula limits.
- GB standard alignment:China's MIIT durability protocols for commercial vehicle axles are accelerating export qualification programs among Asian suppliers seeking access to domestic OEM assembly contracts.
- Aluminum forging advances:Controlled atmosphere heat treatment processes are enabling 15-20% weight reductions in drive axle housings without sacrificing fatigue life under vocational duty cycles.
Market Restraints
- Alloy steel price volatility:Scrap metal arbitrage and energy-intensive electric arc furnace operations in Turkey and Brazil are transmitting cost instability into forged axle shaft input budgets.
- Single-source forging concentration:North American heavy-duty axle housing production clusters among three integrated forgers, creating vulnerability to localized labor disruptions or equipment failures.
- Air disc brake retrofit friction:NHTSA brake performance standards mandate compatibility matrices that delay axle-integrated braking system introductions by 18-24 months.
Strategic Opportunities
- Indian commercial vehicle modernization:BIS axle load limit harmonization with UNECE regulations is opening qualification pathways for European and North American suppliers into domestic truck assembly.
- Electric axle module convergence:Integration of high-voltage electric motors with planetary reduction gearsets is creating white space for suppliers with power electronics packaging expertise.
- IRA commercial vehicle incentives:Tax credits for medium- and heavy-duty zero-emission vehicles are accelerating demand for lightweight axle architectures that offset battery mass penalties.
Industry Challenges
- Multi-physics simulation talent scarcity:Finite element analysis expertise spanning thermal, structural, and fatigue domains commands premium compensation and extends recruitment timelines.
- Weld qualification protocol delays:ISO 3834 and AWS D1.1 certification for automated axle housing fabrication requires 12-18 month validation cycles that gate production ramp schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Axle Market |
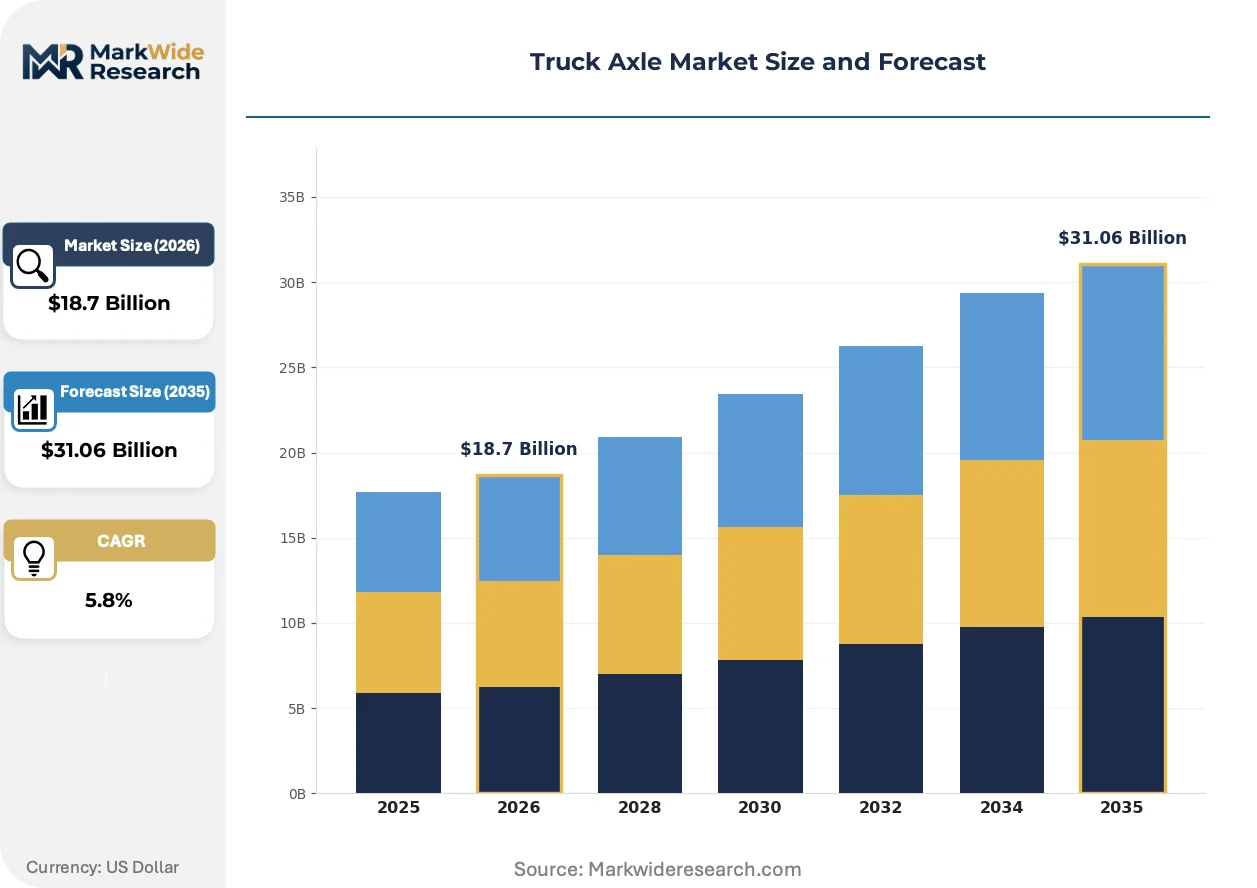
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Axle, Tandem Axle, Tri-Axle, Dead Axle End User: Commercial Vehicles, Heavy-Duty Trucks, Light-Duty Trucks, Fleet Operators Material: Steel, Aluminum, Composite, Cast Iron Application: Transportation, Construction, Agriculture, Mining |
| Companies Covered | Meritor, Inc., Hendrickson USA, L.L.C., American Axle & Manufacturing, Inc., Automotive Axles Ltd., ZF Friedrichshafen AG, Dana Inc., SAF-HOLLAND SE, Qingte Group Co. Ltd., Cummins, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Axle Market Emerging Trajectories
Axle system architecture is fragmenting along powertrain electrification fault lines, with mechanical purity giving way to electromechanical integration and software-defined torque management.
Composite-reinforced aluminum axle housings are hybridizing structural responsibilities between metallic load-bearing frames and carbon fiber shear panels that manage torsional stress from regenerative braking events. Vocational fleet operators in refuse and urban delivery segments are piloting these configurations to offset the 800-1,200 pound mass penalty of battery electric powertrains. The technology is hybridizing supplier competencies, forcing traditional forging houses to acquire composite layup and adhesive bonding capabilities.
EPA's Phase 3 greenhouse gas standards for medium- and heavy-duty vehicles are cascading into axle design specifications through downstream OEM fuel economy targets and aerodynamic drag reduction requirements. The regulation mandates 2% annual efficiency improvements that translate into axle bearing friction reduction programs and lubricant viscosity grade downshifts. Long-haul tractor segments face the steepest compliance gradients, prompting accelerated adoption of precision-ground hypoid gearsets and low-fill lubrication systems.
Fleet procurement departments are consolidating axle purchases through powertrain-agnostic platform agreements that decouple component sourcing from vehicle brand loyalty. Large for-hire carriers in the United States are negotiating direct supply relationships with axle manufacturers, bypassing traditional OEM captive sourcing arrangements. This disintermediation is most pronounced among 500+ unit fleet operators with in-house maintenance infrastructure and warranty risk absorption capacity.
Truck Axle Market Segmentation
Axle procurement cycles vary dramatically across product configurations and end-use applications, with replacement intervals spanning from 3 years in severe-duty mining to 10+ years in light-duty transportation. Material selection and axle architecture directly determine warranty exposure, fleet maintenance scheduling, and residual value calculations for vehicle operators.
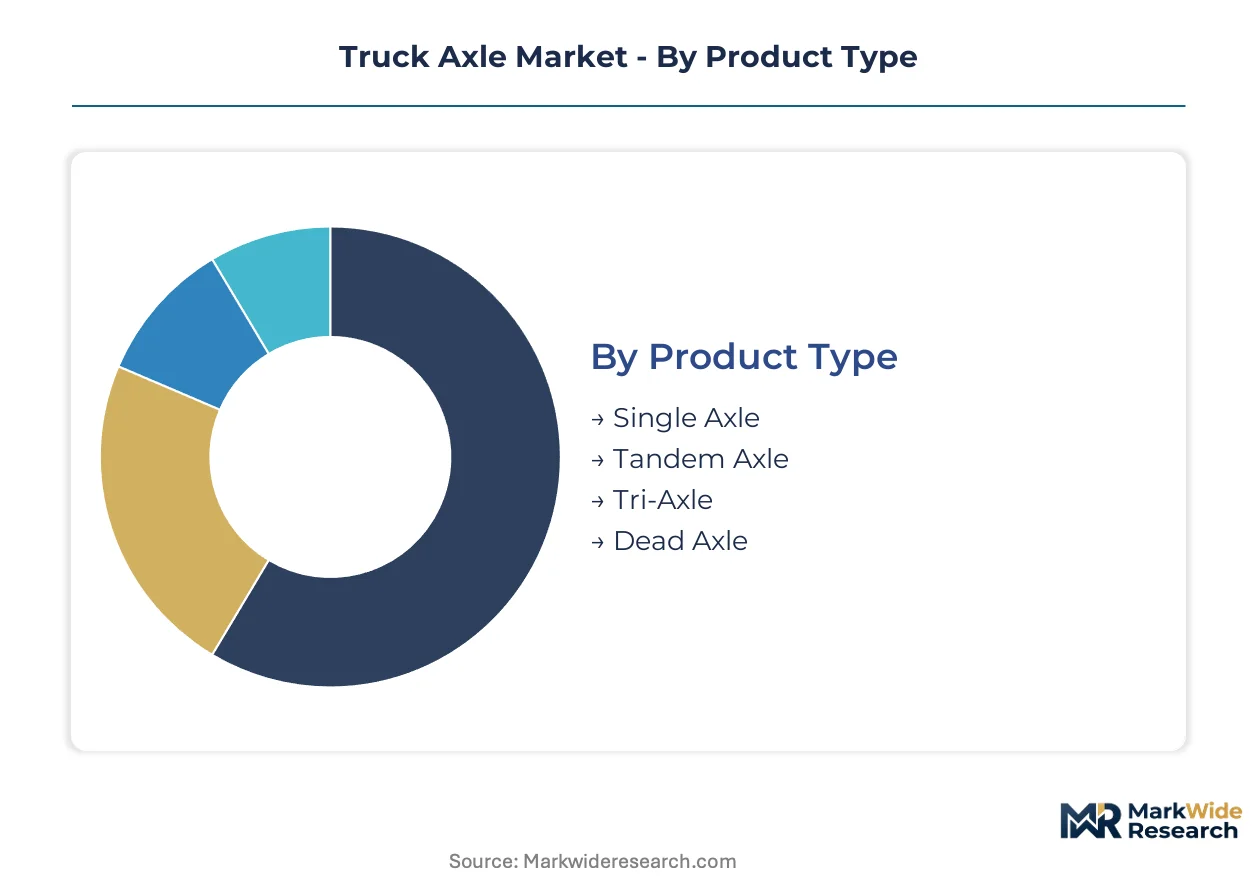
Product Type:
Replacement cycles compress from tri-axle heavy-haul configurations down to single axle light-duty units, with vocational severity and regulatory weight limits dictating wear rates and overhaul timing.
- Tandem Axle:Dual-axle assemblies rated for 34,000-pound federal bridge formula limits dominate long-haul tractor-trailer combinations. Parcel carriers operating under US DOT hours-of-service rules specify these configurations for maximum payload density within legal weight envelopes.
- Single Axle:Independent shaft assemblies support 12,000-20,000-pound ratings in urban delivery and last-mile logistics. German parcel fleets deploy these units in 7.5-tonne vehicles to optimize maneuverability in dense European city centers.
- Tri-Axle:Triple-axle configurations address specialized heavy-haul and vocational applications exceeding standard federal weight limits.
- Dead Axle:Non-driven tag and pusher axles distribute weight without torque transmission in specific trailer applications.
Tandem axle configurations anchor the volume base while single axle units gain share at the steepest rate through last-mile electrification programs.
End User:
Procurement sophistication escalates from individual owner-operators through captive fleet maintenance departments, with scale determining specification authority and warranty negotiation leverage.
- Fleet Operators:Multi-hundred-unit carriers with in-house technical staff negotiate direct supply agreements bypassing OEM distribution. These operators specify axle configurations based on total cost of ownership models incorporating fuel economy, maintenance intervals, and resale value.
- Heavy-Duty Trucks:Class 8 vehicles above 33,000 pounds GVWR require axles engineered for 500,000-mile design life under sustained interstate operation. US EPA Phase 3 compliance pressures are accelerating lightweight housing adoption in this segment.
- Commercial Vehicles:Broad category encompassing medium-duty and vocational chassis deployed across regional freight and specialized service applications.
- Light-Duty Trucks:Class 1-3 pickup and delivery vehicles with axle ratings below 10,000 pounds per unit.
Heavy-duty trucks generate the largest revenue pool while fleet operators are expanding procurement autonomy fastest through disintermediation strategies.
Material:
Cost structures diverge sharply across metallurgical categories, with raw material volatility and heat treatment energy intensity determining margin stability.
- Steel:Forged alloy steel maintains dominance in heavy-duty drive axles where fatigue resistance and impact durability outweigh mass considerations. Chinese MIIT durability protocols continue validating traditional steel architectures for domestic commercial vehicle qualification.
- Aluminum:Heat-treated aluminum forgings achieve 15-20% weight reduction in drive axle housings through controlled atmosphere processes. North American OEMs specify these units to offset battery mass in electric medium-duty platforms qualifying for IRA commercial vehicle incentives.
- Composite:Hybrid carbon fiber and aluminum architectures emerging in vocational electric vehicle applications.
- Cast Iron:Ductile iron housings retaining cost advantage in select non-structural axle components.
Steel retains volume leadership while aluminum is climbing the fastest through electrification-driven lightweighting mandates.
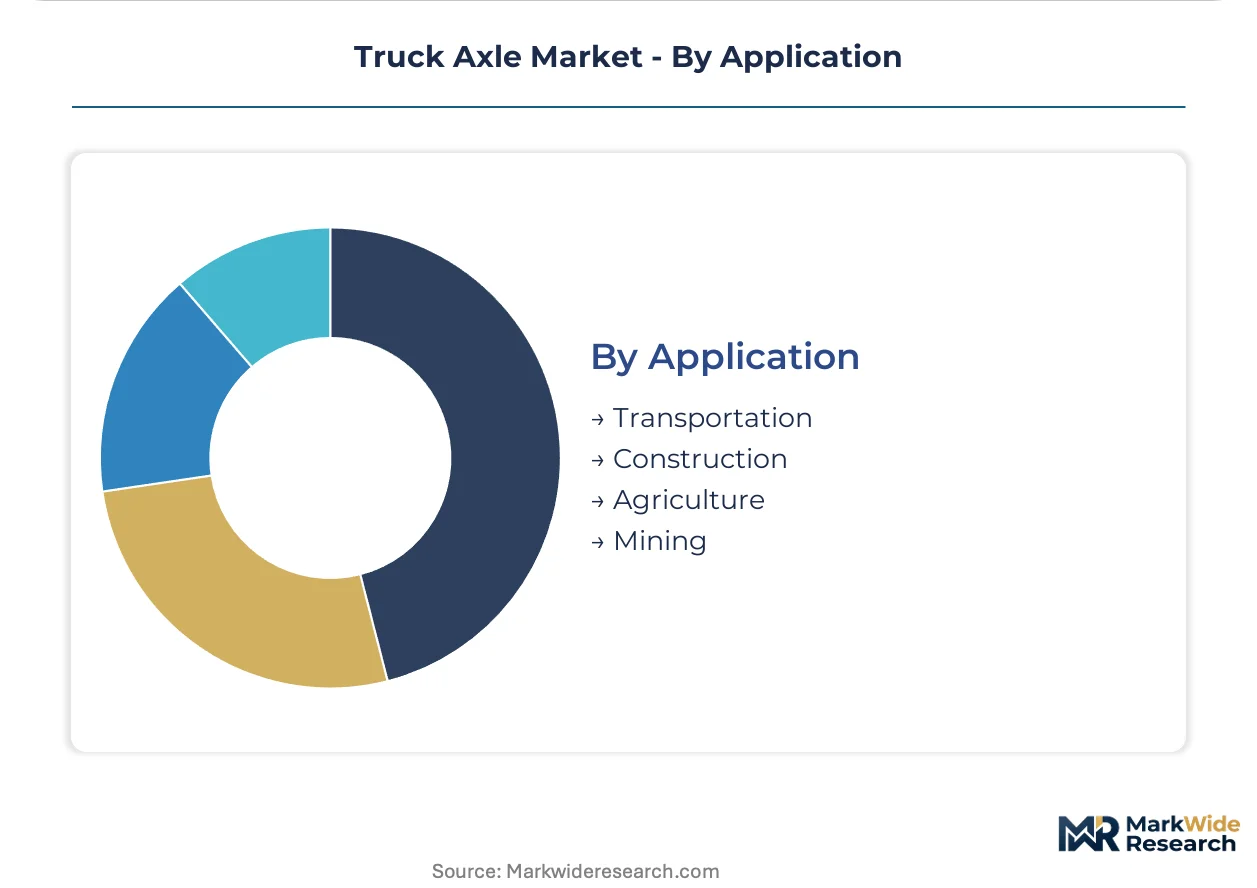
Application:
Duty cycle severity and operating environment determine specification requirements, with mining and construction imposing mechanical stresses orders of magnitude above highway transportation.
- Transportation:Highway freight and logistics applications prioritize fuel economy through bearing friction reduction and precision gear manufacturing. Long-haul segments face the steepest EPA efficiency compliance gradients, prompting low-viscosity lubricant adoption and aerodynamic integration.
- Construction:Vocational duty cycles with high shock loads and contaminated operating environments demand robust sealing systems and reinforced housing geometries. Off-road traction requirements drive specialized differential configurations with enhanced torque bias.
- Agriculture:Seasonal use patterns with extended storage periods create unique corrosion protection requirements.
- Mining:Extreme payload ratings and continuous operation in abrasive environments impose the most severe durability demands.
Transportation commands the largest installed base while construction applications are expanding specification complexity fastest through electrification and automation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese axle manufacturers export forged housings to North American heavy-duty OEMs under MIIT GB standard qualification protocols. German precision-machined shaft suppliers serve European automated assembly lines. Indian commercial vehicle modernization is opening qualification pathways for foreign component suppliers.
United States
Parcel delivery fleets in California and Texas are scaling last-mile deployments requiring lighter tandem axle configurations. EPA Phase 3 greenhouse gas standards and NHTSA fuel economy mandates cascade into axle housing re-engineering programs. Detroit-area forging clusters concentrate heavy-duty axle housing production among integrated suppliers serving Class 8 tractor platforms.
Germany
Automated manufacturing lines in Baden-Württemberg produce precision-machined axle shafts for OEM assembly contracts across European long-haul transportation. The KBA enforces UNECE brake performance standards that govern axle-integrated air disc brake compatibility matrices. Munich-based engineering centers develop low-friction bearing systems for highway freight fuel economy compliance.
China
Domestic commercial vehicle production scaling in Shandong and Hubei provinces concentrates demand for steel-forged drive axles rated under MIIT durability protocols. GB standards for axle load limits and fatigue testing shape export qualification requirements for Asian suppliers. Yangtze River Delta forging clusters supply both domestic OEMs and Southeast Asian truck assembly plants.
India
BIS axle load limit harmonization with UNECE regulations is opening qualification pathways for European and North American suppliers into domestic truck assembly. The PLI scheme for automotive components incentivizes localized axle housing fabrication. Maharashtra and Gujarat commercial vehicle manufacturing corridors are expanding procurement of medium-duty axle configurations for regional freight.
Brazil
Scrap metal arbitrage and energy-intensive electric arc furnace operations transmit alloy steel price volatility into forged axle shaft input budgets. ANVISA commercial vehicle safety standards govern wheel retention and brake system compatibility for interstate commerce. São Paulo-state assembly plants source axles from regional forgers serving Mercosur heavy-duty platforms.
Truck Axle Market Vendor Landscape
On the supply side, the industry is consolidating around integrated forgers with captive heat treatment and precision machining capabilities. Three dominant strategic archetypes have emerged: steel-forged heavy-duty specialists, aluminum lightweighting innovators, and electric axle module integrators. Competitive moves center on backward integration into alloy supply and geographic expansion through MIIT GB standard qualification for Chinese market access.
Among North American heavy-duty specialists, Meritor, Inc. and American Axle & Manufacturing, Inc. occupy positions within the steel-forged tier serving Class 8 interstate transportation. Dana Inc. exemplifies the aluminum lightweighting archetype through forged housing programs targeting electric medium-duty platforms. These three entities anchor the premium-tier supply base for EPA-compliant axle configurations.
| Leading Market Players |
|---|
| Meritor, Inc. |
| Hendrickson USA, L.L.C. |
| American Axle & Manufacturing, Inc. |
| Automotive Axles Ltd. |
| ZF Friedrichshafen AG |
| Dana Inc. |
| SAF-HOLLAND SE |
| Qingte Group Co. Ltd. |
| Cummins, Inc. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta forging clusters concentrate heavy-duty axle housing capacity for export qualification programs, transmitting localized scrap metal arbitrage volatility into North American OEM contract negotiations. Fleet procurement departments leverage multi-year volume commitments to compress supplier margins while demanding extended warranty coverage that shifts residual risk upstream.
Pricing Analysis
Technology-generation pricing gaps separate legacy steel-forged housings from aluminum lightweighting architectures and emerging composite-integrated electric axle modules. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—MIIT GB standard qualification commands 15-20% premiums over uncertified Asian supply. Price differentiation hinges on heat treatment traceability and NHTSA brake compatibility matrix completion. Pricing pressure stems from Turkish and Brazilian electric arc furnace cost instability transmitting into alloy steel input budgets. Fleet operators with 500+ unit scale exhibit lowest price sensitivity, prioritizing total cost of ownership over upfront component cost.
Supply Chain Analysis
Upstream scrap metal and primary aluminum ingot feedstock flows concentrate supply risk in Chinese Yangtze Delta forging corridors, Turkish Izmir electric arc furnace clusters, and Brazilian Minas Gerais alloy steel production. Component dependencies center on precision-machined hypoid gearsets, low-friction bearing systems, and air disc brake caliper integration modules. Single-source forging concentration among three integrated North American suppliers creates vulnerability to localized labor disruptions. Distribution runs through OEM captive sourcing channels, though fleet operator disintermediation is accelerating direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation into multi-hundred-unit carriers with in-house maintenance infrastructure is shifting procurement leverage toward buyers, fragmenting traditional OEM distribution control and forcing axle suppliers into direct warranty negotiations.
For Market Incumbents: Insulate margin position through backward integration into alloy steel supply and captive heat treatment capacity in Detroit-area forging corridors. Threats from Chinese MIIT GB-standard qualified exporters require accelerated NHTSA brake compatibility certification investment. Priority lever rests on locking multi-year supply agreements with IRA-eligible electric medium-duty platforms before battery mass penalty offset demand peaks. For New Entrants and Emerging Players: Pursue Indian commercial vehicle modernization pathways opened by BIS-UNECE harmonization, where domestic axle load limit alignment creates qualification white space for foreign suppliers. Most penetrable segment sits in Maharashtra and Gujarat medium-duty regional freight corridors. Go-to-market angle centers on PLI scheme partnership structures that localize housing fabrication while retaining precision machining technology transfer control. For Investors and Strategic Acquirers: Long-term, this sits as a electrification-infrastructure play because battery electric commercial vehicle penetration will sustain 15-20% annual demand growth for lightweight axle architectures across the analysis window. Acquisition target archetype: aluminum forging specialists with in-house composite layup capabilities and MIIT GB standard export qualification. Signal to watch: IRA commercial vehicle tax credit utilization rates triggering fleet operator procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Forging Capacity Expansion | Captures IRA incentive-driven demand from electric medium-duty platforms requiring mass-reduced housings. |
| MIIT GB Standard Qualification | Unlocks Chinese domestic OEM assembly contracts and Southeast Asian export pathways for forged components. |
| Air Disc Brake Integration Partnership | Accelerates NHTSA compliance timelines and reduces 18-24 month introduction delays for axle-integrated systems. |
| Composite Manufacturing Acquisition | Hybridizes supplier capabilities for vocational electric vehicle applications offsetting battery mass penalties. |
| Fleet Direct Supply Agreement | Bypasses OEM distribution channels and locks multi-year pricing with 500+ unit carriers absorbing warranty risk. |
Methodological Framework
Cross-validation between primary interviews with axle supplier procurement directors, OEM platform engineers, and fleet maintenance managers anchors the qualitative findings against secondary validation from EPA regulatory filings, NHTSA brake performance standards, MIIT GB protocol documentation, and IHS Markit commercial vehicle production databases. Bottom-up segment modeling triangulates against top-down market sizing across material, product type, and application dimensions.
Calibration against historical axle replacement cycle data and fleet procurement survey responses refines volume projections across the analysis window. Segmentation dimensions span steel-aluminum-composite material tiers, tandem-single-tri-axle configurations, and transportation-construction-mining application severity classes. CAGRs derive from regression analysis of commercial vehicle production forecasts, regulatory compliance cost curves, and electrification penetration assumptions. Industry-specific inputs incorporate EPA Phase 3 efficiency gradient impacts and IRA commercial vehicle incentive utilization trajectories.
Sensitivities concentrate around alloy steel price volatility from scrap metal arbitrage, NHTSA brake standard revision timelines, and Chinese MIIT protocol harmonization with UNECE regulations. Forecasts reflect documented assumptions on fleet electrification pace and OEM lightweighting adoption curves. Material shifts in EPA greenhouse gas standard stringency or IRA incentive program extension would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Charge Air Coolers Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Chassis Sensors Market
Vehicle Components
Limited Slip Differential (LSD) Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
Spark Plug Accessories Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Rolling Stock LED Lights Market
Vehicle Components
Steering Gear Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Anchorage Connector Market