
 Navigation Light Market | 2026-2036
Navigation Light Market Size, Share, and Industry Trends Forecast 2026-2036
Navigation Light Market Analytics
The split between premium and commodity tiers is hardening in navigation lighting. Hella Marine leverages its marine heritage to dominate high-specification yacht and commercial vessel segments. Glamox AS anchors Nordic offshore supply with ice-rated fixtures. Perko Inc. competes on volume through standardized Coast Guard-compliant products for recreational boats.
Navigation lights are optoelectronic signaling devices engineered to specific candela output, arc of visibility, and chromaticity coordinates defined by international convention. Marine vessels command the largest application share as SOLAS-mandated LED retrofits displace incandescent fixtures across cargo fleets. LED technology leads product substitution with xenon retaining niche roles in long-range beacon applications where intensity requirements exceed solid-state output thresholds. Wireless connectivity is gaining installation preference where retrofit cabling costs on aging infrastructure prove prohibitive.
The International Maritime Organization, the U.S. Coast Guard, and the European Committee for Electrotechnical Standardization shape product compliance through COLREGs alignment, inland waterway rules, and EN 14744 testing protocols. These frameworks mandate color fidelity, flash character accuracy, and failure-mode redundancy that elevate engineering barriers for new entrants. Stakeholders must weigh certification investment against the accelerating replacement cycle as ports and flag states tighten enforcement of visibility equipment standards.
Market Dynamics
The Navigation Light Market pivots on mandatory SOLAS LED retrofit deadlines that compress replacement cycles across aging commercial fleets, forcing capital allocation toward solid-state fixtures while rendering incandescent inventories obsolete.
Growth Catalysts
- IMO SOLAS Visibility Mandates:The International Maritime Organization's tightened chromaticity and candela output rules eliminate grandfathered incandescent fixtures, compelling systematic fleet-wide upgrades.
- Harbor Infrastructure Modernization:Southeast Asian port authorities deploy solar-powered marker systems to accommodate container traffic expansion without grid dependency.
- LED Efficacy Thresholds:Solid-state emitters now achieve nautical-mile visibility at wattage levels that reduce generator load on battery-dependent vessels.
Market Restraints
- Optical Component Supply Concentration:Precision lens and reflector manufacturing clusters in German and Japanese supplier networks create single-source vulnerability.
- Photometric Testing Bottlenecks:EN 14744 certification backlog at European notified bodies extends product launch timelines by quarters.
- Xenon Intensity Floor:Long-range beacon applications exceeding 50 candela requirements remain beyond solid-state output ceilings, preserving legacy technology.
Strategic Opportunities
- Wireless Retrofit Channels:Battery-powered, radio-linked fixtures bypass cabling costs on heritage infrastructure in Greek and Turkish shipyards.
- Arctic Route Expansion:Ice-rated navigation lighting demand rises with Northern Sea Route commercialization, requiring cold-start performance to minus 40 Celsius.
- Port Electrification Incentives:Shore power integration programs in Singapore and Rotterdam subsidize low-draw LED harbor lighting as auxiliary load reduction.
Industry Challenges
- Marine Optoelectronics Talent Scarcity:Candela calibration and chromaticity engineering expertise concentrates among aging specialists in Northern European maritime clusters.
- Flag State Compliance Fragmentation:Divergent Coast Guard interpretation of COLREGs arc-of-visibility testing forces product variant proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Navigation Light Market |
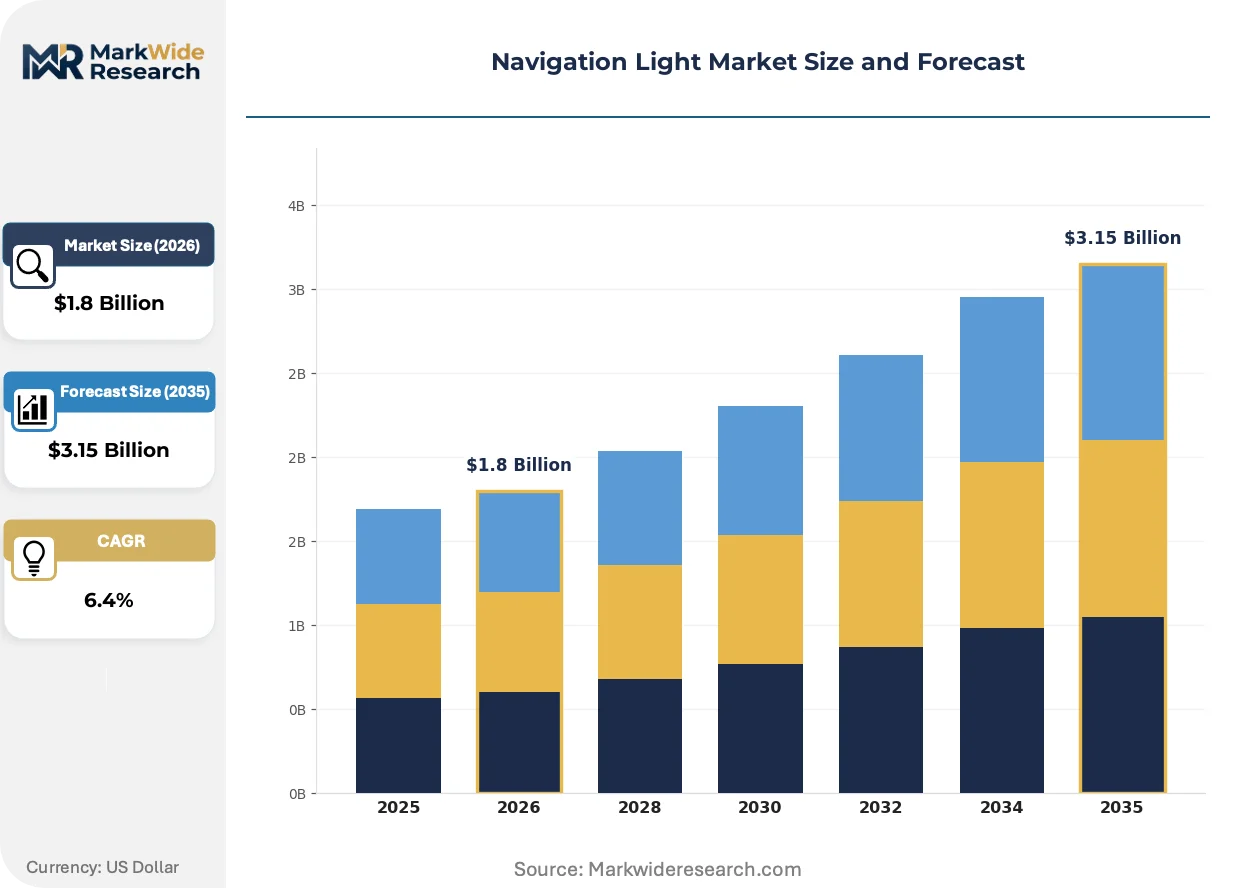
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lights, Xenon Lights, Incandescent Lights, Halogen Lights Application: Marine Vessels, Aircraft, Road Vehicles, Rail Transportation Technology: Solar Powered, Battery Operated, Plug-In, Wireless Installation: Permanent Mounting, Temporary Installation, Surface Mounting, Flush Mounting |
| Companies Covered | Hella Marine, Glamox AS, Perko Inc., Den Haan Rotterdam, Collins Aerospace, Daniamant, Tideland Signal, OSRAM Licht AG, Lumitec LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Navigation Light Market Evolving Landscape
Solid-state illumination architectures are compressing fixture lifecycles while regulatory harmonization efforts and procurement centralization reshape how navigation lighting reaches end-users.
Multi-junction LED arrays with secondary optics are overtaking xenon and incandescent sources in masthead and stern applications. Container carriers operating Singapore-Rotterdam routes now specify all-LED running light packages as standard newbuild configuration. This technology is overtaking legacy filament inventory across the retrofit segment, collapsing replacement part demand curves.
REACH substance restrictions on heavy metals in optical coatings force reformulation of reflector metallization processes. The European Committee for Electrotechnical Standardization's accelerated EN 14744 revision timeline compresses certification validity windows. Nordic offshore supply vessel operators face the steepest compliance cost escalation as ice-rated fixtures require specialized thermal cycling validation.
Consolidated fleet procurement through major ship management groups in Monaco and Hamburg concentrates specification authority. Long-term fixture supply agreements with embedded maintenance clauses displace spot purchasing through chandler networks. Greek and Cypriot tanker operators exhibit the most pronounced shift toward integrated lighting-service contracts spanning decade horizons.
Navigation Light Market Segmentation
Navigation light procurement decisions pivot on visibility requirements, energy constraints, and retrofit feasibility. Segment boundaries sharpen as SOLAS mandates eliminate legacy technologies and port operators prioritize grid-independent harbor marking systems.
Product Type:
Buyers select emitters based on candela output thresholds, generator load tolerance, and replacement cycle economics.
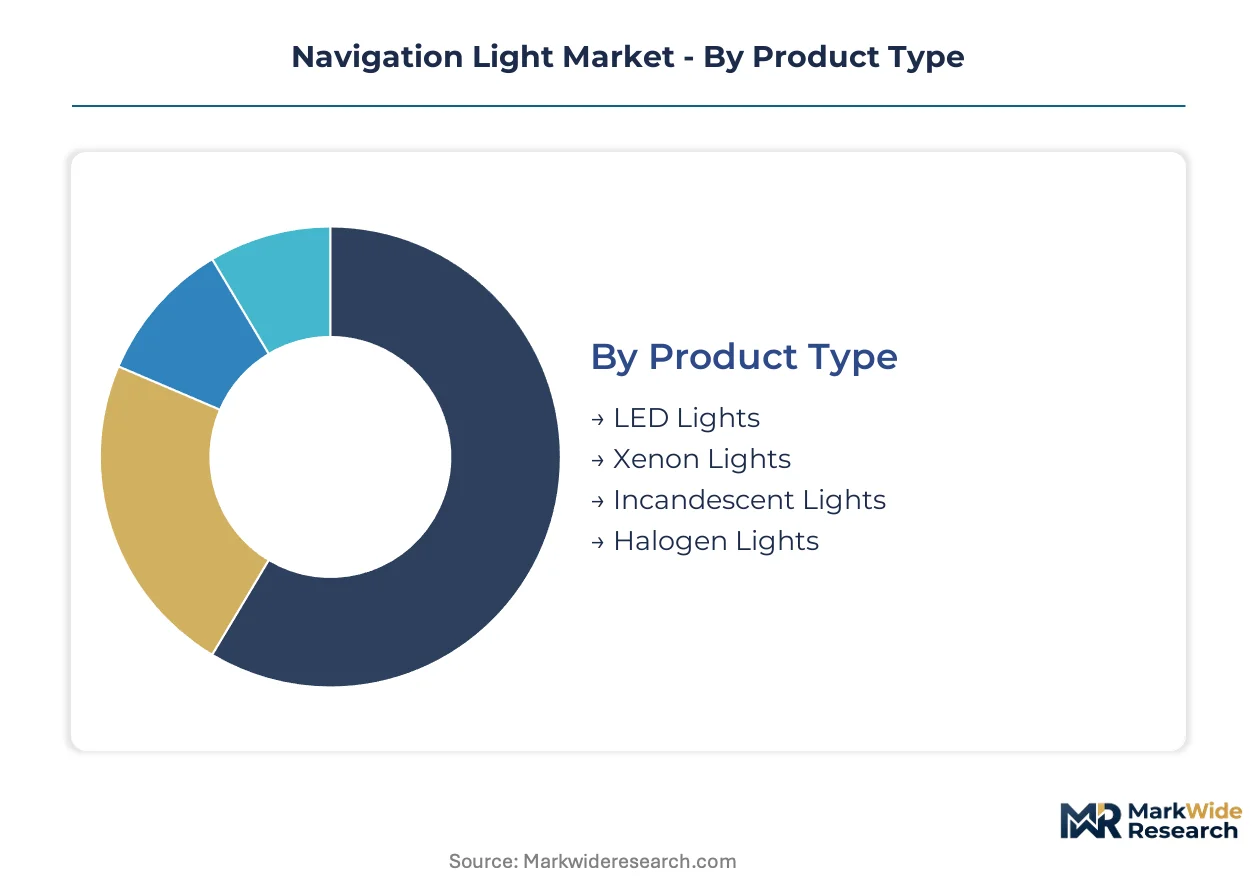
- LED Lights:Multi-junction arrays with secondary optics deliver nautical-mile visibility at fractional wattage. Container carriers on Singapore-Rotterdam routes specify all-LED running light packages as standard newbuild configuration, collapsing demand for incandescent replacement parts.
- Xenon Lights:Gas-discharge tubes generate candela levels exceeding solid-state ceilings in long-range beacon applications. Arctic route markers and offshore platform identifiers in Norwegian waters retain xenon for intensity requirements above 50 candela.
- Incandescent Lights:Filament-based fixtures face systematic phase-out under IMO chromaticity mandates. Grandfathered inventories concentrate in aging recreational fleets with limited capital for SOLAS compliance retrofits.
- Halogen Lights:Tungsten-halogen cycles offer marginal efficacy gains over standard incandescent sources. Greek and Turkish shipyards specify halogen for interim retrofits where LED supply chains face certification delays.
Volume sits with LED Lights; growth tilts toward Xenon Lights in specialized high-intensity niches.
Application:
End-use environments dictate arc-of-visibility precision, failure-mode redundancy, and environmental sealing specifications.
- Marine Vessels:SOLAS-mandated chromaticity and flash character accuracy dominate specification sheets. LED retrofits displace incandescent fixtures across cargo fleets as flag states tighten enforcement of visibility equipment standards.
- Aircraft:Anti-collision strobes and position lights require FAA-compliant intensity modulation. Solid-state emitters now satisfy candela requirements for commercial aviation navigation lighting.
- Road Vehicles:Automotive signaling applications fall outside COLREGs jurisdiction but share optoelectronic component supply chains. Heavy truck marker lights in German manufacturing corridors absorb LED module capacity.
- Rail Transportation:Locomotive headlamps and crossing signals demand vibration-resistant mounting architectures. European rail operators specify EN 14744-aligned fixtures for interoperability across border networks.
Marine Vessels command the largest revenue pool; Aircraft applications are climbing the fastest as aviation LED retrofits accelerate.
Technology:
Power architecture selection hinges on cabling accessibility, grid reliability, and maintenance interval targets.
- Solar Powered:Photovoltaic-battery hybrids eliminate trenching and grid connection costs. Southeast Asian port authorities deploy solar marker systems to accommodate container traffic expansion without utility dependency.
- Battery Operated:Self-contained units with wireless control bypass retrofit cabling on heritage infrastructure. Greek shipyards favor battery-powered fixtures for tanker deck lighting where cable routing through explosion-proof conduits proves prohibitive.
- Plug-In:Hardwired AC connections dominate newbuild installations with integrated shore power. Singapore and Rotterdam port electrification programs subsidize low-draw LED harbor lighting as auxiliary load reduction.
- Wireless:Radio-linked fixtures enable centralized monitoring and flash synchronization. Consolidated fleet procurement through Hamburg ship management groups specifies wireless-ready architectures for decade-spanning service contracts.
Plug-In systems retain the installed base; Solar Powered configurations are expanding most quickly in emerging port infrastructure.
Installation:
Mounting geometry determines optical alignment stability, environmental sealing integrity, and labor cost profiles.
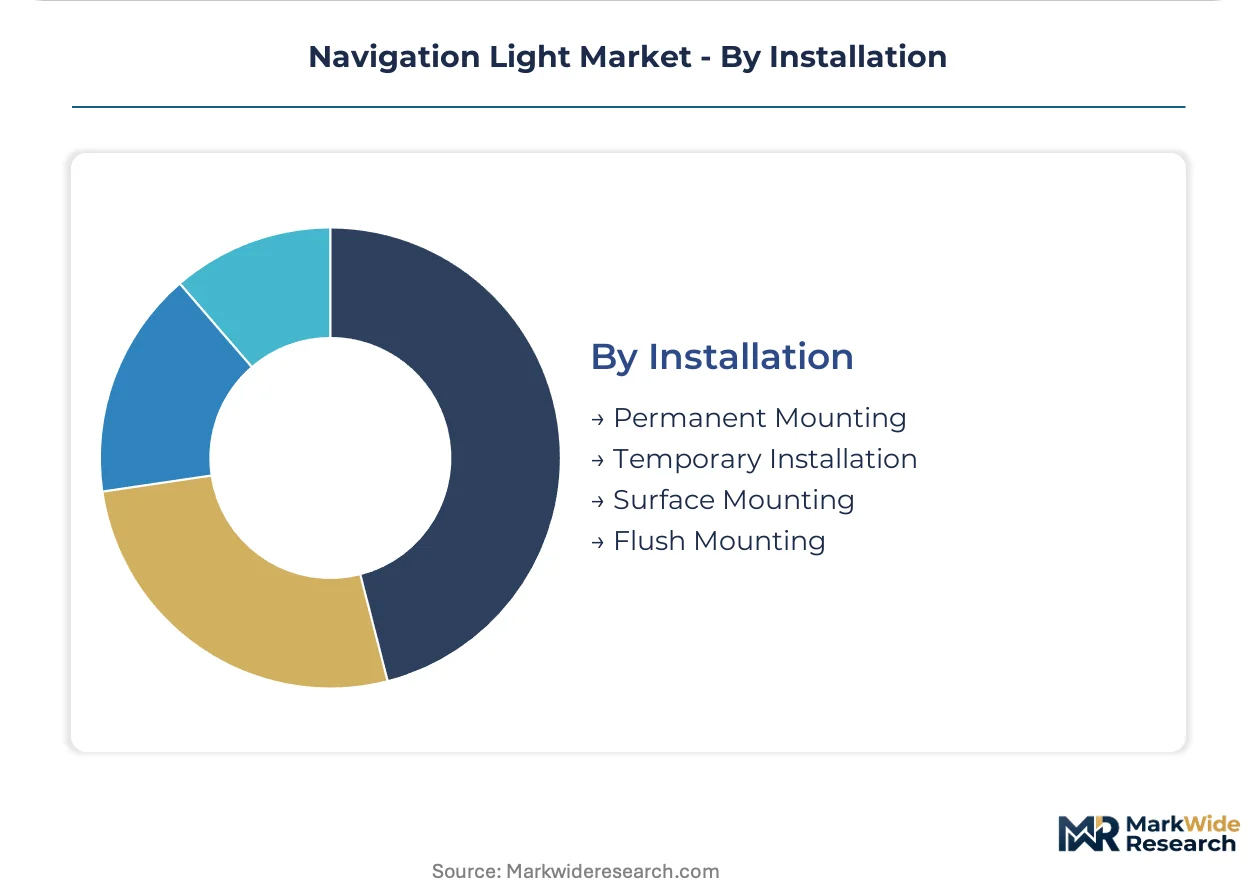
- Permanent Mounting:Bolted fixtures with marine-grade sealing withstand cyclical loading and salt spray. Nordic offshore supply vessels specify permanent-mounted ice-rated fixtures requiring specialized thermal cycling validation.
- Temporary Installation:Magnetic or clamp-based attachments serve emergency signaling and maintenance operations. Turkish shipyards deploy temporary navigation lights during drydock periods when permanent fixtures are removed for servicing.
- Surface Mounting:External bracket assemblies simplify retrofit on vessels with limited internal cable routing. Recreational boat manufacturers in US coastal states favor surface-mounted Coast Guard-compliant products for production efficiency.
- Flush Mounting:Recessed integration reduces wind resistance and snag hazards on high-speed craft. Yacht builders in Monaco specify flush-mounted LED arrays for aesthetic integration with composite superstructures.
Surface Mounting dominates retrofit volume; Flush Mounting is gaining share fastest in premium yacht and high-speed ferry segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's port electrification programs and container terminal expansions anchor demand concentration in Southeast Asian maritime corridors, while Hamburg and Rotterdam cluster Northern European specification authority for ice-rated and harbor lighting systems.
United States
The U.S. Coast Guard enforces COLREGs-aligned arc-of-visibility testing that forces product variant proliferation for domestic flag fleets. Florida's recreational boat manufacturing corridor absorbs standardized Coast Guard-compliant surface-mounted fixtures, while Pacific Northwest shipyards drive wireless retrofit adoption for aging tanker infrastructure.
Germany
Precision lens and reflector manufacturing clusters in German supplier networks create single-source vulnerability for optical components. The KBA's interpretation of inland waterway rules shapes EN 14744 testing protocol implementation, with Hamburg ship management groups consolidating fleet procurement through decade-spanning service contracts.
Norway
Arctic route commercialization demands ice-rated navigation lighting with cold-start performance to minus 40 Celsius. Norwegian offshore supply vessel operators face steep compliance cost escalation from specialized thermal cycling validation requirements, with Stavanger and Bergen harbors deploying high-intensity xenon beacons for platform identification.
China
Yangtze River Delta container traffic expansion drives solar-powered harbor marker deployment without grid dependency. The MIIT's GB standards alignment with SOLAS mandates accelerates LED retrofit penetration across state-owned cargo fleets, with Shanghai port authorities subsidizing shore power integration for auxiliary load reduction.
Greece
Greek tanker operators exhibit pronounced shifts toward integrated lighting-service contracts spanning decade horizons. Piraeus shipyards favor battery-powered fixtures for tanker deck lighting where cable routing through explosion-proof conduits proves prohibitive, while drydock operations deploy temporary magnetic-mount navigation lights during fixture servicing.
Navigation Light Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and thermal performance specifications. The vendor base concentrates around three strategic archetypes: marine heritage specialists leveraging yacht and commercial vessel relationships, Nordic offshore suppliers anchoring ice-rated fixture demand, and volume-driven fabricators competing through standardized regulatory compliance. Dominant competitive moves include backward integration into optical component supply and long-term service contract embedding that displaces spot purchasing through traditional chandler networks.
Among the named marine lighting specialists, Hella Marine and Glamox AS occupy positions on the premium-performance vector, with Perko Inc. representing the standardized volume tier. Hella Marine exemplifies marine heritage positioning, while Glamox AS anchors Nordic offshore supply relationships. Perko Inc. sits within the Coast Guard-compliant recreational fabrication segment where production efficiency drives specification capture.
| Leading Market Players |
|---|
| Hella Marine |
| Glamox AS |
| Perko Inc. |
| Den Haan Rotterdam |
| Collins Aerospace |
| Daniamant |
| Tideland Signal |
| OSRAM Licht AG |
| Lumitec LLC |
| Others |
Value Network & Pricing Analysis
Backward integration into precision optical component manufacturing anchors pricing power for navigation lighting specialists serving SOLAS-mandated commercial fleets. German and Japanese supplier networks concentrate lens and reflector production, creating captive supply advantages for Hella Marine and Glamox AS while forcing commodity-tier competitors toward outsourced procurement with thinner margin profiles.
Pricing Analysis
Value-based pricing tied to certification grade and failure-mode redundancy anchors the navigation light market. Three-tier pricing structure across premium, standard, and economy levels separates ice-rated offshore fixtures from Coast Guard-compliant recreational products and grandfathered incandescent inventories. Pricing pressure stems from EN 14744 certification backlog extending product launch timelines and compressing margin recovery. Recreational boat manufacturers in US coastal states exhibit highest price sensitivity, while Nordic offshore supply operators accept premium positioning for thermal cycling validation.
Supply Chain Analysis
Certification gating through notified bodies in Germany and Norway constrains supplier qualification and concentrates tier-one relationships. Precision lens manufacturing clusters in Germany and Japan, with secondary optical component sourcing from Taiwan. German suppliers draw from specialized borosilicate glass and marine-grade aluminum feedstocks. Single-source vulnerability in precision reflector metallization creates structural risk from REACH substance restrictions on heavy metals. Distribution runs through Hamburg and Monaco ship management groups consolidating fleet procurement, displacing traditional chandler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Navigation lighting supply is tightening around photometric testing capacity, with European notified body backlog propping pricing for certified fixtures across the analysis window.
For Market Incumbents: Anchor market position through captive control over precision optical component supply and embedded long-term service contracts. Wireless retrofit architectures threaten traditional hardwired fixture demand; defend through decade-spanning maintenance agreements with Greek and Cypriot tanker operators. Prioritize EN 14744 pre-certification investment to compress competitor launch timelines. For New Entrants and Emerging Players: Begin with battery-powered wireless fixtures targeting Greek and Turkish shipyards where cabling retrofit costs prove prohibitive. Solar-powered harbor markers in Southeast Asian ports offer most penetrable white-space, with port authority procurement centralizing around grid-independent systems. Pursue direct technical sales to consolidated fleet management groups in Hamburg and Monaco. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to marine heritage lighting groups seeking ice-rated fixture capabilities. Long-term viability favors specialists with backward integration into optical component supply and established Nordic offshore relationships. Watch for Northern Sea Route commercialization milestones as inflection signal for Arctic-rated demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | Captive supply of precision lenses from German manufacturing clusters reduces single-source vulnerability. |
| Wireless Retrofit Architecture Development | Battery-powered radio-linked fixtures bypass cabling costs on aging Greek and Turkish tanker infrastructure. |
| EN 14744 Pre-Certification Investment | Accelerated validation at European notified bodies compresses competitor product launch timelines. |
| Long-Term Service Contract Embedding | Decade-spanning maintenance agreements with Monaco ship management groups displace spot purchasing. |
| Ice-Rated Fixture Thermal Validation | Specialized cold-start testing to minus 40 Celsius captures Arctic route commercialization demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this navigation lighting analysis. Primary interviews with marine lighting procurement officers at Hamburg ship management groups, photometric testing engineers at European notified bodies, and technical directors at Nordic offshore supply operators combined with secondary validation from IMO SOLAS amendments, EN 14744 protocol revisions, and US Coast Guard interpretation bulletins. Bottom-up fixture shipment data and top-down port infrastructure investment flows were triangulated to establish market sizing.
Granularity-level modeling proceeded at product type, application, technology, and installation method dimensions across the analysis window. LED, xenon, incandescent, and halogen emitter categories were modeled separately with distinct replacement cycle assumptions. Marine vessel, aircraft, road vehicle, and rail transportation applications each carried unique regulatory compliance cost structures. CAGRs derived from weighted average of fleet retrofit deadlines, port modernization timelines, and newbuild specification trends. SOLAS mandate enforcement intensity and REACH substance restriction timelines served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; LED retrofit volumes carry tighter precision than grandfathered incandescent inventory estimates. Forecasts reflect assumptions on flag state enforcement consistency and certification body processing capacity. A model refresh is warranted upon material change in IMO COLREGs interpretation or Northern Sea Route ice condition classification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
Italy Automotive Composites Market
Vehicle Components
Gas Station Equipment Market
Vehicle Components
Autonomous Trains Components Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Truck Suspension System Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Motorcycle Side Box Market
Vehicle Components
Precision Bearing Market
Vehicle Components
HCV Axles Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Rear Axle Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market